
Dairy blends swap costly milk fat for cheaper vegetable fat
The dairy blends market was valued at USD 9.97 billion in 2025 and is projected to increase from USD 10.40 billion in 2026 to USD 15.38 billion by 2035, registering a CAGR of 4.43% during 2025–2035. That price logic is simple, since milk fat is expensive and vegetable fat is not, so a blend that keeps the dairy protein and swaps part of the fat passes the saving to the buyer. Among regions, Asia Pacific held the largest share, 30.2% in 2025, while Africa is the fastest-growing at 5.68% a year. The main commercial change is consolidation, as three large European dairy deals completed in 2026 fold milk supply, butter plants and blending into fewer, larger groups.
Who buys dairy blends, and which products stay outside the count?
Dairy blend demand comes from three kinds of buyers, as households in import-dependent markets buy fat-filled powder and filled canned milk as affordable milk, food factories and foodservice chains buy ingredient blends made to their recipes, and shoppers in Northern Europe and Oceania buy spreadable butter blends for convenience. Codex standard CXS 251-2006 sets the reference for the largest family, and under it a powdered blend of skimmed milk and vegetable fat must contain at least 26% fat, with milk protein at least 34% of milk solids-not-fat.
The value chain runs from dairy cooperatives and vegetable-oil refiners through blenders and traders to importers, brand owners and food plants. Within that chain, the count excludes straight dairy commodities such as whole milk powder, skim milk powder and butter, as well as infant formula, creamers and spreads with no dairy content, and whey blends for animal feed.
Dairy Blends Market Insights
- The dairy blends market is forecast to grow from USD 10.40 billion in 2026 to USD 15.38 billion by 2035, a 4.43% CAGR, as import-dependent households and food plants buy more blends.
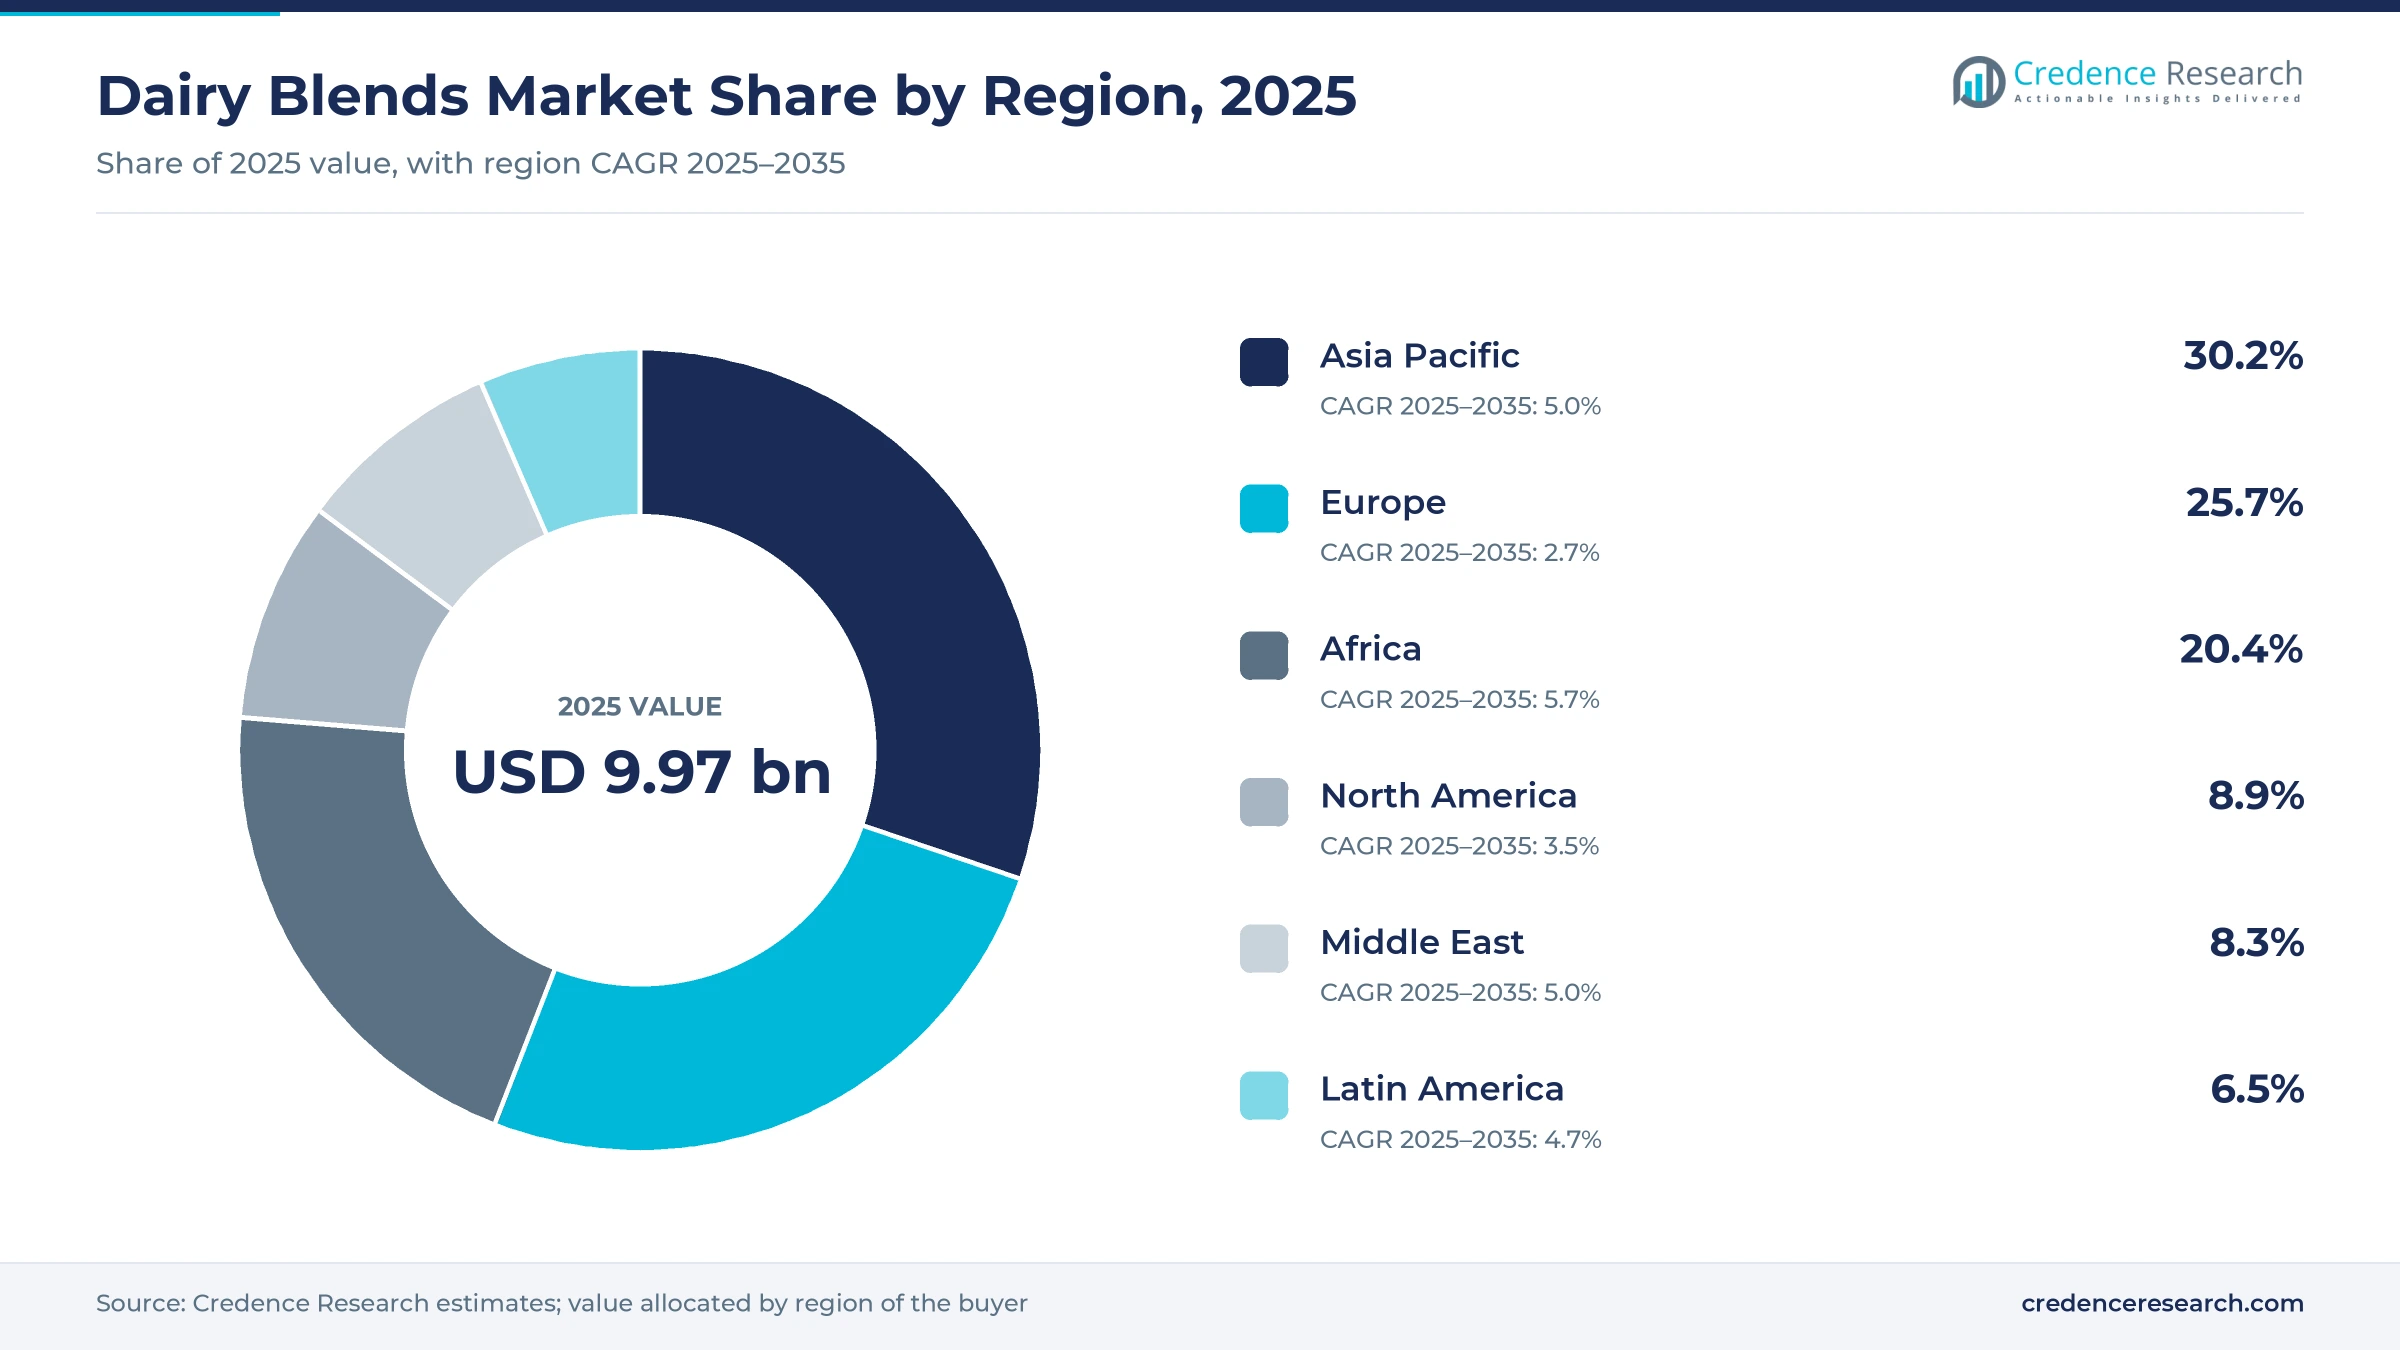
- Asia Pacific held 30.2% of 2025 value, the largest regional share, because the Philippines, Indonesia, Malaysia and China buy powder, canned and ingredient blends.
- Fat-filled milk powders accounted for 35.5% of 2025 value, the largest type, because vegetable fat replaces costly milk fat while the dairy protein stays.
- Arla–DMK, FrieslandCampina–Milcobel and Lactalis–Mainland deals completed in 2026 fold milk supply, butter plants and blending into fewer, larger dairy groups.
- Ornua added a range of Kerrygold butter blends in 2025, showing that premium butter brands now invest in spreadable blends rather than defending butter alone.
Fat-filled powders lead value and growth, spreads lead use
Fat-filled milk powders lead by type and grow fastest
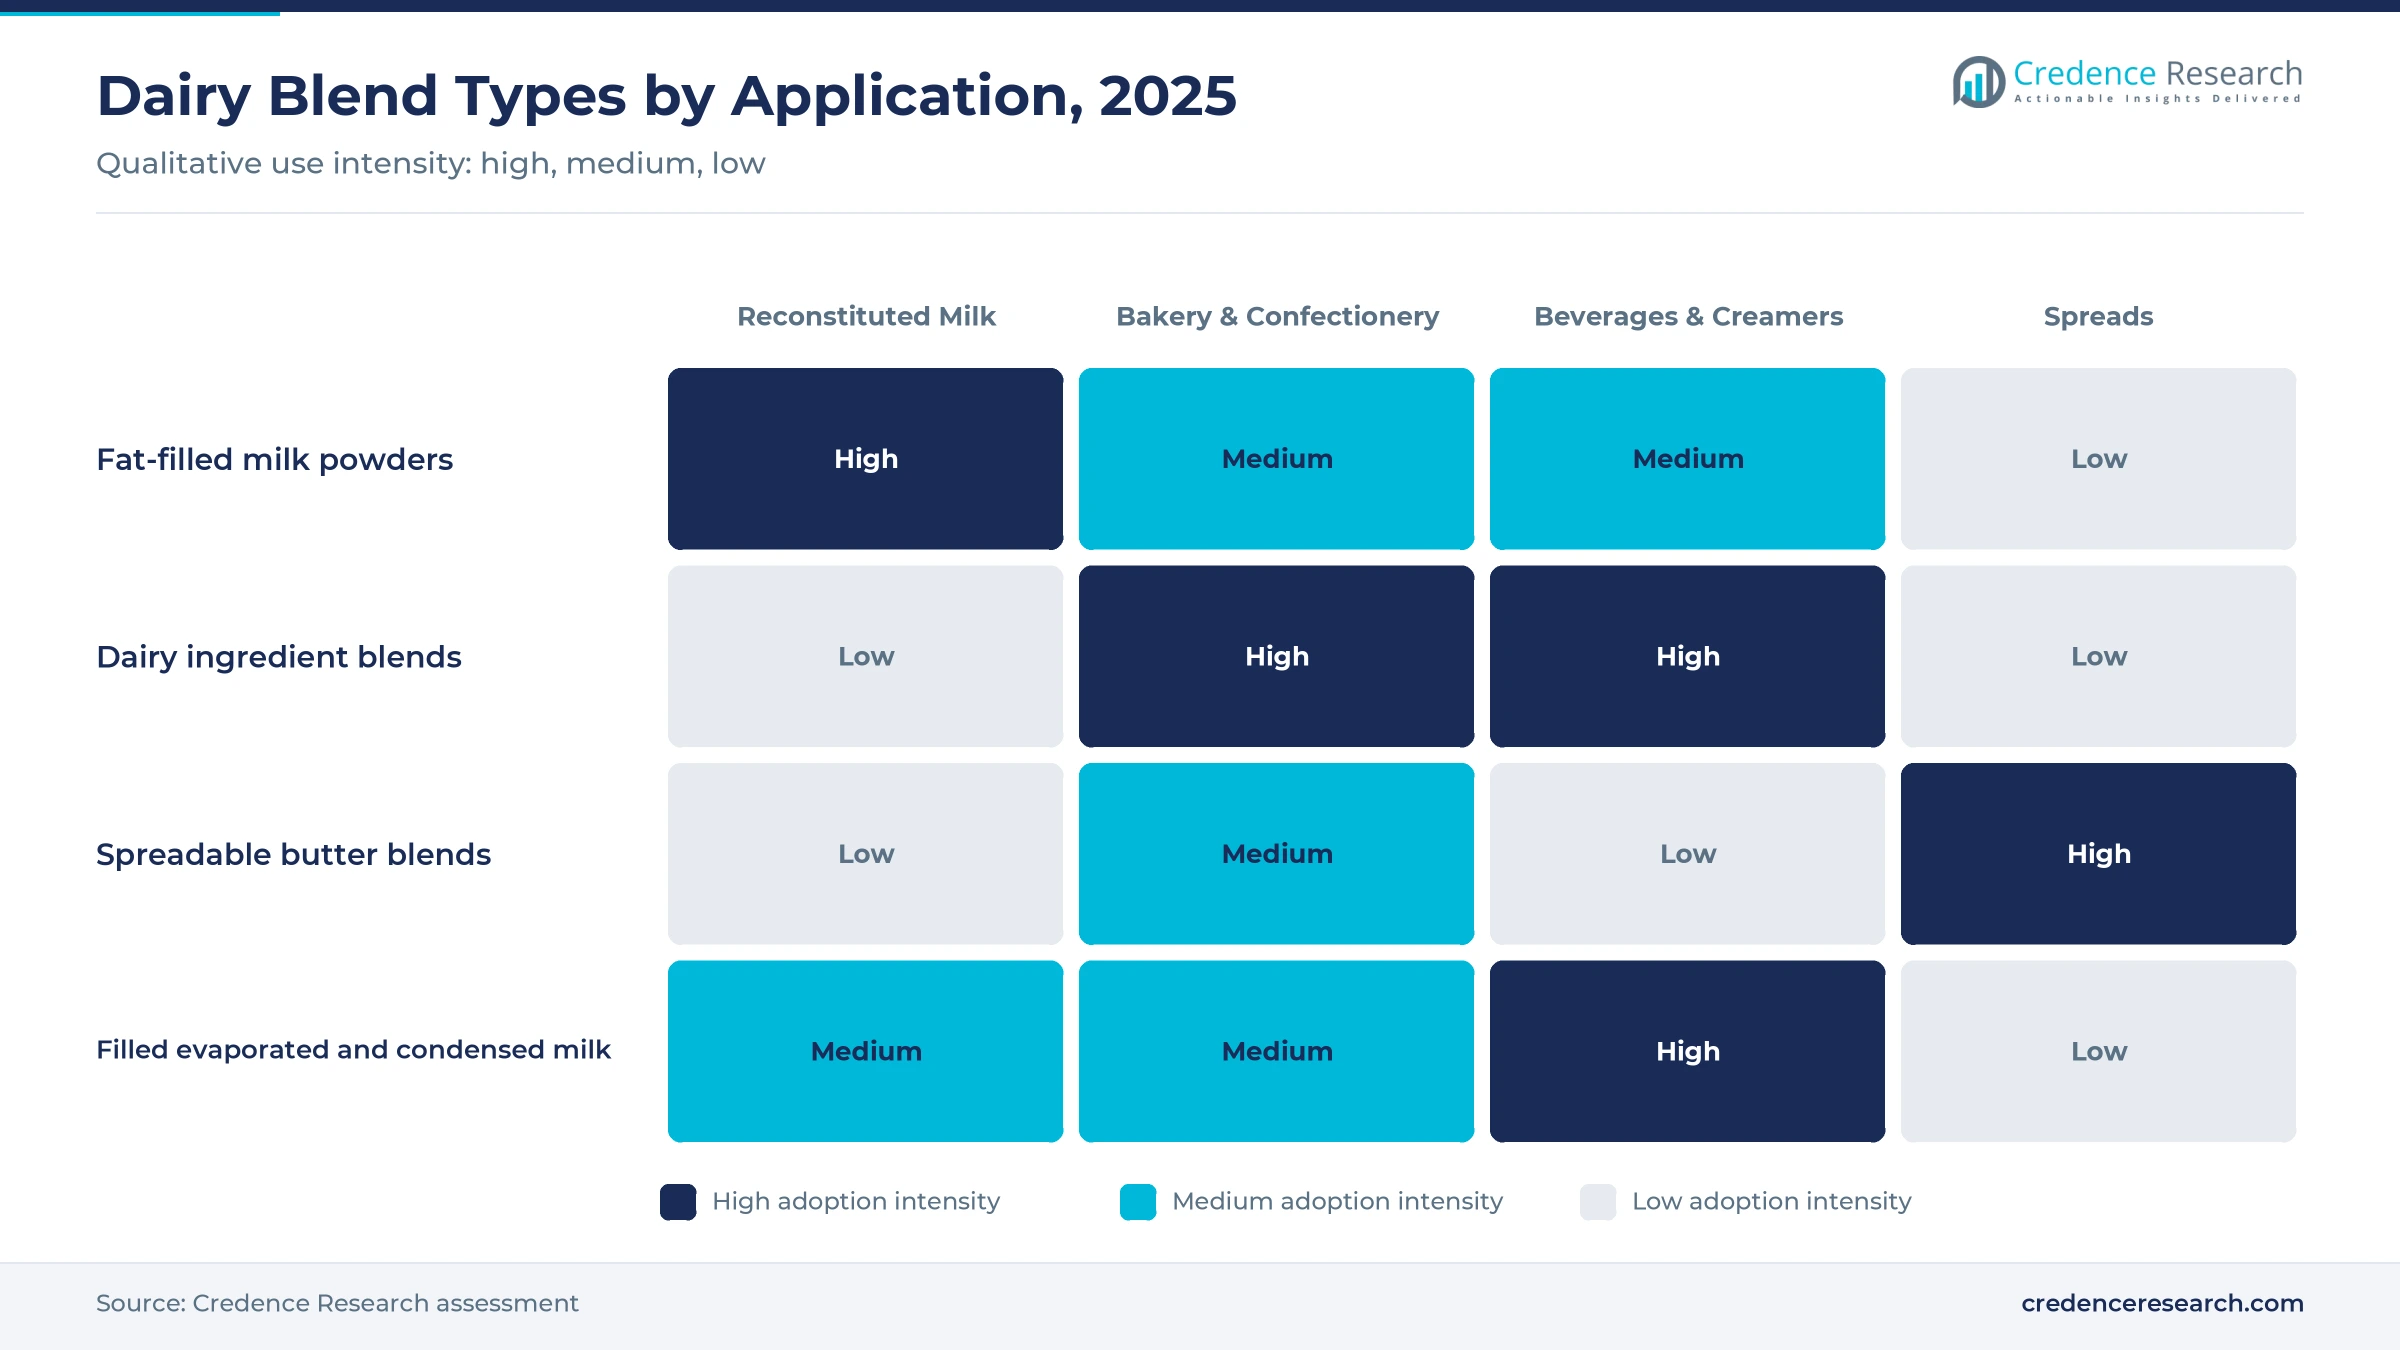
Based on type, the market is categorized into fat-filled milk powders, dairy ingredient blends, spreadable butter blends and filled evaporated and condensed milk. Fat-filled milk powders led with 35.5% of 2025 value and also grow fastest at 5.43% a year, because they sell well below full-cream powder and reconstitute into a familiar milk drink for import-dependent households. Ingredient blends earn higher margins per ton, while spreadable blends carry the highest prices but grow slowly in mature European markets.
Spreads lead application value while reconstituted milk grows fastest
Based on application, the market is categorized into household and reconstituted milk, spreads and table use, bakery and confectionery, beverages and creamers, ice cream and frozen desserts, and prepared foods and foodservice. Spreads and table use led with 23.7% of 2025 value, reflecting the high price per ton of butter blends in Northern Europe and Oceania. Household and reconstituted milk grows fastest at 5.26% a year, riding on population growth in Africa and Asia.
Shelf-stable powders dominate by form and grow fastest
Based on form, the market is categorized into powder, spreadable and liquid blends. Powder led with 61.0% of 2025 value and grows fastest at 5.20% a year, because powders travel well and keep for a year or more without refrigeration, which suits import markets with thin cold chains. Spreadable blends need a chilled chain that keeps them close to home markets, while canned liquid blends serve tea, coffee and dessert use in Southeast Asia and West Africa.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Type | Fat-filled Milk Powders | 35.5% | Fat-filled Milk Powders | 5.43% |
| By Application | Spreads & Table Use | 23.7% | Household & Reconstituted Milk | 5.26% |
| By Form | Powder | 61.0% | Powder | 5.20% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
The milk-fat price gap and West African imports lift demand
The price gap between milk fat and vegetable fat drives substitution
Dairy blends exist because milk fat is expensive and vegetable fat is not. On World Bank commodity price data, palm oil costs a fraction of what butter fetches per metric ton, and on EU customs data butter leaves the bloc at well over three times the price of fat-filled powder. Replacing milk fat with palm or coconut oil cuts the cost of a reconstituted glass of milk by close to half. Importers with thin margins and price-sensitive shoppers respond first, and the gap is structural rather than cyclical.
West African import demand anchors powder volumes
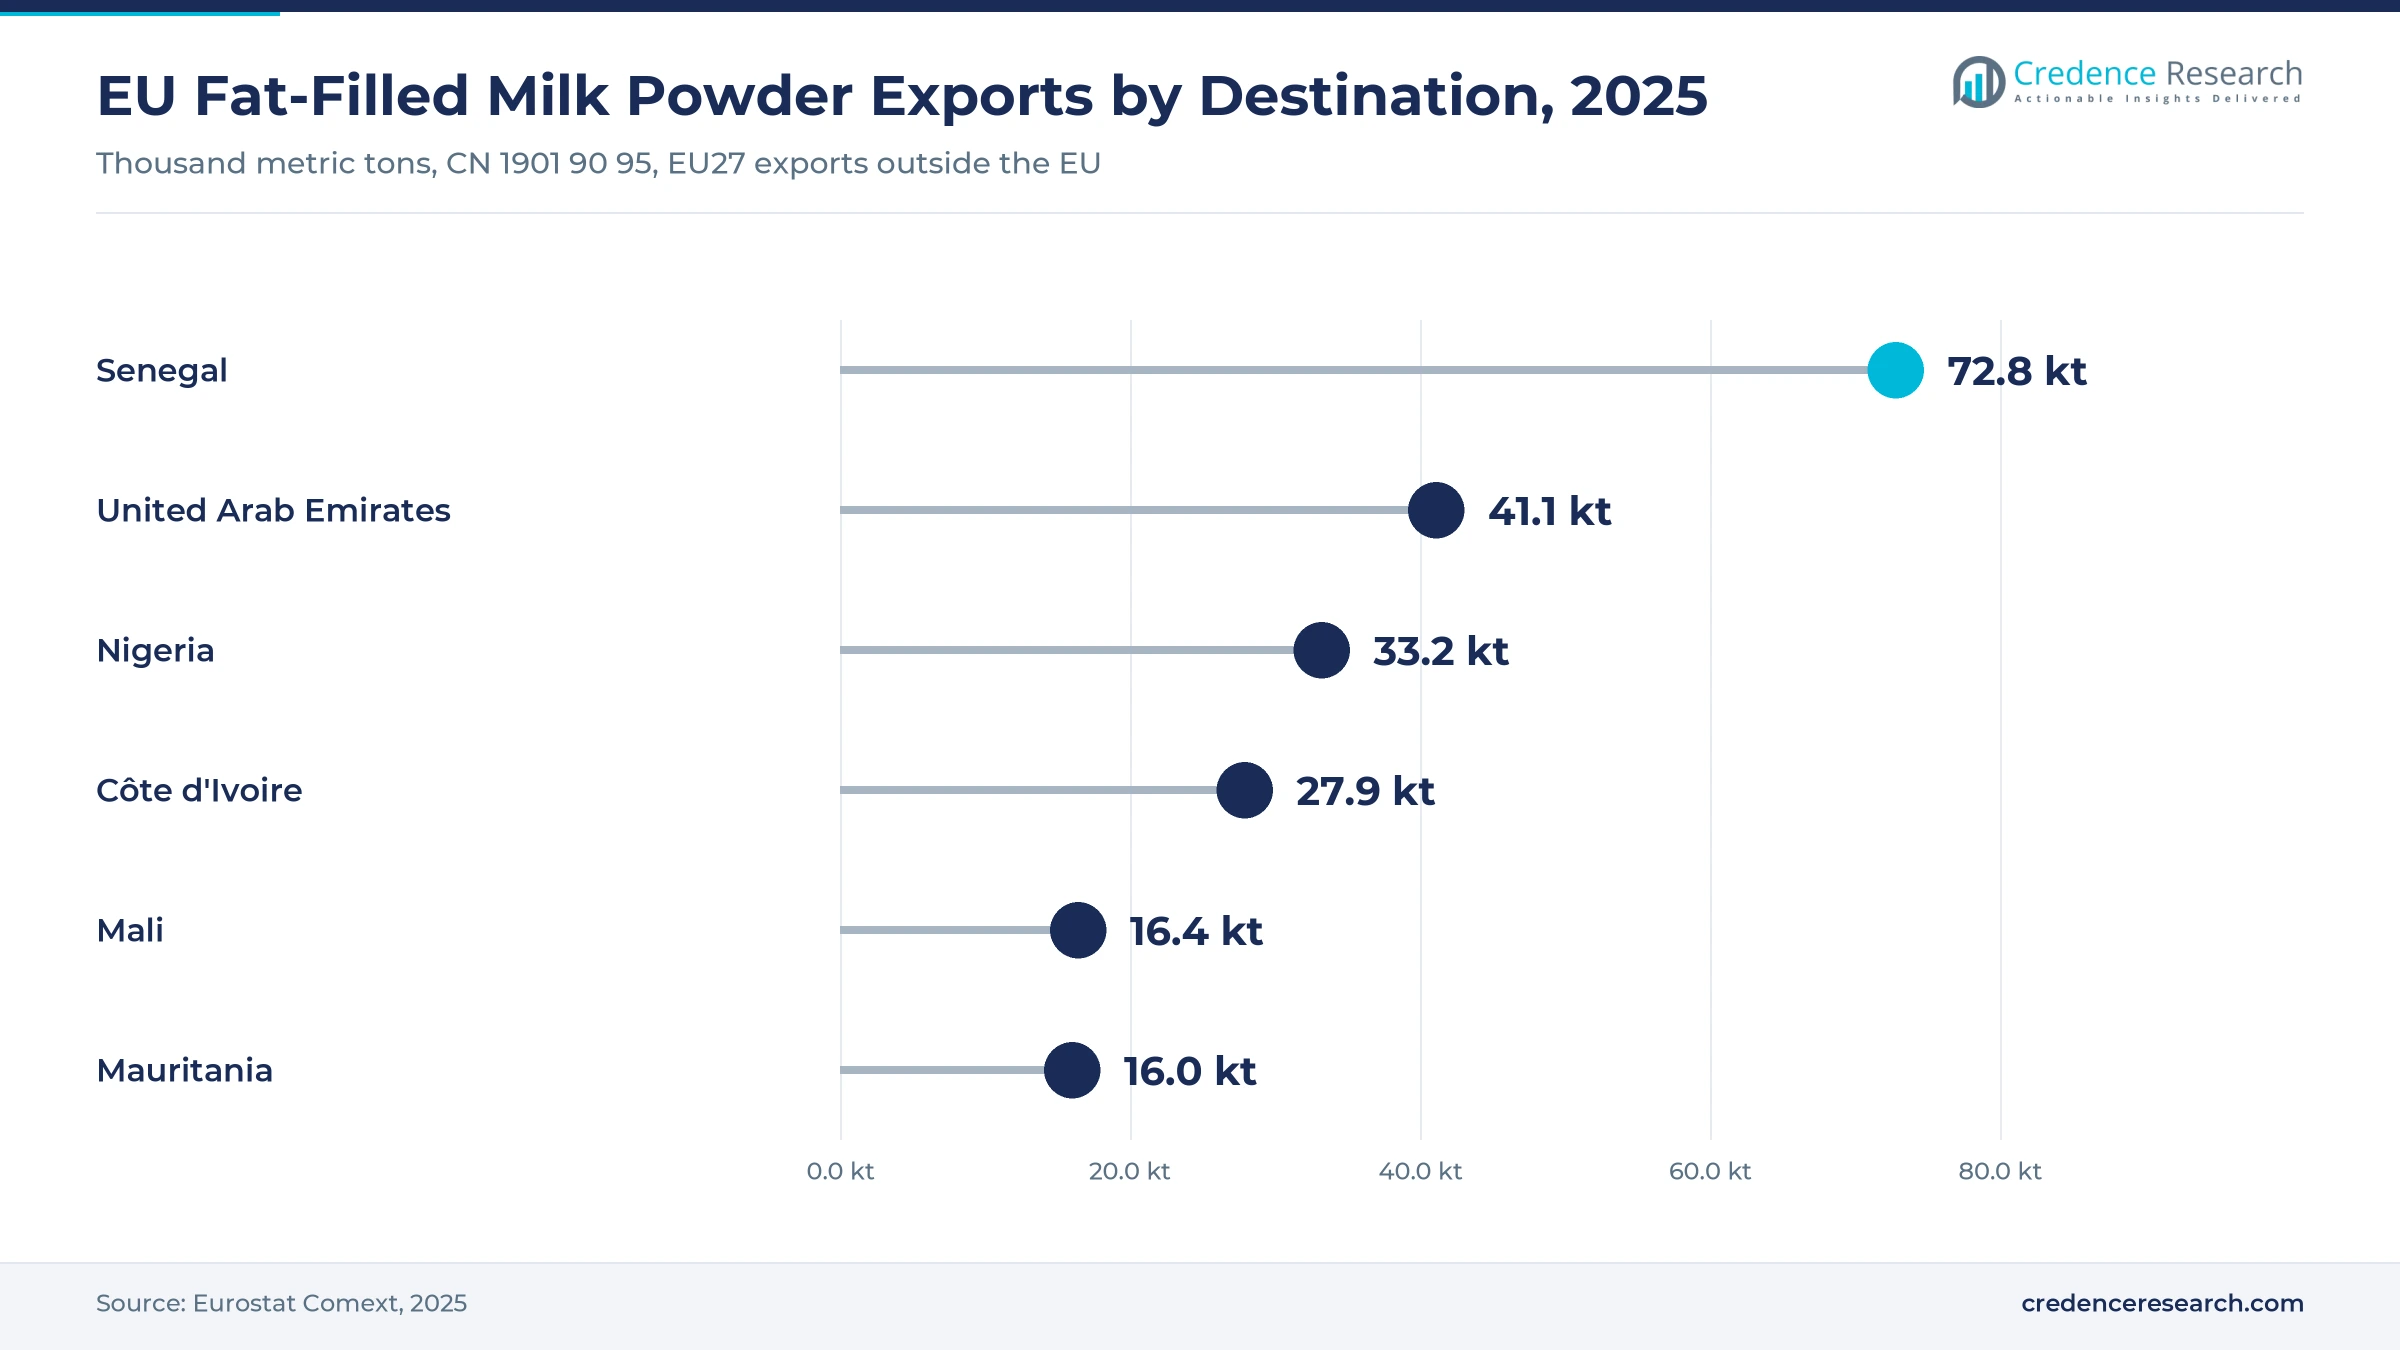
Powdered milk is how much of West Africa drinks milk, because local supply is small and cold chains are thin. On Eurostat Comext trade data, Senegal took about 72,800 metric tons of EU fat-filled powder in 2025, followed by the United Arab Emirates at 41,100, Nigeria at 33,200 and Côte d'Ivoire at 27,900. Fast population growth adds consumers every year, which makes Africa the fastest-growing region through 2035, although import-substitution policy is the main limit on this driver.
Food plants buy ready-made blends to simplify production
Bakery, ice cream and confectionery plants buy pre-blended dairy powders because one bag replaces three or four separate ingredients. The blend arrives with a fixed fat, protein and sugar ratio, which cuts weighing errors and shortens changeovers. Demand is strongest in Asian ice cream and beverage plants and among Gulf bakery chains. Suppliers win on recipe matching and qualification, which locks in repeat orders once a blend is approved, a medium-term effect.
Slow milk supply growth keeps blends competitive
Milk supply from the main exporters grows slowly, and USDA projects 1.6% growth in milk output across the five major exporting regions in 2026. In 2025, the FAO Dairy Price Index averaged 13.2% above 2024 and butter set a record in June, according to FAO. Vegetable oils rose 17.1%, but from a far lower price per ton, so the absolute gap widened. As a result, when milk fat tightens, buyers in Asia, Africa and the Middle East extend dairy solids with vegetable fat in the near term.
Cooperative mergers and new fat systems reshape dairy blends
Mergers increasingly fold milk supply and blending into fewer groups
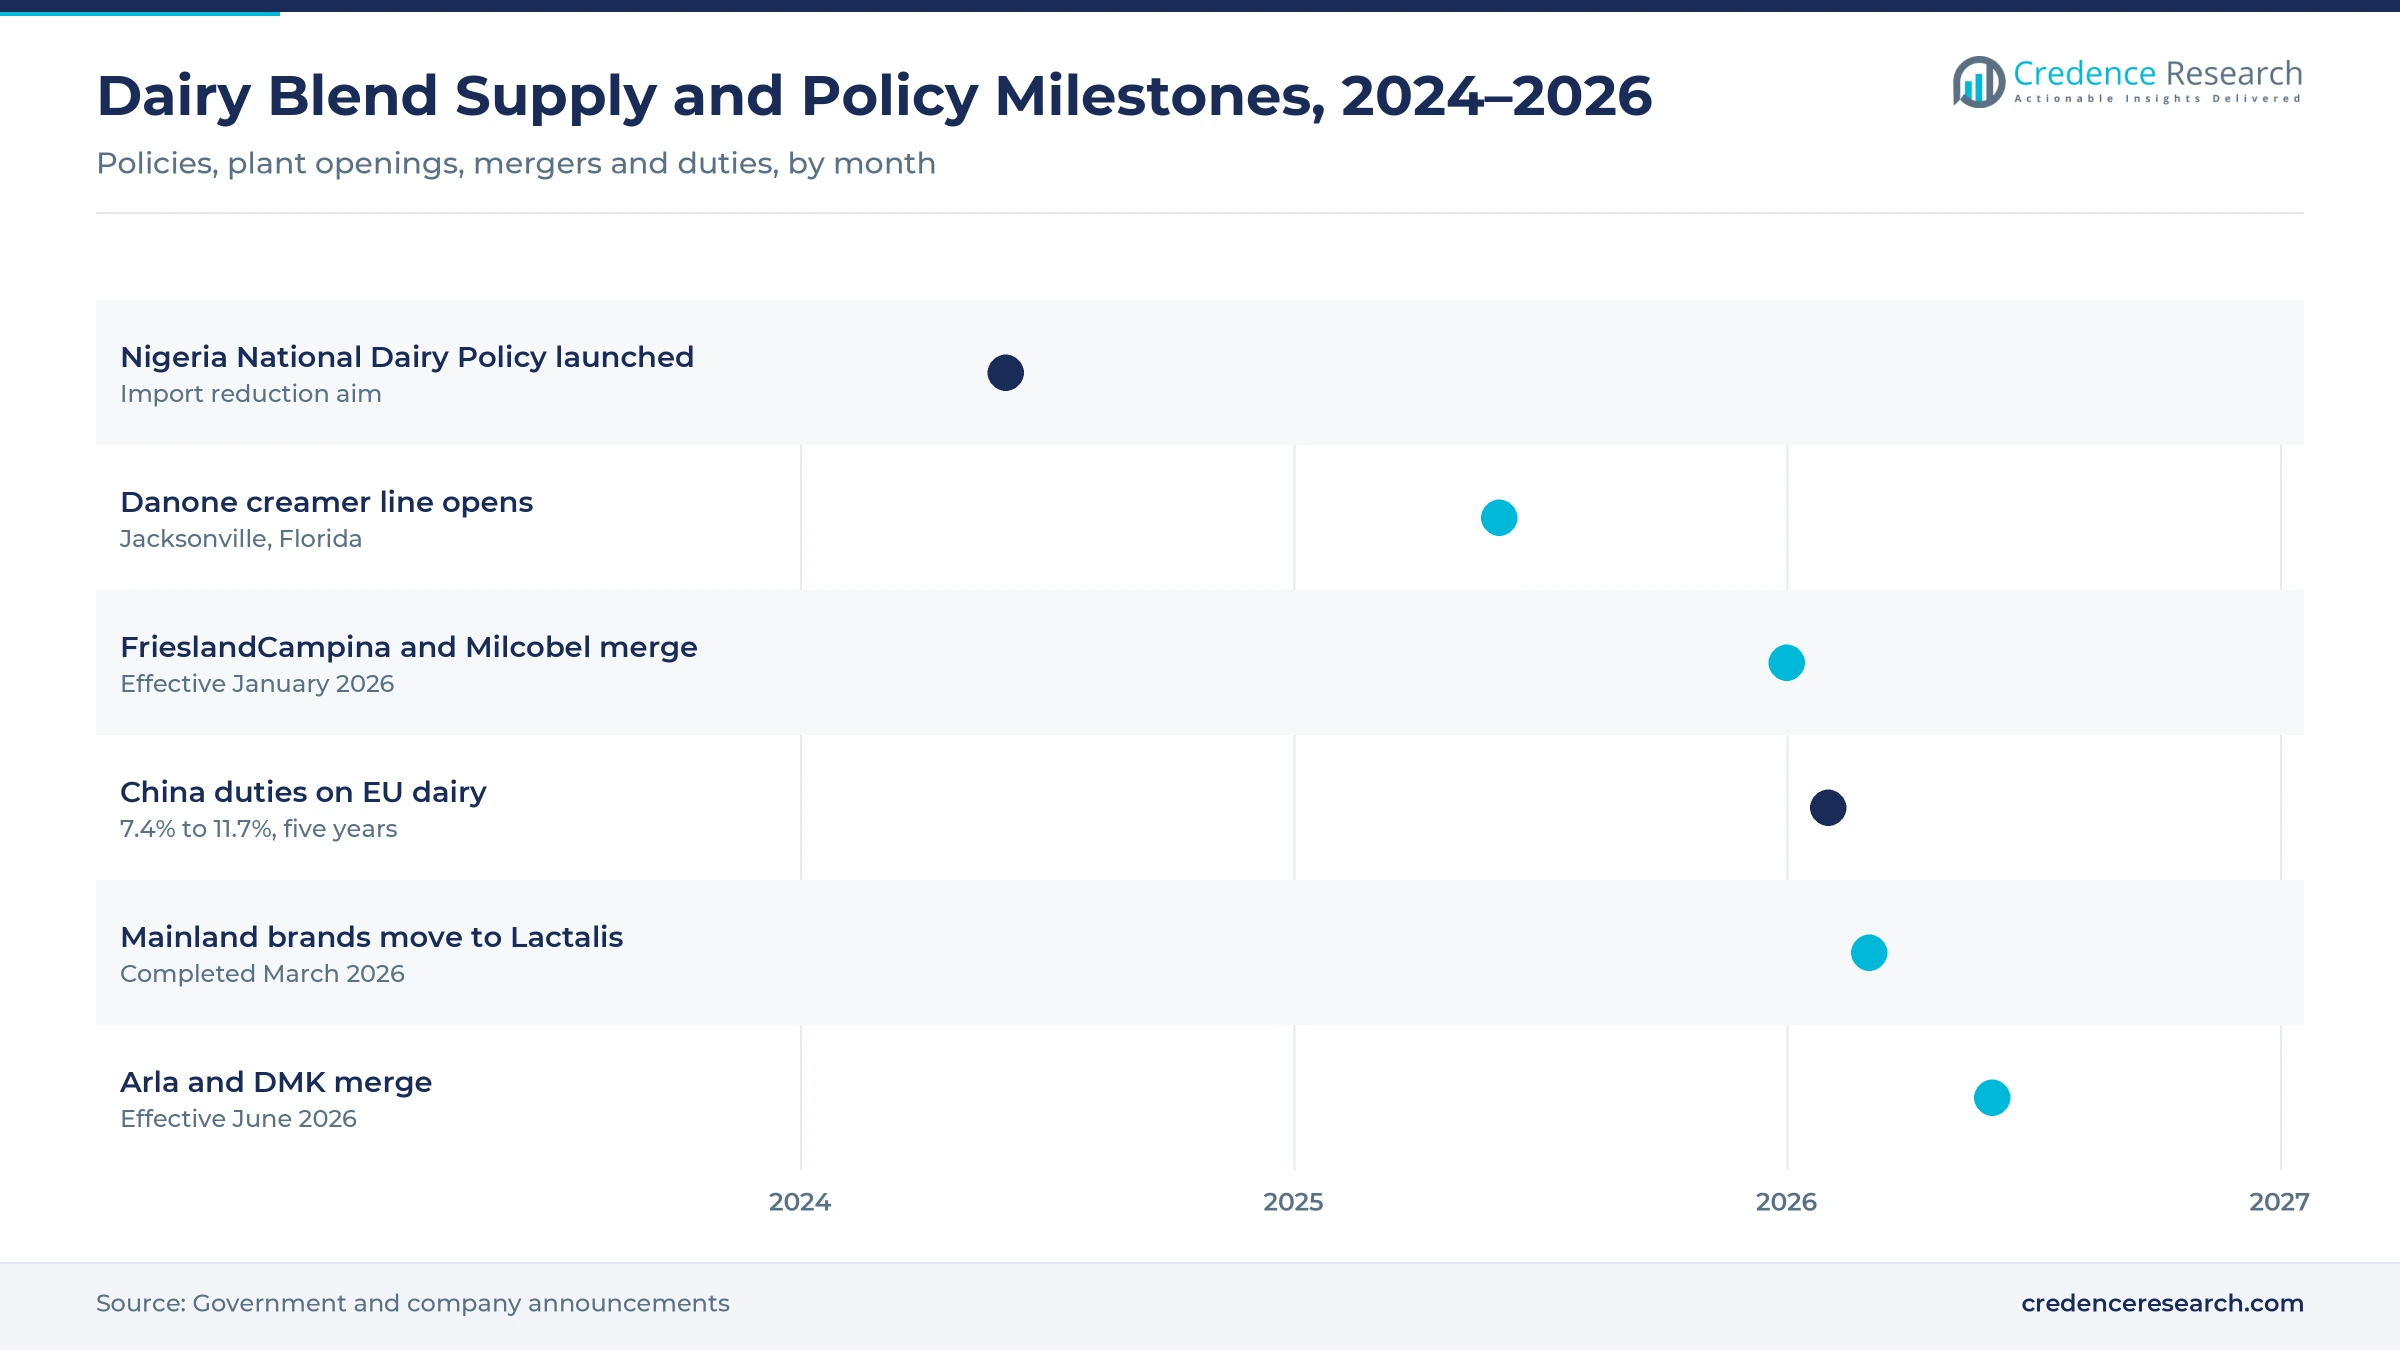
Dairy groups that own both milk and blending capacity are getting larger. FrieslandCampina and Milcobel merged on Jan. 1, 2026, joining a West African filled-milk business with Belgian butter and cheese plants. Fonterra completed the sale of its Mainland consumer business to Lactalis on March 31, 2026, and Arla Foods and DMK Group merged on June 1, 2026, creating Europe's largest dairy cooperative. Larger groups can move milk between powder, butter and cheese, which should steady blend pricing across cycles.
Fat systems shift toward palm mixes and rapeseed
Palm-based fat still dominates fat-filled powder because it is cheap, stable and solid at room temperature. Spreadable blends lean on rapeseed oil for spreadability and a cleaner fatty-acid profile, and Arla's Lurpak Spreadable lists butter and rapeseed oil as its fat. Buyer sustainability pledges and EU deforestation rules for palm and soy push a gradual move toward blends that mix palm with coconut or rapeseed oil. As a result, suppliers with traceable fat sourcing gain an edge in European retail.
Blending inside importing countries opens an opportunity
A growing part of fat-filled powder is blended inside importing countries from imported skim milk powder and local or imported vegetable fat. Repacking and blending plants in Nigeria, Senegal and Indonesia cut freight and duty costs and fit policies that favor local processing. European and Oceanian suppliers can serve this demand by selling skim powder and fat bases to local blenders or by forming joint ventures, though currency risk, import licensing and local quality control remain the main execution hurdles.
Reduced-fat, fortified and foodservice blends offer growth opportunities
Codex already allows a reduced-fat blend with more than 1.5% and less than 26% fat, giving suppliers room to compete on nutrition rather than price alone, especially in public tenders. Bakery chains and quick-service restaurants in Asia Pacific and the Middle East still buy separate milk powder, butter and fat. Ready-made bakery and dessert blends save them storage space and training time, a strong selling point where staff turnover is high, but suppliers must match local recipes and price points.
Naming rules, import policy and price swings limit blends
Naming rules keep blends off the butter shelf
In the EU, Regulation (EU) No 1308/2013 sets fat bands for spreadable fats and reserves the word butter for products made only from milk fat. Blends must use their own sales names, which places them next to margarine and other fats. Shoppers often read a butter blend as a lesser product even when most of its fat is dairy, which caps price premiums for brand owners. Clear labeling of dairy content and premium brands such as Kerrygold help narrow the gap.
Import-substitution policy is a long-run risk in West Africa
Nigeria launched its National Dairy Policy for 2023 to 2028 in June 2024, naming import reduction as an aim. The policy carries no tariff change or volume target, so Credence Research treats it as a risk to long-run demand rather than a cut to near-term volumes. Exporters of fat-filled powder to Nigeria and neighboring markets would be hit hardest if duties followed. Local blending, partnerships with domestic dairies and support for local milk collection give suppliers a hedge against tighter rules.
Volatile fat and milk prices squeeze blender margins
Blenders sit between two volatile input markets, milk fat and vegetable fat. On the dairy side, the FAO dairy index rose through 2025 and butter set a record in June 2025, yet by September 2026 the index was 19.1% below a year earlier. Contract prices adjust with a lag, so a sharp move in either input squeezes margins for a quarter or two, hitting traders and regional blenders with little hedging capacity hardest. Large cooperatives that own milk supply and can switch output between powder, butter and cheese absorb these swings better.
Trade disputes add friction for EU suppliers
China set countervailing duties of 7.4% to 11.7% on certain EU dairy products from Feb. 13, 2026, for five years. The direct volume at stake for blends is small, but the ruling adds cost for EU suppliers that sell cream and fat-based ingredients into Asia, the largest region by value. Suppliers can respond by serving Asian buyers from plants outside the EU, by shifting product mix, or by redirecting exports toward West Africa and the Gulf, where demand grows faster.
Asia Pacific leads value while Africa grows fastest
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Asia Pacific | 30.2% | 4.96% |
| Europe | 25.7% | 2.70% |
| Africa | 20.4% | 5.68% |
| North America | 8.9% | 3.49% |
| Middle East | 8.3% | 4.96% |
| Latin America | 6.5% | 4.72% |
Asia Pacific leads on powder, canned milk and factory blends
Asia Pacific held 30.2% of 2025 value and grows at 4.96% a year, buying fat-filled powder in the Philippines, Indonesia and Malaysia, filled canned milk across Southeast Asia, and ingredient blends for a growing ice cream and bakery industry in China. Malaysia and Singapore act as regional blending and export hubs. Price-sensitive households and expanding food factories support growth, while Chinese duties on some EU dairy products may shift sourcing toward non-EU suppliers and regional blenders.
Europe holds value in spreadable butter blends as the region grows slowest
Europe held 25.7% of 2025 value and grows at 2.70% a year, the slowest of any region. Spreadable butter blends make up most of that value, led by the United Kingdom, Denmark and Ireland, where brands such as Lurpak Spreadable and Kerrygold compete. Europe is also the main exporter of fat-filled powder through Irish and Dutch cooperatives, but that value is counted where it is consumed. Mergers among Arla, DMK, FrieslandCampina and Milcobel concentrate regional supply.
Africa grows fastest on West African powder demand
Africa held 20.4% of 2025 value and is the fastest-growing region at 5.68% a year. West Africa drives demand, with Senegal, Nigeria, Côte d'Ivoire, Mali and Guinea among the largest buyers of EU fat-filled powder, with Mali taking about 16,400 metric tons and Guinea about 16,000 in 2025. Local brands such as Promasidor's Cowbell and FrieslandCampina WAMCO's Three Crowns are built on imported powder. Fast population growth and thin cold chains favor shelf-stable powder, while Nigeria's import-reduction aim is the main policy risk for suppliers.
North America, the Middle East and Latin America rely on ingredient, Gulf and confectionery demand
North America held 8.9% of 2025 value and grows at 3.49% a year, buying ingredient blends for ice cream and bakery plants, butter blends in U.S. and Canadian supermarkets and dairy creamers such as Danone's International Delight. The Middle East held 8.3% and grows at 4.96% a year, with the United Arab Emirates the second-largest destination for EU fat-filled powder. Latin America held 6.5% and grows at 4.72% a year, led by confectionery and ice cream makers in Brazil and Mexico.
Co-op mergers, a brand sale and Chinese duties mark 2026
| Development | Status and market relevance |
|---|---|
| In June 2026, Arla Foods and DMK Group completed their merger, creating Europe's largest dairy cooperative. | Completed. Puts Lurpak Spreadable and Dano powders inside one group. |
| In June 2026, Lakeland Dairies announced an investment at Ballyrashane, Northern Ireland, including specialist bakery butter. | Announced. Adds butter capacity that feeds bakery blends and spreads. |
| In March 2026, Fonterra completed the sale of its Mainland consumer business to Lactalis. | Completed. Moves Oceania butter and spreads brands to Lactalis. |
| In February 2026, China began applying countervailing duties of 7.4% to 11.7% on certain EU dairy products, for five years. | In force. Adds cost for EU cream and fat-based exports to China. |
| In January 2026, the merger of FrieslandCampina and Milcobel took effect. | Completed. Joins a West African filled-milk business with Belgian butter supply. |
Fat sourcing, fortification and local blending shape recipes
- Fat systems use palm, coconut and rapeseed mixes tuned for melting point and spreadability, with traceable sourcing to meet EU deforestation rules.
- Instant powders in fat-filled grades, such as Alpen Food Group's powder with 28% vegetable fat, serve beverages, yogurt, bakery and creamers.
- Fortification with added vitamins and minerals, and Codex reduced-fat blends, let suppliers compete in public nutrition tenders and health-focused retail.
- Local blending on dry-blending and repacking lines inside importing countries cuts freight and duty costs and fits local-processing policies.
- Canned liquids such as filled evaporated and condensed milks rely on heat treatment and canning for long shelf life in hot climates.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Co-ops, blenders and brand owners share a fragmented supply
Supply sits with three groups, starting with large dairy cooperatives that own the milk and the drying towers. Tirlán sells fat-filled powder under its Millac brand, Lakeland Dairies exports fat-filled powder, FrieslandCampina runs WAMCO in Nigeria, and Arla Foods owns Lurpak. Specialist traders and blenders, including Alpen Food Group, Dana Dairy Group and Vreugdenhil Dairy Foods, buy powder and fat and sell finished blends to importers and food plants. Brand owners such as Ornua, Promasidor, Lactalis and Danone sell spreadable blends, powders and creamers to shoppers, while Fonterra left consumer butter brands with the Mainland sale. Branded spreadable blends are concentrated, while powder and ingredient blends are fragmented across hundreds of regional blenders. No company reports dairy blend sales on a comparable basis, so no share ranking is given.
Dairy blend suppliers profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Arla Foods | Dairy cooperative | Lurpak and Lurpak Spreadable; merged with DMK Group in June 2026 |
| Ornua | Dairy cooperative and brand owner | Kerrygold, including a butter blends range added in 2025 |
| FrieslandCampina | Dairy cooperative | WAMCO in Nigeria with Three Crowns filled milk; merged with Milcobel in January 2026 |
| Tirlán | Dairy cooperative | Fat-filled milk powder under the Millac brand |
| Lakeland Dairies | Dairy cooperative | Fat-filled powder exports; Ballyrashane butter investment announced in June 2026 |
| Alpen Food Group | Blender and trader | Instant fat-filled powder with 28% vegetable fat |
| Dana Dairy Group | Blender and trader | Fat-filled powders and filled condensed milk |
| Promasidor | Brand owner | Cowbell powders across Africa, including fat-filled ranges |
| Lactalis | Brand owner | Took over Fonterra's Mainland consumer brands in March 2026 |
| Danone | Brand owner | International Delight creamers; Jacksonville creamer line opened in 2025 |
| Vreugdenhil Dairy Foods | Milk powder processor | Milk powders with fat-filled grades in its range |
The price of milk fat sets the growth rate of dairy blends
Credence Research's view is that dairy blends exist because milk fat is expensive and vegetable fat is not, and that this price logic, more than marketing, sets the growth rate. The largest new volume lies in fat-filled powder for West Africa and Asia, while the highest value per ton stays with European spreadable blends. Suppliers that combine secure milk supply, traceable vegetable fats and local blending partners are best positioned. Buyers and investors should watch the milk-to-palm price gap, West African import policy and the integration of merged European cooperatives.
How Credence Research sized dairy blend sales
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built product family by product family from volume and manufacturer selling-price estimates and checked against EU customs data and disclosed brand performance; segment and regional splits are Credence Research estimates, and form values are the sum of the matching type families. Supporting evidence comes from Eurostat trade statistics, FAO and World Bank price data, USDA dairy outlooks, Codex standards and company releases.
Powder blends for Africa and Asia carry growth to 2035
Through 2035, dairy blend growth will come mainly from powder and canned blends in Africa and Asia, while European spreadable blends grow slowly. Blending will move closer to buyers as importing countries add repacking plants, and fat systems will shift toward traceable palm mixes and rapeseed. The forecast assumes that the price gap between milk fat and vegetable fat persists and that West African import policy stays free of new tariffs. A sustained fall in milk fat prices or tighter import rules would slow growth below the base case.
Frequently Asked Questions
What was the size of the dairy blends market in 2025?
What is the forecast value and CAGR of the dairy blends market?
What drives demand for dairy blends?
Which region leads the dairy blends market?
Which type of dairy blend leads the market?
Who are the major companies in the dairy blends market?
Why do buyers choose fat-filled milk powder over whole milk powder?
What challenges could slow the dairy blends market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Fat-filled Milk Powders
- 1.2.2 Dairy Ingredient Blends
- 1.2.3 Spreadable Butter Blends
- 1.2.4 Filled Evaporated & Condensed Milk
- 1.3 By Application
- 1.3.1 Household & Reconstituted Milk
- 1.3.2 Spreads & Table Use
- 1.3.3 Bakery & Confectionery
- 1.3.4 Beverages & Creamers
- 1.3.5 Ice Cream & Frozen Desserts
- 1.3.6 Prepared Foods & Foodservice
- 1.4 By Form
- 1.4.1 Powder
- 1.4.2 Spreadable
- 1.4.3 Liquid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 9.97 billion → 2035: USD 15.38 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dairy Blends Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dairy Blends Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dairy Blends Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dairy Blends Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dairy Blends Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dairy Blends Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dairy Blends Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dairy Blends Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 9.97 billion → 2035: USD 15.38 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dairy Blends Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fat-filled Milk Powders
- 12.3.7.2 Dairy Ingredient Blends
- 12.3.7.3 Spreadable Butter Blends
- 12.3.7.4 Filled Evaporated & Condensed Milk
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Household & Reconstituted Milk
- 12.4.7.2 Spreads & Table Use
- 12.4.7.3 Bakery & Confectionery
- 12.4.7.4 Beverages & Creamers
- 12.4.7.5 Ice Cream & Frozen Desserts
- 12.4.7.6 Prepared Foods & Foodservice
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Form - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Powder
- 12.5.7.2 Spreadable
- 12.5.7.3 Liquid
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dairy Blends End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dairy Blends Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dairy Blends Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dairy Blends Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arla Foods
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ornua
- 18.4 FrieslandCampina
- 18.5 Tirlán
- 18.6 Lakeland Dairies
- 18.7 Alpen Food Group
- 18.8 Dana Dairy Group
- 18.9 Promasidor
- 18.10 Lactalis
- 18.11 Danone
- 18.12 Vreugdenhil Dairy Foods
- 18.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

