
Cellular Health Screening Market Overview:
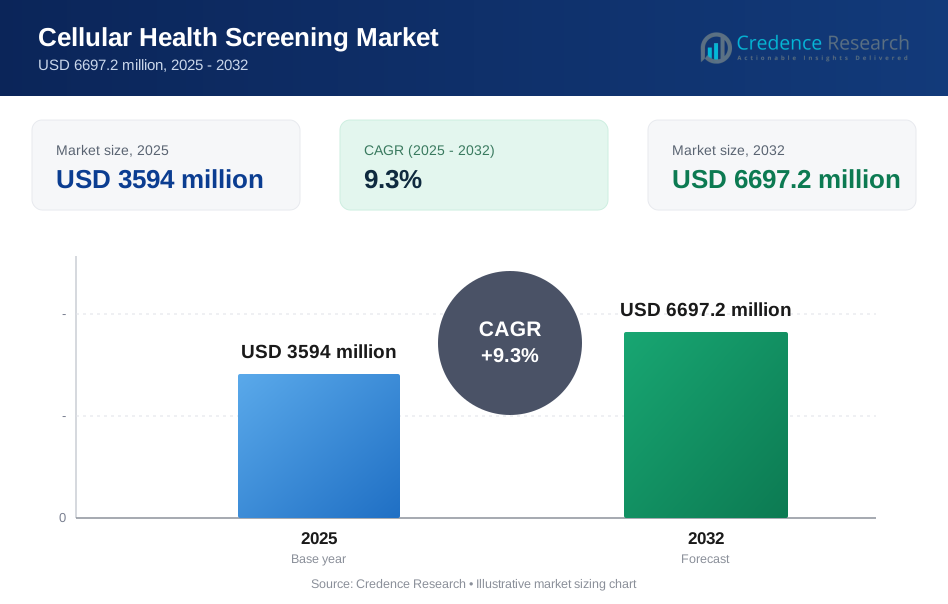
The global Cellular Health Screening Market size was estimated at USD 3594 million in 2025 and is expected to reach USD 6697.2 million by 2032, growing at a CAGR of 9.3% from 2025 to 2032. Demand expands as consumers and providers prioritize earlier risk visibility through biomarkers linked to aging, inflammation, oxidative stress, and micronutrient status. Growth also benefits from increasing test accessibility across digital ordering pathways and expanding availability of preventative screening packages across major healthcare and wellness ecosystems.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cellular Health Screening Market Size 2025 | USD 3594 million |
| Cellular Health Screening Market, CAGR | 9.3% |
| Cellular Health Screening Market Size 2032 | USD 6697.2 million |
Key Market Trends & Insights
- The global Cellular Health Screening Market is projected to grow from USD 3594 million in 2025 to USD 6697.2 million by 2032, reflecting a CAGR of 9.3% over 2025–2032.
- North America represented 44.9% of 2025 revenue, supported by mature diagnostics infrastructure and higher preventive health adoption in routine care pathways.
- Single-Test Panels accounted for the largest share of 60.8% in 2025, supported by targeted ordering patterns and easier longitudinal tracking for specific biomarkers.
- Blood-based testing led sample utilization with 66.4% share in 2025, reflecting clinical familiarity and broad compatibility across key cellular health biomarker classes.
- Hospital-based collection represented 41.2% share in 2025, reflecting clinician-directed testing pathways and bundled screening within broader diagnostic evaluations.

Segment Analysis
Cellular health screening adoption is shaped by a combination of clinical validation, consumer demand for actionable wellness baselines, and expanding access to preventive testing pathways. The Cellular Health Screening Market increasingly aligns with routine monitoring behaviors in longevity-oriented care models where biomarkers support earlier intervention decisions. Buyers show preference for tests that provide interpretable outputs, repeatable measurement over time, and clear next-step recommendations that translate into lifestyle or care-plan adjustments.
Growth momentum is also supported by expanded ordering convenience and broader biomarker menus that reduce friction for both providers and consumers. The Cellular Health Screening Market benefits from the ability to bundle multiple physiological signals into a single screening journey, improving compliance and follow-up rates. At the same time, testing providers compete to improve turnaround time, reporting clarity, and longitudinal tracking that strengthens recurring demand across wellness and preventive care programs.
By Test Type Insights
Single-Test Panels accounted for the largest share of 60.8% in 2025. Single-Test Panels remain widely adopted because targeted biomarker questions can be answered quickly without requiring broad panel interpretation. These offerings simplify ordering decisions for consumers who want focused checks such as inflammation or oxidative stress monitoring. Single-Test Panels also support repeat testing cycles, enabling trend tracking across time with consistent baselines and reduced cost and complexity.
By Sample Type Insights
Blood accounted for the largest share of 66.4% in 2025. Blood remains the primary sample because established handling workflows and standardized reference ranges support high reliability across a wide biomarker set. Blood collection also integrates smoothly into routine care settings, supporting clinician confidence and consistent pre-analytical quality. Blood testing enables broad menu coverage, allowing providers to deliver more complete screening narratives when aligned to cellular aging, inflammation, and nutrient status goals.
By Collection Site Insights
Hospital accounted for the largest share of 41.2% in 2025. Hospital collection leads because screening is frequently bundled into broader clinical workups, creating high-throughput testing volumes and stronger physician-directed utilization. Hospitals also provide structured collection protocols that reduce variability and improve result consistency. Hospital pathways support follow-up decision-making, which increases perceived utility and reinforces repeat testing behavior within preventive and chronic care monitoring programs.
Cellular Health Screening Market Drivers
Rising Preventive Health and Longevity-Oriented Care
Preventive health adoption increases demand for biomarker-based screening that supports earlier risk identification and proactive interventions. Cellular health screening is used to benchmark inflammation, oxidative stress, and nutrient status signals that can inform lifestyle and care-plan changes. The Cellular Health Screening Market benefits from consumers seeking measurable indicators of progress rather than symptom-driven testing. Provider ecosystems also expand preventive screening packages, increasing testing frequency and reinforcing recurring demand.
- For instance, InsideTracker introduced a first-responder blood panel built around 9 biomarkers, and the company reported that 65% of retested first responders improved HDL levels versus 49% in the general population; across its broader platform, it analyzes up to 48 blood biomarkers spanning 10 health categories.
Expansion of Direct-to-Consumer Access and Digital Ordering
Digital ordering and home-oriented testing pathways broaden reach beyond traditional referral-driven lab testing. The Cellular Health Screening Market benefits from simplified purchase flows, clearer reporting formats, and consumer-friendly test selection. Convenience-driven adoption supports first-time buyers and improves repeat testing cycles for longitudinal tracking. Testing providers also strengthen engagement through coaching, interpretive support, and personalized result narratives that reduce confusion and improve follow-through.
- For instance, Function Health offers 160+ lab tests through a digital platform and connects members to over 2,000 Quest Diagnostics locations, creating a scalable consumer pathway for repeat screening and longitudinal result tracking.
Broader Biomarker Menus and Integrated Panel Offerings
Broader biomarker menus increase the value proposition of screening programs by improving the completeness of health baselines. The Cellular Health Screening Market gains from multi-marker approaches that connect oxidative stress, inflammation, and cellular aging signals into a cohesive view. Integrated panels reduce friction by limiting multiple orders and streamlining sample collection. Panel-based reporting also supports clearer action pathways that reinforce customer satisfaction and repeat utilization.
Improving Clinical and Wellness Partnerships
Partnerships between labs, wellness providers, and preventive care platforms expand test adoption by embedding screening into structured programs. The Cellular Health Screening Market benefits when providers integrate results into coaching, nutrition plans, or risk-management protocols. These relationships improve patient engagement and create a repeatable pathway for follow-up testing. Partnerships also strengthen credibility and distribution, supporting growth across both consumer-initiated and provider-initiated channels.
Cellular Health Screening Market Challenges
The Cellular Health Screening Market faces challenges related to variability in test interpretation and differences in reference ranges across providers and methodologies. Consumers may struggle to translate biomarker results into clear actions when reporting lacks consistent context or when results appear contradictory across repeat tests. Market adoption can be limited when clinicians perceive limited standardization across wellness-focused offerings. Stakeholders must improve clarity, harmonize interpretation approaches, and support better education to reduce confusion.
Cost sensitivity also remains a barrier, particularly for broader panels that are not reimbursed or are perceived as discretionary spend. The Cellular Health Screening Market can experience uneven demand during periods of reduced consumer discretionary spending, especially within premium wellness segments. High-quality logistics, sample stability, and operational consistency increase delivery costs for at-home models. Providers must balance affordability with accuracy, service quality, and scalable reporting infrastructure.
- For instance, Everlywell conducted FDA-reviewed sample stability studies in partnership with Gravity Diagnostics, demonstrating that nasal swabs collected in 0.9% saline remained fully intact for up to 96 hours from time of collection double the prior 48-hour window reducing cold-chain dependency and associated shipping costs for its at-home model.
Cellular Health Screening Market Trends and Opportunities
Demand grows for longitudinal monitoring formats that convert one-time screening into recurring programs. The Cellular Health Screening Market increasingly emphasizes trend tracking, baseline building, and periodic reassessment rather than single-event testing. Providers strengthen engagement through dashboards, interpretive layers, and coaching-supported result journeys that improve retention. Longitudinal monitoring creates opportunities for subscription-like models and integrated wellness pathways.
- For instance, Function Health structures its membership around a longitudinal health-management model in which members undergo an initial test covering 100+ biomarkers, followed by a repeat panel measuring 60+ markers at six-month intervals, enabling trend-based comparisons across biological systems rather than isolated readings.
Opportunity expands through integration with preventive care ecosystems, including corporate wellness, integrative medicine, and personalized nutrition programs. The Cellular Health Screening Market benefits when screening outputs connect to care pathways such as lifestyle protocols, supplementation strategies, and referral workflows. New panels that combine cellular aging signals with cardiometabolic risk markers increase program value. Expansion across emerging markets is supported by growing diagnostics capacity and rising interest in preventive health services.
Regional Insights
North America
North America accounted for 44.9% share in 2025, supported by established diagnostics infrastructure and broader availability of consumer-initiated testing pathways. The region benefits from higher spending on preventive screening and stronger adoption of biomarker-driven wellness programs. Major laboratory networks and digital health platforms support expanded distribution and faster uptake of integrated panel offerings. Continuous investment in reporting clarity and patient engagement strengthens repeat testing behavior.
Europe
Europe represented 29.6% share in 2025, supported by growing preventive health awareness and expanding integrative care adoption. Demand is supported by increasing interest in early risk identification, lifestyle-linked health programs, and structured screening packages. Regulatory and quality expectations encourage emphasis on validated workflows and clearer result interpretation. Provider partnerships and cross-border diagnostics networks support broader access to screening services.
Asia Pacific
Asia Pacific held 18.5% share in 2025, supported by rising healthcare access, increasing wellness spending, and expanding diagnostics capacity in major economies. Demand is strengthened by growing consumer awareness of preventive screening and interest in longevity-linked health tracking. Digital-first ordering models and expanding private healthcare networks support adoption across urban populations. Scaling affordable screening pathways creates further room for expansion.
Latin America
Latin America captured 4.2% share in 2025, with demand supported by expanding private diagnostics capacity and increasing awareness of preventive screening services. Growth is shaped by affordability constraints and uneven access across countries, which reinforces focus on targeted tests and selective panel adoption. Private labs and urban wellness clinics support the most consistent uptake. Strengthening distribution and education improves conversion and repeat testing behavior.
Middle East & Africa
Middle East & Africa accounted for 2.8% share in 2025, with adoption centered in premium preventive health segments and private healthcare networks. Demand is supported by wellness tourism, rising chronic disease risk awareness, and growing investment in diagnostics infrastructure across key markets. Uptake is stronger where consumer purchasing power supports premium screening packages. Expansion of clinician-directed pathways and improved logistics can support broader access.
Competitive Landscape
The Cellular Health Screening Market remains competitive across large reference laboratories, specialty wellness diagnostics providers, and emerging digital-first testing platforms. Competition focuses on expanding biomarker menus, improving reporting and interpretive support, strengthening distribution partnerships, and reducing ordering friction. Differentiation is shaped by test portfolio breadth, sample collection convenience, turnaround time, and the ability to convert test results into clear action plans. Providers also compete on credibility, quality assurance, and program integration with preventive care pathways.
Quest Diagnostics Incorporated operates with broad laboratory scale and consumer-facing pathways that support growth through expanded test menus and interpretation support. Quest Diagnostics Incorporated leverages strong distribution reach and established lab infrastructure to support high-volume processing and consistent sample handling. The company strengthens engagement through consumer-friendly ordering and tools that help explain results and encourage follow-up testing. This approach supports retention and positions the company for recurring demand within preventive health and wellness screening workflows.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Quest Diagnostics Incorporated
- Laboratory Corporation of America Holdings (Labcorp)
- Genova Diagnostics
- SpectraCell Laboratories
- Telomere Diagnostics
- Life Length
- Repeat Diagnostics
- Cell Science Systems
- Immundiagnostik AG
- BioReference Laboratories
- Segterra, Inc.
- Titanovo, Inc.
- Cleveland HeartLab, Inc.
- DNA Labs India
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In March 2025, L’Oréal Groupe announced a strategic research and development partnership with Tru Diagnostic to study links between beauty indicators and epigenomic markers. Tru Diagnostic said the collaboration is intended to advance epigenetic science in longevity-related applications, which is relevant to cellular health screening built around biological age and epigenomics.
- In February 2025, Telo Genomics expanded and extended its agreement with Trusted Health Advisors to support the partnering and commercialization of Telo’s diagnostic technologies. The company said the expanded relationship will help advance clinical and research initiatives around its telomere-based platform, including commercialization support for its diagnostic applications.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 3594 million |
| Revenue forecast in 2032 | USD 6697.2 million |
| Growth rate (CAGR) | 9.3% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Test Type Outlook: Single Test Panels (Telomere Tests, Oxidative Stress Tests, Inflammation Tests, Heavy Metals Tests); Multi-Test Panels; By Sample Type Outlook: Blood; Saliva; Serum; Urine; By Collection Site Outlook: Home / At-Home Sample Collection; Office / In-Office Sample Collection; Hospital; Diagnostic Laboratories |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Quest Diagnostics Incorporated; Laboratory Corporation of America Holdings (Labcorp); Genova Diagnostics; SpectraCell Laboratories; Telomere Diagnostics; Life Length; Repeat Diagnostics; Cell Science Systems; Immundiagnostik AG; BioReference Laboratories; Segterra, Inc.; Titanovo, Inc.; Cleveland HeartLab, Inc.; DNA Labs India |
| No.of Pages | 327 |
Segmentation
By Test Type
- Single Test Panels
- Telomere Tests
- Oxidative Stress Tests
- Inflammation Tests
- Heavy Metals Tests
- Multi-Test Panels
By Sample Type
- Blood
- Saliva
- Serum
- Urine
By Collection Site
- Home / At-Home Sample Collection
- Office / In-Office Sample Collection
- Hospital
- Diagnostic Laboratories
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and forecast market size for the Cellular Health Screening Market?
What is the growth rate of the Cellular Health Screening Market?
Which segment holds the largest share in the Cellular Health Screening Market?
What factors are driving growth in the Cellular Health Screening Market?
Who are the leading companies in the Cellular Health Screening Market?
Which region leads the Cellular Health Screening Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cellular Health Screening Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cellular Health Screening Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 3594 million → 2032: USD 6697.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cellular Health Screening Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cellular Health Screening Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cellular Health Screening Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cellular Health Screening Market Drivers
- 3.3 Cellular Health Screening Market Restraints & Challenges
- 3.4 Cellular Health Screening Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cellular Health Screening Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cellular Health Screening Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cellular Health Screening category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cellular Health Screening Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cellular Health Screening Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cellular Health Screening market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cellular Health Screening Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cellular Health Screening Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cellular Health Screening Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cellular Health Screening (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cellular Health Screening Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cellular Health Screening Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cellular Health Screening Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cellular Health Screening Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cellular Health Screening Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cellular Health Screening Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cellular Health Screening Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cellular Health Screening Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cellular Health Screening Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
