
Europe Cardiovascular Devices Market Overview:
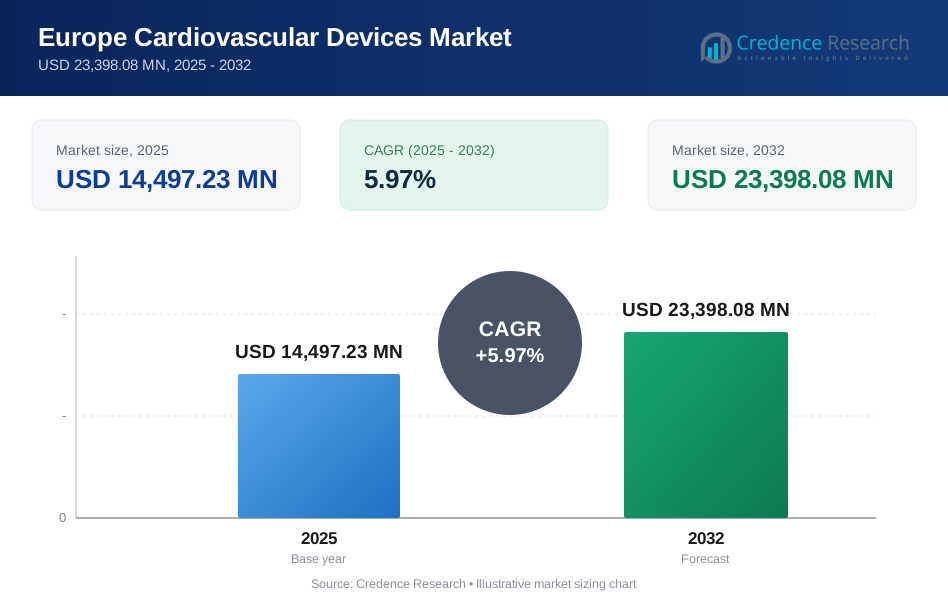
The Europe Cardiovascular Devices Market size was valued at USD 11,331.07 MN in 2021 and reached USD 14,497.23 MN in 2025. It is anticipated to reach USD 23,398.08 MN by 2032, growing at a CAGR of 5.97% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2025-2032 |
| Europe Cardiovascular Devices Market Size 2025 | USD 14,497.23 million |
| Europe Cardiovascular Devices Market, CAGR | 5.97% |
| Europe Cardiovascular Devices Market Size 2032 | USD 23,398.08 million |
Europe Cardiovascular Devices Market Insights
- Market growth is supported by cardiovascular disease burden, structural heart procedures, rhythm management demand, cardiac imaging upgrades, electrophysiology adoption and remote monitoring expansion.
- Interventional Cardiology holds a strong position because Europe continues to adopt catheter-based treatment for coronary artery disease, valve disease and structural heart conditions.
- Rhythm Management and Electrophysiology are gaining momentum due to atrial fibrillation treatment, leadless pacemakers, cardiac resynchronization therapy and pulsed field ablation systems.
- Hospitals remain the leading end-user segment because cardiovascular devices often require specialist teams, hybrid labs, cath labs, imaging suites, intensive care support and reimbursement authorization.

Europe Cardiovascular Devices Market Segment Insights
By product
By product, Interventional Cardiology held a strong position in 2025 because coronary intervention, transcatheter valve treatment and structural heart procedures require advanced catheter-based devices, imaging support and hospital-based procedural infrastructure. Cardiac Imaging remains essential because echocardiography, CT, MRI, nuclear imaging and angiography support diagnosis, procedure planning and follow-up. Rhythm Management is supported by pacemakers, implantable cardioverter defibrillators, cardiac resynchronization therapy and leadless pacing. Cardiac Assist Devices support advanced heart failure treatment. Electrophysiology is gaining demand through atrial fibrillation ablation and mapping systems. Monitoring is expanding through implantable sensors, remote monitoring, ambulatory devices and home-based cardiac surveillance.
By end user
By end user, Hospital held the strongest position in 2025 because most cardiovascular devices require specialist physicians, operating rooms, cath labs, cardiac imaging facilities and post-procedure care. Hospitals dominate Interventional Cardiology, Cardiac Assist Devices, Rhythm Management implants and complex Electrophysiology procedures. Home Care Setting is gaining importance as remote monitoring, connected cardiac devices and post-discharge surveillance expand. Ambulatory Surgical Centers are gaining relevance for selected procedures that can shift safely from inpatient hospitals to lower-cost outpatient settings. Research Institutes remain important for device trials, imaging innovation and electrophysiology research. Clinics support diagnosis, screening, follow-up and long-term monitoring.
Key Market Drivers
Cardiovascular disease burden and procedure demand
Cardiovascular disease burden and procedure demand represent major growth drivers for the Europe Cardiovascular Devices Market. Cardiovascular diseases require diagnostics, monitoring, rhythm management, interventional therapy and long-term care, creating sustained demand for device-based treatment. The European Commission says cardiovascular diseases are the leading cause of death in the EU and claim 1.7 million lives each year. The Commission also unveiled the Safe Hearts Plan in December 2025 as the first EU approach to tackling cardiovascular disease. Eurostat reported 1.68 million EU deaths from diseases of the circulatory system in 2022, equal to 32.7% of all deaths. This driver supports Cardiac Imaging, Interventional Cardiology, Monitoring, Hospital and Clinics.
Structural heart and transcatheter valve adoption
Structural heart and transcatheter valve adoption support demand for Interventional Cardiology, Cardiac Imaging and hospital-based procedures. Older patients with aortic, mitral and tricuspid valve disease increasingly benefit from minimally invasive treatment pathways. Edwards Lifesciences reported that TAVR product net sales increased in 2025, driven by higher sales of the Edwards SAPIEN platform, primarily the SAPIEN 3 Ultra RESILIA valve in the United States and Europe. Edwards also said TMTT sales increased due to higher sales of the PASCAL transcatheter edge-to-edge repair system and EVOQUE tricuspid valve replacement system in the United States and Europe. This driver supports Interventional Cardiology, Cardiac Imaging, Hospitals and Ambulatory Surgical Centers where appropriate.
Rhythm management and electrophysiology growth
Rhythm management and electrophysiology growth is strengthening device demand as atrial fibrillation, heart failure and conduction disorders require advanced pacing, ablation, mapping and monitoring solutions. Abbott reported that its Medical Devices segment sales increased 11.9% in 2025, excluding foreign exchange, with double-digit growth in Heart Failure, Electrophysiology, Structural Heart and Rhythm Management. Abbott also reported 2025 Electrophysiology sales growth of 11.6%, Heart Failure growth of 12.7%, Structural Heart growth of 11.5% and Rhythm Management growth of 10.2%, excluding foreign exchange. This driver supports Rhythm Management, Electrophysiology, Monitoring and Hospital end users.
Pulsed field ablation and next-generation cardiac mapping
Pulsed field ablation and next-generation cardiac mapping are reshaping Electrophysiology as physicians adopt nonthermal ablation technologies for atrial fibrillation care. Boston Scientific said its FARAPULSE Pulsed Field Ablation platform has treated more than 500,000 patients to date and label expansions in multiple global regions have expanded access for persistent atrial fibrillation. The company also said it received FDA approval and CE mark for the FARAPOINT Pulsed Field Ablation Catheter and is evaluating Cortex OPTIMAP mapping technology. In November 2025, Boston Scientific also announced CE mark for FARAPOINT, the newest PFA catheter in its electrophysiology portfolio. This driver supports Electrophysiology, Monitoring, Hospitals and Research Institutes.
Key Trends and Opportunities
EU cardiovascular policy supports prevention and monitoring
EU cardiovascular policy is creating opportunities for monitoring, imaging and connected care solutions. The European Commission’s Safe Hearts Plan includes a protocol on cardiovascular health checks, a proposal for personalized treatment and monitoring and an incubator for AI and digital technologies in cardiovascular health care. This trend supports Cardiac Imaging, Monitoring, Clinics, Home Care Setting and Research Institutes. Device manufacturers can benefit by developing connected diagnostic tools, AI-enabled imaging workflows, remote monitoring solutions and interoperable platforms that align with prevention-focused care.
Transcatheter and minimally invasive procedures expand
Transcatheter and minimally invasive procedures are expanding as hospitals seek shorter recovery, lower procedural burden and treatment options for older or higher-risk patients. Edwards reported 2025 growth in TAVR, transcatheter mitral and tricuspid therapies and surgical structural heart products in Europe and other major regions. This trend supports Interventional Cardiology, Cardiac Imaging and Hospital end users. Growth will favor companies with strong clinical evidence, physician training programs, imaging compatibility and catheter-based procedure support.
Remote monitoring shifts cardiac care beyond hospitals
Remote monitoring is shifting cardiac care beyond hospitals as implanted devices, wearables and connected monitoring systems support earlier intervention and long-term follow-up. The European Commission’s cardiovascular plan highlights personalized tools, AI, digital technologies and monitoring as part of the EU response to cardiovascular disease. Home Care Setting and Clinics will gain relevance as device connectivity improves. Hospitals will remain central for implantation and complex care, but post-discharge monitoring can improve follow-up efficiency and reduce unnecessary visits.
Key Market Challenges
EU MDR compliance and product lifecycle burden
EU MDR compliance and product lifecycle burden remain major challenges for the Europe Cardiovascular Devices Market. Cardiovascular devices require clinical evidence, technical documentation, post-market surveillance, vigilance systems and conformity assessment. Abbott’s 2025 results referenced incremental costs related to European Union Medical Device Regulations and In Vitro Diagnostic Medical Device Regulations compliance for previously approved products. The compliance burden can raise cost, extend timelines and affect smaller manufacturers. Companies must maintain strong regulatory teams, clinical evidence generation and post-market surveillance systems.
High procedural cost and reimbursement pressure
High procedural cost and reimbursement pressure limit adoption of advanced cardiovascular devices in some European markets. Interventional Cardiology, Cardiac Assist Devices, structural heart procedures and Electrophysiology systems require specialized equipment, trained teams and hospital budgets. National health systems assess clinical benefit, budget impact and cost-effectiveness before reimbursement. Access can vary across Western Europe, Northern Europe, Southern Europe and Central and Eastern Europe. Manufacturers must support outcomes data, health economic evidence and physician training to improve adoption.
Training and infrastructure constraints
Training and infrastructure constraints affect market growth because advanced cardiovascular procedures require skilled cardiologists, electrophysiologists, cardiac surgeons, imaging specialists and trained nurses. PFA systems, structural heart implants, cardiac assist devices and imaging-guided interventions depend on learning curves and coordinated care teams. Smaller hospitals may lack hybrid operating rooms, cath lab capacity or advanced imaging suites. Research Institutes and major hospitals can drive early adoption, but broader regional uptake requires training networks, referral pathways and service expansion.
Regional Analysis
Western Europe
Western Europe leads the Europe Cardiovascular Devices Market due to advanced hospitals, strong reimbursement, broad adoption of interventional cardiology and high access to rhythm management and structural heart therapies. Germany, France, the U.K., Switzerland, Belgium, the Netherlands and Austria support demand for Cardiac Imaging, Interventional Cardiology, Electrophysiology and Monitoring. Hospitals dominate device use due to procedure complexity and infrastructure requirements. Home Care Setting is gaining relevance as connected devices and remote monitoring expand. Growth will depend on reimbursement, EU MDR compliance, physician training and digital cardiovascular care.
Northern Europe
Northern Europe represents a high-value market supported by mature public health systems, strong digital health adoption and structured cardiovascular care pathways. Sweden, Denmark, Norway, Finland and Ireland support advanced cardiac imaging, monitoring and rhythm management adoption. Hospitals remain the primary end users for procedural devices, while Clinics and Home Care Setting support follow-up and monitoring. Northern Europe is well positioned for AI-enabled imaging and remote monitoring due to digital infrastructure and population health programs. Growth will depend on procurement policy, health technology assessment and evidence-based adoption.
Southern Europe
Southern Europe offers steady demand supported by large aging populations, hospital cardiology networks and increasing use of minimally invasive cardiovascular procedures. Italy, Spain, Portugal and Greece support demand for Interventional Cardiology, Cardiac Imaging, Rhythm Management and Monitoring. Hospital budgets and reimbursement constraints can slow uptake of premium systems, but disease burden and procedure needs remain strong. Clinics support diagnosis and long-term follow-up, while Ambulatory Surgical Centers may gain relevance for selected lower-risk procedures. Growth will depend on public-sector budgets, procurement cycles, clinician training and access to advanced devices.
Central and Eastern Europe
Central and Eastern Europe represents an expanding market with strong unmet need and improving cardiovascular infrastructure. Eurostat data show wide cardiovascular mortality differences across EU countries, with circulatory disease burden substantially higher in several Eastern European markets than in lower-rate Western European countries. Poland, Czech Republic, Hungary, Romania, Bulgaria and Baltic markets present opportunities for Cardiac Imaging, Monitoring, Rhythm Management and Interventional Cardiology. Growth will depend on EU funding, hospital modernization, procurement capacity, reimbursement expansion and specialist training.
Rest of Europe
Rest of Europe includes smaller and non-EU markets with varied access to advanced cardiovascular devices. Switzerland and Norway remain high-value markets due to strong reimbursement and advanced hospitals, while Balkan and Eastern European markets offer gradual growth as hospital capacity improves. Interventional Cardiology and Cardiac Imaging remain key demand areas, while Monitoring and Home Care Setting will expand with digital health adoption. Growth will depend on distributor networks, regulatory alignment, affordability, procurement timelines and hospital investment.
Report Attribute Details
| Report Attribute | Details |
| Historical Period | 2021–2024 |
| Base Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size in 2021 | USD 11,331.07 MN |
| Market Size in 2025 | USD 14,497.23 MN |
| Market Size in 2032 | USD 23,398.08 MN |
| CAGR | 5.97% |
| Segments Covered | Product, End User and Geography |
| Key Companies Covered | Abbott, GE HealthCare, Edwards Lifesciences Corporation, W. L. Gore & Associates, Inc., Siemens Healthcare GmbH, BIOTRONIK SE & Co. KG, Canon Medical Systems Asia Pte. Ltd, B. Braun SE, LivaNova PLC, Cardinal Health, Medtronic and Boston Scientific Corporation |
Europe Cardiovascular Devices Market segmentations
By Product
- Cardiac Imaging
- Rhythm Management
- Cardiac Assist Devices
- Interventional Cardiology
- Electrophysiology
- Monitoring
By End User
- Hospital
- Home Care Setting
- Ambulatory Surgical Centers
- Research Institutes
- Clinics
Key players
- Abbott
- GE HealthCare
- Edwards Lifesciences Corporation
- W. L. Gore & Associates, Inc.
- Siemens Healthcare GmbH
- BIOTRONIK SE & Co. KG
- Canon Medical Systems Asia Pte. Ltd
- B. Braun SE
- LivaNova PLC
- Cardinal Health
- Medtronic
- Boston Scientific Corporation
Recent Developments
- In November 2025, Boston Scientific announced CE mark for FARAPOINT Pulsed Field Ablation Catheter, expanding its electrophysiology portfolio in Europe.
- In February 2025, Boston Scientific announced CE mark for the navigation-enabled FARAWAVE NAV Ablation Catheter and FARAVIEW Software for treatment of paroxysmal atrial fibrillation.
- In 2025, Edwards Lifesciences reported higher TAVR product net sales, driven by sales of the Edwards SAPIEN platform in the United States and Europe.
- In 2025, Abbott reported double-digit growth across Electrophysiology, Heart Failure, Structural Heart and Rhythm Management within its Medical Devices segment, excluding foreign exchange.
Report Coverage
The research report offers an in-depth analysis based on product, end user and geography. It details leading market players, providing an overview of their business positioning, cardiovascular device portfolios, cardiac imaging systems, rhythm management products, cardiac assist devices, interventional cardiology platforms, electrophysiology systems, monitoring solutions and strategic relevance in the Europe Cardiovascular Devices Market. The report includes insights into the competitive environment, market trends, growth drivers, restraints and opportunities. It also examines cardiovascular disease burden, structural heart adoption, rhythm management demand, pulsed field ablation, cardiac imaging modernization, remote monitoring, EU cardiovascular policy and EU MDR compliance as major factors shaping market development. The report assesses the impact of reimbursement pressure, procedural cost, clinical training requirements, infrastructure gaps and regulatory burden on market growth. It provides strategic recommendations for device manufacturers, hospitals, clinics, ambulatory surgical centers, research institutes, distributors, investors and new entrants seeking to navigate Europe’s cardiovascular devices ecosystem.
Future Outlook
- Demand for cardiovascular devices will continue to rise as Europe addresses high cardiovascular disease burden and expands prevention, diagnosis and treatment pathways.
- Cardiac Imaging will remain essential for diagnosis, procedure planning, treatment guidance and follow-up.
- Rhythm Management will grow through leadless pacemakers, implantable defibrillators, cardiac resynchronization therapy and connected follow-up systems.
- Cardiac Assist Devices will support advanced heart failure treatment in specialist hospitals.
- Interventional Cardiology will remain a major growth area due to coronary intervention, TAVR and structural heart procedures.
- Electrophysiology will gain momentum through pulsed field ablation, cardiac mapping and atrial fibrillation treatment.
- Monitoring will expand through remote patient monitoring, implantable sensors, wearables and connected cardiac platforms.
- Hospitals will remain the leading end-user segment due to cath labs, hybrid operating rooms, imaging suites and specialist care teams.
- Home Care Setting and Clinics will gain relevance as digital cardiovascular care and remote monitoring expand.
- Competition will increase as companies compete on clinical evidence, procedure efficiency, AI-enabled workflows, EU MDR readiness, reimbursement support and physician training.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Europe Cardiovascular Devices Market and what is its projected size in 2032?
At what CAGR is the Europe Cardiovascular Devices Market projected to grow?
Which product segment is expected to hold strong demand?
Which product category is gaining momentum?
Which end-user segment leads the market?
Who are the leading companies in the market?
Which region leads the Europe market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Cardiovascular Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Cardiovascular Devices Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 14,497.23 MN → 2032: USD 23,398.08 MN)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Cardiovascular Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Cardiovascular Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Cardiovascular Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Cardiovascular Devices Market Drivers
- 3.3 Europe Cardiovascular Devices Market Restraints & Challenges
- 3.4 Europe Cardiovascular Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Cardiovascular Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Cardiovascular Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Cardiovascular Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Cardiovascular Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Cardiovascular Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Cardiovascular Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Cardiovascular Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Cardiovascular Devices Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Cardiovascular Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Cardiovascular Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Cardiovascular Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Cardiovascular Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Cardiovascular Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Cardiovascular Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Cardiovascular Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Cardiovascular Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Cardiovascular Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Cardiovascular Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Cardiovascular Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
