
Cerebral Palsy Treatment Market Overview:
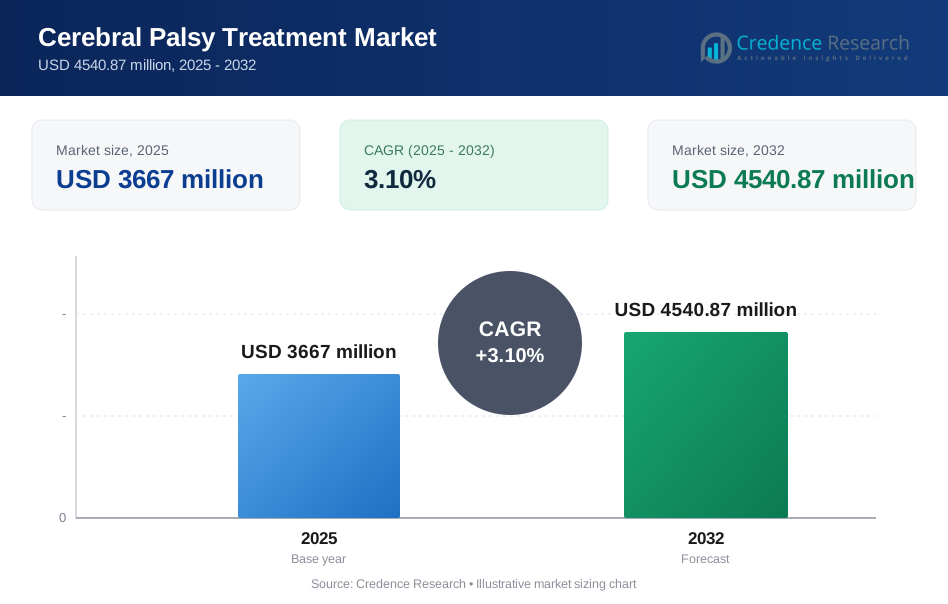
The global cerebral palsy treatment market size was estimated at USD 3667 million in 2025 and is expected to reach USD 4540.87 million by 2032, growing at a CAGR of 3.1% from 2025 to 2032. Demand expansion is primarily driven by rising diagnosis rates and earlier intervention pathways that increase the lifetime intensity of multidisciplinary care across neurology, rehabilitation, orthopedics, and pharmacy-led management. North America maintains a leading role supported by strong reimbursement, specialist density, and wider availability of procedure-linked spasticity management and assistive solutions.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cerebral Palsy Treatment Market Size 2025 | USD 3667 million |
| Cerebral Palsy Treatment Market, CAGR | 3.1% |
| Cerebral Palsy Treatment Market Size 2032 | USD 4540.87 million |
Key Market Trends & Insights
- The cerebral palsy treatment market is projected to expand from USD 3667 million (2025) to USD 4540.87 million (2032) at 3.1% CAGR (2025–2032).
- Medication accounted for the largest share of 55.80% in 2025, reflecting sustained reliance on spasticity and comorbidity management regimens.
- Spastic Cerebral Palsy represented 64.90% in 2025, keeping tone-related management pathways central to overall treatment demand.
- Children (0–13 Years) contributed 71.60% in 2025, highlighting pediatric intensity in therapy cycles, follow-ups, and long-term care planning.
- North America led with 36.90% in 2025, followed by Europe at 28.60% and Asia Pacific at 23.70%, reflecting differences in access and per-patient spend.

Segment Analysis
The cerebral palsy treatment market reflects a care pathway where pharmacologic management and rehabilitation services operate as complementary layers rather than substitutes. Medication-led management remains central due to repeat intervention cycles for tone abnormalities and ongoing management of comorbidities such as seizures, pain, and sleep or behavioral issues. Rehabilitation services reinforce functional outcomes through structured programs that extend across clinical settings and home routines, supporting recurring utilization across disease severity ranges.
Demand patterns also vary by phenotype complexity and care delivery setting. Spastic presentations account for the majority of clinical management intensity because tone abnormalities require continuous reassessment and frequent adjustments to therapy and supportive devices. Pediatric pathways dominate overall utilization, driven by early neurodevelopmental windows and caregiver engagement in ongoing therapy adherence. Home-care growth is accelerating as remote monitoring, tele-rehabilitation, and portable assistive solutions expand continuity beyond facility-based care.
By Disease Type Insights
Spastic Cerebral Palsy accounted for the largest share of 64.90% in 2025. Higher prevalence of tone-driven impairment keeps spasticity management as the most frequent clinical pathway across outpatient and specialist settings. Repeat intervention cycles such as injections, therapy programs, and orthotic optimization sustain utilization across the year. Multidisciplinary coordination across neurology, rehabilitation, and orthopedics further supports consistent demand concentration in this segment.
By Treatment Type Insights
Medication accounted for the largest share of 55.80% in 2025. Pharmacologic interventions remain foundational for spasticity management and comorbidity control, supporting repeat prescribing and specialist follow-up patterns. Combination care models often pair medication management with therapy regimens, keeping medication embedded in most care plans. Access to procedure-linked interventions and supportive drugs also reinforces medication leadership across higher-spend healthcare systems.
By Drug Type Insights
Drug utilization in the cerebral palsy treatment market is shaped by comorbidity burden and symptom clustering rather than a single uniform prescribing pathway. Seizure management frequently drives sustained anticonvulsant use in patient subsets with epilepsy comorbidity. Muscle relaxants and anticholinergics are commonly positioned around tone and movement-control needs, often requiring titration and monitoring. Antidepressants and broader supportive medications remain important in long-term care for secondary symptoms that affect function and quality of life.
By Age Group Insights
Children (0–13 Years) accounted for the largest share of 71.60% in 2025. Early intervention models amplify service intensity during pediatric developmental windows, increasing the frequency of therapy sessions and clinical assessments. Pediatric care pathways also tend to involve coordinated multidisciplinary teams that raise overall utilization across services. Caregiver engagement supports adherence to ongoing home programs, strengthening continuity of pediatric consumption.
By End User Insights
Hospitals accounted for the largest share of 49.70% in 2025. Complex diagnostics, multidisciplinary evaluations, and procedure-linked care pathways often originate within hospital-centered systems. Hospital settings also support initiation and optimization of advanced interventions that require specialized oversight and structured follow-up. Referral networks and specialist availability further reinforce hospital concentration for moderate-to-severe cases requiring integrated clinical management.
By Distribution Channel Insights
Distribution channel dynamics in the cerebral palsy treatment market follow the complexity of therapy initiation and the shift toward outpatient maintenance. Hospital pharmacies remain important for specialized therapies and procedure-adjacent medication pathways coordinated through hospital systems. Retail pharmacies support recurring refills for chronic management and broaden access for ongoing supportive medications. Online pharmacies are expanding where regulation and payer acceptance enable home delivery for maintenance prescriptions.
Cerebral Palsy Treatment Market Drivers
Expansion Of Early Diagnosis And Intervention Pathways
Earlier diagnosis and structured intervention pathways increase lifetime care intensity across medication management, rehabilitation services, and assistive solutions. Pediatric screening improvements and specialist referral networks expand the treated population within formal healthcare systems. Earlier therapy initiation drives recurring therapy cycles and repeated reassessments as functional needs evolve. Greater caregiver engagement in early years improves adherence to therapy programs and follow-up schedules. These dynamics collectively raise utilization frequency across multiple treatment modalities.
High Spasticity Burden And Long-Term Symptom Management Needs
Spasticity remains a major driver of sustained treatment demand because tone management often requires repeat interventions and ongoing functional monitoring. Care plans frequently combine clinical procedures, supportive drugs, and therapy programs to maintain mobility and reduce contracture risk. Orthotic use and assistive devices create ongoing replacement and adjustment cycles. Long-term management needs extend across childhood and adult transitions, maintaining persistent service demand. Disease complexity therefore sustains multi-year consumption across settings.
- For instance, in a phase III study of onabotulinumtoxinA for pediatric lower-limb spasticity in cerebral palsy, 381 participants were randomized, and the average Modified Ashworth Scale reduction at weeks 4 and 6 reached -1.06 in the 8 U/kg arm versus -0.8 with placebo, with additional improvement also reported on Modified Tardieu Scale and Goal Attainment Scale measures.
Growing Multidisciplinary Rehabilitation Infrastructure
Rehabilitation capacity growth supports broader therapy access through physical therapy, occupational therapy, speech therapy, and technology-enabled programs. Specialized centers and integrated hospital networks strengthen referral patterns and expand intensity-based therapy models. Robotics-assisted rehabilitation and digital progress tracking improve patient engagement and continuity. Standardized therapy protocols increase consistency of outcomes measurement and clinical adoption. Expanded rehabilitation infrastructure therefore supports both utilization and retention across patient pathways.
- For instance, Hocoma’s Lokomat was evaluated in a study involving 26 individuals with cerebral palsy aged 4 to 23 years, where post-program results showed significant reductions in median 10-meter walk test and Timed Up and Go durations, while training data showed the strongest gains in walking distance and number of steps taken.
Advancements In Orthopedic And Assistive Technology Solutions
Orthopedic correction pathways and assistive technology improvements expand treatment options for patients with significant gait impairment and musculoskeletal complications. Better device design, comfort, and functional integration supports higher adoption in daily routines. Technology-enabled mobility aids and rehabilitation devices improve tracking and personalized program design. These advances also strengthen home-care delivery by extending support beyond facility visits. The combined impact supports broader functional gains and sustained demand for enabling solutions.
Cerebral Palsy Treatment Market Challenges
Clinical heterogeneity remains a key challenge because cerebral palsy presents across diverse phenotypes and severity levels that require individualized and frequently adjusted care plans. Treatment outcomes vary due to comorbidity burden, adherence differences, and uneven access to multidisciplinary teams. Care coordination across neurology, rehabilitation, orthopedics, and community services can be fragmented, increasing pathway inefficiency. Outcome measurement also differs by provider setting, complicating standardized evaluation and reimbursement justification. These factors can slow consistent uptake of newer approaches.
- For instance, clinical evaluations of Hocoma's Lokomat robotic gait training system in children with CP demonstrated that patients classified at GMFCS levels I and II achieved a walking speed of 1.26 ± 0.31 m/s on the 10-Meter Walk Test, while children at more impaired functional levels (GMFCS III–IV) showed a 39.38% increase in distance covered and a 41.94% increase in step count underscoring how the same technology platform produces markedly different response profiles across CP severity classifications.
Cost and access constraints also limit adoption across several regions due to shortages of specialized providers and uneven reimbursement for therapy intensity and assistive technologies. Families often face logistical burdens related to frequent visits, long therapy cycles, and caregiver time requirements. Out-of-pocket exposure for devices and long-term therapy can reduce continuity, especially outside major urban centers. Supply constraints for advanced rehabilitation infrastructure can further delay therapy initiation. These challenges create disparities in care intensity and market penetration.
Cerebral Palsy Treatment Market Trends and Opportunities
Care delivery is shifting toward hybrid models that blend clinic-based programs with home-centered continuity through tele-rehabilitation and digitally guided therapy plans. Remote coaching, adherence tracking, and caregiver education tools increase engagement and can expand reach beyond specialized centers. Home-care expansion aligns with rising demand for convenience and long-term routine integration. These models also create opportunities for service providers and device makers to bundle tools with therapy workflows. Increased adoption can strengthen long-term engagement and retention.
Technology-enabled rehabilitation and assistive solutions represent a growing opportunity as robotics, sensor feedback, and progress analytics improve personalization and outcomes monitoring. Data-driven therapy pathways support more consistent documentation, enabling stronger payer discussions in higher-coverage markets. Integration across multidisciplinary teams improves coordination and reduces repetition across appointments. Partnerships between rehabilitation centers and technology providers can accelerate adoption and expand patient access. These trends support differentiation across therapy providers and device portfolios.
- For instance, in a randomized controlled trial summarized by Ekso Bionics, non-ambulatory subacute stroke patients using the company’s exoskeleton averaged 592 plus or minus 332 steps per session versus 330 plus or minus 355 in usual care, and follow-up results favored the Ekso group on gait speed and the 6-minute walk test.
Regional Insights
North America
North America led the cerebral palsy treatment market in 2025 with 36.90% share, supported by strong reimbursement, specialized pediatric neurology access, and higher availability of procedure-linked spasticity management. Hospital-centered multidisciplinary models increase treatment intensity and follow-up frequency. Robust rehabilitation infrastructure and wider assistive technology adoption support continuity across pediatric and adult transition pathways. Higher per-patient spend sustains regional leadership even as other regions expand access.
Europe
Europe accounted for 28.60% share in 2025, driven by structured healthcare coverage and established rehabilitation networks in major countries. Access to long-term therapy programs and coordinated care pathways supports stable utilization. National health systems often support pediatric care continuity, strengthening demand across therapy services. Growth continues through expanded community-based rehabilitation capacity and increased standardization of care pathways.
Asia Pacific
Asia Pacific represented 23.70% share in 2025, supported by a large patient pool and expanding specialty capacity across several markets. Growth is strengthened by improving diagnosis pathways, rising rehabilitation investments, and increasing availability of assistive devices. Per-patient spending remains lower than North America and Europe in many countries, which moderates share despite scale. Urban-centered care expansion and increasing provider networks support continued momentum.
Latin America
Latin America held 6.90% share in 2025, reflecting expanding access but persistent constraints in reimbursement breadth and specialist density. Demand concentrates in larger cities where multidisciplinary care models are more available. Therapy continuity can be limited by travel burden and affordability for long-term programs. Growth opportunities are linked to expanding rehabilitation access, stronger payer pathways, and increased availability of cost-effective devices.
Middle East & Africa
Middle East & Africa captured 3.90% share in 2025, with demand concentrated in higher-resource subregions and urban tertiary centers. Specialist availability and rehabilitation infrastructure remain uneven across broader MEA, limiting penetration in several countries. Investments in advanced hospitals and rehabilitation centers support growth in select markets. Expanded training capacity and stronger payer coverage can improve long-term access and utilization.
Competitive Landscape
The cerebral palsy treatment market features competition across pharmaceuticals, procedure-linked spasticity management, rehabilitation technology, and orthopedic and mobility solutions. Differentiation depends on clinical outcomes, physician adoption, continuity of therapy support, and integration into multidisciplinary pathways. Pricing and reimbursement influence adoption for advanced devices and intensive therapy programs, while accessibility shapes volume for chronic medications. Partnerships with rehabilitation centers and hospital systems strengthen distribution reach and long-term utilization.
AbbVie maintains a strong position through established spasticity management offerings that align with recurring intervention cycles and specialist-led care pathways. Portfolio strength is supported by physician familiarity, repeat utilization patterns, and integration into broader multidisciplinary care plans. Investment focus typically centers on sustaining clinical confidence through evidence, training, and care pathway alignment. Hospital-based initiation and follow-up routines further reinforce competitive positioning where specialist density and reimbursement are favorable.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AbbVie
- Ipsen
- Merz Pharma
- Teva Pharmaceuticals
- Pfizer
- GlaxoSmithKline (GSK)
- Novartis
- Medtronic
- Abbott Laboratories
- Supernus Pharmaceuticals
- Neurocrine Biosciences
- Acorda Therapeutics
- Hocoma (DIH)
- Össur
- Zimmer Biomet
- Stryker
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2026, United Cerebral Palsy (UCP) launched its 2026 “Change is Possible for CP” grant program, with applications opening on January 12, 2026, to support clinical and translational research focused on early diagnosis, treatment, and rehabilitation for cerebral palsy. The initiative also includes pilot and extension grants, showing UCP’s continued investment in advancing CP care pathways.
- In September 2025, Neurotech International launched an Authorised Prescriber program for NTI164 on September 23, 2025, creating a specialist-led access pathway for the therapy in pediatric neurological conditions. The update is relevant to the cerebral palsy treatment market because Neurotech had already received regulatory clearance to begin a Phase I/II trial of NTI164 in pediatric patients with spastic cerebral palsy.
- In May 2025, Cerebral Palsy Foundation, together with Cerebral Palsy Alliance and the International Cerebral Palsy Society, advanced a partnership-driven initiative through CP360, with a key global event held on May 20, 2025, during the World Health Assembly in Geneva. The coalition was presented as the first global partnership for cerebral palsy and was aimed at improving health coverage and broader treatment support for people with CP.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 3667 million |
| Revenue forecast in 2032 | USD 4540.87 million |
| Growth rate (CAGR) | 3.1% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Disease Type Outlook: Spastic Cerebral Palsy, Dyskinetic Cerebral Palsy, Ataxic Cerebral Palsy, Mixed Cerebral Palsy; By Treatment Type Outlook: Medication, Physical Therapy, Occupational Therapy, Speech Therapy, Surgical Procedures, Assistive Technology; By Drug Type Outlook: Muscle Relaxants, Anticonvulsants, Anticholinergics, Antidepressants, Others; By Age Group Outlook: Children (0–13 Years), Adolescents and Adults; By End User Outlook: Hospitals, Rehabilitation Centers, Home-Care Settings; By Distribution Channel Outlook: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | AbbVie; Ipsen; Merz Pharma; Teva Pharmaceuticals; Pfizer; GlaxoSmithKline (GSK); Novartis; Medtronic; Abbott Laboratories; Supernus Pharmaceuticals; Neurocrine Biosciences; Acorda Therapeutics; Hocoma (DIH); Össur; Zimmer Biomet; Stryker |
| No.of Pages | 340 |
Segmentation
By Disease Type
- Spastic Cerebral Palsy
- Dyskinetic Cerebral Palsy
- Ataxic Cerebral Palsy
- Mixed Cerebral Palsy
By Treatment Type
- Medication
- Physical Therapy
- Occupational Therapy
- Speech Therapy
- Surgical Procedures
- Assistive Technology
By Drug Type
- Muscle Relaxants
- Anticonvulsants
- Anticholinergics
- Antidepressants
- Others
By Age Group
- Children (0–13 Years)
- Adolescents and Adults
By End User
- Hospitals
- Rehabilitation Centers
- Home-Care Settings
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the cerebral palsy treatment market in 2025 and the forecast for 2032?
What is the CAGR for the cerebral palsy treatment market during 2025–2032?
Which segment holds the largest share in the cerebral palsy treatment market?
What factors are driving growth in the cerebral palsy treatment market?
Which companies are leading in the cerebral palsy treatment market?
Which region leads the cerebral palsy treatment market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cerebral Palsy Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cerebral Palsy Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 3667 million → 2032: USD 4540.87 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cerebral Palsy Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cerebral Palsy Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cerebral Palsy Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cerebral Palsy Treatment Market Drivers
- 3.3 Cerebral Palsy Treatment Market Restraints & Challenges
- 3.4 Cerebral Palsy Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cerebral Palsy Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cerebral Palsy Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cerebral Palsy Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cerebral Palsy Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cerebral Palsy Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cerebral Palsy Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cerebral Palsy Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cerebral Palsy Treatment Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cerebral Palsy Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cerebral Palsy Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cerebral Palsy Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cerebral Palsy Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cerebral Palsy Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cerebral Palsy Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cerebral Palsy Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cerebral Palsy Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cerebral Palsy Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cerebral Palsy Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cerebral Palsy Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
