
Market Overview:
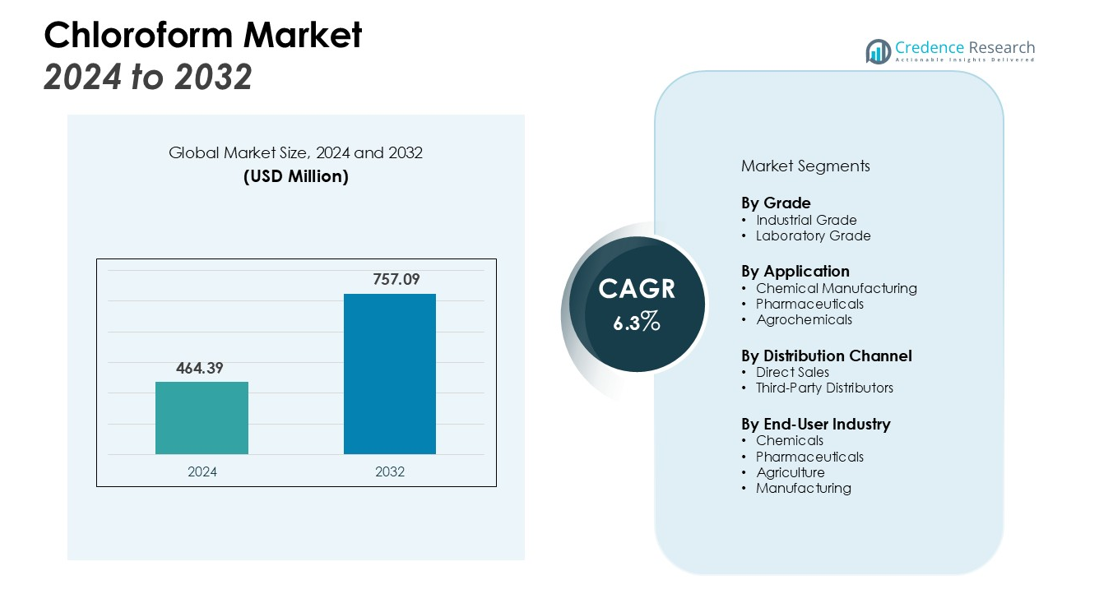
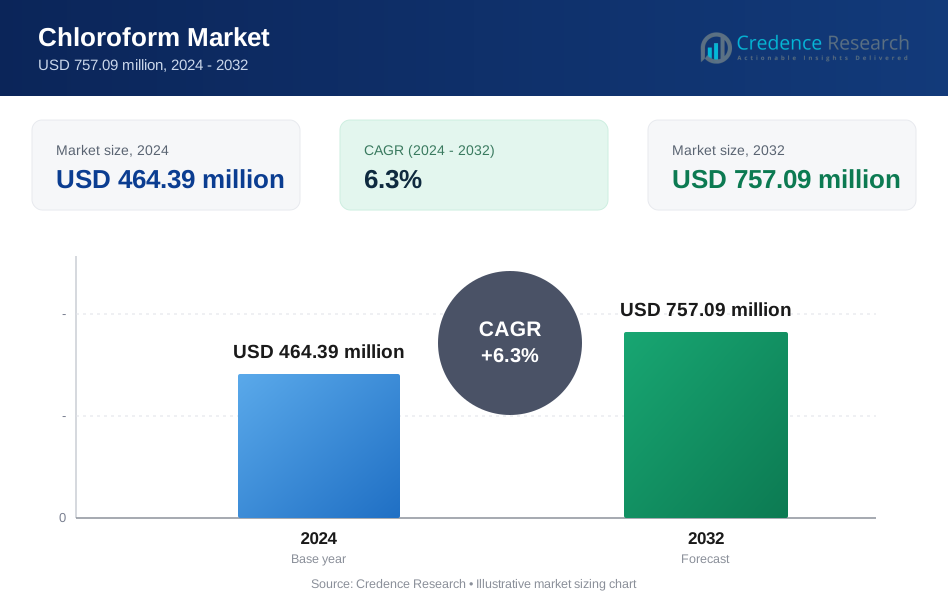
The Chloroform Market size was valued at USD 464.39 million in 2024 and is anticipated to reach USD 757.09 million by 2032, at a CAGR of 6.3% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chloroform Market Size 2024 | USD 464.39 million |
| Chloroform Market, CAGR | 6.3% |
| Chloroform Market Size 2032 | USD 757.09 million |
Key drivers of the market include the growing demand for chloroform in the production of hydrofluorocarbon refrigerants and its use in manufacturing various chemicals, including chlorofluorocarbons (CFCs). Furthermore, the rising need for chloroform in pharmaceuticals and its application in the preparation of certain drugs contributes significantly to the market growth. Stringent regulations and safety measures around chloroform’s use also propel innovations to enhance its application in industries while ensuring compliance with environmental and health safety standards. Additionally, the increasing focus on sustainable chemical production methods further drives the demand for safer alternatives and efficient production techniques.
Regionally, North America holds the largest share of the chloroform market, driven by its demand in the pharmaceutical and chemical sectors. Europe follows, with significant demand from industrial applications, while the Asia Pacific region is expected to witness the highest growth, driven by expanding chemical industries in countries like China and India. The rapid industrialization and infrastructure development in emerging economies are also expected to boost the chloroform market in this region.
Market Insights:
- The Chloroform Market, valued at USD 464.39 million in 2024, is projected to reach USD 757.09 million by 2032, growing at a CAGR of 6.3%.
- The demand for hydrofluorocarbon refrigerants, where chloroform plays a key role, contributes significantly to market growth, especially in emerging markets.
- The pharmaceutical industry is a major driver, with chloroform used as a solvent in drug formulation and research, supporting market expansion.
- Stringent regulations on chloroform's environmental and health risks drive innovation in safer, more efficient production methods.
- Health concerns, including liver and kidney damage, and environmental risks, continue to limit chloroform's market growth due to stricter regulations.
- Volatility in raw material prices, particularly chlorine and methane, disrupts production costs and introduces market instability.
- North America holds 35% of the global market, Europe 28%, and Asia Pacific 22%, with Asia Pacific expected to witness the highest growth.
Market Drivers:
Growing Demand for Hydrofluorocarbon Refrigerants
The Chloroform market benefits from the rising demand for hydrofluorocarbon (HFC) refrigerants, where chloroform plays a key role in production. These refrigerants are used in air conditioning, refrigeration, and other cooling applications, where chloroform serves as a critical component. The demand for HFCs is expanding in line with the growth of the refrigeration industry worldwide. This trend is especially pronounced in emerging economies where the need for modern refrigeration solutions continues to rise.
- For instance, Honeywell invested $300 million to build the world's largest production facility for its next-generation HFO-1234yf refrigerant in Geismar, Louisiana, to meet this growing global demand.
Increasing Use of Chloroform in Chemical Manufacturing
Chloroform is integral in the synthesis of a range of chemicals, including chlorofluorocarbons (CFCs) and other organic compounds. These chemicals find applications in industries such as agriculture, pharmaceuticals, and manufacturing. As industrial applications expand globally, the demand for chloroform increases, supporting its growth in the market. Its versatility in chemical reactions makes it a valuable solvent for many production processes, further boosting its market presence.
- For instance, BASF, a leading manufacturer of chloroformates and acid chlorides, operates with a production capacity of 60,000 metric tons per year across its sites in Ludwigshafen, Germany, and Yeosu, Korea.
Pharmaceutical Applications Driving Market Growth
The pharmaceutical industry is a major driver of the Chloroform market, where it is used in the preparation of various drugs. Chloroform serves as a solvent in drug formulation, contributing to the efficient extraction of active ingredients. The growing demand for pharmaceuticals, especially in developing regions, is significantly increasing chloroform’s market footprint. This trend is expected to continue as the healthcare industry expands, particularly with the rising prevalence of chronic diseases.
Regulatory Pressure Enhances Innovation
Strict regulatory standards surrounding the use of chloroform are promoting innovation in its production and application. These regulations focus on minimizing environmental and health risks, encouraging the development of safer production methods. Manufacturers are investing in research and development to comply with these regulations while maintaining the efficiency and functionality of chloroform. This commitment to safety and sustainability enhances the overall market growth.
Market Trends:
Shift Toward Sustainable and Eco-Friendly Production Methods
The Chloroform market is witnessing a growing trend toward sustainability, driven by increasing environmental awareness and regulatory pressure. Manufacturers are focusing on developing safer, eco-friendly production processes that reduce chloroform's environmental footprint. Innovations in green chemistry are leading to the use of renewable resources and the optimization of existing production methods to minimize waste and energy consumption. This shift aligns with global sustainability goals and is helping to meet stricter environmental regulations. It reflects a broader industry move toward reducing harmful emissions while maintaining product quality and efficacy. The trend toward sustainability is also influencing consumer preferences for greener alternatives, further encouraging changes within the Chloroform market.
- For instance, BASF is modernizing its production facilities for chloroformates and acid chlorides at its Ludwigshafen site, which has a current annual capacity of 60,000 metric tons.
Technological Advancements Enhancing Chloroform Applications
Technological advancements are significantly impacting the Chloroform market by expanding its range of applications. Improved manufacturing techniques are increasing the efficiency of chloroform production, leading to cost reductions and enhanced product availability. These advancements are particularly noticeable in the chemical and pharmaceutical sectors, where chloroform is used in the development of new compounds and drug formulations. Additionally, innovations in purification methods are enhancing the purity and performance of chloroform, making it more suitable for specialized applications. These technological developments are creating new opportunities for market growth, especially in sectors requiring high-performance chemicals and materials. The continued focus on improving production techniques and application versatility is expected to sustain the market’s expansion.
- For instance, a novel precipitation-based purification method has been developed that is over 10 times cheaper than using commercial silica column kits for DNA purification.
Market Challenges Analysis:
Environmental and Health Concerns Hindering Market Growth
One of the major challenges facing the Chloroform market is the increasing concern over its environmental and health impacts. Chloroform is classified as a hazardous substance, with exposure linked to various health issues, including liver and kidney damage, as well as potential carcinogenic effects. These concerns have led to stringent regulatory measures and increased scrutiny of its use across industries. Manufacturers must comply with safety and environmental standards, which can result in higher operational costs. These regulatory challenges restrict market expansion, particularly in regions with strict environmental policies. Efforts to minimize its harmful effects are underway but add complexity to its continued use.
Volatility in Raw Material Prices Affecting Market Stability
The Chloroform market is also impacted by fluctuations in raw material prices, which can disrupt production costs and market stability. The primary feedstocks for chloroform production, such as chlorine and methane, experience price volatility due to supply chain disruptions, geopolitical tensions, and changing market conditions. These fluctuations can lead to higher production costs, which, in turn, affect the final price of chloroform. The uncertainty surrounding raw material availability and pricing can hinder market growth and make long-term planning difficult for manufacturers. This instability presents a significant challenge to maintaining consistent production and meeting market demand efficiently.
Market Opportunities:
Growing Demand in Emerging Markets Presents Expansion Opportunities
The Chloroform market has significant opportunities in emerging economies, where industrialization and urbanization are accelerating. In countries like China, India, and Brazil, the growing chemical manufacturing, pharmaceutical, and agrochemical industries are driving the demand for chloroform. The rise in consumer awareness of health and wellness is further boosting demand in the pharmaceutical sector. Manufacturers can capitalize on this growing need by increasing production capacity and expanding their distribution networks in these regions. Additionally, as these countries continue to invest in infrastructure and industrial processes, the demand for chloroform is expected to grow steadily, offering new opportunities for market players.
Advancements in Green Chemistry Open New Application Avenues
There is an emerging opportunity for the Chloroform market in the growing field of green chemistry, where the development of sustainable production methods and environmentally friendly alternatives is a key focus. Manufacturers can explore the use of chloroform in more sustainable processes that meet evolving regulatory standards. The development of safer, more efficient production techniques is opening new applications for chloroform in industries like renewable energy, biotechnology, and advanced material science. These advancements are positioning chloroform as a critical chemical in next-generation technologies, which could drive long-term growth in its market.
Market Segmentation Analysis:
By Grade
The Chloroform market is segmented by grade, with the main categories being industrial grade and laboratory grade. Industrial-grade chloroform is widely used in manufacturing processes, including chemical synthesis and refrigeration applications, while laboratory-grade chloroform is used primarily in research and pharmaceutical formulations. The demand for laboratory-grade chloroform is increasing as pharmaceutical research and drug development activities grow, particularly in emerging markets. Industrial-grade chloroform dominates the market due to its broader application across various industries.
- For instance, chemical supplier Lab Alley offers multiple grades to meet diverse needs, including high-purity HPLC grade for sensitive analytics and lab-grade chloroform in package sizes ranging from 500 mL bottles to 55-gallon drums for industrial use.
By Application
The primary applications of chloroform include chemical manufacturing, pharmaceuticals, and agrochemicals. In chemical manufacturing, chloroform is used as a solvent and in the production of chlorofluorocarbons (CFCs). The pharmaceutical industry uses it for drug formulation, where it serves as a solvent for active ingredients. The agrochemical industry also relies on chloroform for the synthesis of pesticides and herbicides. The growing demand in these sectors drives the overall market, with the pharmaceutical application segment expected to see the highest growth due to increased drug production needs globally.
By Distribution Channel
The Chloroform market is distributed through direct sales and third-party distributors. Direct sales are common in large-scale industrial applications, where companies engage directly with manufacturers. Third-party distributors cater to smaller-scale buyers, including research laboratories and pharmaceutical companies. This segment is driven by the need for timely delivery and consistent supply, particularly in regions where local production facilities are limited. The market’s distribution channels support its widespread availability across industries, contributing to market growth.
- For instance, a distributor like Reagents, Inc. serves a wide range of customers by manufacturing and supplying chloroform in various volumes, including 500 mL, 1 L, and 4 L bottles, to meet specific laboratory and production requirements.
Segmentations:
By Grade
- Industrial Grade
- Laboratory Grade
By Application
- Chemical Manufacturing
- Pharmaceuticals
- Agrochemicals
By Distribution Channel
- Direct Sales
- Third-Party Distributors
By End-User Industry
- Chemicals
- Pharmaceuticals
- Agriculture
- Manufacturing
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America: Leading Market Share
North America holds a dominant share of the Chloroform market, accounting for 35% of the global market. Driven primarily by strong demand in the pharmaceutical and chemical industries, the region continues to maintain its leadership. The well-established healthcare infrastructure and extensive industrial base further bolster this dominance. Chloroform plays a critical role in the production of pharmaceutical formulations and agrochemicals. Regulatory agencies like the EPA enforce stringent environmental standards, prompting innovation in production methods. The U.S. remains the key driver of this growth, with Canada also contributing to market expansion due to its growing pharmaceutical and chemical production.
Europe: Significant Market Share and Steady Growth
Europe holds a significant share of the Chloroform market, contributing 28% to the global market. The demand is driven by industrial applications in sectors like chemicals, pharmaceuticals, and agrochemicals. Strict environmental regulations in the region have led to the adoption of safer and more sustainable production methods. Countries such as Germany, the UK, and France are prominent consumers of chloroform, where it is used in various applications, including laboratory research and drug manufacturing. The rising focus on sustainable industrial practices and renewable energy also creates new avenues for chloroform use, positioning Europe for steady market growth.
Asia Pacific: Rapid Market Growth and High Potential
Asia Pacific accounts for 22% of the global Chloroform market share, with high growth potential in the coming years. The region is experiencing rapid industrialization, increasing chemical production, and rising pharmaceutical needs. Countries like China and India are leading this growth, with their expanding chemical and manufacturing sectors driving demand for chloroform. Healthcare investments in pharmaceuticals, which rely on chloroform for drug development, are also on the rise. As the region continues to invest in infrastructure and industrial capabilities, the demand for chloroform is expected to surge, offering significant opportunities for manufacturers to expand in Asia Pacific.
Key Player Analysis:
- Tokyo Chemical Industry Co., Ltd.
- Sankyo Chemical Co., Ltd.
- Arihant Chemicals
- Olin Corporation
- abcr GmbH
- Kem One
- SRF Limited
- Shin-Etsu Chemical Co., Ltd.
- Khimprom
Competitive Analysis:
The global Chloroform market is characterized by a competitive landscape featuring both established multinational corporations and regional players. Key industry participants include BASF SE, Dow Chemical Company, Solvay S.A., Shin-Etsu Chemical Co., Ltd., Tokuyama Corporation, and Occidental Petroleum Corporation. These companies leverage their extensive production capabilities and global distribution networks to maintain a strong market presence. Regional players such as Arihant Chemicals, Khimprom, and SRF Limited contribute to market diversification, offering specialized products to cater to local demands. The market is moderately concentrated, with a few major players holding significant shares, while numerous smaller companies operate in niche segments. Strategic initiatives such as mergers, acquisitions, and partnerships are common, aiming to enhance product offerings and expand market reach. Innovation in production processes and compliance with stringent environmental regulations are critical factors influencing competitive dynamics. The Asia Pacific region, particularly China and India, is witnessing increased competition due to rapid industrialization and growing demand in chemical manufacturing and pharmaceuticals. Overall, the Chloroform market remains dynamic, with competition driven by technological advancements, regulatory compliance, and regional market needs.
Recent Developments:
- In August 2025, Sankyo Co., Ltd. announced the launch of a new project called KUGITAMA, involving the establishment of a subsidiary to promote pachinko-related digital and real components including game applications and a digital museum.
- In August 2025, Lubrizol expanded its strategic partnership with Arihant Innochem to include a portfolio of nutraceutical ingredients, aimed at enhancing health and wellness product offerings in the Indian market.
Report Coverage:
The research report offers an in-depth analysis based on Grade, Application, Distribution Channel, End-User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Chloroform market is expected to witness steady growth as demand increases across chemical, pharmaceutical, and agrochemical industries.
- Advances in green chemistry and sustainable production methods will enhance market opportunities, aligning with stricter environmental regulations.
- The pharmaceutical sector's growing need for chloroform in drug formulations and research will drive continued demand in this segment.
- Increasing industrial applications, particularly in refrigerant production, will further support market expansion globally.
- The Asia Pacific region will continue to be a key growth area, driven by rapid industrialization, chemical production, and healthcare investments in countries like China and India.
- Regulatory pressure will prompt innovation in safer, more efficient production technologies, ensuring long-term market sustainability.
- The shift toward eco-friendly alternatives will lead to the development of less harmful chemical production processes, boosting adoption.
- North America and Europe will maintain strong market shares, with continued demand in pharmaceuticals and chemicals, particularly in developed countries.
- Small and medium enterprises in emerging markets will drive growth through increased local production and distribution capabilities.
- The market will continue evolving with increasing investments in infrastructure and research to meet growing global demand and regulatory standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chloroform, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chloroform market projected to grow between 2024 and 2032?
Which Chloroform market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Chloroform market?
Who are the leading companies in the Chloroform market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chloroform Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chloroform Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 464.39 million → 2032: USD 757.09 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chloroform Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chloroform Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chloroform Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chloroform Market Drivers
- 3.3 Chloroform Market Restraints & Challenges
- 3.4 Chloroform Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chloroform Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chloroform Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chloroform category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chloroform Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Chloroform Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Chloroform market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chloroform Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chloroform Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Chloroform Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chloroform (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Chloroform Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chloroform Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Chloroform Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chloroform Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chloroform Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chloroform Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chloroform Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chloroform Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chloroform Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
