
DNA Forensics Market
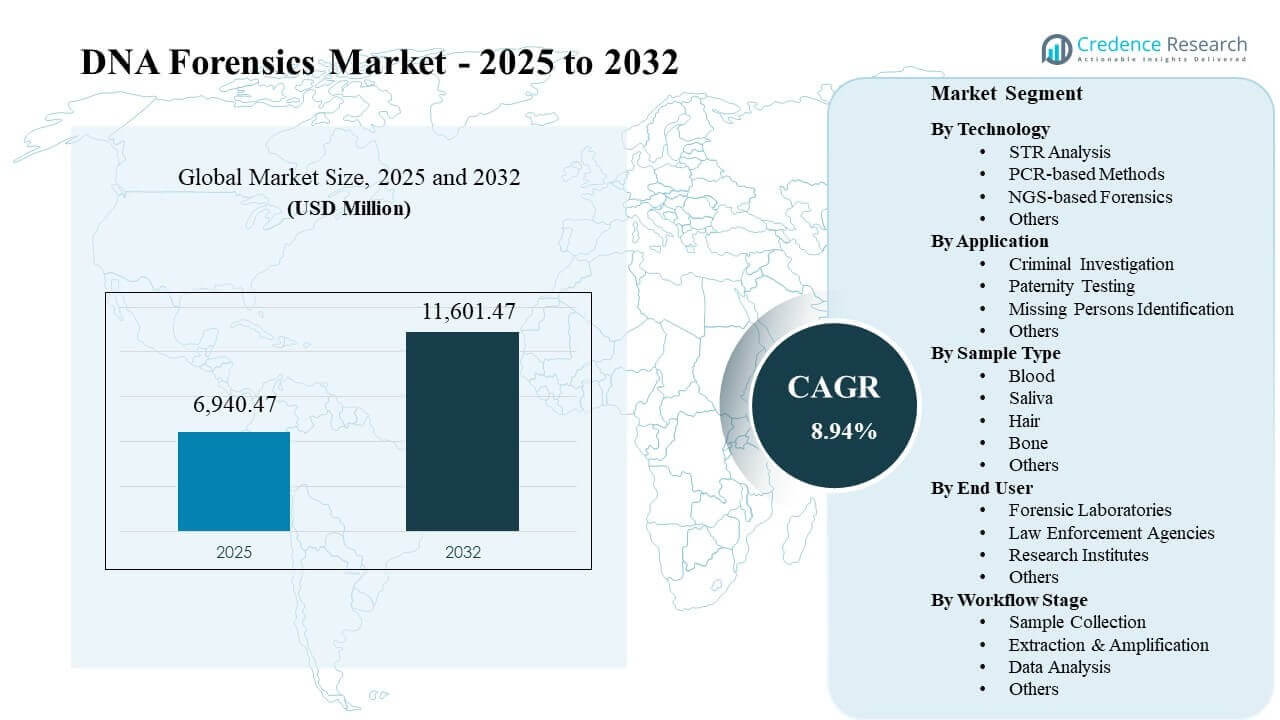
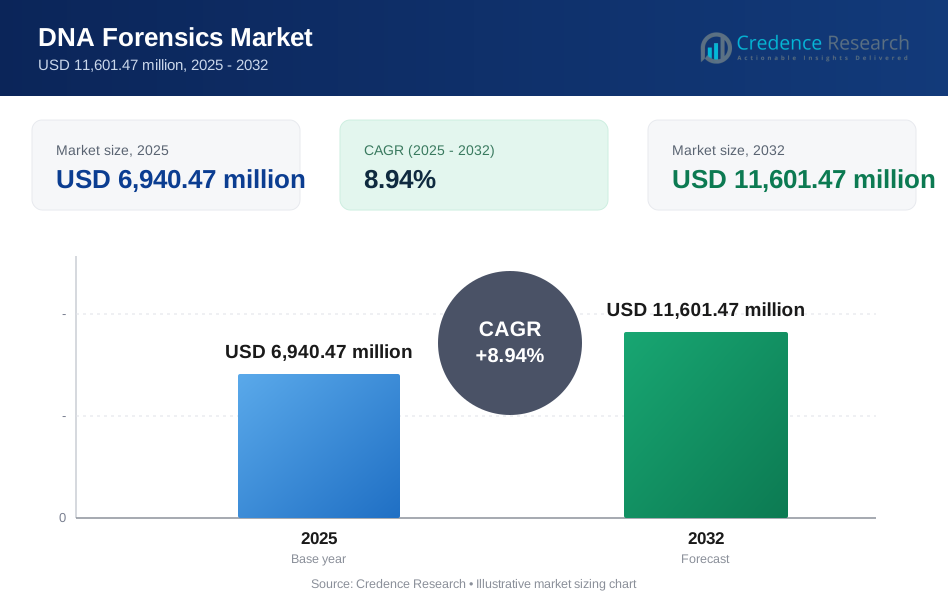
The DNA Forensics Market size was estimated at USD 6,940.47 million in 2025 and is expected to reach USD 11,601.47 million by 2032, growing at a CAGR of 8.94% from 2025 to 2032. Growth is primarily driven by expanding criminal justice reliance on DNA evidence, which is increasing routine casework volumes and raising demand for validated, repeatable workflows across accredited laboratories. A supporting catalyst is the steady modernization of forensic infrastructure, including automation in extraction and amplification and improved software-driven interpretation that helps laboratories address complex mixtures and degraded samples without compromising chain-of-custody requirements.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| DNA Forensics Market Size 2025 | USD 6,940.47 million |
| DNA Forensics Market , CAGR | 8.94% |
| DNA Forensics Market Size 2032 | USD 11,601.47 million |
Key Market Trends & Insights
- The market is projected to expand from USD 6,940.47 million (2025) to USD 11,601.47 million (2032), reflecting an 8.94% CAGR for 2025–2032.
- North America represented 41.6% of 2025 revenue, supported by mature forensic laboratory capacity and established DNA database utilization.
- PCR-based Methods accounted for the largest share of 44.7% in 2025 due to broad installed base, validated kits, and high-throughput casework suitability.
- Europe held 26.4% share in 2025, reflecting steady public-sector investment and extensive adoption of standardized laboratory workflows.
- Asia Pacific reached 19.8% share in 2025, driven by expanding forensic infrastructure and increasing national focus on identification programs.
Segment Analysis
Demand patterns in the market are shaped by the need for reliable results across routine criminal casework and more complex scenarios such as mixed DNA profiles and low-template samples. Laboratories prioritize workflows that reduce variability, strengthen reproducibility, and maintain defensible documentation for court proceedings. Automation is becoming more common in extraction and amplification, helping laboratories improve throughput and reduce analyst time per case. Software-enabled interpretation is gaining attention as laboratories seek consistent approaches to mixture deconvolution and database comparison.
Buyer selection increasingly emphasizes validated chemistries, standardized protocols, and compatibility with existing laboratory infrastructure. End users prefer platforms that support predictable turnaround times and clear quality control checkpoints across the workflow. Adoption is also influenced by training requirements, accreditation standards, and the ability to scale processing without compromising evidence handling practices. These factors continue to support demand for integrated solutions across instruments, consumables, and analysis software.
By Technology Insights
PCR-based Methods accounted for the largest share of 44.7% in 2025. PCR workflows remain preferred because laboratories rely on well-validated chemistries and standardized kits that support repeatable results across high case volumes. Compatibility with established laboratory instruments and quality systems supports consistent implementation across accredited sites. PCR methods also align with common evidence types and operational requirements, including routine throughput targets and robust documentation needs.
By Application Insights
Criminal investigation remains the dominant demand center because forensic laboratories process high volumes of casework tied to evidence collection, analysis, and database comparison. Paternity testing continues to contribute stable demand where legal and civil requirements drive repeat testing and verification. Missing persons identification supports sustained activity through targeted programs that require specialized sample handling and strict chain-of-custody practices. Across applications, validated workflows and defensible reporting remain critical purchasing and adoption criteria.
By Sample Type Insights
Blood and saliva samples support a large portion of routine workflows due to collection familiarity and established laboratory protocols. Hair and bone samples require more specialized processing because sample quality and DNA yield can vary significantly by condition and handling. Degraded samples elevate the importance of robust extraction chemistry and contamination control. Sample variability also increases demand for standardized consumables and documentation practices that support reproducible results.
By End User Insights
Forensic laboratories represent the operational core of testing demand because accredited facilities manage validated workflows, quality control, and reporting requirements. Law enforcement agencies influence demand through case volumes, evidence submission practices, and prioritization of turnaround time. Research institutes contribute to method validation, workflow refinement, and advanced interpretation approaches that later diffuse into operational settings. Across end users, procurement decisions emphasize reliability, training support, and interoperability across workflow steps.
By Workflow Stage Insights
Sample collection remains essential because evidence integrity depends on consistent handling, contamination controls, and documentation. Extraction and amplification are central value steps because these stages determine DNA quality and downstream assay performance. Data analysis is becoming more visible in procurement decisions as laboratories manage complex mixtures and higher interpretation workloads. Workflow improvements focus on reducing variability, improving throughput, and strengthening defensibility of reporting.
DNA Forensics Market Drivers
Expanding use of DNA evidence in criminal justice
Law enforcement and criminal justice systems increasingly rely on DNA evidence to strengthen investigative confidence and courtroom defensibility. This reliance drives consistent demand for validated laboratory workflows that produce repeatable results. Higher case volumes also push laboratories to modernize processes that reduce turnaround time. Procurement preferences favor integrated solutions that support documentation and quality control. These factors collectively sustain steady investment in instruments, kits, and analysis tools.
Modernization of forensic laboratory infrastructure
Public-sector investment in laboratory modernization supports adoption of automated extraction and amplification workflows. Automation reduces manual variability and improves throughput for routine casework. Modern infrastructure upgrades also support better sample tracking and standardized reporting requirements. Laboratories seek solutions that integrate with existing processes and training programs. The modernization cycle strengthens demand for complete workflow offerings rather than isolated components.
- For instance, QIAGEN’s QIAcube Connect system automates nucleic acid extraction for up to 12 samples per run with minimal hands-on time, enabling consistent processing and reducing operator-dependent variability.
Growth in database-driven identification programs
National and regional identification programs increase utilization of DNA databases and expand the scope of profile comparison workloads. Expanded database activity encourages laboratories to prioritize consistency and scalable processing. As sample volumes rise, laboratories emphasize workflows that maintain quality control across high-throughput environments. Standardization needs also elevate demand for validated consumables and software-based interpretation. These requirements support ongoing spending across multiple workflow stages.
- For instance, Verogen’s MiSeq FGx Forensic Genomics System enables sequencing of hundreds of DNA markers per run, supporting high-throughput analysis aligned with expanding forensic DNA databases.
Rising complexity of forensic interpretation needs
Complex cases involving mixtures, low-template DNA, and degraded samples require more capable workflows and stronger interpretation approaches. This complexity increases demand for improved chemistries, refined laboratory protocols, and advanced analysis software. Laboratories seek tools that support defensible interpretation and clear documentation for reporting. Training and validation requirements also influence platform selection. The combined effect supports a shift toward more comprehensive, end-to-end solutions.
DNA Forensics Market Challenges
Cost and procurement constraints can limit the pace of modernization in public-sector forensic environments. Budget cycles and tender processes may delay technology refresh and slow adoption of newer workflow upgrades. Laboratories must also allocate resources for training, method validation, and accreditation alignment. Operational constraints can intensify when case volumes rise faster than staffing capacity. These factors can extend timelines for broad deployment across regions.
Regulatory, legal, and quality requirements create additional complexity for platform changes. Evidence handling standards and chain-of-custody rules require strict process control and documentation. Laboratories may hesitate to change workflows without clear validation pathways and demonstrated reproducibility. Interoperability gaps between instruments, consumables, and software can add integration burden. These constraints can slow adoption of newer methods across routine casework.
- For instance, Promega Corporation demonstrated that transitioning to its PowerPlex Fusion 6C System required concordance studies across more than 1,000 DNA samples to meet FBI Quality Assurance Standards, while integration with existing LIMS platforms often required custom middleware development cycles exceeding 3–6 months to ensure full chain-of-custody traceability.
DNA Forensics Market Trends and Opportunities
Workflow automation is expanding beyond extraction into broader end-to-end processing, creating opportunities for integrated systems that reduce analyst time and improve consistency. Laboratories increasingly value solutions that support standard operating procedures, scalable throughput, and robust quality control checkpoints. Integrated offerings that combine validated kits with compatible instrumentation can improve implementation efficiency. Training and service capabilities are becoming stronger decision factors. This trend supports vendors that offer comprehensive workflow portfolios.
- For instance, Thermo Fisher Scientific’s Ion Torrent Genexus System integrates sample preparation, sequencing, and analysis in a single platform, delivering results in approximately 24 hours with the ability to process up to 16 samples per run, significantly reducing manual intervention and workflow variability.
Advanced interpretation capabilities are gaining attention as laboratories manage complex mixtures and larger data workloads. Improved data analysis tools can enhance consistency in reporting and strengthen defensibility for court outcomes. Opportunities are emerging for platforms that support standardized reporting formats and audit-ready documentation. Partnerships between technology suppliers and laboratory service providers can accelerate adoption. These dynamics support innovation across software and specialized reagents.
Regional Insights
North America
North America represented 41.6% of 2025 revenue, supported by mature forensic laboratory infrastructure and established operational workflows. Accreditation practices and standardized procedures support consistent adoption of validated kits and instrumentation. Demand is strongly tied to criminal justice casework volumes and database utilization. Buyers emphasize reproducibility, training support, and integration across workflow stages. Modernization programs continue to favor automation and robust interpretation capabilities.
Europe
Europe accounted for 26.4% of 2025 revenue, reflecting steady investment in forensic services and standardized laboratory practices. Public-sector procurement emphasizes validated workflows and defensible documentation for legal proceedings. Cross-border collaboration increases interest in harmonized methods and consistent reporting. Laboratories also prioritize contamination control and chain-of-custody alignment. Demand supports integrated solutions that fit established quality systems.
Asia Pacific
Asia Pacific held 19.8% share in 2025, driven by expanding forensic capacity and rising focus on identification programs. Adoption varies by country based on laboratory readiness, funding intensity, and training availability. Many buyers prioritize scalable workflows that support high throughput without compromising quality control. Modernization efforts are strengthening demand for automation and standardized consumables. Growth momentum supports incremental upgrades across the workflow.
Latin America
Latin America reached 7.4% share in 2025, supported by modernization initiatives and growing emphasis on public security capabilities. Budget sensitivity influences purchasing, leading to phased adoption and selective upgrades. Laboratories often prioritize reliable extraction and amplification workflows that integrate with existing infrastructure. Training and service access can shape vendor selection. Demand remains strongest where forensic capacity building programs are active.
Middle East & Africa
Middle East & Africa represented 4.8% of 2025 revenue, with demand concentrated in countries investing in forensic modernization and identification capabilities. Procurement often focuses on validated workflows, strong training support, and operational reliability. Laboratory density and routine casework volumes remain uneven across the region. Buyers prioritize contamination control and chain-of-custody readiness. Targeted investments can support steady growth in higher-capability workflows.
Competitive Landscape
Competition in the DNA Forensics Market centers on validated workflow performance, breadth of consumables and instruments, and software-enabled interpretation capabilities. Suppliers differentiate through end-to-end portfolio coverage, laboratory automation compatibility, and support for accredited implementation. Service, training, and method validation support influence purchasing decisions, especially for public-sector laboratories. Partnerships and platform extensions into specialized casework workflows strengthen positioning across routine and complex testing needs.
Thermo Fisher Scientific emphasizes broad portfolio coverage across instruments, consumables, and workflow-support tools used in forensic laboratories. The company focus supports standardized implementation through validated kits and compatible systems designed for repeatable results. Global distribution and service capabilities help sustain adoption across accredited laboratories and public-sector accounts. Portfolio breadth supports laboratories seeking fewer integration gaps across workflow stages. Strong training and technical support can improve implementation consistency in high-throughput environments.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Thermo Fisher Scientific
- QIAGEN
- Illumina
- Agilent Technologies
- Promega Corporation
- Roche Diagnostics
- Eurofins Scientific
- NIPPON Genetics
- Bio-Rad Laboratories
- BGI Genomics
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In March 2026, Thermo Fisher Scientific launched an advanced rapid DNA analysis platform designed to accelerate crime scene processing and enable near real-time forensic identification, enhancing its position in high-throughput forensic workflows.
- In March 2026, Eurofins Scientific expanded its forensic services division through acquisitions of regional DNA testing laboratories, increasing its footprint in law enforcement and legal markets for DNA testing services.
- In February 2026, Illumina expanded its next-generation sequencing (NGS) portfolio tailored for forensic applications, focusing on improving the accuracy of complex DNA mixture analysis for human identification use cases.
- In January 2026, Promega Corporation introduced enhanced STR analysis kits aimed at higher sensitivity and improved recovery from degraded samples, further strengthening its short tandem repeat (STR) offerings for forensic laboratories.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 6,940.47 million |
| Revenue forecast in 2032 | USD 11,601.47 million |
| Growth rate (CAGR) | 8.94% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Technology, By Application, By Sample Type, By End User, By Workflow Stage |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Thermo Fisher Scientific; QIAGEN; Illumina; Agilent Technologies; Promega Corporation; Roche Diagnostics; Eurofins Scientific; NIPPON Genetics; Bio-Rad Laboratories; BGI Genomics |
| No. of pages | 326 |
Segmentation
By Technology
- STR Analysis
- PCR-based Methods
- NGS-based Forensics
- Others
By Application
- Criminal Investigation
- Paternity Testing
- Missing Persons Identification
- Others
By Sample Type
- Blood
- Saliva
- Hair
- Bone
- Others
By End User
- Forensic Laboratories
- Law Enforcement Agencies
- Research Institutes
- Others
By Workflow Stage
- Sample Collection
- Extraction & Amplification
- Data Analysis
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the DNA Forensics Market?
What is the CAGR for the DNA Forensics Market during 2025–2032?
What is the largest segment in the market?
What factors are driving market growth?
Who are the leading companies in the DNA Forensics Market?
Which region leads the DNA Forensics Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 DNA Forensics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global DNA Forensics Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 6,940.47 million → 2032: USD 11,601.47 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 DNA Forensics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. DNA Forensics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 DNA Forensics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 DNA Forensics Market Drivers
- 3.3 DNA Forensics Market Restraints & Challenges
- 3.4 DNA Forensics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 DNA Forensics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 DNA Forensics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, DNA Forensics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 DNA Forensics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. DNA Forensics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the DNA Forensics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 DNA Forensics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 DNA Forensics Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 DNA Forensics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in DNA Forensics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New DNA Forensics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global DNA Forensics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America DNA Forensics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe DNA Forensics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific DNA Forensics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America DNA Forensics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East DNA Forensics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa DNA Forensics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. DNA Forensics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
