
Market Overview:
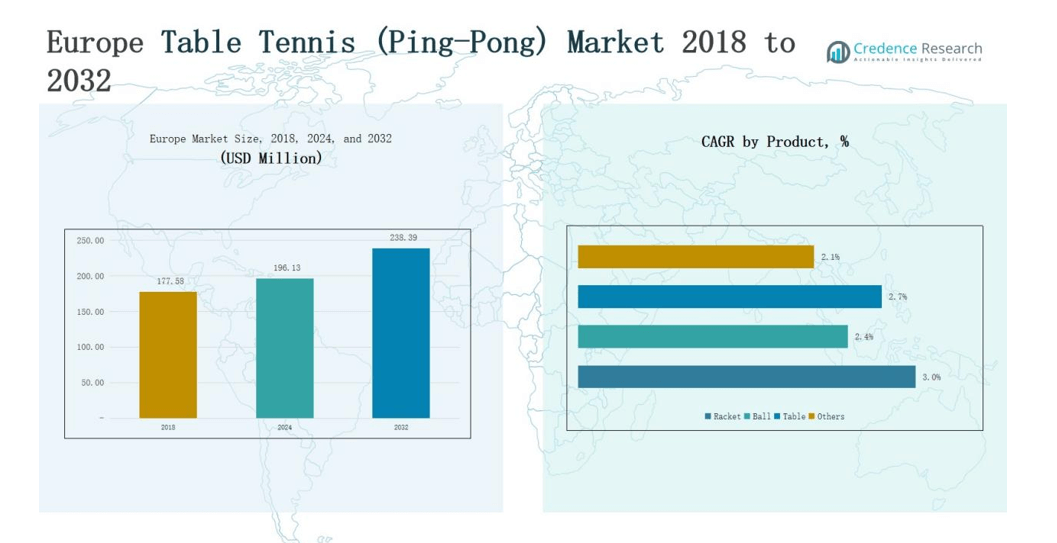
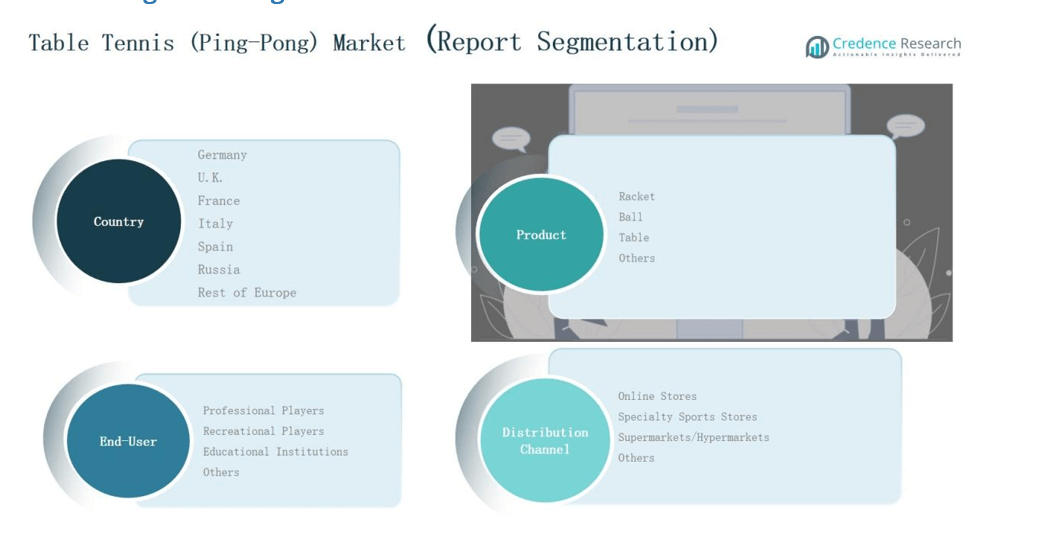
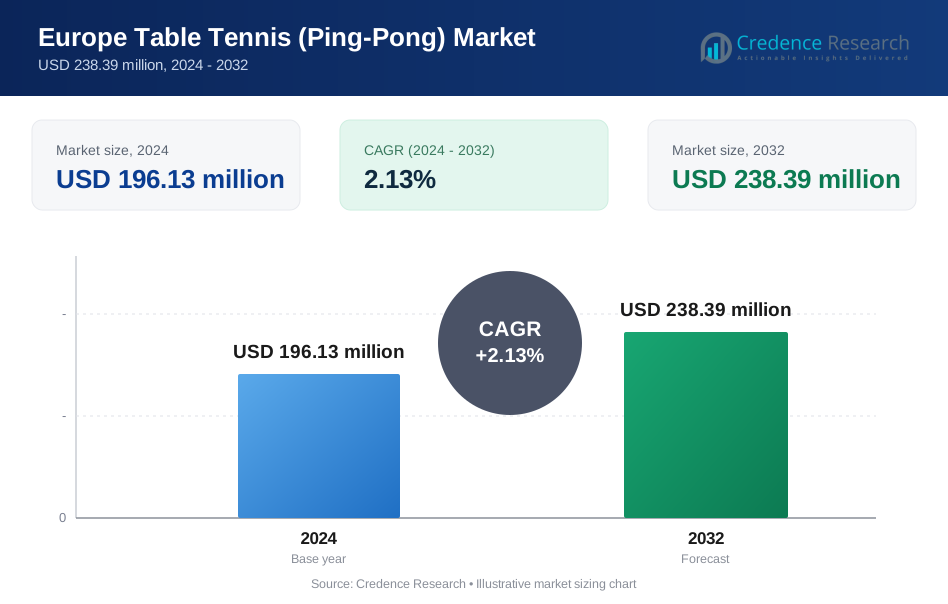
Europe Table Tennis (Ping-Pong) Market size was valued at USD 177.58 million in 2018 to USD 196.13 million in 2024 and is anticipated to reach USD 238.39million by 2032, at a CAGR of 2.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Table Tennis (Ping-Pong) Market Size 2024 | USD 196.13 million |
| Europe Table Tennis (Ping-Pong) Market, CAGR | 2.13% |
| Europe Table Tennis (Ping-Pong) Market Size 2032 | USD 238.39 million |
The Europe Table Tennis (Ping-Pong) Market is led by prominent players such as JOOLA, Butterfly, Sponeta GmbH, Nittaku, Double Happiness Co. Ltd., DONIC, STIGA, C&C, TELAMON, and KETTLER. These companies maintain strong positions through diverse product portfolios, including rackets, balls, tables, and accessories, while leveraging technological innovation, ITTF certification, and premium material usage. Strategic initiatives, including partnerships, sponsorships, and e-commerce expansion, enhance brand visibility and market penetration. Germany emerges as the leading region, commanding 22% of the market in 2024, supported by robust recreational participation, established club networks, school programs, and high consumer demand for quality and certified equipment.
Market Insights
- The Europe Table Tennis (Ping-Pong) Market is projected to grow steadily, driven by rising recreational and professional participation.
- Rackets dominated with a 42% share in 2024, fueled by innovation in materials, grip design, and ITTF approvals.
- Recreational players led end-user demand with a 48% share, supported by clubs, schools, and fitness initiatives.
- Online stores captured 38% of distribution in 2024, reflecting strong e-commerce adoption and consumer preference for convenience.
- Germany held the largest market share at 22% in 2024, supported by robust infrastructure, club networks, and high-quality equipment demand.
Market Segment Insights
By Product
Rackets dominated the Europe Table Tennis (Ping-Pong) Market in 2024 with a 42% share. Their leadership is driven by continuous innovation in blade materials, ergonomic grip designs, and ITTF approvals. Professional and recreational players demand premium rackets tailored for speed, spin, and control. Balls followed with a steady share, supported by mandatory use in competitive tournaments and training programs. Tables also contributed notably, with rising adoption in educational institutions and sports clubs. The “Others” category, including accessories and nets, remained a niche segment but supported market breadth.
- For instance, Butterfly’s Viscaria blade series, used by Olympic champion Ma Long, is known for its arylate-carbon composition that balances speed and stability.
By End User
Recreational players held the largest share of 48% in 2024, making them the key growth driver. Rising participation in clubs, fitness centers, and casual setups across Europe boosts this segment. Educational institutions followed with strong adoption, backed by sports curriculum integration and school-level tournaments. Professional players contributed a smaller but premium-driven share, as they prefer high-end equipment from global brands. The “Others” category, which includes community centers and corporate events, adds incremental demand. Recreational growth is also supported by increasing online content and awareness campaigns promoting table tennis as a health-friendly sport.
- For instance, Butterfly’s Tenergy and Dignics rubber lines remain the preferred choice among ITTF-ranked athletes, with the company officially supplying equipment for multiple international tournaments.
By Distribution Channel
Online stores led the distribution channel in 2024 with a 38% share, reflecting Europe’s strong e-commerce penetration. Consumers prefer online platforms for wide product availability, competitive pricing, and fast delivery. Specialty sports stores maintained a significant share, catering to buyers seeking expert guidance and premium equipment. Supermarkets and hypermarkets held a moderate portion, attracting casual and price-sensitive consumers. The “Others” segment, including local sports shops and direct sales from clubs, supported accessibility in smaller regions. Growth in online sales is further driven by digital promotions and partnerships with leading e-commerce platforms.
Market Overview
Rising Recreational Participation Across Europe
Increasing interest in table tennis as a recreational sport drives market expansion. Community clubs, fitness centers, and local tournaments encourage amateur engagement, boosting equipment sales. Schools and universities also integrate table tennis into physical education programs, further expanding user base. Recreational players seek affordable yet quality rackets, balls, and tables, creating demand for mid-range and premium products. Growing health awareness, low space requirement, and suitability for all age groups sustain consistent participation. This widespread adoption fuels overall revenue growth in the European market.
- For instance, STIGA Sports partnered with the Swedish Table Tennis Association in 2022 to supply schools and recreational centers with beginner-friendly rackets and indoor tables, making the sport more accessible to youth and families.
Technological Innovation in Equipment
Continuous innovation in materials, design, and manufacturing of rackets, balls, and tables supports market growth. Advanced composite blades, high-spin rubber surfaces, and ergonomic grips enhance player performance. Manufacturers focus on durable, lightweight, and eco-friendly products to meet evolving consumer preferences. Integration of ITTF-certified standards ensures acceptance in professional competitions, further boosting credibility. These innovations attract both professional athletes and recreational users. Enhanced product performance and customization options drive repeat purchases and strengthen brand loyalty across Europe.
Expansion of Online and Specialty Distribution Channels
E-commerce platforms and specialty sports stores drive market accessibility and visibility. Online channels offer convenience, wide product variety, and competitive pricing, appealing to tech-savvy consumers. Specialty stores provide expert guidance and premium equipment, enhancing purchase confidence. Retail expansion across urban and semi-urban areas improves availability, while digital marketing campaigns boost brand awareness. Partnerships with online marketplaces and clubs amplify reach. This multi-channel presence ensures consistent product supply, broadens customer base, and accelerates adoption, supporting sustainable revenue growth in Europe.
- For instance, Decathlon expanded its digital platform in Europe by integrating real-time inventory visibility across its 1,817 global stores, ensuring faster delivery and product availability for customers.
Key Trends & Opportunities
Integration of Table Tennis in Schools and Community Programs
Educational institutions increasingly adopt table tennis for physical education and extracurricular activities. School-level competitions, inter-school tournaments, and recreational clubs enhance student participation. Governments and local sports authorities promote sports infrastructure, creating procurement opportunities for manufacturers. This trend generates steady demand for tables, balls, and training equipment. Additionally, collaboration with coaches and sports academies presents avenues for branded products and training kits. Expanding youth engagement fosters long-term growth potential while establishing brand recognition among future professional and recreational players.
- For instance, table tennis clubs in the UK actively collaborate with schools through after-school programs, school visits, and local tournaments, boosting student participation and community engagement.
Premiumization and Customization of Equipment
Consumers increasingly prefer high-quality, performance-oriented equipment tailored to skill levels. Professional and semi-professional players seek customized rackets and accessories for competitive advantage. Manufacturers capitalize on premium offerings with advanced rubber sheets, specialized blades, and ergonomic designs. Limited-edition products, branded collaborations, and eco-friendly options attract niche buyers. This trend encourages higher spending per customer and strengthens market differentiation. Growing awareness of product benefits, combined with rising disposable incomes, offers manufacturers a strategic opportunity to capture high-margin segments and expand market share.
- For instance, Butterfly’s “Zhang Jike Super ZLC” racket, priced above $350, is engineered with carbon-fiber reinforcement and is widely adopted by international players for speed and control.
Key Challenges
High Price Sensitivity Among Recreational Users
While demand is rising, many recreational players prioritize affordability over premium quality. High costs of professional-grade rackets, tables, and ITTF-certified balls limit adoption in price-sensitive regions. Competition from local, low-cost manufacturers creates pricing pressure. Brands must balance quality and cost to retain market share. Failure to address this sensitivity may reduce penetration in emerging markets and smaller European towns. Additionally, excessive reliance on mid-to-high-end segments can restrict growth among casual players seeking entry-level equipment.
Fragmented Market with Numerous Players
The European table tennis market features many global and regional players, creating intense competition. Small manufacturers and local brands challenge established companies ith competitive pricing and regional familiarity. Differentiating products becomes difficult, particularly for mid-range offerings. Market fragmentation complicates distribution, marketing, and brand recognition strategies. Companies must invest in R&D, promotions, and partnerships to maintain competitiveness. Fragmentation may also lead to inconsistent quality standards, affecting consumer trust and slowing adoption, especially among newer recreational players.
Limited Awareness in Emerging Regions
Despite urban popularity, table tennis remains underdeveloped in smaller towns and rural areas. Lack of awareness and limited access to equipment and clubs restrict market growth. Promotional initiatives, training programs, and government-supported events are less frequent in these regions. This disparity limits potential recreational and professional player base, constraining overall revenue. Companies must invest in marketing, grassroots campaigns, and distribution infrastructure to expand reach. Without strategic initiatives, untapped markets may remain inaccessible, slowing the growth trajectory of the European table tennis sector.
Regional Analysis
Germany
Germany holds the largest share of the Europe Table Tennis (Ping-Pong) Market with 22% in 2024. It benefits from a strong sports culture, high disposable incomes, and extensive recreational infrastructure. Clubs and schools actively promote table tennis, boosting demand for rackets, balls, and tables. Professional tournaments and local leagues drive sales of premium equipment. Online and specialty stores dominate distribution, ensuring widespread product availability. Consumer preference for high-quality and ITTF-certified equipment strengthens market revenue. Germany continues to attract investments from leading European and global manufacturers.
United Kingdom
The United Kingdom accounts for 18% of the market in 2024. Its market expansion is supported by growing recreational participation and increasing integration of table tennis in educational institutions. Specialty stores and online platforms provide easy access to diverse product ranges. Recreational players dominate demand, but professional players contribute to premium segment sales. Government initiatives and local associations encourage youth involvement. Rising awareness about fitness and indoor sports supports steady revenue growth. The UK market shows potential for further expansion through club and school partnerships.
France
France represents 16% of the Europe Table Tennis (Ping-Pong) Market in 2024. It features active professional and recreational segments, with strong club networks in urban areas. Educational institutions contribute significantly to equipment demand. Consumers prefer mid-range to premium products for training and competition. E-commerce channels support accessibility and variety. Manufacturers leverage partnerships with local clubs and associations to increase visibility. France demonstrates steady growth due to rising participation and professional events across the country.
Italy
Italy holds 12% of the market in 2024. Recreational players dominate, while professional participation supports high-end equipment sales. Schools and sports academies promote table tennis through competitions and programs. Online stores provide convenient access to products, complementing specialty retail. Regional clubs increase adoption and brand awareness. Consumer interest in health and indoor sports drives consistent demand. Italy remains an important market for European and global manufacturers targeting both recreational and professional segments.
Spain
Spain contributes 10% of the market in 2024. It experiences growth from recreational and youth segments, supported by schools and local clubs. Demand for tables and rackets increases due to competitions and community programs. E-commerce and sports stores expand distribution reach. Premium and mid-range products attract professional and amateur players. Consumer preference for indoor fitness activities reinforces market expansion. Spain presents opportunities for targeted promotional campaigns and product customization.
Russia
Russia captures 14% of the Europe Table Tennis (Ping-Pong) Market in 2024. It benefits from strong recreational engagement and growing interest in competitive table tennis. Schools and clubs drive demand for beginner and intermediate equipment. Online stores support accessibility across urban and remote areas. Professional events increase demand for high-quality products. Rising disposable income enhances purchases in the premium segment. Russia remains a key market for European and global equipment manufacturers.
Rest of Europe
The Rest of Europe accounts for 8% of the market in 2024. It includes smaller markets with emerging recreational and professional segments. Participation in schools and clubs drives equipment demand. Online sales and specialty stores ensure availability. Consumers increasingly prefer quality products over price in developed areas. Market growth remains steady due to rising awareness and gradual adoption. Opportunities exist in underdeveloped regions for education-based promotions and retail expansion.
Market Segmentations:
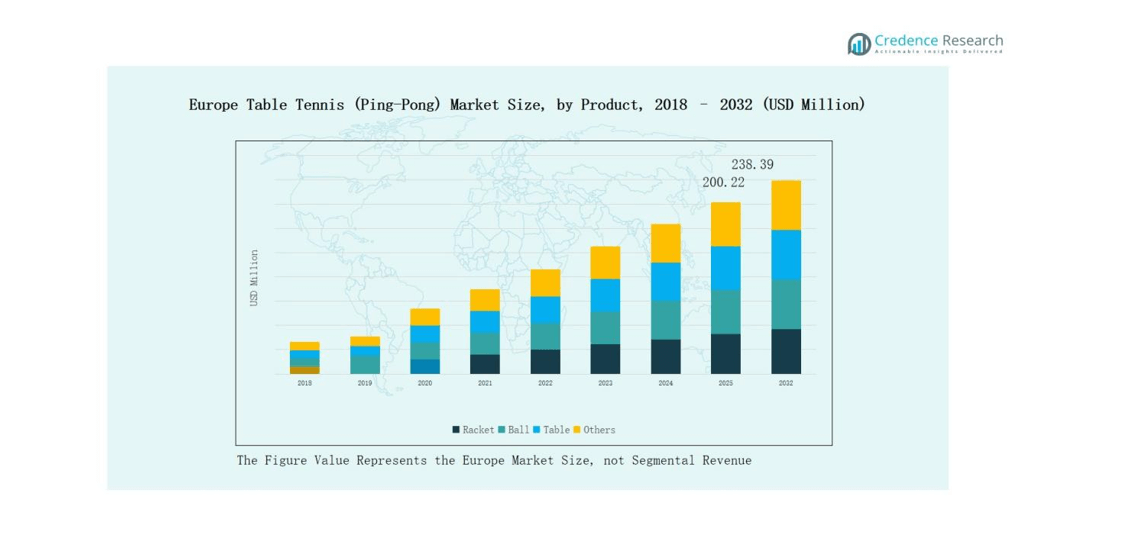
By Product
- Racket
- Ball
- Table
- Others
By End User
- Professional Players
- Recreational Players
- Educational Institutions
- Others
By Distribution Channel
- Online Stores
- Specialty Sports Stores
- Supermarkets/Hypermarkets
- Others
By Country (Europe)
- Germany
- UK
- France
- Italy
- Spain
- Russia
- Rest of Europe
Competitive Landscape
The Europe Table Tennis (Ping-Pong) Market features a highly competitive landscape with several established and emerging players driving innovation and market growth. Leading companies such as JOOLA, Butterfly, Nittaku, Double Happiness Co. Ltd., STIGA, DONIC, Sponeta GmbH, C&C, TELAMON, and KETTLER maintain strong market positions through diversified product portfolios, including rackets, balls, tables, and accessories. These players leverage technological advancements, high-quality materials, and ITTF certification to meet professional and recreational demands. Strategic initiatives such as mergers, partnerships, sponsorship of tournaments, and expansion of e-commerce and retail distribution strengthen market presence. Companies focus on customer engagement through training programs, promotional events, and collaborations with clubs and educational institutions. Product differentiation through premium offerings, affordable options, and customized solutions enhances competitiveness. The market’s fragmented nature allows emerging local manufacturers to capture niche segments. Continuous innovation, brand recognition, and extensive distribution networks remain crucial for sustaining leadership and expanding market share across Europe.
Key Players
- JOOLA
- Butterfly
- Sponeta GmbH
- Nittaku
- Double Happiness Co. Ltd.
- DONIC
- STIGA
- C&C
- TELAMON
- KETTLER
- Others
Recent Developments
- In 2025, JOOLA Table Tennis GmbH partnered with Pingpod, becoming its exclusive supplier for table tennis equipment and performance apparel.
- In May 2025, the International Table Tennis Federation (ITTF) launched the Sustainability Pledge during the World Championships in Qatar, aimed at promoting responsible and eco-friendly equipment practices.
- In March 2025, the European Table Tennis Union (ETTU) partnered with JOOLA. JOOLA will be the title sponsor of the ETTU Europe Youth Series for 2025 and 2026. The deal includes JOOLA sponsoring Development Camps and supplying equipment like balls to support young talent across Europe.
- In May 2025, Liebherr became an Official Event Partner for WTT Champions events in Europe. The company backed the Montpellier 2025 stop and returned as Official Event Partner for WTT Champions Frankfurt, marking expanded presence in Europe.
Report Coverage
The research report offers an in-depth analysis based on Product, End User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising interest in recreational table tennis will expand consumer base across Europe.
- Professional tournaments and league activities will boost demand for premium equipment.
- E-commerce growth will increase accessibility and sales of table tennis products.
- Educational institutions will integrate table tennis programs, driving consistent demand.
- Technological advancements in racket and ball materials will enhance product performance.
- Manufacturers will focus on eco-friendly and sustainable materials to meet regulatory standards.
- Strategic partnerships and sponsorships will strengthen brand presence and market penetration.
- Emerging local players will target niche segments and regional markets.
- Multi-channel distribution strategies will improve market reach and customer engagement.
- Innovation in compact and home-use tables will attract casual players and urban consumers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Table Tennis (Ping-Pong) Market, and what is its projected size in 2032
At what Compound Annual Growth Rate is the Europe Table Tennis (Ping-Pong) Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Europe Table Tennis (Ping-Pong) Market?
Who are the leading companies in the Europe Table Tennis (Ping-Pong) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Table Tennis (Ping-Pong) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Table Tennis (Ping-Pong) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 196.13 million → 2032: USD 238.39 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Table Tennis (Ping-Pong) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Table Tennis (Ping-Pong) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Table Tennis (Ping-Pong) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Table Tennis (Ping-Pong) Market Drivers
- 3.3 Europe Table Tennis (Ping-Pong) Market Restraints & Challenges
- 3.4 Europe Table Tennis (Ping-Pong) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Table Tennis (Ping-Pong) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Table Tennis (Ping-Pong) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Table Tennis (Ping-Pong) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Table Tennis (Ping-Pong) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Table Tennis (Ping-Pong) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Table Tennis (Ping-Pong) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Table Tennis (Ping-Pong) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Table Tennis (Ping-Pong) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Table Tennis (Ping-Pong) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Table Tennis (Ping-Pong) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Table Tennis (Ping-Pong) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Table Tennis (Ping-Pong) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Table Tennis (Ping-Pong) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Table Tennis (Ping-Pong) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Table Tennis (Ping-Pong) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Table Tennis (Ping-Pong) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Table Tennis (Ping-Pong) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Table Tennis (Ping-Pong) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Table Tennis (Ping-Pong) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
