
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Fertigation Control System Market Size 2024 | USD 1214.5 Million |
| Fertigation Control System Market, CAGR | 15% |
| Fertigation Control System Market Size 2032 | USD 3715.18 Million |
Market Overview:
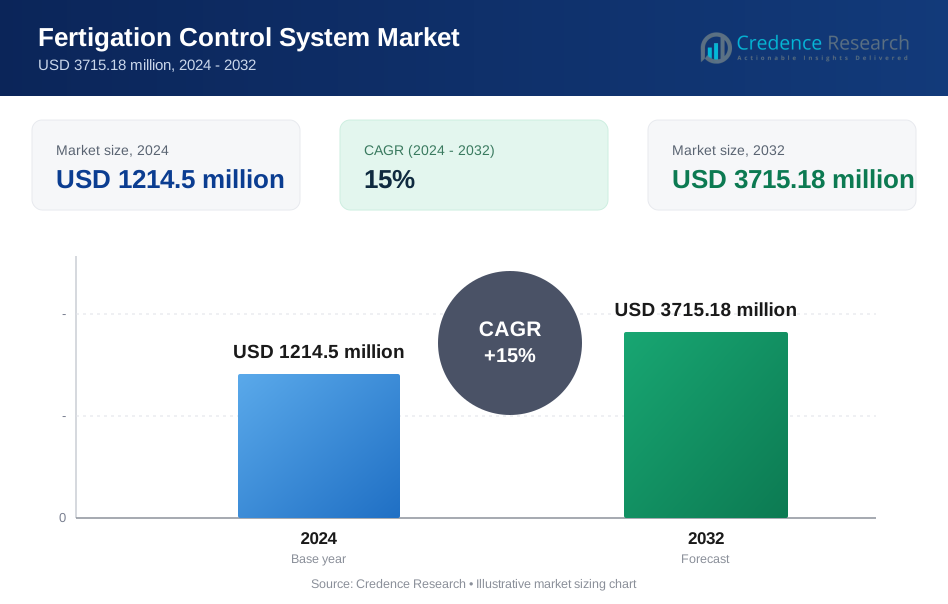
The Fertigation Control System Market is projected to grow from USD 1214.5 million in 2024 to USD 3715.18 million by 2032, at a CAGR of 15% from 2024 to 2032.
Key drivers of the fertigation control system market include the increasing global population, which necessitates higher agricultural productivity, and the need for precision farming techniques that ensure optimal use of water and nutrients. Fertigation systems, which combine fertilization and irrigation, offer enhanced crop yields and resource efficiency, reducing the environmental impact of agriculture. The rise of smart farming and automation technologies, alongside growing awareness of the benefits of integrated nutrient and irrigation management, further boosts market growth. Additionally, government initiatives promoting sustainable farming practices and the rise in greenhouse farming globally are contributing to the widespread adoption of fertigation control systems. This growing demand is expected to drive innovation in fertigation technologies, further supporting market expansion.
From a regional perspective, North America and Europe dominate the market due to the widespread adoption of advanced agricultural technologies and a strong focus on sustainability in farming practices. These regions benefit from highly developed agricultural infrastructure and are increasingly integrating fertigation systems into their operations. The Asia Pacific region is expected to witness significant growth due to the rising demand for food production driven by an expanding population and limited arable land. Countries like China and India are rapidly adopting modern irrigation and fertigation practices to boost agricultural efficiency. The Middle East and Africa also present promising growth opportunities, as regions with water scarcity increasingly look to fertigation systems to optimize water use and enhance agricultural efficiency. The demand for innovative water-saving techniques in these regions is propelling the adoption of fertigation systems. These regional dynamics are critical in shaping the future of the fertigation control system market.
Market Insights:
- The fertigation control system market is projected to grow from USD 1214.5 million in 2024 to USD 3715.18 million by 2032, driven by increasing global food demand.
- Precision farming and resource efficiency are significant growth drivers, as fertigation systems optimize water and nutrient delivery to crops, enhancing productivity.
- Technological advancements, including IoT and automation, are accelerating the adoption of fertigation control systems, enabling real-time monitoring and improved efficiency.
- Government policies and sustainability initiatives are encouraging the adoption of fertigation systems, particularly in regions with water scarcity.
- North America and Europe are leading the market, with advanced agricultural technologies and a strong focus on sustainability.
- The Asia Pacific region is experiencing rapid growth due to rising food production demands and limited arable land, with countries like China and India adopting modern fertigation practices.
- High initial costs, technical knowledge gaps, and maintenance complexities remain significant challenges in the widespread adoption of fertigation control systems.
Market Drivers:
Increasing Global Population and Food Demand:
The growing global population is one of the key drivers of the fertigation control system market. For instance, as populations continue to rise, particularly in emerging economies like India and Brazil, there is an urgent need to increase agricultural productivity to meet food demand. Fertigation systems provide an effective solution by optimizing water and nutrient delivery to crops, enhancing crop yields and ensuring the efficient use of resources. This enables farmers to meet the food requirements of a growing population while maintaining sustainable agricultural practices.
Precision Farming and Resource Efficiency:
The rise of precision farming techniques has significantly boosted the demand for fertigation control systems. For instance, fertigation control systems from Valmont Industries and Toro Company allow for precise irrigation and nutrient delivery, reducing water wastage by 30% and minimizing the use of fertilizers. These systems allow for precise irrigation and nutrient delivery, reducing water wastage and minimizing the use of fertilizers. This results in more efficient farming operations and increased crop productivity. As resource conservation becomes increasingly important, especially in regions facing water scarcity, fertigation systems play a vital role in maximizing agricultural output while minimizing environmental impact.
Technological Advancements and Smart Farming:
Technological advancements in agricultural equipment and smart farming solutions are accelerating the adoption of fertigation control systems. For instance, automation and IoT-enabled fertigation systems from companies like Netafim and Jain Irrigation offer real-time monitoring, control, and data-driven insights, enabling farmers to optimize fertilizer application and irrigation schedules. These innovations increase the precision and efficiency of fertigation systems, making them an essential component of modern farming practices.
Government Initiatives and Sustainability Focus:
Government policies supporting sustainable farming practices are driving the adoption of fertigation control systems. For instance, many governments, such as those in the European Union and Australia, are offering incentives and subsidies for adopting water-saving and environmentally friendly agricultural technologies. Many governments are offering incentives and subsidies for adopting water-saving and environmentally friendly agricultural technologies. This is further supported by a growing global focus on sustainability, with greenhouse farming and organic agriculture gaining traction. Fertigation control systems help meet sustainability goals by reducing water usage and ensuring optimal nutrient application, making them an essential part of future agricultural practices.
Market Trends:
Integration of IoT and Automation:
ne of the key trends in the fertigation control system market is the growing integration of Internet of Things (IoT) technology and automation. For instance, farmers are increasingly adopting smart fertigation systems from companies like Netafim and Jain Irrigation that enable remote monitoring and real-time control of irrigation and fertilization processes. IoT-enabled systems provide data-driven insights that allow for more accurate scheduling and adjustment, ensuring optimal resource use. Automation not only increases operational efficiency but also reduces human error, making fertigation systems more reliable and effective in precision farming.
Sustainable Agricultural Practices:
As sustainability becomes a focal point in agriculture, fertigation control systems are gaining popularity for their ability to reduce water and fertilizer usage. For instance, these systems from companies like Valmont Industries and Hunter Industries help address environmental concerns by ensuring that nutrients are delivered precisely to plants, minimizing waste and runoff. In regions where water scarcity is a critical issue, efficient fertigation systems are being increasingly seen as essential tools for conserving water resources while maintaining high agricultural productivity.
Greenhouse and Indoor Farming Expansion:
The rise in greenhouse and indoor farming is also contributing to the growth of the fertigation control system market. For instance, these farming environments require highly controlled conditions, making fertigation systems from companies like Netafim and Lindsay Corporation ideal for providing precise nutrient and water delivery. With the increased focus on urban farming and local food production, greenhouse operations are expanding globally, which is driving the demand for advanced fertigation control systems that can optimize these environments.
Adoption in Developing Markets:
While fertigation control systems have been widely adopted in developed markets, there is a growing trend of their adoption in developing economies. For instance, with the increasing pressure to boost food production and address resource limitations, countries in Asia, Africa, and Latin America are increasingly investing in fertigation technologies from companies like Jain Irrigation and Netafim. With the increasing pressure to boost food production and address resource limitations, countries in Asia, Africa, and Latin America are increasingly investing in fertigation technologies. These systems offer a practical solution to enhance crop yield while conserving vital resources.
Market Challenges Analysis:
High Initial Investment Costs:
One of the primary challenges facing the fertigation control system market is the high initial cost of installation. Advanced fertigation systems, especially those incorporating IoT and automation, require significant capital investment. This can be a barrier for small-scale farmers or those in developing economies, where budgets are limited. Although these systems offer long-term savings through improved efficiency, the upfront costs remain a key hurdle for broader adoption, especially in price-sensitive markets.
Lack of Technical Knowledge and Skilled Workforce:
Another challenge is the lack of technical knowledge and skilled workforce. The adoption of fertigation control systems often requires specialized knowledge of both agricultural practices and technology. Many farmers, particularly in rural or less developed areas, lack the technical expertise needed to operate and maintain these advanced systems. Training and developing a skilled workforce capable of handling complex fertigation systems is essential for ensuring successful implementation. Without adequate support and education, the effectiveness of these systems can be compromised, limiting their potential.
Maintenance and Operational Complexity:
Maintenance and operational complexity also pose significant challenges. Fertigation control systems, particularly those with sophisticated technology, can be complex to maintain and operate. Frequent maintenance is required to ensure the system operates efficiently, especially when dealing with issues such as clogging in irrigation lines or nutrient imbalances. Farmers may struggle with system failures or breakdowns, which can disrupt crop production. This operational complexity can deter potential users, particularly those who are not familiar with advanced agricultural technologies.
Regulatory and Policy Constraints:
Finally, regulatory and policy constraints can hinder market growth. In some regions, stringent regulations surrounding water use and fertilizer application can limit the flexibility and scalability of fertigation systems. These regulations may vary from country to country and can create uncertainty for businesses seeking to invest in or expand the use of fertigation systems. Navigating these regulatory hurdles can slow market growth and impact system adoption, especially in regions with rapidly changing environmental policies.
Market Opportunities:
The growing demand for sustainable agriculture presents significant opportunities for the fertigation control system market. As global concerns over water scarcity and environmental sustainability rise, fertigation systems offer an effective solution to optimize resource use, ensuring efficient water and fertilizer application. This trend is particularly prevalent in regions facing water shortages, such as the Middle East, parts of Africa, and Southeast Asia. Governments and organizations are increasingly encouraging the adoption of water-saving technologies, creating a favorable environment for the growth of fertigation systems. Additionally, the rise in greenhouse farming and controlled-environment agriculture provides a substantial opportunity for advanced fertigation control systems, which are essential for maintaining optimal growing conditions in such environments.
Another key opportunity lies in the adoption of precision farming techniques across both developed and emerging markets. As farmers continue to seek ways to improve crop yields and reduce costs, fertigation systems that integrate with data analytics and IoT technologies offer the potential to revolutionize agricultural practices. The growing popularity of smart farming and automation is further driving the demand for efficient fertigation systems that provide real-time monitoring and control. Additionally, the expansion of the agriculture sector in developing countries, coupled with increased investments in modern farming technologies, offers promising growth prospects. Fertigation systems are becoming an integral part of modern agriculture, creating long-term opportunities for businesses to capitalize on these innovations.
Market Segmentation Analysis:
By Channel In terms of channel, the market is primarily divided into direct sales and distribution networks. Direct sales are typically favored by large-scale commercial farmers and agricultural corporations, who often require customized fertigation solutions. Distribution networks, on the other hand, cater to smaller farmers and regional distributors, offering a wider reach and facilitating the availability of fertigation systems in both urban and rural areas.
By Technology
The market is also segmented by technology, including traditional fertigation systems, automated fertigation systems, and IoT-based fertigation systems. Automated fertigation systems are gaining popularity due to their precision and ease of use, reducing the need for manual intervention. IoT-based systems are seeing rapid adoption, driven by the growing demand for real-time monitoring and control, as they enable farmers to optimize water and nutrient delivery remotely, improving efficiency and crop yield.
By End-Use
In terms of end-use, the market is classified into agriculture, horticulture, and greenhouse farming. Agriculture remains the largest segment, with a significant portion of fertigation systems being used for field crops. Horticulture, particularly in controlled environments like greenhouses, is growing in importance, as it demands high precision for nutrient and water management. Greenhouse farming is also expected to witness substantial growth, driven by the increasing popularity of urban farming and sustainable farming practices.
Segmentations:
By Channel:
- Dual
- Multi
- Single
By Technology:
- Manual
- Automated
By End-use:
- Open Field
- Research Body
- Greenhouse
- Others
By Region:
- North America
- Europe
- Asia Pacific (APAC)
- Latin America
- Middle East & Africa (MEA)
Regional Analysis:
North America
North America holds the largest market share in the fertigation control system market, accounting for 35% of the global market. The United States is the primary contributor to this dominance, driven by advanced agricultural technologies and a strong focus on sustainable farming practices. Precision farming and the adoption of IoT-based fertigation systems are widespread across the region, especially in large-scale agricultural operations. With the growing awareness of resource conservation and high demand for efficient water and nutrient management, North America is expected to maintain its leading position. The government's support for sustainable farming through subsidies and grants further strengthens the adoption of fertigation systems.
Europe
Europe holds a market share of 25% in the fertigation control system market, with countries like Germany, the UK, and the Netherlands leading the adoption of modern agricultural technologies. The region has a strong focus on sustainability, with stringent regulations promoting the reduction of water usage and fertilizer runoff. The rise of greenhouse farming and controlled-environment agriculture is a key factor contributing to the growth of fertigation control systems in Europe. The integration of IoT and automation technologies within European agricultural practices is further enhancing the market demand for advanced fertigation solutions.
Asia Pacific
Asia Pacific holds a market share of 20% in the global fertigation control system market. This region is witnessing significant growth due to the increasing population, rising demand for food production, and limited arable land. Countries such as China and India are investing heavily in modern irrigation systems to enhance agricultural productivity. The adoption of fertigation control systems is gaining momentum as a means to conserve water and improve crop yields, particularly in water-scarce regions. The growing focus on sustainable farming, along with government incentives for water-saving technologies, is fueling market expansion in this region.
Middle East and Africa
The Middle East and Africa region accounts for 15% of the market share in the fertigation control system market. Water scarcity and arid climates make this region a key adopter of fertigation systems, particularly in countries such as Saudi Arabia, the UAE, and Israel. Fertigation control systems are essential in optimizing water usage and improving crop yields in these regions. The increasing adoption of greenhouse farming and the need for efficient water management in agriculture are major drivers of market growth in the Middle East and Africa.
Latin America
Latin America holds a market share of 5% in the fertigation control system market, with Brazil being the key player in the region. The demand for fertigation systems in Latin America is driven by the need to increase agricultural productivity and optimize water usage in countries with large agricultural sectors. Fertigation control systems are increasingly being adopted in the region’s growing horticulture and greenhouse farming industries, as these sectors require precise irrigation and nutrient management for optimal crop production.
Key Player Analysis:
- Netafim Ltd.
- Jain Irrigation Systems Ltd.
- The Toro Company
- Rivulis Irrigation
- Hunter Industries
- Lindsay Corporation
- Valmont Industries, Inc.
- Priva
- Irritec
- Gaviota
Competitive Analysis:
The fertigation control system market is highly competitive, with key players such as Netafim Ltd., Jain Irrigation Systems Ltd., and The Toro Company leading the industry. These companies dominate due to their technological advancements, strong distribution networks, and extensive experience in agricultural solutions. Smaller players, such as Rivulis Irrigation and Hunter Industries, focus on niche markets and regional expansion, offering innovative, cost-effective systems for various farming needs. Competition in the market is further intensified by the growing demand for IoT-enabled and automated fertigation systems, which provide real-time monitoring and data-driven insights. Companies are increasingly focusing on partnerships, mergers, and acquisitions to enhance their market position. For instance, Jain Irrigation Systems recently merged with International Irrigation Solutions to strengthen their market presence. Additionally, the market is witnessing significant investments in research and development to introduce more efficient and sustainable fertigation technologies, aimed at catering to the rising demand for resource-efficient farming solutions.
Recent Developments:
- In September 2024, Orbia’s Netafim unveiled GrowSphere, an operating system automating precision irrigation and fertigation. This system integrates hydraulic, operational, and agronomic capabilities into one intuitive platform, significantly reducing the need for manual in-field operations.
- In October 2023, Netafim announced the launch of Toofan, an innovative irrigation technology designed to revolutionize sustainable farming. Toofan offers 40% stronger drip lines with advanced anti-clogging technology and is 20% more affordable than existing options, ensuring efficient and cost-effective irrigation for farmers of all scales.
- In October 2024, Centro Tecnológico, a participant in the irrigation automation technology industry, launched smart sensor technology, which assists in optimizing the coverage of irrigation ponds.
- In July 2024, Mobitech Wireless Solution Private Limited launched Dcon Ag AIR, a newly developed controller for irrigation systems and motors, expected to assist farmers in remote monitoring irrigation systems and provide real-time soil moisture data and other insights.
Market Concentration & Characteristics:
The fertigation control system market is moderately concentrated, with a few major players holding significant market share. Key players such as Netafim Ltd., Jain Irrigation Systems Ltd., and The Toro Company dominate the market, leveraging their extensive product portfolios, technological advancements, and strong distribution networks. However, the market also features a variety of regional and smaller players who cater to specific agricultural needs, creating a competitive landscape with moderate fragmentation. The market is characterized by continuous innovation, with a strong focus on integrating IoT, automation, and data analytics into fertigation systems. Companies are increasingly emphasizing sustainability and resource efficiency to meet the growing demand for precision farming solutions. Additionally, strategic partnerships, acquisitions, and collaborations are common, as companies seek to enhance their technological capabilities and expand their global presence. This dynamic environment is expected to drive future growth and competition.
Report Coverage:
The research report offers an in-depth analysis based on Channel, Technology, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for fertigation control systems is expected to rise as farmers adopt more sustainable and resource-efficient agricultural practices.
- Increasing global concerns over water scarcity will drive the adoption of fertigation systems that optimize water usage in agriculture.
- The integration of IoT and automation in fertigation control systems will become more prevalent, enhancing precision and real-time monitoring capabilities.
- Government incentives and policies promoting sustainable farming techniques will accelerate the adoption of fertigation control systems worldwide.
- The rise of greenhouse farming and controlled-environment agriculture will contribute to the growth of the fertigation control system market.
- Precision farming practices will continue to gain traction, with fertigation systems playing a crucial role in improving crop yields and reducing input costs.
- Technological advancements, including AI and data analytics, will further enhance the efficiency and functionality of fertigation systems.
- Emerging markets, particularly in Asia and Africa, will witness significant growth as these regions prioritize agricultural productivity and resource management.
- Increased focus on organic farming and sustainable practices will drive demand for eco-friendly fertigation solutions.
- Strategic partnerships and acquisitions among key players will help strengthen market position and foster innovation in fertigation technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the fertigation control system market?
What are the key drivers of market growth?
Which regions are leading the market?
Why is fertigation control important for agriculture?
What impact does government policy have on the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fertigation Control System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fertigation Control System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1214.5 million → 2032: USD 3715.18 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fertigation Control System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fertigation Control System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fertigation Control System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fertigation Control System Market Drivers
- 3.3 Fertigation Control System Market Restraints & Challenges
- 3.4 Fertigation Control System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fertigation Control System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fertigation Control System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fertigation Control System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fertigation Control System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fertigation Control System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fertigation Control System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fertigation Control System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fertigation Control System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fertigation Control System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fertigation Control System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fertigation Control System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fertigation Control System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fertigation Control System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fertigation Control System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fertigation Control System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fertigation Control System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fertigation Control System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fertigation Control System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fertigation Control System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
