
Food Intolerance Test Market Overview:
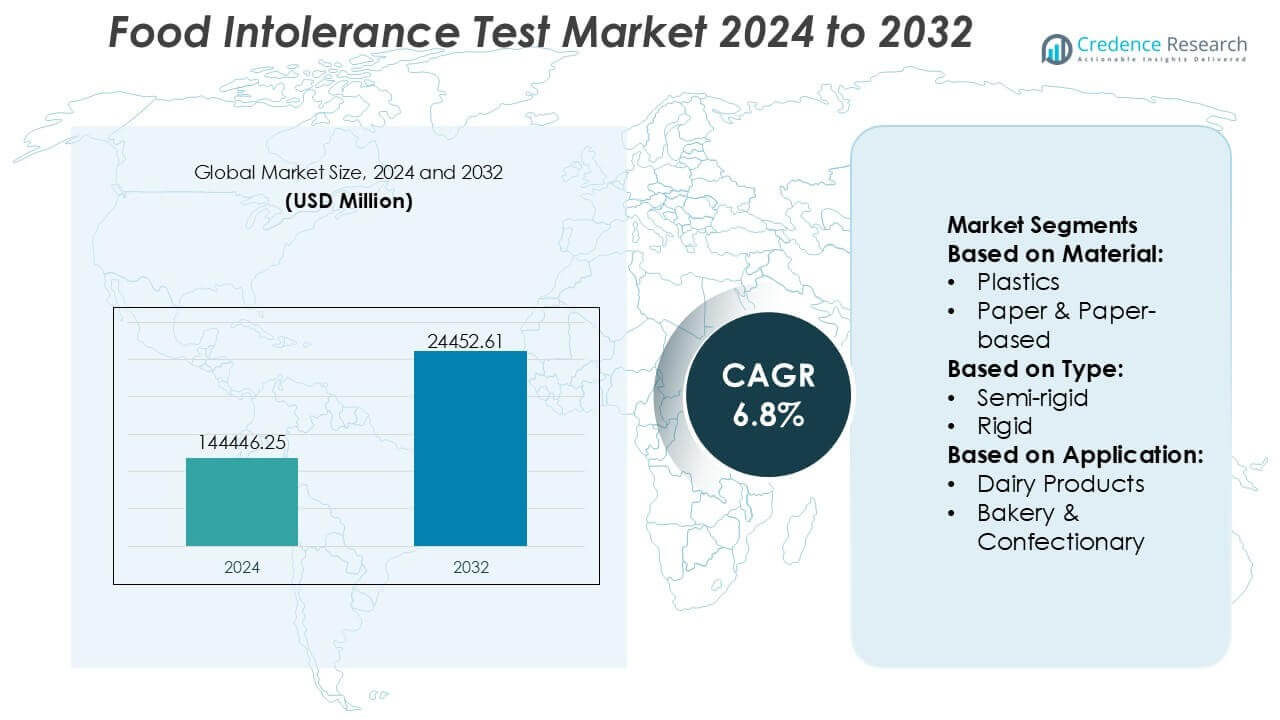
Food Intolerance Test Market size was valued USD 14444.25 million in 2024 and is anticipated to reach USD 24445.61 million by 2032, at a CAGR of 6.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Intolerance Test Market Size 2024 | USD 14444.25 million |
| Food Intolerance Test Market, CAGR | 6.8% |
| Food Intolerance Test Market Size 2032 | USD 24445.61 million |
Food Intolerance Test Market Insights
- Rising prevalence of digestive disorders, food sensitivities, and lifestyle-related gut health issues is accelerating demand, with laboratory-based testing remaining the dominant segment at nearly 62% share due to higher clinical reliability.
- Technological trends focus on improved immunoassay sensitivity, expanded antigen panels, and digital result platforms, while direct-to-consumer testing shows faster adoption, capturing around 28% of total testing volume.
- Competitive dynamics reflect moderate consolidation, with players differentiating through assay accuracy, regulatory compliance, and omnichannel distribution spanning hospitals, diagnostics labs, and online platforms.
- Regionally, North America leads with an exact 38% market share, followed by Europe at 30%, supported by strong diagnostic infrastructure, high awareness, and routine use of intolerance testing in dietary management.
Food Intolerance Test Market Segmentation Analysis:
By Material
Within the Food Intolerance Test Market, plastics represent the dominant material segment, accounting for approximately 46% market share. This leadership is driven by the widespread use of plastic-based consumables such as test cassettes, sample wells, and reagent containers, which offer cost efficiency, chemical resistance, and compatibility with automated immunoassay platforms. Plastic materials support high-volume manufacturing and single-use testing requirements, reducing contamination risk. Paper & paper-based materials follow, supported by lateral flow strips and filter papers, while glass and metal are primarily limited to specialized laboratory storage and instrumentation components.
By Type
The market by type is led by rigid formats, holding nearly 44% market share, due to their extensive use in laboratory-based and clinic-based food intolerance testing kits. Rigid housings ensure structural stability, precise reagent alignment, and consistent optical or immunological readouts, which are critical for ELISA and microarray-based assays. Semi-rigid formats maintain moderate adoption in hybrid testing systems, while flexible formats are gaining traction in rapid and at-home test kits, driven by portability, reduced material usage, and growing consumer preference for self-testing solutions with simplified handling.
By Application
By application, dairy products testing dominates the Food Intolerance Test Market with an estimated 38% market share, reflecting the high global prevalence of lactose and milk protein intolerance. Demand is driven by increased screening for lactose, casein, and whey sensitivities across clinical diagnostics and consumer health segments. Bakery & confectionery applications follow, supported by gluten and yeast intolerance testing. Meat, poultry, and seafood testing shows steady growth due to rising awareness of histamine and protein sensitivities, while fruits, vegetables, and sauces contribute niche but expanding demand.
Key Growth Drivers
Rising Prevalence of Food Sensitivities and Gastrointestinal Disorders
The Food Intolerance Test Market benefits from the growing global incidence of food-related sensitivities, including lactose intolerance, gluten sensitivity, and non-IgE–mediated reactions. Increasing cases of irritable bowel syndrome, bloating, migraines, and chronic fatigue have encouraged patients and clinicians to investigate dietary triggers more systematically. Greater awareness that food intolerance differs from food allergy has expanded testing demand beyond acute reactions to include chronic and lifestyle-related symptoms. This shift supports wider adoption of elimination diets supported by diagnostic testing, strengthening market growth across clinical and consumer segments.
Growing Consumer Awareness and Preventive Healthcare Orientation
Rising health literacy and preventive healthcare adoption significantly drive demand for food intolerance testing. Consumers increasingly seek personalized nutrition solutions to improve digestive health, energy levels, and overall well-being. Media coverage, digital health platforms, and nutrition influencers have amplified awareness of food intolerance diagnostics as part of proactive health management. This consumer-driven demand extends beyond hospitals to wellness centers and home-testing formats, enabling earlier identification of trigger foods. The emphasis on self-managed health and dietary optimization continues to expand the addressable market.
Advancements in Diagnostic Technologies and Test Accuracy
Technological progress in immunoassays, biomarker detection, and laboratory automation has enhanced the reliability and scalability of food intolerance tests. Improvements in assay sensitivity, reproducibility, and turnaround time have increased clinician confidence and patient acceptance. Automation and standardized workflows reduce operational errors and support higher testing volumes in diagnostic laboratories. These advancements also enable multiplex testing, allowing simultaneous analysis of multiple food antigens, which improves clinical utility and cost efficiency, thereby accelerating adoption across both developed and emerging healthcare systems.
Key Trends & Opportunities
Expansion of Direct-to-Consumer and At-Home Testing Solutions
A major trend shaping the Food Intolerance Test Market is the expansion of direct-to-consumer testing models. At-home sample collection kits combined with centralized laboratory analysis improve accessibility and convenience for consumers. This approach reduces dependency on hospital visits and aligns with the broader shift toward decentralized diagnostics. Digital result delivery and dietary guidance further enhance user engagement. The growing acceptance of home-based testing creates strong opportunities for market penetration among health-conscious consumers and individuals managing chronic, non-acute symptoms.
Integration with Personalized Nutrition and Digital Health Platforms
Food intolerance testing increasingly integrates with personalized nutrition programs and digital health ecosystems. Test results are being linked with mobile applications, diet-planning tools, and virtual nutrition consultations to deliver actionable insights. This integration supports tailored dietary interventions rather than generic elimination strategies. The convergence of diagnostics, data analytics, and nutrition services enhances long-term user value and adherence. As personalized healthcare models gain traction, food intolerance testing becomes a foundational data input, creating sustained demand and differentiation opportunities.
Rising Adoption in Emerging Markets
Emerging economies present significant growth opportunities due to improving healthcare infrastructure, urbanization, and rising disposable incomes. Increased awareness of digestive health and western dietary patterns has elevated the incidence of food intolerance symptoms in these regions. Private diagnostic laboratories and wellness clinics are expanding rapidly, supporting broader test availability. As affordability improves and preventive healthcare gains importance, emerging markets are expected to contribute meaningfully to volume growth over the forecast period.
Key Challenges
Lack of Standardization and Clinical Consensus
A key challenge in the Food Intolerance Test Market is the lack of universal clinical consensus on testing methodologies and result interpretation. Variability in biomarkers, reference ranges, and testing protocols can lead to inconsistent outcomes across providers. This inconsistency raises skepticism among healthcare professionals and limits formal guideline adoption. In some cases, clinicians prefer symptom-based elimination diets over diagnostic tests, constraining clinical uptake. Addressing standardization and strengthening clinical validation remain critical to improving credibility and long-term market acceptance.
Reimbursement Limitations and Cost Sensitivity
Limited reimbursement coverage poses another significant challenge, particularly in cost-sensitive healthcare systems. Many food intolerance tests are classified as elective or wellness-oriented, resulting in out-of-pocket expenses for patients. This restricts access among lower-income populations and limits routine clinical use. Price sensitivity also affects adoption in emerging markets despite rising awareness. To overcome this barrier, manufacturers and service providers must demonstrate stronger clinical utility, cost-effectiveness, and long-term health benefits to support broader reimbursement inclusion.
Regional Analysis
North America
North America leads the Food Intolerance Test Market with an estimated 38% share, supported by high consumer awareness of food sensitivities, advanced diagnostic infrastructure, and strong adoption of preventive healthcare practices. The United States dominates regional demand due to widespread availability of laboratory-based and at-home testing kits, coupled with favorable reimbursement for diagnostic services. Rising prevalence of lactose intolerance, gluten sensitivity, and IBS further drives testing volumes. Strong presence of specialized diagnostic laboratories, continuous product innovation, and direct-to-consumer testing models reinforce market leadership across both clinical and non-clinical testing channels.
Europe
Europe accounts for approximately 30% of the Food Intolerance Test Market, driven by growing health consciousness, stringent food labeling regulations, and proactive dietary management trends. Countries such as Germany, the UK, France, and Italy show high uptake of food intolerance diagnostics, particularly among aging populations and individuals with chronic gastrointestinal conditions. Public healthcare systems support diagnostic screening, while private laboratories expand personalized nutrition and sensitivity testing services. Rising adoption of elimination diets, increasing awareness of celiac disease, and strong emphasis on preventive care continue to support steady regional market growth.
Asia-Pacific
Asia-Pacific holds around 22% of the global Food Intolerance Test Market and represents the fastest-growing region. Growth is driven by expanding middle-class populations, increasing urbanization, and rising awareness of digestive health issues. Countries such as China, Japan, India, and Australia are witnessing higher demand for allergy and intolerance diagnostics due to changing dietary habits and increased consumption of processed foods. Improving healthcare infrastructure, expanding private diagnostic networks, and growing penetration of at-home testing kits further support market expansion across emerging and developed economies in the region.
Latin America
Latin America captures roughly 6% of the Food Intolerance Test Market, supported by gradual improvements in healthcare access and rising awareness of food-related digestive disorders. Brazil and Mexico lead regional demand due to expanding private diagnostic laboratories and increasing prevalence of lactose intolerance. Growing urban populations and rising disposable incomes encourage adoption of preventive health testing, particularly among younger consumers. However, limited reimbursement coverage and lower awareness levels compared to developed regions moderately constrain growth, keeping the market at an emerging but steadily expanding stage.
Middle East & Africa
The Middle East & Africa region accounts for approximately 4% of the Food Intolerance Test Market, reflecting early-stage adoption. Growth is supported by rising healthcare investments, increasing incidence of lifestyle-related digestive conditions, and expanding private healthcare facilities in Gulf countries. Demand is primarily concentrated in urban centers, where awareness of personalized nutrition and diagnostic testing is higher. However, limited access to advanced diagnostics, lower awareness in rural areas, and affordability constraints restrict broader market penetration, resulting in a comparatively smaller regional share.
Food Intolerance Test Market Segmentations:
By Material:
- Plastics
- Paper & Paper-based
By Type:
- Semi-rigid
- Rigid
By Application:
- Dairy Products
- Bakery & Confectionary
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Key Player Analysis
Conagra Brands Inc. Doves Farm Foods Ltd Chobani LLC Danone SA Hain Celestial Group Inc. Amy's Kitchen Inc. Monde Nissin Arla Foods Amba Dr. Schär Ecotone General Mills Inc.Report Coverage
The research report offers an in-depth analysis based on Material, Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing adoption of personalized nutrition programs will increase routine use of food intolerance testing in preventive healthcare.
- Advancements in immunoassay and molecular diagnostic technologies will improve test accuracy and reproducibility.
- Expansion of direct-to-consumer testing models will enhance accessibility and consumer engagement.
- Integration of digital platforms and mobile health applications will streamline result interpretation and dietary guidance.
- Rising awareness of gut health and chronic digestive disorders will sustain long-term testing demand.
- Broader food antigen panels will support more comprehensive and customized intolerance assessments.
- Increased collaboration between diagnostic providers and nutrition professionals will strengthen clinical relevance.
- Regulatory standardization will improve test credibility and market transparency.
- Emerging economies will contribute incremental growth through improving diagnostic infrastructure.
- Emphasis on preventive healthcare will position food intolerance testing as a routine wellness tool.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Food Intolerance Test Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Intolerance Test Market projected to grow between 2024 and 2032?
Which Food Intolerance Test Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Intolerance Test Market?
Who are the leading companies in the Food Intolerance Test Market?
Which region commanded the largest share of the Food Intolerance Test Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 144,44.25 million → 2032: USD 244,45.61 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Intolerance Test Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Intolerance Test Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Intolerance Test Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Intolerance Test Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Intolerance Test Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Intolerance Test Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Intolerance Test Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Intolerance Test Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 144,44.25 million → 2032: USD 244,45.61 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Intolerance Test Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Intolerance Test Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Food Intolerance Test Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Food Intolerance Test Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

