
Market Overview:
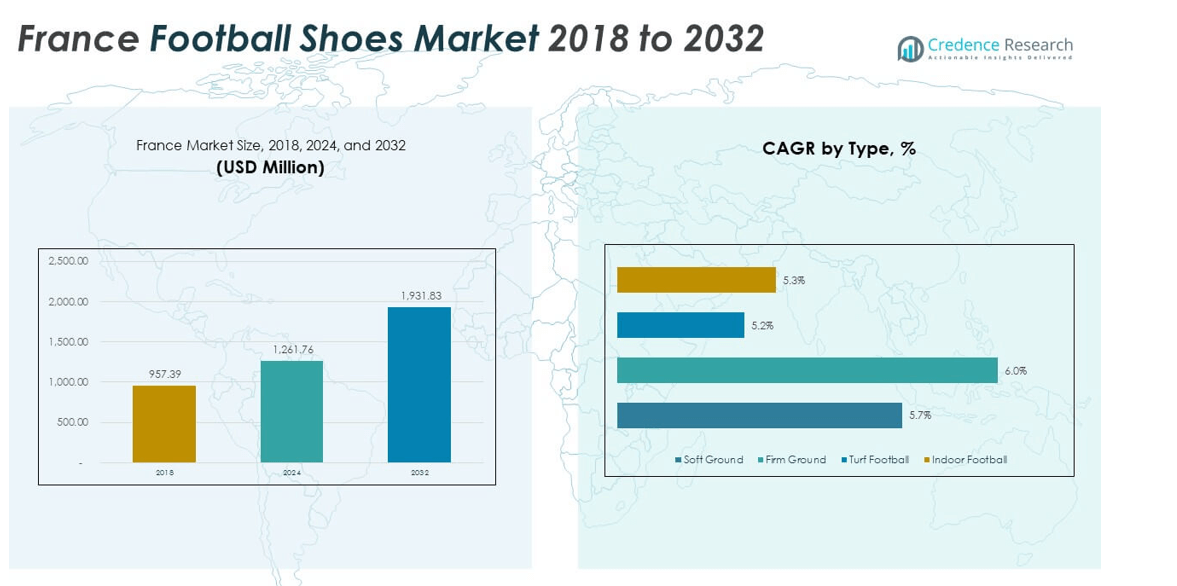
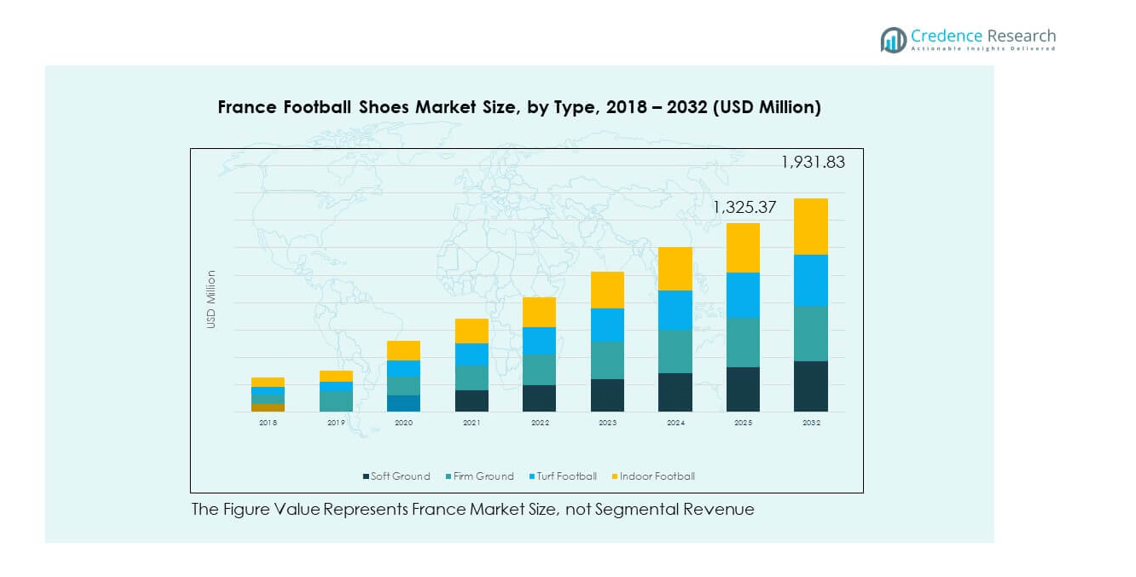
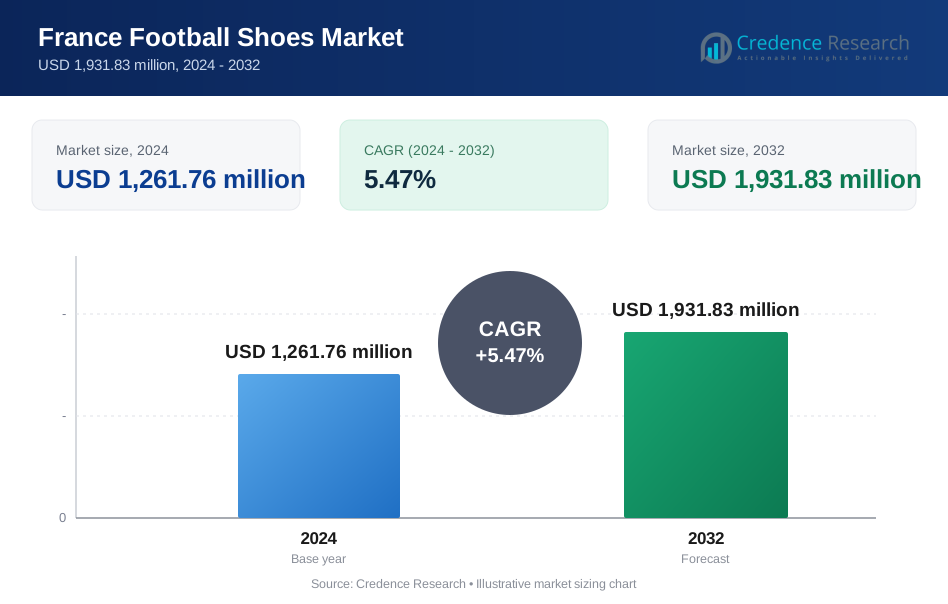
The France Football Shoes Market size was valued at USD 957.39 million in 2018 to USD 1,261.76 million in 2024 and is anticipated to reach USD 1,931.83 million by 2032, at a CAGR of 5.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Football Shoes Market Size 2024 | USD 1,261.76 million |
| France Football Shoes Market, CAGR | 5.47% |
| France Football Shoes Market Size 2032 | USD 1,931.83 million |
The market is driven by France’s strong football culture, increasing participation in organized leagues, and rising popularity of women’s football. Consumers seek performance-oriented shoes featuring lightweight materials, advanced soleplate construction, and durability for multiple playing surfaces. Professional endorsements, grassroots initiatives, and the influence of Ligue 1 clubs boost awareness and adoption. Sustainability also acts as a key driver, with brands integrating recycled and eco-friendly materials to match consumer preferences and regulatory expectations.
Regionally, Northern France leads due to its established clubs, strong grassroots programs, and proximity to neighboring European football hubs. Southern France shows dynamic growth supported by major clubs in Marseille, Nice, and Lyon and its favorable climate for extended outdoor play. Central France remains steady, driven by recreational participation and growing indoor and turf facility use. Emerging demand also stems from smaller towns and community programs, where football continues to expand access and inclusivity, creating balanced opportunities for brands across the country.
Market Insights
- The France Football Shoes Market was valued at USD 957.39 million in 2018, grew to USD 1,261.76 million in 2024, and is expected to reach USD 1,931.83 million by 2032, registering a CAGR of 5.47%.
- Northern France led with 38% share due to strong club presence and grassroots participation, Southern France followed with 35% driven by major clubs and favorable climate, while Central France held 27% supported by recreational football and indoor facilities.
- The fastest-growing subregion is Southern France with 35% share, supported by professional clubs, youth academies, and high outdoor football activity, making it a dynamic growth hub.
- Firm ground shoes represented the largest segment in 2024, capturing 42% of the market, driven by their adaptability across natural playing surfaces.
- Turf and indoor football shoes together held 33% share, supported by the popularity of futsal, urban football culture, and the expansion of artificial playing surfaces.
Market Drivers
Growing Football Participation Across All Age Groups
The France Football Shoes Market gains momentum from growing participation in both professional and amateur levels. The popularity of Ligue 1, local clubs, and school tournaments increases demand across different age groups. Parents and schools invest in durable and safe footwear for younger players. Professional clubs inspire adoption of premium models among teenagers. Women’s football also expands participation and broadens the consumer base. Football remains France’s most practiced sport, which sustains consistent market demand. Local retailers benefit from this surge through steady turnover of new models. Rising grassroots activities strengthen the position of global and domestic brands.
Technological Advancements Driving Performance-Oriented Footwear
Innovations in design and material technology drive purchase decisions among athletes. Lightweight uppers improve agility while engineered soleplates maximize traction on natural and synthetic turf. Enhanced cushioning systems reduce injury risk and support comfort during extended play. International brands invest in research to meet evolving performance expectations. The France Football Shoes Market benefits from these advances, creating a preference for premium and mid-range categories. Customizable fit options encourage consumer loyalty by improving user experience. Professional endorsements highlight the effectiveness of advanced shoes. Technology remains a clear driver of consumer trust and repeated purchases.
- For instance, Nike’s Air Zoom Mercurial, released in June 2022, features a 4-mm Air Zoom Strobel unit across the soleplate, designed to deliver enhanced responsiveness and propulsion as highlighted in Nike’s official product briefing.
Sustainability Influencing Product Development and Purchase Choices
Eco-friendly initiatives directly influence product development strategies in this market. Brands experiment with recycled polyester, plant-based materials, and reduced packaging. Younger consumers prioritize sustainability alongside performance features. The France Football Shoes Market adapts to these shifts by offering green product lines. Large companies set measurable goals to reduce carbon footprints. Retailers promote sustainability messaging to capture eco-conscious buyers. Government awareness programs support the movement toward responsible consumption. The combination of sustainability and high-performance footwear aligns with current market preferences.
- For instance, Adidas confirmed in its 2023 sustainability report that 96% of the polyester used across its global product range came from recycled sources, reinforcing its commitment to transition entirely to recycled polyester by 2025.
Brand Endorsements and Sports Marketing Strengthening Market Position
Endorsements from elite players create aspirational demand among consumers. Sponsorship deals between clubs and global footwear brands expand visibility. The France Football Shoes Market sees strong influence from international tournaments hosted or played in Europe. Marketing campaigns highlight exclusive collections tied to major events. Local fans replicate the styles of their favorite athletes. Digital platforms allow brands to target specific demographics effectively. Social media engagement enhances consumer interaction with product launches. Strong marketing strategies build trust and secure consistent revenue streams.
Market Trends
Rise of Customization and Personalization Options Among Consumers
The France Football Shoes Market experiences growth in customization demand. Consumers prefer personalized colors, soleplate choices, and fit adjustments. Digital platforms offer real-time design tools that enable unique product selection. Younger demographics view personalization as an expression of style and identity. Professional players often debut custom models, creating aspirational value. Retailers leverage online platforms to highlight customization services. It provides differentiation in a competitive marketplace. The trend strengthens consumer loyalty by linking individuality with performance footwear.
- For instance, Adidas’ Paris flagship store provides in-store customization services, enabling consumers to personalize football shoes with preferred colors, materials, and graphic details, showcasing the brand’s commitment to individual expression in France.
Expansion of Digital Sales Channels and Online Retail Platforms
E-commerce shapes consumer buying patterns across this market. Major retailers invest in mobile-friendly platforms to reach broader audiences. Brands use online launches to create exclusivity for limited editions. The France Football Shoes Market benefits from strong online distribution networks. Virtual try-on tools improve consumer confidence in fit and comfort. Discounts, easy returns, and home delivery encourage adoption of online shopping. Digital campaigns integrate with social media promotions for targeted engagement. Online retail continues to outpace traditional outlets in growth speed.
- For instance, Nike has emphasized its direct-to-consumer strategy in France through Nike.com and its mobile apps, where digital sales have become an important growth driver for its football footwear business.
Integration of Smart Features and Connected Footwear Technologies
Smart footwear gains recognition among performance-driven athletes. Embedded sensors measure running speed, stride length, and workload intensity. Data integration through apps supports performance tracking and injury prevention. The France Football Shoes Market leverages this innovation to attract tech-savvy consumers. Partnerships between footwear brands and digital platforms expand connected ecosystems. Elite players influence adoption by showcasing benefits of performance analytics. Pricing strategies focus on premium placement for smart models. The trend highlights the merging of sports performance and technology.
Influence of Streetwear and Lifestyle Integration in Football Footwear
Football shoes expand their reach into casual fashion and streetwear. Influencers and designers collaborate on limited lifestyle collections. The France Football Shoes Market benefits from growing interest in sport-inspired street fashion. Shoes originally designed for pitch use gain traction in urban settings. Global brands release hybrid models suitable for everyday wear. The blending of lifestyle and performance increases brand visibility. Retailers promote dual-use shoes for broader market appeal. The crossover trend fuels demand beyond traditional athletes.
Market Challenges Analysis
High Competition and Price Sensitivity Across Market Segments
The France Football Shoes Market faces intense competition between international and domestic brands. Consumers often compare prices before making purchases, creating strong pressure on margins. Premium shoes dominate among professionals, but price-sensitive buyers opt for entry-level models. It limits the ability of brands to expand revenue without constant innovation. Seasonal sales and discounting reduce profitability for retailers. Smaller brands struggle to maintain visibility against global giants. Strong competition requires heavy investment in marketing and promotions. This situation challenges long-term sustainability for several market players.
Counterfeit Products and Distribution Channel Constraints Affect Growth
Counterfeit football shoes continue to affect brand reputation and market trust. It leads to reduced revenues and lower consumer confidence in authentic models. Unregulated online platforms allow fakes to enter the market easily. Distribution challenges in rural areas also slow product reach. Retailers face inventory management issues with frequent product updates. Some consumers face limited access to the latest models due to uneven supply. The France Football Shoes Market struggles with these structural challenges. Effective regulations and improved distribution strategies remain essential to overcome these issues.
Market Opportunities
Growing Demand for Women’s Football and Grassroots Development Programs
The France Football Shoes Market presents opportunities through the rising popularity of women’s football. National initiatives promote inclusivity at both professional and youth levels. It creates new demand across product categories for women-specific designs. Grassroots programs expand participation in smaller towns and schools. Local retailers gain from this expansion by offering tailored collections. Global brands respond with gender-specific performance lines. The opportunity enhances diversity and broadens consumer outreach. Continued support of grassroots development ensures a stable growth pipeline.
Innovation in Lightweight Designs and Multi-Surface Footwear Performance
Advancements in materials create opportunities for lighter and more versatile shoes. Consumers value footwear that adapts to natural grass, turf, and indoor courts. The France Football Shoes Market leverages this demand to promote new designs. It drives innovation in soleplate flexibility and midsole cushioning. Multi-surface footwear supports recreational and semi-professional players. Performance improvements encourage repeat purchases. Retailers highlight these features to strengthen product differentiation. Innovation in lightweight, multi-surface designs positions brands for long-term advantage.
Market Segmentation Analysis
By type, the France Football Shoes Market is segmented into soft ground, firm ground, turf football, and indoor football. Firm ground shoes dominate due to their adaptability across natural pitches, while soft ground variants remain popular in professional leagues. Turf shoes gain traction in urban areas where artificial surfaces are common. Indoor football shoes record steady growth, supported by the popularity of futsal and year-round training facilities. Each type caters to distinct performance needs, creating clear demand across player categories.
- For instance, the Nike Phantom GX II Elite, launched in 2024, incorporates the Cyclone 360 soleplate for enhanced rotational traction on firm ground, and the Gripknit upper for improved touch and control, features directly verified by Nike’s official product releases and performance reviews.
By stud, the market divides into metal studs, rubber studs, and flat soles. Metal studs maintain relevance among elite players requiring traction on moist fields, while rubber studs remain the most widely adopted due to versatility. Flat soles are integral to indoor and futsal play, offering balance and grip on hard surfaces. It reflects consumer preference for surface-specific performance, driving consistent innovation in outsole design.
- For instance, the Mizuno Morelia Neo IV, released in 2024, weighs just 195g in a US size 9 and incorporates a graded nylon soleplate with a reengineered conical stud design, according to the company’s official technical specifications.
By sales channel, retail continues to hold a strong share through sports outlets and specialty stores, supported by trial-based purchases. E-commerce rapidly expands with wide availability of models, easy return policies, and exclusive launches. Direct-to-consumer channels gain momentum, enabling brands to strengthen customer relationships and promote customization services. It shows a clear shift toward online and direct engagement while retaining retail as an essential distribution pillar.
Segmentation
By Type
- Soft Ground
- Firm Ground
- Turf Football
- Indoor Football
By Stud
- Metal Studs
- Rubber Studs
- Flat Sole
By Sales Channel
- Retail Channels
- E-commerce
- Direct to Consumer
Regional Analysis
Northern France
Northern France accounts for 38% of the France Football Shoes Market, supported by high participation in organized football and the presence of established clubs such as Lille OSC and RC Lens. Strong retail penetration and proximity to European football hubs further strengthen demand in this subregion. Consumers prefer premium models endorsed by professional players, while grassroots programs maintain steady growth in mid-range segments. Cross-border access to Belgium and the UK supports distribution and cross-market opportunities. The subregion benefits from active youth academies, enhancing consistent demand for durable and performance-oriented shoes.
Central France
Central France holds a 27% share, influenced by grassroots participation and recreational football in smaller cities and towns. Demand remains concentrated in mid-tier categories, with families and youth players driving consistent turnover. It sees higher adoption of turf and indoor shoes due to the presence of multipurpose sports facilities. Retailers adapt by promoting affordable collections alongside branded premium products. Regional training academies create awareness of modern footwear technologies. Growing involvement of women and children in community football ensures steady product uptake in this subregion.
Southern France
Southern France contributes 35% of the France Football Shoes Market, supported by strong football culture in Marseille, Nice, and Lyon. Professional clubs boost visibility of international brands and drive adoption of premium lines. The warm climate supports extended outdoor play, strengthening demand for firm ground shoes. Regional tournaments and youth academies reinforce long-term interest in football footwear. E-commerce penetration is high in this subregion, increasing access to limited editions and global launches. It represents a dynamic growth hub, supported by high visibility of local and international competitions.
Key Player Analysis
- Nike Inc.
- Adidas AG
- Puma SE
- Umbro
- Mizuno
- Lotto Sport Italia
- New Balance
- DECATHLON Group
- Heckel
- Sokito
- Other Key Players
Competitive Analysis
The France Football Shoes Market is highly competitive, with global brands such as Nike, Adidas, and Puma leading through strong distribution, premium launches, and marketing campaigns tied to Ligue 1 and international tournaments. Local players, including Decathlon and Lotto Sport Italia, maintain market relevance by focusing on affordability and accessibility across retail channels. It shows clear segmentation, where premium products dominate among professionals and enthusiasts, while mid-tier and entry-level models serve mass participation. Companies differentiate through advanced technologies, sustainable designs, and customization features that align with evolving consumer preferences. Competition extends into digital platforms, where e-commerce and direct-to-consumer strategies provide brands with deeper consumer engagement and higher visibility. Strategic partnerships, athlete endorsements, and limited-edition releases secure market presence and intensify rivalry across product categories.
Recent Developments
- In September 2025, Adidas AG advanced its partnership efforts in the French market by collaborating with lifestyle brand Kith. On September 19, 2025, they jointly released the “Kith for adidas Football Fall 2025” collection, which blends sports and streetwear fashion for French consumers seeking exclusive, collaborative football footwear drops.
- In June 2025, Nike Inc. launched the highly anticipated France National Team kit for the Women's Euro 2025, presenting a bold statement in innovation, self-expression, and athletic performance. This kit features Nike’s advanced Dri-FIT ADV technology, state-of-the-art body-mapping, and the use of sustainable materials like Nike Grind, developed from recycled production waste, old sneakers, and unsold footwear.
- In March 2025, Adidas AG released the special Adidas 11Pure 2025 football boots, featuring a maroon colorway and a Taurus leather upper. This model marks a nostalgic nod to the classic 11Pro boot, combined with a modern Copa Pure soleplate, and celebrates Toni Kroos’ retirement by renaming the Adipure 11Pro as TKPro. The new design became available on March 4, 2025, aligning with elevated demand from the French football community for innovative materials and fit.
Report Coverage
The research report offers an in-depth analysis based on Type, Stud and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The France Football Shoes Market will benefit from rising grassroots initiatives that expand participation among youth and amateur players.
- Increasing demand for sustainable materials will drive innovation in eco-friendly shoe collections tailored to eco-conscious consumers.
- Digital platforms will expand brand visibility, with e-commerce strengthening as a preferred channel for both premium and affordable shoes.
- Customization will evolve further, offering consumers personalized fit, style, and performance features for unique buying experiences.
- Growth in women’s football will open new demand avenues, pushing companies to design gender-specific footwear lines.
- Smart footwear adoption will increase as connected technologies gain traction among professional and semi-professional athletes.
- Lifestyle and streetwear crossovers will continue to influence product design, extending market relevance beyond traditional players.
- Regional clubs and Ligue 1 sponsorships will strengthen brand positioning, fueling aspirational demand for professional-grade models.
- Mid-range categories will remain critical in Central France, supporting accessibility for grassroots and community-level football.
- Retail and online synergies will define competitive strategies, with direct-to-consumer platforms becoming core growth drivers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for France Football Shoes Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Football Shoes Market projected to grow between 2024 and 2032?
Which France Football Shoes Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Football Shoes Market?
Who are the leading companies in the France Football Shoes Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Football Shoes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Football Shoes Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,261.76 million → 2032: USD 1,931.83 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Football Shoes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Football Shoes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Football Shoes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Football Shoes Market Drivers
- 3.3 France Football Shoes Market Restraints & Challenges
- 3.4 France Football Shoes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Football Shoes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Football Shoes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Football Shoes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Football Shoes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Football Shoes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Football Shoes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Football Shoes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Football Shoes Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Football Shoes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Football Shoes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Football Shoes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Football Shoes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Football Shoes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Football Shoes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Football Shoes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Football Shoes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Football Shoes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Football Shoes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Football Shoes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
