
Market Overview:
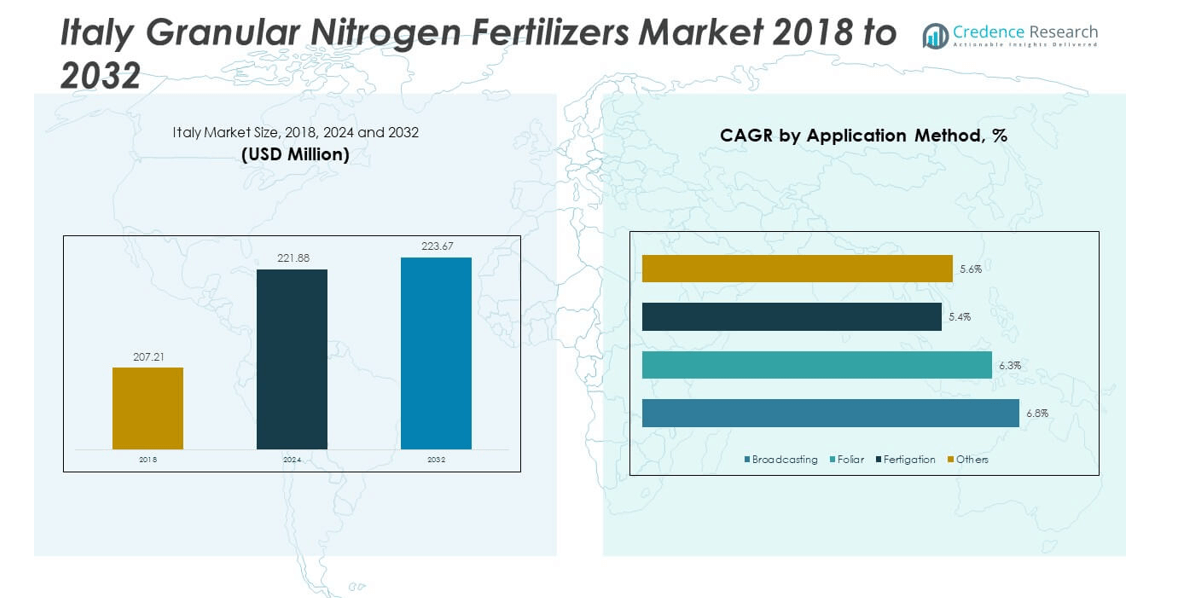
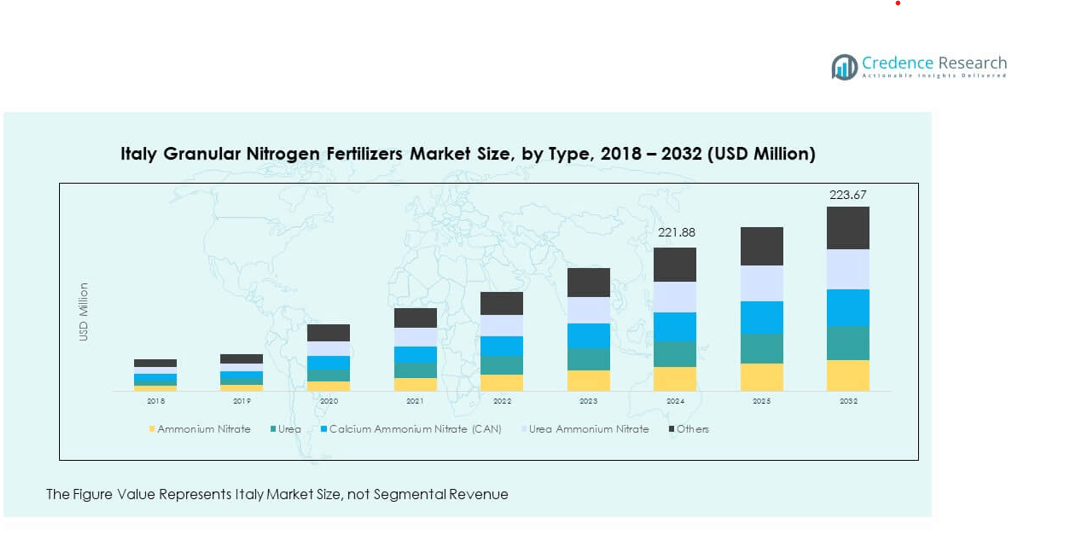
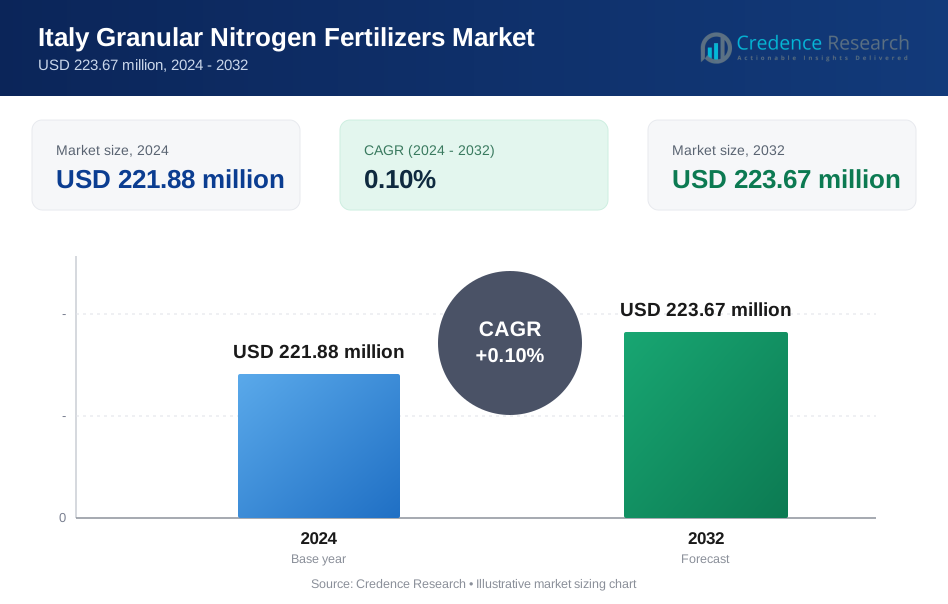
The Italy Granular Nitrogen Fertilizers Market size was valued at USD 207.21 million in 2018 to USD 221.88 million in 2024 and is anticipated to reach USD 223.67 million by 2032, at a CAGR of 0.10% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Italy Granular Nitrogen Fertilizers Market Size 2024 | USD 221.88 million |
| Italy Granular Nitrogen Fertilizers Market, CAGR | 0.10% |
| Italy Granular Nitrogen Fertilizers Market Size 2032 | USD 223.67 million |
The market growth is driven by the rising demand for high-yield crops, adoption of advanced farming practices, and government initiatives promoting sustainable agriculture. Italian farmers are increasingly using granular nitrogen fertilizers for better nutrient efficiency and soil health. Technological advances in fertilizer formulations, along with precision agriculture, are further enhancing the market demand across diverse crop categories.
Geographically, northern Italy leads the market due to its high concentration of agricultural activities and developed farming infrastructure. Regions such as Lombardy, Emilia-Romagna, and Veneto show strong fertilizer adoption supported by intensive crop cultivation. Southern regions, including Sicily and Puglia, are emerging with growing awareness and investment in modern agriculture. This regional expansion is strengthening the country’s overall fertilizer consumption landscape.
Market Insights:
- The Italy Granular Nitrogen Fertilizers Market was valued at USD 207.21 million in 2018, grew to USD 221.88 million in 2024, and is expected to reach USD 223.67 million by 2032, expanding at a CAGR of 0.10% during the forecast period.
- Northern Italy led the market with a 56% share in 2024, supported by large-scale farming, advanced irrigation systems, and precision agriculture practices. Central Italy accounted for 25%, driven by strong horticultural and vineyard activity, while Southern Italy held 19% due to increasing fertilizer adoption in arid regions.
- Southern Italy and its islands represent the fastest-growing region with a 19% share, supported by government-backed modernization programs and expanding greenhouse cultivation.
- The urea segment accounted for around 35% of total revenue, driven by its high nitrogen content and cost-effectiveness.
- Calcium ammonium nitrate (CAN) held approximately 25% share due to its balanced nutrient composition and growing preference for sustainable fertilizer options.
Market Drivers:
Rising Focus on Crop Productivity and Nutrient Efficiency
The Italy Granular Nitrogen Fertilizers Market is driven by growing demand for high-yield crops supported by advanced agricultural inputs. Farmers aim to enhance soil fertility and ensure consistent nutrient delivery across key crops. Granular nitrogen fertilizers offer controlled release, improving plant uptake and reducing nutrient loss. It supports efficient nitrogen utilization, minimizing environmental impact from leaching. Government initiatives promoting precision agriculture encourage the adoption of these fertilizers. Increased awareness of sustainable farming practices boosts their use in cereals, fruits, and vegetables. Rising population and food demand continue to strengthen fertilizer consumption.
- For instance, Yara’s N-Sensor technology has delivered up to a 12% increase in crop yields and up to a 14% reduction in nitrogen fertilizer usage across multiple crop types, according to verified company reports and field results.
Government Initiatives and Sustainable Agricultural Programs
Italian authorities are supporting eco-friendly farming policies that promote balanced nutrient management. Subsidies and awareness programs focus on responsible fertilizer use to protect soil health. The Italy Granular Nitrogen Fertilizers Market benefits from the Common Agricultural Policy (CAP) and EU environmental guidelines. Farmers receive training to optimize fertilizer efficiency and limit overuse. Sustainable nitrogen management aligns with carbon neutrality goals in the agricultural sector. It encourages innovative fertilizer blends that balance crop nutrition and soil sustainability. Continuous public investment in sustainable inputs strengthens long-term growth.
- For instance, Yara’s N-Sensor has reduced nitrogen residues in soil post-harvest and cut the risk of nitrogen losses to the environment, supporting national and EU sustainability targets in farming practices.
Technological Advancements in Fertilizer Formulation and Application
Manufacturers are investing in advanced coating technologies for controlled and slow-release fertilizers. The Italy Granular Nitrogen Fertilizers Market gains from enhanced efficiency and reduced nitrogen volatilization. Automation in fertilizer blending and precision spreading improves accuracy and uniformity. It allows farmers to optimize dosage based on real-time soil data. Integration with GPS-guided machinery supports resource conservation and productivity gains. New product developments focus on customized nutrient compositions tailored for local crops. Technological innovation continues to improve application methods and reduce operational costs.
Growing Adoption of Precision Agriculture and Smart Farming Solutions
Modern farming practices across Italy are increasingly data-driven, encouraging efficient fertilizer use. The Italy Granular Nitrogen Fertilizers Market sees rising integration with IoT-based monitoring systems. Farmers use data analytics to adjust nitrogen application by soil type and crop stage. Precision agriculture reduces waste, enhances yield, and supports environmental sustainability. It helps maintain soil balance and improves cost-effectiveness in crop management. Agritech companies are partnering with cooperatives to deliver smart fertilizer solutions. These innovations expand adoption among small and medium-scale farms nationwide.
Market Trends:
Shift Toward Environmentally Friendly and Low-Emission Fertilizers
Growing concerns over nitrogen runoff and greenhouse emissions are reshaping fertilizer production. The Italy Granular Nitrogen Fertilizers Market is moving toward low-emission and bio-based products. Manufacturers are introducing sustainable formulations to meet EU climate goals. Eco-labeled fertilizers help farmers align with green certification programs. Demand for biodegradable coatings and organic nitrogen sources is increasing steadily. It supports reduced environmental impact and aligns with circular economy principles. These trends highlight Italy’s transition to climate-smart agriculture.
- For instance, Yara’s N-Sensor technology has led to a 10-30% decrease in the carbon footprint of fertilizer application by improving nitrogen use efficiency through site-specific application and monitoring.
Integration of Digital Agriculture Tools and Farm Automation
Digitalization is transforming how farmers plan and monitor fertilizer application. The Italy Granular Nitrogen Fertilizers Market benefits from AI-driven soil analysis and remote sensing systems. Digital tools improve nutrient mapping and enhance crop response tracking. Automation in fertilizer application reduces wastage and increases precision. It enables integration with drones and variable-rate technologies for real-time adjustments. Agritech startups are developing cloud-based platforms for nutrient management. The growing use of these systems is redefining efficiency in agricultural production.
- For instance, Yara’s N-Sensor provides real-time, variable-rate nitrogen application to ensure optimal fertilizer for every part of the field, with documented increases in combine output by up to 18.5% and a reduction in lodging rates by 80% for cereal crops.
Emergence of Customized and Crop-Specific Fertilizer Formulations
Farmers increasingly prefer fertilizers suited to regional soils and specific crop needs. The Italy Granular Nitrogen Fertilizers Market is witnessing demand for tailor-made formulations. Companies focus on optimizing nitrogen balance for high-value crops like grapes and olives. It ensures balanced nutrition while supporting export-quality yields. Research centers collaborate with fertilizer firms to develop locally adapted solutions. Customized nutrient blends help minimize waste and enhance profitability. The trend supports long-term sustainability and competitiveness in agricultural production.
Increasing Collaboration Between Fertilizer Producers and Research Institutions
Collaboration between universities and fertilizer manufacturers is strengthening innovation in the market. The Italy Granular Nitrogen Fertilizers Market benefits from scientific input on nutrient efficiency and soil interaction. Joint projects focus on improving fertilizer composition and minimizing nitrogen loss. It promotes sustainable soil enrichment practices supported by data validation. Such partnerships enhance product quality and build farmer confidence. They also drive pilot projects for advanced formulations in diverse climatic zones. Continuous research ensures alignment with global agricultural standards.
Market Challenges Analysis:
Environmental Regulations and Compliance Constraints in Fertilizer Use
Strict EU environmental directives are posing operational challenges for fertilizer manufacturers. The Italy Granular Nitrogen Fertilizers Market faces tighter limits on nitrogen application rates to curb emissions. Compliance with nitrate directives requires advanced monitoring and recordkeeping. It increases production costs for companies adapting to green chemistry standards. Smaller producers struggle to meet the certification requirements for sustainable fertilizers. Farmers also face pressure to reduce dependency on synthetic nitrogen inputs. This regulatory tightening impacts market flexibility and pricing competitiveness.
Rising Production Costs and Supply Chain Disruptions Impacting Profit Margins
The fertilizer industry is affected by volatile raw material and energy prices. The Italy Granular Nitrogen Fertilizers Market experiences cost fluctuations due to natural gas dependency. High transportation and logistics expenses further affect distribution efficiency. It challenges producers to balance affordability and profitability. Imported fertilizers face longer lead times and variable import tariffs. These conditions force companies to revise pricing strategies and production planning. The market’s long-term stability depends on improving domestic manufacturing resilience and raw material diversification.
Market Opportunities:
Expansion of Organic and Bio-Based Fertilizer Production in Italy
Growing demand for organic produce offers strong opportunities for fertilizer innovation. The Italy Granular Nitrogen Fertilizers Market can benefit from bio-based nitrogen alternatives. Manufacturers are investing in natural nutrient sources like composted manure and green ammonia. It aligns with Italy’s focus on reducing chemical dependence in farming. Expanding organic farming zones create new prospects for sustainable fertilizer use. Public incentives for eco-friendly inputs further support product diversification. This trend enhances Italy’s position in the European sustainable agriculture movement.
Adoption of Smart Fertilizer Management Systems for Yield Optimization
Digital transformation across agriculture is creating new growth avenues for fertilizer producers. The Italy Granular Nitrogen Fertilizers Market is witnessing adoption of AI-based nutrient monitoring systems. Smart sensors enable precise nitrogen management and reduce environmental loss. It allows real-time crop data analysis for adaptive fertilizer application. Government-backed precision farming initiatives encourage this technological shift. Collaboration between agritech firms and cooperatives is driving awareness among small farmers. These developments ensure efficient fertilizer use and sustainable productivity growth.
Market Segmentation Analysis:
By Type
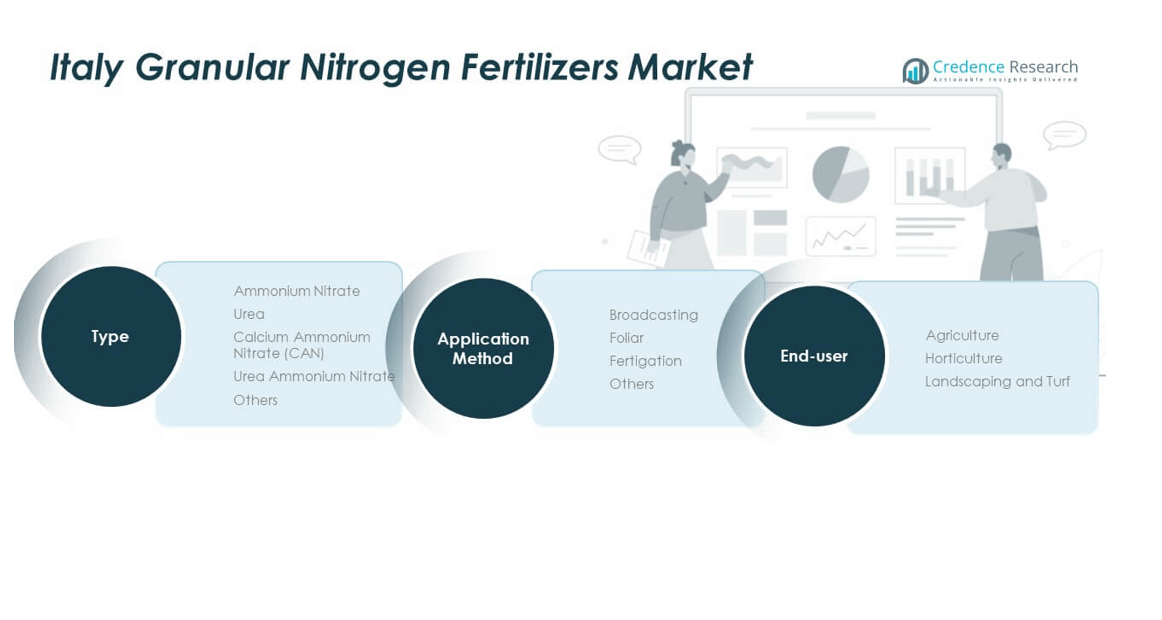
The Italy Granular Nitrogen Fertilizers Market is segmented into ammonium nitrate, urea, calcium ammonium nitrate (CAN), urea ammonium nitrate, and others. Urea dominates the market due to its high nitrogen concentration and widespread use in major crops. Ammonium nitrate follows, valued for its rapid nutrient release and compatibility with Italian soil types. CAN is gaining preference for its stable performance and reduced risk of soil acidification. Urea ammonium nitrate supports precision agriculture with uniform distribution and higher efficiency. The others category includes specialized nitrogen blends used in niche agricultural applications. Each fertilizer type addresses specific nutrient and soil requirements across different farming systems.
- For instance, Yara’s N-Sensor technology demonstrated 3.5% greater cereal yields and up to 3.9% higher canola yields when used with standard and advanced fertilizer types in Italy.
By Application Method
The market is divided into broadcasting, foliar, fertigation, and others. Broadcasting holds the largest share due to its practicality and adoption in large-scale crop cultivation. Foliar application is expanding due to faster nutrient absorption and reduced wastage. Fertigation is growing steadily with advancements in irrigation systems and precision agriculture. It improves nutrient delivery, enhances soil balance, and supports water-efficient farming. The others category includes innovative methods applied in greenhouse and controlled environments. This segmentation highlights a clear trend toward efficiency-driven application practices across Italian farms.
- For instance, the implementation of Yara’s N-Sensor allowed precision application via broadcasting, resulting in more uniform crop nutrition, improved protein consistency (0.2–0.5% above target), and lower harvesting costs for Italian farmers.
By End-User
End users include agriculture, horticulture, and landscaping and turf. Agriculture represents the dominant segment due to extensive nitrogen use in grain and cereal cultivation. Horticulture is expanding with higher fertilizer consumption for fruits, vegetables, and floriculture. Landscaping and turf are emerging segments supported by urban development projects and recreational spaces. It reflects Italy’s growing attention to sustainable soil management and productivity enhancement across all farming sectors.
Segmentation:
By Type
- Ammonium Nitrate
- Urea
- Calcium Ammonium Nitrate (CAN)
- Urea Ammonium Nitrate
- Others
By Application Method
- Broadcasting
- Foliar
- Fertigation
- Others
By End-User
- Agriculture
- Horticulture
- Landscaping and Turf
Regional Analysis:
Northern Italy – Dominant Agricultural and Industrial Hub (56% Market Share)
Northern Italy leads the Italy Granular Nitrogen Fertilizers Market with a 56% share, driven by intensive agricultural activities and advanced farming infrastructure. Regions such as Lombardy, Emilia-Romagna, and Veneto have high fertilizer usage due to the cultivation of cereals, maize, and industrial crops. It benefits from well-developed irrigation systems and precision agriculture adoption. Strong agrochemical distribution networks and access to research institutions support product innovation and farmer awareness. Local cooperatives encourage sustainable fertilizer practices and efficient nutrient management. High-income farms in this region focus on maximizing yield and maintaining soil fertility through balanced nitrogen applications.
Central Italy – Expanding Horticultural and Vineyard Production (25% Market Share)
Central Italy holds around 25% of the total market share, supported by diversified crop cultivation and expanding horticultural output. Tuscany, Umbria, and Marche regions have growing demand for granular nitrogen fertilizers used in vineyards, olive groves, and vegetable farming. It shows a strong shift toward organic and eco-friendly fertilizers, aligning with regional sustainability goals. Farmers are investing in advanced fertilization techniques to meet export-grade production standards. Government support for agri-innovation and local cooperatives enhances access to improved fertilizer blends. This region is expected to maintain steady growth through modernization and targeted nutrient application.
Southern Italy and Islands – Emerging Growth Region (19% Market Share)
Southern Italy, including Sicily and Puglia, accounts for 19% of the Italy Granular Nitrogen Fertilizers Market. It is an emerging growth area driven by increasing awareness of soil nutrition and modernization of farming practices. The region benefits from rising investments in irrigation infrastructure and greenhouse farming. Growing horticultural and citrus crop cultivation is creating demand for high-efficiency nitrogen fertilizers. Local producers are focusing on fertigation and precision application to optimize usage in arid conditions. Government-led rural development projects and subsidies for fertilizer adoption continue to support growth, making the southern region a potential hotspot for future expansion.
Key Player Analysis:
- Yara International ASA
- FCP Cerea
- Vita Chemie
- Delta Fertil
- Lea Agricola
- EuroChem Group AG
- OCI Nitrogen
- BASF SE
Competitive Analysis:
The Italy Granular Nitrogen Fertilizers Market is moderately competitive, featuring both international and domestic producers focused on improving fertilizer efficiency and environmental performance. It is led by companies such as Yara International ASA, EuroChem Group AG, BASF SE, FCP Cerea, and Lea Agricola, which emphasize innovation and sustainable fertilizer formulations. Firms compete on product differentiation, nutrient efficiency, and regional distribution strength. The market shows rising collaboration between manufacturers and research institutions to develop advanced nitrogen solutions. Local players are strengthening their presence through tailored products for regional crop requirements and expanding precision agriculture partnerships.
Recent Developments:
- In July 2025, Yara International ASA reported record-high production results in the granular nitrogen fertilizers segment, driven by commercial performance and supportive market fundamentals.
- In January 2025, FCP Cerea announced a strategic merger agreement with Demeter Investment Managers, positioning the joint entity as Demea Invest—a leading player in private equity and debt investments for startups, SMEs, and mid-sized companies in the agri-food value chain and energy sectors.
Report Coverage:
The research report offers an in-depth analysis based on by type, application method, and end-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of precision agriculture is expected to improve nitrogen efficiency across Italian farms.
- Government initiatives supporting eco-friendly fertilizers will drive innovation in product formulations.
- Demand for slow-release and coated nitrogen fertilizers will expand with sustainability awareness.
- Northern Italy will retain market leadership due to advanced infrastructure and high crop productivity.
- Fertigation-based applications will grow rapidly, supported by irrigation modernization.
- Local manufacturers will gain share through region-specific fertilizer blends.
- Investments in bio-based and low-emission fertilizers will create new growth opportunities.
- Partnerships between agritech companies and cooperatives will enhance distribution networks.
- Technological advancements in monitoring systems will optimize nitrogen application precision.
- The market will maintain steady long-term growth with increasing focus on soil health and regulatory compliance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Italy Granular Nitrogen Fertilizers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Italy Granular Nitrogen Fertilizers Market projected to grow between 2024 and 2032?
Which Italy Granular Nitrogen Fertilizers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Italy Granular Nitrogen Fertilizers Market?
Who are the leading companies in the Italy Granular Nitrogen Fertilizers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Italy Granular Nitrogen Fertilizers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Italy Granular Nitrogen Fertilizers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 221.88 million → 2032: USD 223.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Italy Granular Nitrogen Fertilizers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Italy Granular Nitrogen Fertilizers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Italy Granular Nitrogen Fertilizers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Italy Granular Nitrogen Fertilizers Market Drivers
- 3.3 Italy Granular Nitrogen Fertilizers Market Restraints & Challenges
- 3.4 Italy Granular Nitrogen Fertilizers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Italy Granular Nitrogen Fertilizers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Italy Granular Nitrogen Fertilizers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Italy Granular Nitrogen Fertilizers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Italy Granular Nitrogen Fertilizers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Italy Granular Nitrogen Fertilizers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Italy Granular Nitrogen Fertilizers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Italy Granular Nitrogen Fertilizers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Italy Granular Nitrogen Fertilizers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Italy Granular Nitrogen Fertilizers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Italy Granular Nitrogen Fertilizers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Italy Granular Nitrogen Fertilizers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Italy Granular Nitrogen Fertilizers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Italy Granular Nitrogen Fertilizers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Italy Granular Nitrogen Fertilizers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Italy Granular Nitrogen Fertilizers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Italy Granular Nitrogen Fertilizers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Italy Granular Nitrogen Fertilizers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Italy Granular Nitrogen Fertilizers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Italy Granular Nitrogen Fertilizers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
