
Laser Welding Machine Market Overview:
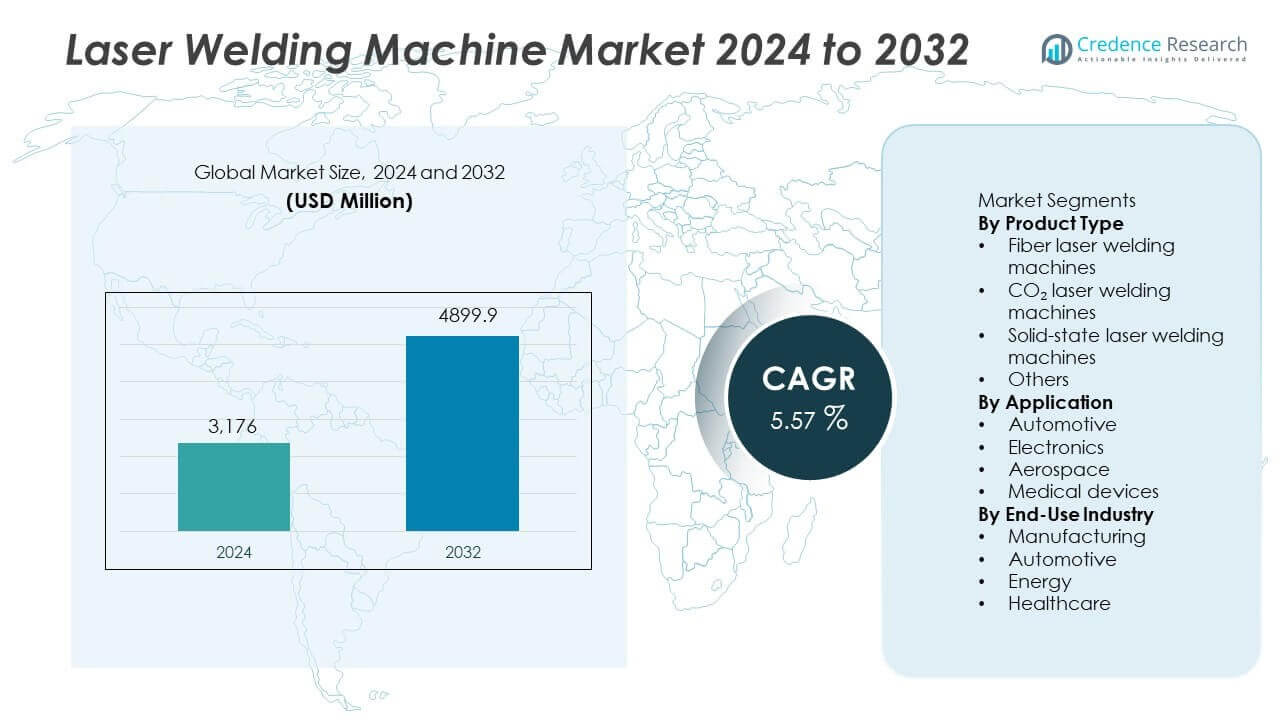
The laser welding machine market was valued at USD 3,176 million in 2024 and is anticipated to reach USD 4,899.9 million by 2032, growing at a CAGR of 5.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Laser Welding Machine Market Size 2024 | USD 3,176 million |
| Laser Welding Machine Market, CAGR | 5.57% |
| Laser Welding Machine Market Size 2032 | USD 4,899.9 million |
Laser Welding Machine Market Insights
- Industrial automation and electric vehicle production act as key market drivers, with manufacturing end use leading at a segment share of 44.6%, driven by productivity gains, quality consistency, and reduced rework.
- Market trends highlight strong preference for fiber laser welding machines, which hold a segment share of 54.2%, supported by high energy efficiency, low maintenance, and superior beam quality.
- Competitive analysis indicates a technology-driven landscape, where leading players focus on automation integration, smart controls, and application-specific solutions to strengthen long-term customer relationships.
- Regional analysis shows Asia Pacific leading with a market share of 38.9%, followed by North America at 27.6% and Europe at 25.1%, driven by automotive production, electronics manufacturing, and industrial modernization.
Laser Welding Machine Market Segmentation Analysis:
By Product Type
The product type segment shows clear dominance of fiber laser welding machines, which hold a market share of 54.2%. Manufacturers prefer fiber lasers due to high energy efficiency, superior beam quality, and low maintenance needs. These systems support high-speed welding and precise control across metals. Strong adoption comes from automotive and electronics manufacturing. CO₂ laser welding machines account for a share of 21.6%, supported by thick material welding needs. Solid-state laser welding machines hold 18.3%, driven by precision applications. Product demand grows due to productivity gains, automation compatibility, and reduced operating costs.
- For instance, TRUMPF deployed TruFiber systems delivering 6,000 W output with beam parameter product below 2.0 mm·mrad, enabling weld speeds above 10 m/min on steel.
By Application
The automotive application segment leads with a market share of 39.8%. Laser welding machines enable lightweight body structures and high-strength joints. Precision welding supports electric vehicle battery and powertrain assembly. Electronics follows with a share of 27.4%, driven by miniaturized components and circuit welding. Aerospace holds 19.1%, supported by demand for high-reliability joints. Medical devices account for 13.7%, led by implant and instrument manufacturing. Application growth depends on accuracy, repeatability, and reduced thermal distortion. Automation trends further strengthen laser welding adoption across high-volume and precision-driven industries.
- For instance, FANUC integrates laser welding cells achieving cycle times below 3 seconds per weld with robot repeatability of ±0.02 mm. Electronics manufacturing relies on fine control and low heat input.
By End-Use Industry
Manufacturing dominates end-use consumption with a market share of 44.6%. General manufacturing benefits from flexible integration into automated production lines. Automotive end-use follows with 31.2%, driven by vehicle production and lightweight design needs. Energy holds 14.3%, supported by battery systems and renewable equipment manufacturing. Healthcare accounts for 9.9%, focused on precision medical components. End-use demand grows due to productivity improvement and quality consistency. Rising industrial automation and smart factory investments support long-term adoption. Cost efficiency and reduced rework remain key drivers across end-use industries.
Key Growth Drivers
Rising Adoption of Industrial Automation
Manufacturers increasingly adopt laser welding machines to support automated production lines. High precision and repeatability improve output quality. Integration with robots reduces labor dependency and cycle time. Automotive and electronics plants prioritize automated welding for consistency. Laser systems enable real-time control and process stability. Smart factories favor digital connectivity and monitoring. Reduced rework lowers operational costs. Automation investments continue across developed and emerging markets. This driver supports steady demand growth as industries scale production with efficiency and accuracy.
- For instance, Bystronic supplies automated laser welding solutions achieving precise seam tracking using integrated vision sensors, which reduces rework and scrap generation.
Expansion of Electric Vehicle and Battery Manufacturing
Electric vehicle production drives strong demand for laser welding machines. Battery cells require precise and clean welding processes. Laser systems support thin materials and complex joints. Thermal control protects sensitive battery components. Automotive OEMs expand EV platforms globally. High production volumes favor fast and reliable welding. Lightweight vehicle design increases laser usage. Energy storage systems also adopt laser welding. This driver aligns with long-term electrification and mobility trends.
- For instance, Amada develops laser systems capable of welding aluminum battery housings at speeds of 5 m/min while maintaining heat-affected zones under 0.3 mm, protecting sensitive cell structures.
Growth in Precision Manufacturing Applications
Precision industries rely on laser welding for tight tolerances. Electronics manufacturing uses lasers for micro-welding tasks. Aerospace applications require strong and defect-free joints. Medical device production demands clean and controlled welding. Laser systems reduce heat-affected zones. High-quality finishes improve component reliability. Advanced materials increase process complexity. Precision requirements drive technology upgrades. This driver supports adoption across high-value manufacturing sectors.
Key Trends & Opportunities
Shift Toward Fiber Laser Welding Technology
Fiber laser welding gains preference due to energy efficiency. Compact design supports flexible installation. Low maintenance reduces downtime and costs. High beam quality improves welding accuracy. Manufacturers replace older CO₂ systems with fiber lasers. Automation compatibility strengthens adoption. Small and mid-sized enterprises enter the market. Cost reductions improve accessibility. This trend creates opportunities for equipment upgrades and system integration services.
- For instance, IPG Photonics supplies continuous-wave fiber lasers with electrical efficiency above 45 and operational lifetimes exceeding 100,000 hours, lowering service interruptions.
Integration of Digital Monitoring and Smart Controls
Digital control systems enhance laser welding performance. Sensors monitor weld quality in real time. Data analytics support predictive maintenance. Smart interfaces improve operator control. Connectivity enables integration with factory management systems. Quality assurance improves with automated inspection. Manufacturers seek traceable production processes. This trend opens opportunities for software-enabled welding solutions and service contracts.
- For instance, Coherent Corp. delivers laser platforms with inline power monitoring sampling at 10 kHz, allowing immediate detection of weld energy deviations.
Key Challenges
High Initial Investment and System Costs
Laser welding machines require significant capital investment. Advanced systems increase upfront costs. Small manufacturers face adoption barriers. Integration expenses add to total ownership cost. Skilled workforce requirements raise training costs. Return on investment depends on production scale. Price sensitivity affects purchasing decisions. Financing options remain limited in some regions. Cost challenges slow adoption among smaller end users.
Technical Complexity and Skilled Labor Requirement
Laser welding systems demand technical expertise. Process optimization requires trained operators. Equipment calibration affects weld quality. Lack of skilled labor limits utilization. Training programs increase operational time. Improper use leads to defects and downtime. Maintenance needs technical support. Complexity discourages first-time users. Addressing skill gaps remains critical for broader market adoption.
Regional Analysis
North America
North America holds a market share of 27.6% in the laser welding machine market. Strong demand comes from automotive, aerospace, and electronics manufacturing. The United States leads regional adoption due to advanced automation and high labor costs. Manufacturers invest in laser welding to improve productivity and quality consistency. Electric vehicle and battery production supports equipment demand. Aerospace firms rely on laser welding for precision and strength. Presence of advanced manufacturing facilities accelerates technology upgrades. Skilled workforce availability supports complex system integration. Stable industrial investment sustains long-term regional growth.
Europe
Europe accounts for a market share of 25.1%, driven by strong automotive and industrial manufacturing bases. Germany, France, and Italy lead equipment adoption across factories. Strict quality and emission standards encourage advanced welding technologies. Automotive OEMs use laser welding for lightweight structures and electric vehicles. Aerospace and electronics sectors support precision welding demand. Industry focus on energy efficiency favors fiber laser systems. High automation penetration strengthens replacement demand. Innovation-driven manufacturing supports stable growth. Regulatory compliance and technology leadership define the regional market.
Asia Pacific
Asia Pacific dominates the laser welding machine market with a market share of 38.9%. Rapid industrialization drives strong equipment demand across China, Japan, South Korea, and India. Automotive production and electronics manufacturing remain key growth engines. Expanding electric vehicle supply chains increase laser welding usage. Cost-effective manufacturing attracts global investments. Rising automation adoption improves productivity across factories. Government support for advanced manufacturing boosts installations. High-volume production favors fast and precise welding systems. Infrastructure and industrial expansion sustain long-term regional leadership.
Rest of the World
The Rest of the World region holds a market share of 8.4%. Growth is driven by gradual industrial expansion in Latin America and the Middle East. Automotive assembly and metal fabrication support equipment demand. Energy and infrastructure projects increase welding needs. Adoption remains moderate due to cost sensitivity. Import dependence affects equipment availability. Industrial modernization initiatives improve market potential. Africa shows early-stage adoption tied to manufacturing growth. Long-term expansion depends on automation investment and skilled labor development.
Laser Welding Machine Market Segmentations:
By Product Type
- Fiber laser welding machines
- CO₂ laser welding machines
- Solid-state laser welding machines
- Others
By Application
- Automotive
- Electronics
- Aerospace
- Medical devices
By End-Use Industry
- Manufacturing
- Automotive
- Energy
- Healthcare
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights TRUMPF Group, IPG Photonics Corporation, Coherent Corp., Han’s Laser Technology Industry Group, Amada Co., Ltd., Bystronic Group, FANUC Corporation, Mitsubishi Electric Corporation, Jenoptik AG, and Laserline GmbH as the core participants shaping the laser welding machine market. These companies compete through technology leadership, system reliability, and automation integration. Strong investment in fiber laser innovation supports higher efficiency and precision. Global manufacturing footprints ensure faster delivery and service support. Strategic partnerships with automotive and electronics manufacturers strengthen long-term contracts. Product portfolios increasingly focus on smart controls and digital monitoring. Mid-sized players compete through cost efficiency and application-specific solutions. Competitive intensity remains high due to rapid technology cycles. Overall, innovation capability, automation compatibility, and aftersales service define market positioning.
Key Player Analysis
- TRUMPF Group
- IPG Photonics Corporation
- Coherent Corp.
- Han’s Laser Technology Industry Group
- Amada Co., Ltd.
- Bystronic Group
- FANUC Corporation
- Mitsubishi Electric Corporation
- Jenoptik AG
- Laserline GmbH
Recent Developments
- In September 2025, Coherent Corp. launched the WELD2D MP laser welding scanner at Schweissen & Schneiden. The tool targets e-mobility and electronics welding throughput.
- In June 2025, TRUMPF Group introduced a laser-welding solution with sensors and AI. OCT monitors weld depth, and AI checks seam quality.
- In May 2024, IPG Photonics Corporation launched the LightWELD® 2000 XR handheld welding system. The update targets faster processing and a wider thickness range.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will increase as manufacturers expand industrial automation and smart factories.
- Automotive production will drive adoption for lightweight and high-strength welding needs.
- Electric vehicle and battery manufacturing will remain major growth contributors.
- Fiber laser systems will see higher adoption due to efficiency and reliability.
- Precision electronics manufacturing will support steady equipment demand.
- Integration of digital monitoring will improve weld quality and uptime.
- Aerospace applications will expand with advanced material usage.
- Emerging markets will invest in modern welding technologies.
- Custom system integration will gain importance across end-use industries.
- Continuous innovation will intensify competition among leading players.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Laser Welding Machine market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Laser Welding Machine market projected to grow between 2024 and 2032?
Which Laser Welding Machine market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Laser Welding Machine market?
Who are the leading companies in the Laser Welding Machine market?
Which region commanded the largest share of the Laser Welding Machine market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,176 million → 2032: USD 4,899.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laser Welding Machine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laser Welding Machine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laser Welding Machine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laser Welding Machine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laser Welding Machine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laser Welding Machine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laser Welding Machine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laser Welding Machine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,176 million → 2032: USD 4,899.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laser Welding Machine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laser Welding Machine Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Laser Welding Machine Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Laser Welding Machine Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

