
HVAC System Market Overview:
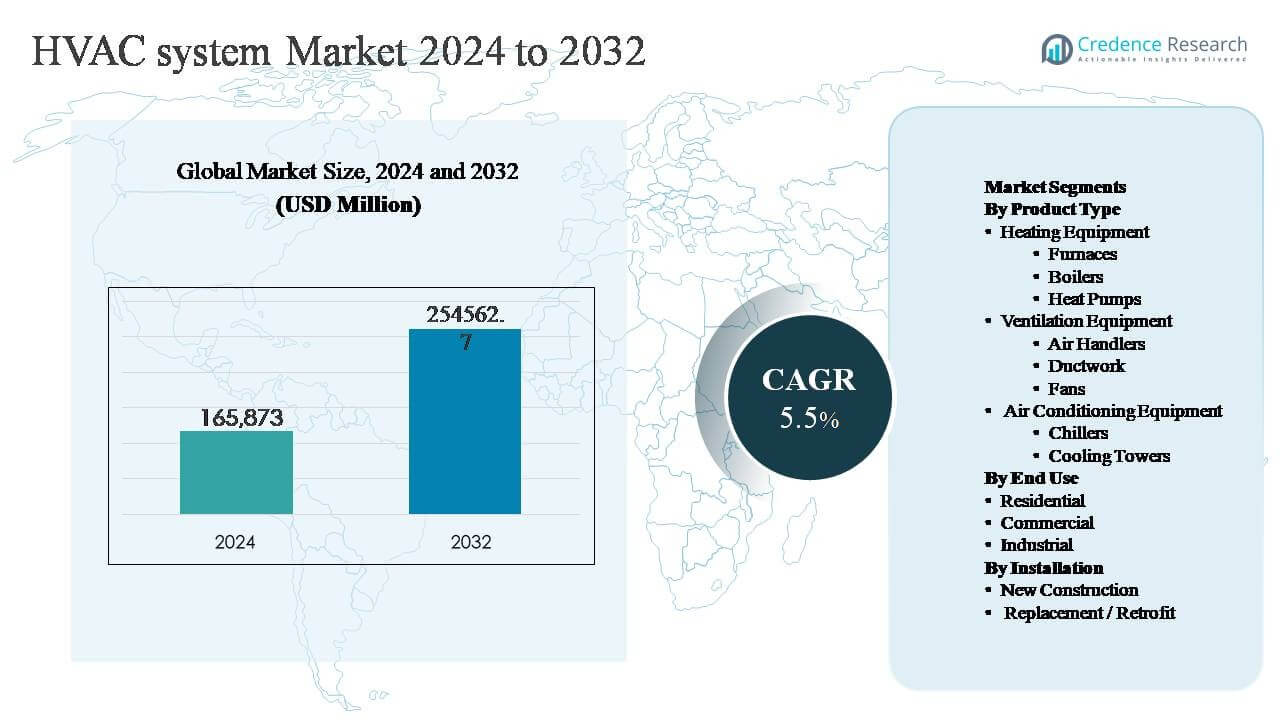
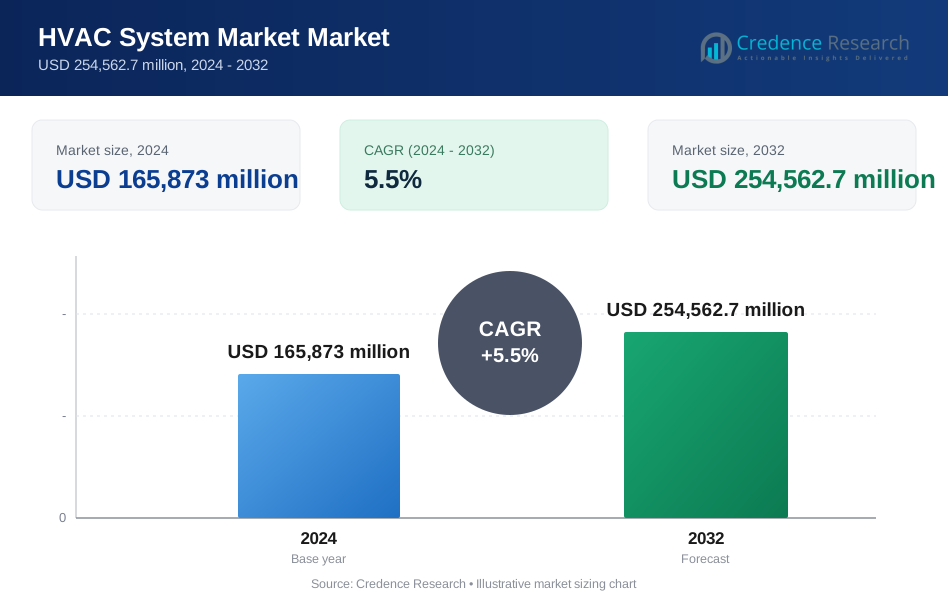
The global HVAC system market size was valued at USD 165,873 million in 2024 and is projected to reach USD 254,562.7 million by 2032, expanding at a compound annual growth rate (CAGR) of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| HVAC System Market Size 2024 | USD 165,873 million |
| HVAC System Market , CAGR | 5.5% |
| HVAC System Market Size 2032 | USD 254,562.7 million |
HVAC System Market Insights
- Market growth is driven by rapid urbanization, expanding construction activity, and rising demand for energy-efficient heating, ventilation, and air conditioning solutions, with air conditioning equipment remaining the dominant product segment due to high cooling requirements in urban and warm-climate regions.
- Key market trends include increasing adoption of heat pumps, smart and connected HVAC systems, and low-GWP refrigerants, while replacement and retrofit installations account for the larger installation share as aging infrastructure undergoes efficiency upgrades.
- The competitive landscape is defined by global leaders focusing on innovation, portfolio expansion, and digital integration, intensifying competition around system efficiency, lifecycle costs, and sustainability performance.
- Regionally, Asia-Pacific leads with around 34% market share, followed by North America at 28% and Europe at 24%, while the commercial end-use segment holds the largest share due to extensive deployment in offices, healthcare, retail, and large infrastructure projects.
HVAC System Market Segmentation Analysis:
By Product Type:
The HVAC system market by product type is led by air conditioning equipment, which holds the dominant market share due to widespread adoption across residential, commercial, and industrial buildings. Chillers represent the leading sub-segment, driven by their critical role in large commercial complexes, data centers, and industrial process cooling. Rising global temperatures, higher cooling load requirements, and expanding urban infrastructure continue to support demand. Heating equipment, particularly heat pumps, is gaining strong traction as energy efficiency regulations and decarbonization goals accelerate adoption, while ventilation equipment such as air handlers remains essential for indoor air quality compliance.
- For instance, Daikin Industries’ centrifugal chillers deployed in large commercial facilities such as airports and district cooling plants are engineered for cooling capacities exceeding 10,000 refrigeration tons per installation, enabling continuous operation in high-load environments such as data centers and mixed-use developments.
By End Use:
The commercial segment accounts for the dominant share of the HVAC system market by end use, supported by extensive deployment in offices, hospitals, retail centers, hotels, airports, and educational facilities. High occupancy levels, stringent indoor air quality standards, and the need for centralized climate control systems drive sustained demand. Commercial buildings increasingly invest in advanced HVAC solutions to reduce operating costs and meet sustainability certifications. Residential demand remains robust due to housing growth and rising comfort expectations, while industrial applications rely on HVAC systems to maintain process stability, equipment protection, and workforce safety.
- For instance, in large healthcare and airport projects, Trane has deployed water-cooled chiller plants with individual unit cooling capacities exceeding 6,000 kW, enabling precise temperature and humidity control required for continuous, high-occupancy environments.
By Installation:
By installation, the replacement and retrofit segment dominates the HVAC system market, reflecting aging building stock and increasing emphasis on energy-efficient upgrades. Building owners are replacing outdated systems to comply with stricter efficiency standards, reduce energy consumption, and integrate smart control technologies. Retrofit activity is particularly strong in mature markets, where upgrading existing infrastructure is more cost-effective than new construction. While new construction continues to generate steady demand, especially in emerging economies, replacement and retrofit projects benefit from regulatory incentives, sustainability mandates, and rising lifecycle cost awareness.
Key Growth Driver
Rapid Urbanization and Construction Activity
Rapid urbanization and sustained construction activity remain a primary growth driver for the HVAC system market. Expanding urban populations are increasing demand for residential housing, commercial buildings, healthcare facilities, educational institutions, and mixed-use developments, all of which require reliable climate control solutions. Large-scale infrastructure investments, particularly in emerging economies, are accelerating installations of centralized HVAC systems in high-rise buildings, transportation hubs, and industrial parks. In mature markets, commercial real estate development continues to support demand for advanced HVAC configurations designed for large floor areas and high occupancy. The need to ensure thermal comfort, air circulation, and humidity control across diverse climatic conditions further strengthens HVAC adoption. Additionally, stricter building performance codes increasingly mandate integrated heating, ventilation, and cooling solutions in new developments, reinforcing long-term market expansion.
- For instance, Carrier provided water-cooled chiller systems for major international airport terminals with individual chiller capacities above 5,000 kW, supporting continuous operation in high-traffic environments.
Rising Focus on Energy Efficiency and Sustainability
Energy efficiency and sustainability considerations are significantly driving HVAC system adoption and upgrades. Governments and regulatory bodies worldwide are enforcing stringent energy efficiency standards and emissions regulations, prompting building owners to replace conventional systems with high-efficiency alternatives. Heat pumps, variable refrigerant flow systems, and inverter-based compressors are gaining traction due to their lower energy consumption and reduced environmental impact. Growing awareness of carbon footprint reduction is also encouraging the use of low-global-warming-potential refrigerants and renewable-energy-integrated HVAC solutions. Commercial and industrial users increasingly prioritize systems that deliver long-term operating cost savings while meeting sustainability targets. This regulatory and environmental push is transforming HVAC systems from basic comfort solutions into strategic assets for energy management and compliance.
- For instance, Mitsubishi Electric’s commercial air-to-water heat pump systems are engineered to deliver heating output water temperatures of up to 80 °C, allowing replacement of fossil-fuel boilers in retrofit projects without major changes to existing hydronic infrastructure.
Growing Demand for Indoor Air Quality and Thermal Comfort
Rising awareness of indoor air quality and occupant well-being is accelerating HVAC system deployment across end-use sectors. Residential consumers are investing in advanced air conditioning and ventilation systems to improve comfort, air filtration, and humidity control. In commercial environments, such as offices, healthcare facilities, and hospitality spaces, HVAC systems play a critical role in maintaining healthy indoor conditions and ensuring occupant productivity. Industrial facilities also rely on precise temperature and airflow control to protect equipment and maintain operational stability. Increased adoption of air handlers, advanced filtration technologies, and controlled ventilation systems reflects this growing emphasis. As expectations for indoor comfort continue to rise, HVAC systems are becoming essential infrastructure rather than optional building components.
Key Trend & Opportunity
Integration of Smart and Connected HVAC Technologies
The integration of smart and connected technologies presents a major growth opportunity for the HVAC system market. Building owners increasingly adopt HVAC systems embedded with sensors, automation controls, and data analytics to enable real-time monitoring and optimized performance. Smart HVAC solutions allow predictive maintenance, energy usage optimization, and remote system management, significantly reducing downtime and operating costs. Commercial buildings and large facilities are integrating HVAC systems with building management platforms to improve efficiency and occupant comfort. This trend is also expanding into the residential sector through smart thermostats and app-based controls. As digitalization of buildings accelerates, connected HVAC systems are emerging as a key differentiator for manufacturers and service providers.
- For instance, Johnson Controls’ OpenBlue digital platform connects chillers, air handlers, and controls across large facilities, with deployed systems capable of processing more than 10 million data points per day from sensors monitoring temperature, pressure, vibration, and energy consumption.
Expansion of Heat Pump and Low-Carbon HVAC Solutions
Heat pumps and low-carbon HVAC solutions represent a strong growth opportunity as decarbonization initiatives gain momentum. Governments are actively promoting electrification of heating systems to reduce reliance on fossil fuels, driving adoption of air-source and ground-source heat pumps. These systems provide both heating and cooling, improving energy efficiency and reducing lifecycle emissions. Commercial buildings and multi-family residential projects are increasingly incorporating heat pumps to meet sustainability benchmarks. Manufacturers are investing in advanced compressor technologies and refrigerants to enhance performance in diverse climates. The transition toward low-carbon HVAC solutions is opening new opportunities across both retrofit and new construction markets.
- For instance, Panasonic’s Aquarea series integrates inverter-driven compressors capable of modulating output from 20 % to full load, supporting precise thermal control in varying demand conditions.
Key Challenge
High Initial Costs and Complex Installation
High upfront costs and complex installation requirements remain a significant challenge for the HVAC system market. Advanced HVAC systems, particularly high-efficiency units and smart-enabled solutions, require substantial capital investment, which can deter cost-sensitive residential and small commercial buyers. Installation complexity increases in retrofit projects, where existing building layouts and infrastructure limitations can raise labor and modification costs. Large centralized systems also demand specialized technical expertise, extending project timelines and increasing overall expenses. These cost and complexity factors can slow adoption, particularly in price-competitive markets. Overcoming this challenge requires cost optimization, modular system designs, and improved installer training.
Regulatory Compliance and Refrigerant Transition Pressures
Evolving regulatory frameworks and refrigerant transition requirements pose ongoing challenges for HVAC manufacturers and end users. Compliance with energy efficiency standards, emissions limits, and refrigerant phase-down policies increases product development costs and operational complexity. Manufacturers must continually redesign systems to accommodate low-global-warming-potential refrigerants while maintaining safety and performance. End users face uncertainty during transitions, particularly when retrofitting older systems to meet new regulations. These regulatory pressures can disrupt supply chains and delay purchasing decisions. Successfully navigating this challenge requires continuous innovation, regulatory alignment, and effective communication across the HVAC value chain.
Regional Analysis
North America:
North America accounts for approximately 28% of the global HVAC system market, driven by strong replacement demand, stringent energy efficiency regulations, and widespread adoption of advanced HVAC technologies. The U.S. dominates regional demand due to large residential housing stock, extensive commercial infrastructure, and ongoing upgrades to energy-efficient and smart HVAC systems. Growth is supported by regulatory mandates promoting high-efficiency heating, ventilation, and air conditioning solutions, particularly heat pumps and low-emission systems. Commercial buildings, healthcare facilities, and data centers continue to invest heavily in modern HVAC installations to optimize energy performance and indoor air quality.
Europe:
Europe represents around 24% of the global HVAC system market, supported by aggressive decarbonization policies and strict building energy performance standards. Demand is primarily driven by retrofit and replacement activities as governments push for reduced carbon emissions in residential and commercial buildings. Heat pumps dominate new installations, particularly in Northern and Western Europe, as countries accelerate the transition away from fossil-fuel-based heating. Commercial buildings, public infrastructure, and multi-family housing projects increasingly deploy energy-efficient HVAC systems to meet sustainability targets. Regulatory incentives and green building certifications continue to reinforce steady regional market growth.
Asia-Pacific:
Asia-Pacific is the largest regional market, holding approximately 34% share of the global HVAC system market, fueled by rapid urbanization, population growth, and expanding construction activity. China, India, and Southeast Asian countries drive demand through large-scale residential and commercial developments. Rising disposable incomes and increasing penetration of air conditioning systems significantly support market expansion. Commercial infrastructure projects, including offices, retail complexes, transportation hubs, and industrial facilities, further strengthen demand. The region also benefits from growing manufacturing capacity and increasing adoption of energy-efficient HVAC technologies to manage rising energy consumption and cooling requirements.
Latin America:
Latin America accounts for about 8% of the global HVAC system market, with growth supported by urban development and increasing adoption of air conditioning systems in residential and commercial buildings. Brazil and Mexico are the key contributors, driven by expanding commercial real estate, hospitality, and retail sectors. Rising temperatures and improved living standards are encouraging HVAC installations in both new construction and retrofit projects. Although price sensitivity remains a constraint, demand for energy-efficient and durable HVAC solutions is gradually increasing. Industrial facilities also contribute to regional demand, particularly in manufacturing and food processing sectors.
Middle East & Africa:
The Middle East & Africa region holds approximately 6% of the global HVAC system market, driven primarily by extreme climatic conditions and large-scale infrastructure projects. High cooling requirements in Gulf countries support strong demand for air conditioning systems in residential, commercial, and industrial buildings. Mega projects, including airports, stadiums, hotels, and smart cities, significantly contribute to HVAC installations. In Africa, gradual urbanization and commercial development support moderate growth. Energy efficiency regulations and investments in district cooling systems are increasingly shaping HVAC adoption across the region.
HVAC System Market Segmentations:
By Product Type
- Heating Equipment
- Furnaces
- Boilers
- Heat Pumps
- Ventilation Equipment
- Air Handlers
- Ductwork
- Fans
- Air Conditioning Equipment
- Chillers
- Cooling Towers
By End Use
- Residential
- Commercial
- Industrial
By Installation
- New Construction
- Replacement / Retrofit
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The HVAC system market features a highly competitive landscape characterized by the presence of global multinational manufacturers and strong regional players competing on technology, efficiency, product breadth, and service capabilities. Leading companies focus on expanding energy-efficient and low-carbon HVAC portfolios, particularly in heat pumps, high-performance chillers, and advanced air handling systems, to align with evolving regulatory standards. Strategic initiatives such as product innovation, geographic expansion, mergers and acquisitions, and long-term service agreements are widely adopted to strengthen market positioning. Manufacturers are increasingly integrating digital controls, smart monitoring, and predictive maintenance features to differentiate offerings and enhance lifecycle value. The competitive environment is further shaped by investments in manufacturing capacity, localization strategies, and partnerships with construction firms and energy service providers. As sustainability and building automation gain prominence, competition continues to intensify around system efficiency, reliability, and total cost of ownership.
Key Player Analysis
- Daikin Industries
- Carrier
- Johnson Controls
- LG Electronics
- Bosch
- Danfoss
- Haier
- GREE Electric Appliances
- Lennox International
- Hisense HVAC Equipment
Recent Developments
- In 9 December 2025, Daikin Applied announced it is investing $163 million in a 71,000-square-foot advanced R&D test laboratory in Plymouth, Minnesota, to accelerate development of next-generation cooling technologies for data centers and traditional HVAC markets.
- In early December 2025, Carrier Japan announced plans to showcase its newest HVAC technologies at HVAC&R JAPAN 2026, underlining continued product innovation pipelines for the Japanese market.
Report Coverage
The research report offers an in-depth analysis based on Product type, End-Use, Installation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the HVAC system, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the HVAC system projected to grow between 2024 and 2032?
Which HVAC system segment held the largest share in 2024?
What are the primary factors fueling the growth of the HVAC system market?
Who are the leading companies in the HVAC system market?
Which region commanded the largest share of the HVAC system market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 HVAC System Market Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global HVAC System Market Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 165,873 million → 2032: USD 254,562.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 HVAC System Market Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. HVAC System Market Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 HVAC System Market Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 HVAC System Market Market Drivers
- 3.3 HVAC System Market Market Restraints & Challenges
- 3.4 HVAC System Market Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 HVAC System Market Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 HVAC System Market Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, HVAC System Market category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 HVAC System Market Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. HVAC System Market Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the HVAC System Market market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 HVAC System Market Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 HVAC System Market Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 HVAC System Market Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in HVAC System Market (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New HVAC System Market Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global HVAC System Market Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America HVAC System Market Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe HVAC System Market Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific HVAC System Market Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America HVAC System Market Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East HVAC System Market Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa HVAC System Market Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. HVAC System Market Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
