
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Marine Navigational Aids Market Size 2024 | USD 5,915.2 million |
| Marine Navigational Aids Market, CAGR | 6.4% |
| Marine Navigational Aids Market Size 2032 | USD 9,716.3 million |
Market Overview:
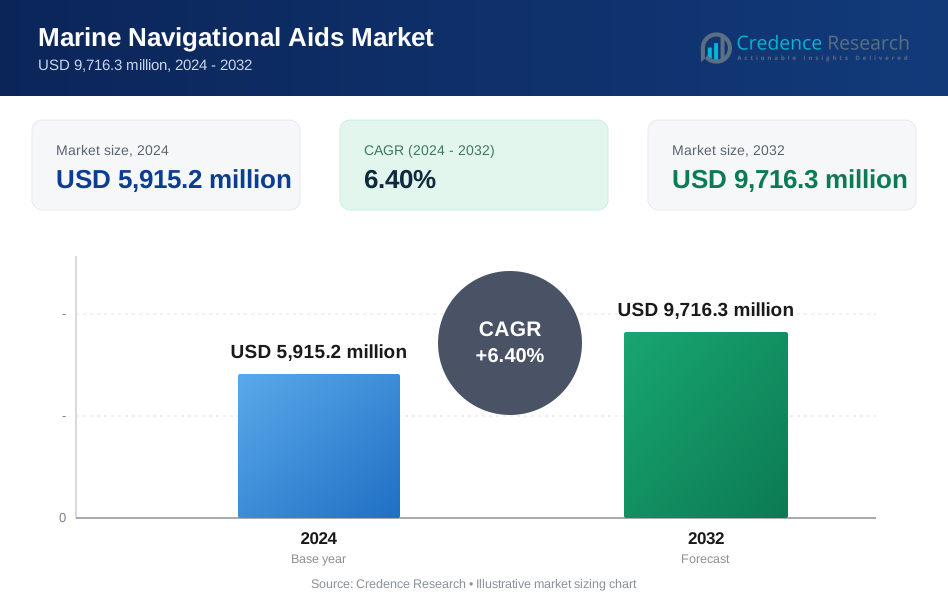
The Marine Navigational Aids (NAVAID) Market is projected to grow from USD 5,915.2 million in 2024 to USD 9,716.3 million by 2032, at a compound annual growth rate (CAGR) of 6.4%.
The Marine Navigational Aids (NAVAID) market is driven by the rising demand for safer and more efficient maritime operations, especially in commercial shipping, offshore energy exploration, and naval defense. Increasing global trade volumes have led to heightened investments in port infrastructure and advanced navigation systems, including buoys, lighthouses, and electronic aids. Regulatory mandates from international maritime authorities further support the adoption of sophisticated NAVAID technologies to minimize maritime accidents and enhance route precision. Additionally, the integration of digital and satellite-based systems, such as AIS (Automatic Identification Systems) and GPS-enabled aids, reflects a key trend transforming traditional navigation. Emerging smart port initiatives and the modernization of aging maritime infrastructure are fueling product innovation and deployment. Growing emphasis on sustainability is also encouraging the development of solar-powered and eco-friendly navigational aids. Together, these drivers and trends are propelling steady market growth and reinforcing the critical role of NAVAIDs in ensuring maritime safety and operational efficiency across global waters.
The Marine Navigational Aids (NAVAID) market is witnessing significant growth across all key regions, including North America, Europe, Asia-Pacific, Middle East and Africa, and Latin America. North America and Europe are well-established markets, driven by advanced infrastructure and stringent safety regulations. Asia-Pacific leads in market share, with rapid port development and growing maritime trade. The Middle East and Africa are experiencing growth due to investments in offshore and port infrastructure, while Latin America is seeing steady adoption driven by modernization projects in key ports like Brazil and Mexico. Leading players such as Furuno Electric Co., Ltd., Thales Group, Kongsberg Gruppen ASA, Garmin Ltd., and Raytheon Technologies Corporation are capitalizing on opportunities in these regions, offering innovative NAVAID solutions tailored to regional needs and regulatory standards.
Market Insights:
- The Marine Navigational Aids (NAVAID) market is projected to grow from USD 5,915.2 million in 2024 to USD 9,716.3 million by 2032, at a CAGR of 6.4%.
- Rising global maritime trade is increasing demand for advanced NAVAID systems to ensure safe and efficient navigation across busy shipping routes.
- Technological advancements, including digital tools like GPS, AIS, and remote monitoring, are transforming traditional navigation aids into smarter, more efficient systems.
- Regulatory mandates from international maritime bodies are driving the adoption of certified, high-performance NAVAID technologies to enhance maritime safety.
- Significant investments in port infrastructure and maritime security are fueling demand for modernized navigational aids worldwide.
- The integration of sustainability efforts, such as solar-powered and eco-friendly navigational aids, aligns with growing environmental concerns in the industry.
- The global NAVAID market is characterized by regional growth, with Asia-Pacific holding the largest market share of 27% in 2024, followed by North America (22%), Europe (21%), Latin America (16%), and Middle East and Africa (14%).
Market Drivers:
Rising Maritime Trade and Global Shipping Activities:
The continuous expansion of global maritime trade is significantly driving the growth of the Marine Navigational Aids (NAVAID) market. As international shipping volumes increase, the need for accurate, reliable, and safe navigation becomes paramount. Ports and shipping companies are investing heavily in advanced navigational infrastructure to accommodate larger vessels and manage increasingly complex maritime traffic. For instance, Sealite Pty Ltd, a key industry player, supplies advanced solar-powered marine buoys and lighting systems to ports worldwide, supporting safer navigation and promoting sustainable maritime operations. This surge in demand for improved navigational systems is encouraging the development and deployment of innovative NAVAID solutions that ensure smooth and secure vessel movement across busy sea routes.
Advancements in Technology and Digital Integratio:
Technological innovation plays a vital role in propelling the NAVAID market forward. The integration of digital tools such as GPS, AIS (Automatic Identification Systems), and remote monitoring platforms is transforming traditional navigation aids into smarter, more efficient systems. These advancements enable real-time data transmission, enhanced tracking accuracy, and improved decision-making for maritime operators. Modern NAVAID solutions are increasingly incorporating automation and IoT capabilities, which facilitate predictive maintenance and operational efficiency, thereby reducing downtime and operational risks.
Stringent Regulatory Frameworks and Safety Mandates:
Compliance with international maritime safety regulations is another key driver shaping the NAVAID market. Regulatory bodies such as the International Maritime Organization (IMO) and national authorities mandate the use of specific navigational aids to prevent maritime accidents and ensure environmental protection. For instance, in 2024, the IMO’s Maritime Safety Committee adopted new SOLAS regulations requiring shipboard lifting appliances and anchor handling winches to meet stringent safety standards, compelling operators to upgrade equipment to remain compliant. As enforcement becomes more stringent, port authorities and ship operators are compelled to upgrade existing systems or invest in new solutions that meet regulatory standards. This regulatory environment reinforces the market demand for certified, high-performance navigational aids across commercial and defense sectors.
Infrastructure Development and Modernization Initiatives:
Ongoing infrastructure development projects and modernization efforts are accelerating the adoption of advanced marine navigational aids worldwide. Coastal nations are prioritizing the enhancement of port facilities and maritime infrastructure to support economic growth and maritime security. As part of these initiatives, substantial investments are being directed toward upgrading navigational equipment, replacing outdated systems, and deploying sustainable, energy-efficient solutions. This trend is expected to sustain market momentum and create new opportunities for manufacturers and service providers in the coming years.
Market Trends:
Integration of Smart and Digital Technologies:
The Marine Navigational Aids (NAVAID) market is experiencing a shift toward smart technologies that enhance navigational efficiency and accuracy. The incorporation of digital systems such as AIS, GPS, and VHF Data Exchange Systems (VDES) has become increasingly prevalent. These technologies enable real-time communication, vessel tracking, and data analytics, allowing for more informed decision-making and safer maritime operations. For instance, Sternula is conducting a global demonstration of the VHF Data Exchange System (VDES), an upgrade to AIS technology, enabling two-way data communication over VHF and satellite channels; this allows ships to access services like real-time ice charts and environmental monitoring from anywhere with a VHF antenna. As a result, traditional aids to navigation are being modernized with digital interfaces and remote-control capabilities, reflecting the broader trend of digital transformation across the maritime industry.
Adoption of Renewable and Energy-Efficient Solutions:
Sustainability is becoming a major focus in the NAVAID market, with stakeholders prioritizing the deployment of environmentally friendly systems. Solar-powered buoys, LED-based lighting, and autonomous power sources are gaining traction due to their lower operational costs and minimal environmental impact. For instance, Carmanah Technologies Corporation has deployed autonomous, solar-powered marine lanterns for offshore wind farm marking, providing reliable operation with zero carbon emissions and minimal maintenance requirements. These sustainable options not only reduce carbon emissions but also offer improved reliability and extended service life, particularly in remote and offshore locations. This trend aligns with global initiatives aimed at reducing the maritime sector's ecological footprint.
Expansion of Coastal Surveillance and Defense Infrastructure:
Governments and defense organizations are increasingly investing in coastal monitoring and navigational systems to enhance maritime security. Navigational aids are being integrated into broader coastal surveillance networks to support strategic operations, monitor illegal activities, and secure territorial waters. The rising importance of maritime domain awareness is contributing to the demand for robust and advanced NAVAID systems that can operate effectively under various environmental and security conditions.
Growth of Smart Port Development Projects:
The global rise of smart port initiatives is influencing the NAVAID market, as ports seek to implement intelligent infrastructure to improve traffic management and logistical efficiency. As part of this transformation, ports are upgrading their navigational systems to support automated docking, remote operations, and seamless integration with port management platforms. This evolution highlights the growing interconnection between navigational aids and broader maritime digital ecosystems.
Market Challenges Analysis:
High Installation and Maintenance Costs:
The Marine Navigational Aids (NAVAID) market faces a significant hurdle in the form of high installation and maintenance costs. Implementing advanced NAVAID systems—such as AIS base stations, radar beacons, and self-powered buoys—requires considerable initial investment. These installations often take place in offshore or remote coastal areas, making the process logistically complex and resource-intensive. Additionally, maintaining these systems in maritime environments presents ongoing challenges due to exposure to saltwater corrosion, extreme weather conditions, and mechanical wear from marine traffic. Specialized equipment and skilled personnel are necessary for inspection, repairs, and upgrades, adding to operational expenses. For many developing nations or small port authorities, limited financial resources restrict the ability to invest in and maintain modern navigational infrastructure. This economic constraint can delay critical upgrades, compromise navigational safety, and inhibit the broader modernization of marine transportation networks. The financial burden remains a substantial barrier to widespread adoption, especially in cost-sensitive regions.
Technological Integration and Interoperability Issues:
Another major challenge in the Marine Navigational Aids (NAVAID) market is the complexity of integrating new technologies with existing maritime systems. Many ports and vessels continue to operate on legacy systems that are incompatible with modern digital and automated NAVAID solutions. As the industry adopts satellite-based tools, remote monitoring capabilities, and advanced data analytics, ensuring interoperability between new and old systems becomes essential. However, this integration process can be difficult and costly, often requiring customized interfaces and extensive system reconfiguration. Furthermore, the lack of universal standards for data formats, communication protocols, and cybersecurity across different regions and manufacturers exacerbates the problem. Vessels operating internationally may face inconsistencies in how NAVAIDs are interpreted and utilized, potentially compromising navigational safety. For instance, Sealite Pty Ltd has introduced solar-powered navigation lights and buoys equipped with IoT-based remote monitoring, yet many ports still need to retrofit or upgrade legacy infrastructure to fully leverage these smart features, which can be costly and complex. These challenges call for collaborative industry efforts to standardize technologies and streamline integration processes. Without such coordination, the full potential of modern NAVAID systems may remain underutilized, hindering progress in global maritime safety and efficiency.
Market Opportunities:
The Marine Navigational Aids (NAVAID) market presents strong growth opportunities fueled by the increasing global emphasis on maritime infrastructure development. Coastal and island nations are investing in the modernization of ports and shipping channels to enhance safety and accommodate rising cargo volumes. These initiatives are opening avenues for the deployment of advanced navigation systems, especially in regions previously underserved by reliable marine infrastructure. Furthermore, as global trade routes expand and Arctic sea lanes become more navigable due to climate change, new maritime corridors are emerging that require comprehensive navigational support. This evolving maritime landscape encourages the adoption of innovative and adaptive NAVAID solutions tailored to unique environmental and operational conditions. Such expansion not only drives demand for physical aids like buoys and lighthouses but also boosts interest in electronic navigation systems and remote monitoring technologies.
Opportunities also stem from the ongoing digital transformation in the maritime industry. The integration of smart technologies such as artificial intelligence, real-time analytics, and the Internet of Things (IoT) into marine navigation systems is revolutionizing the capabilities of NAVAIDs. These advancements allow for predictive maintenance, improved situational awareness, and enhanced decision-making, which are crucial for both commercial shipping and naval operations. Additionally, the growing trend of smart port development provides a platform for deploying connected navigational aids that seamlessly interact with automated port logistics and traffic control systems. Manufacturers and service providers that can offer scalable, interoperable, and data-driven solutions will be well-positioned to capitalize on this trend. As regulatory bodies increasingly mandate digital compliance and environmental sustainability, there is also a significant opportunity to innovate and supply energy-efficient, solar-powered, and environmentally friendly navigational aids. This convergence of infrastructure development, digital innovation, and sustainability creates a favorable environment for long-term market expansion.
Market Segmentation Analysis:
By Product Type:
The Marine Navigational Aids (NAVAID) market comprises a diverse range of products including lighthouses, buoys, beacons, fog signals, daymarks, and other visual or auditory aids. Buoys and beacons dominate due to their widespread use in coastal and offshore navigation. Lighthouses and fog signals remain essential in high-traffic and fog-prone areas.
By Technology:
Technology segmentation divides the market into traditional and electronic systems. Traditional aids continue to play a role in smaller ports and remote areas, while electronic aids are increasingly favored for their precision, automation, and integration capabilities. The shift toward satellite and digital systems drives rapid adoption of electronic NAVAIDs worldwide.
By Application:
Based on application, the market serves both commercial and defense sectors. Commercial shipping demands reliable, cost-efficient navigational aids to support growing trade volumes. Meanwhile, the defense segment emphasizes secure, robust systems for surveillance and strategic operations, fueling investment in high-performance, tamper-resistant navigational technologies.
Segments:
Based on Product Type
- Lighthouses
- Buoys
- Beacons
- Fog Signals
- Daymarks
- Others
Based on Technology
- Traditional
- Electronic
Based on Application
- Commercial
- Defense
Based on End-User
- Ports and Harbors
- Offshore Structures
- Vessels
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds a significant share in the Marine Navigational Aids (NAVAID) market, accounting for 22% of the global market share in 2024. The region benefits from advanced maritime infrastructure, strong regulatory enforcement, and substantial government investments in coastal surveillance and port modernization. The United States, in particular, leads in the adoption of cutting-edge electronic navigation aids, integrating them into commercial shipping and naval defense operations. Ongoing projects to enhance maritime domain awareness and secure strategic sea routes further drive demand for high-performance navigational aids. Canada also contributes to regional growth through investments in Arctic navigation systems and coastal safety programs.
Europe:
Europe stands as a mature and well-established market, contributing 21% of the global market share in 2024. The region benefits from stringent safety regulations mandated by the European Maritime Safety Agency (EMSA) and widespread modernization of ports across EU member states. Countries like Germany, the United Kingdom, France, and the Netherlands are leading adopters of digital NAVAID systems, focusing on energy-efficient and sustainable technologies. Europe’s commitment to green shipping and smart port development has created steady demand for solar-powered and automated navigational aids, reinforcing its strong market presence.
Asia-Pacific:
Asia-Pacific represents the largest regional market, with a market share of 27% in 2024. This growth is driven by rapid maritime trade expansion, infrastructure investments, and the rising importance of regional shipping hubs such as China, Japan, India, and South Korea. Governments in this region are actively modernizing port facilities, deploying electronic navigation systems, and improving coastal monitoring to handle increased cargo volumes and enhance maritime safety. China’s Belt and Road Initiative and its associated seaport development projects play a crucial role in boosting demand for NAVAIDs across Asia-Pacific.
Middle East and Africa:
The Middle East and Africa region accounted for 14% of the Marine Navigational Aids market share in 2024. Growth in this region is supported by investments in offshore oil and gas infrastructure, port development, and maritime safety initiatives. The United Arab Emirates and Saudi Arabia are enhancing coastal surveillance and shipping infrastructure, creating a growing need for advanced navigational aids. African nations are also beginning to invest in basic NAVAID systems to improve maritime trade connectivity and reduce shipping accidents.
Latin America:
Latin America contributed 16% to the global market share in 2024. Regional demand is driven by expanding seaborne trade and modernization of ports in Brazil, Mexico, and Chile. Governments are increasingly prioritizing maritime safety, leading to gradual adoption of both traditional and electronic navigation aids to support their economic and logistical growth.
Key Player Analysis:
- Furuno Electric Co., Ltd.
- Thales Group
- Transas Marine Limited
- Kongsberg Gruppen ASA
- Lockheed Martin Corporation
- Garmin Ltd.
- Saab AB
- Raytheon Technologies Corporation
- Honeywell International Inc.
- Northrop Grumman Corporation
- Japan Radio Co., Ltd.
- Navico Group
Competitive Analysis:
The Marine Navigational Aids (NAVAID) market is highly competitive, with several key players leading innovation and growth. Companies such as Furuno Electric Co., Ltd., Thales Group, Transas Marine Limited, Kongsberg Gruppen ASA, Lockheed Martin Corporation, Garmin Ltd., Saab AB, Raytheon Technologies Corporation, Honeywell International Inc., Northrop Grumman Corporation, Japan Radio Co., Ltd., and Navico Group are at the forefront, offering advanced solutions tailored to maritime safety and operational efficiency. These players differentiate themselves through the development of integrated, smart navigation systems, incorporating cutting-edge technologies such as GPS, AIS, radar, and IoT capabilities. Strategic partnerships, mergers, and acquisitions further bolster their market positions, enabling them to expand product portfolios and penetrate new geographical regions. As competition intensifies, these companies are focusing on R&D to deliver energy-efficient, sustainable solutions, and adhere to increasing regulatory standards for environmental protection. Additionally, customization of products for specific applications and regions ensures continued growth and market dominance in the NAVAID sector.
Recent Developments:
- In February 2024, Furuno Italia launched the new Furuno Integrated Control System for mid-sized super yachts, featuring advanced, user-friendly integration of navigation and vessel control, including the new NAVpilot-1000 autopilot.
- In December 2024, Thales delivered the first serial production system of mine countermeasure drones to the French Navy, marking a world-first in operational deployment of such autonomous systems.
- In 2024, Transas delivered new simulation systems, including the Navi-Trainer Professional 5000, to various clients, supporting onboard and shore-based training environments with realistic NAVAID and eco-driving modules for fuel and emissions optimization.
- In January 2025, Kongsberg announced the integration of Kongsberg Digital’s maritime business into Kongsberg Maritime, consolidating digital maritime solutions for improved decarbonization and digitalization of the marine industry.
Market Concentration & Characteristics:
The Marine Navigational Aids (NAVAID) market exhibits moderate concentration, with a mix of well-established global players and emerging regional companies. Leading companies such as Furuno Electric Co., Ltd., Thales Group, Kongsberg Gruppen ASA, and Garmin Ltd. dominate the market, leveraging their extensive expertise and technological advancements to drive innovation in navigation systems. These companies focus on offering a diverse range of products, including radar, GPS-based aids, and automated monitoring systems, often tailored to specific maritime applications such as commercial shipping, defense, and offshore energy exploration. Market characteristics are marked by significant investment in R&D, particularly in integrating digital and satellite-based systems for enhanced accuracy and operational efficiency. Companies are also focusing on sustainable solutions, incorporating eco-friendly and energy-efficient products in response to growing environmental concerns. The competitive landscape is further shaped by strategic partnerships, mergers, and acquisitions, which enable players to expand their regional presence and enhance product offerings.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Technology, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for Marine Navigational Aids (NAVAID) will continue to rise with the expansion of global maritime trade and increasing shipping traffic.
- Technological advancements, particularly in satellite-based navigation and automation, will drive innovation and efficiency in NAVAID systems.
- Growing focus on environmental sustainability will lead to the development and adoption of energy-efficient and solar-powered navigational aids.
- The modernization of aging maritime infrastructure will create new opportunities for the deployment of advanced NAVAID systems worldwide.
- The integration of IoT and AI technologies will enhance predictive maintenance, operational efficiency, and real-time monitoring in NAVAID solutions.
- Regulatory pressures from international maritime authorities will encourage the adoption of high-performance, compliant NAVAID technologies across sectors.
- As regional shipping hubs expand, demand for tailored navigational aids will increase, particularly in emerging markets in Asia-Pacific and Latin America.
- Increased investments in offshore energy exploration and port infrastructure development will further propel market growth.
- Strategic partnerships, acquisitions, and collaborations between NAVAID manufacturers and port operators will shape the competitive landscape.
- The ongoing shift towards digitalization will push the integration of smart port technologies, which will further boost the demand for sophisticated NAVAID systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Marine Navigational Aids (NAVAID) Market?
What factors are driving the growth of the Marine Navigational Aids (NAVAID) Market?
What are some challenges faced by the Marine Navigational Aids (NAVAID) Market?
Who are the major players in the Marine Navigational Aids (NAVAID) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Marine Navigational Aids Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Marine Navigational Aids Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,915.2 million → 2032: USD 9,716.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Marine Navigational Aids Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Marine Navigational Aids Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Marine Navigational Aids Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Marine Navigational Aids Market Drivers
- 3.3 Marine Navigational Aids Market Restraints & Challenges
- 3.4 Marine Navigational Aids Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Marine Navigational Aids Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Marine Navigational Aids Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Marine Navigational Aids category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Marine Navigational Aids Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Marine Navigational Aids Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Marine Navigational Aids market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Marine Navigational Aids Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Marine Navigational Aids Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Marine Navigational Aids Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Marine Navigational Aids (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Marine Navigational Aids Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Marine Navigational Aids Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Marine Navigational Aids Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Marine Navigational Aids Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Marine Navigational Aids Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Marine Navigational Aids Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Marine Navigational Aids Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Marine Navigational Aids Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Marine Navigational Aids Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
