
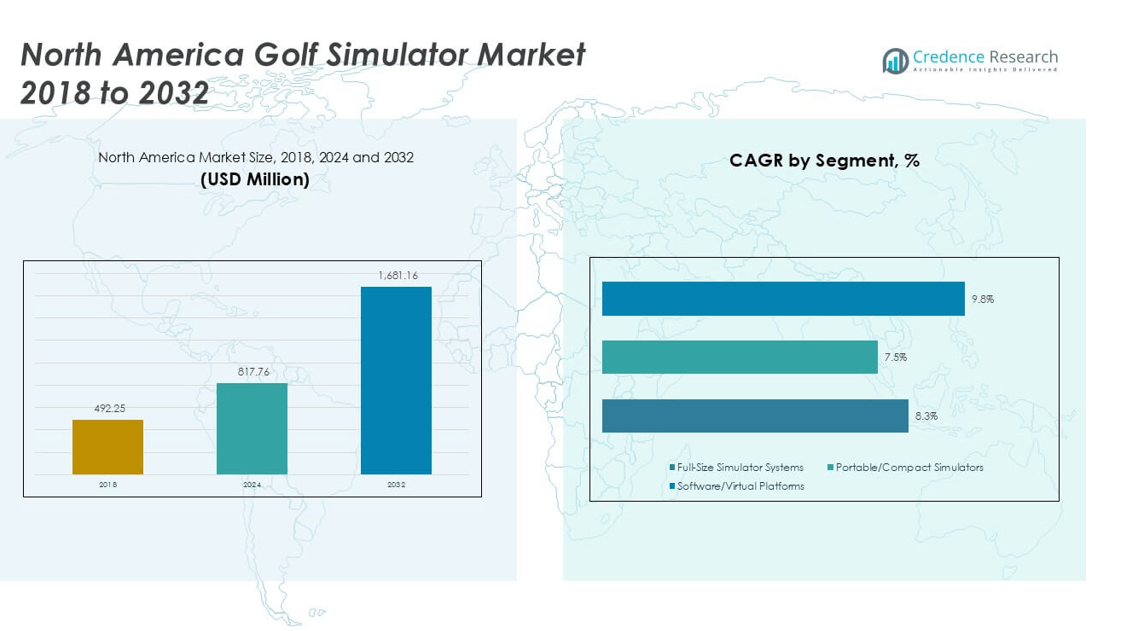
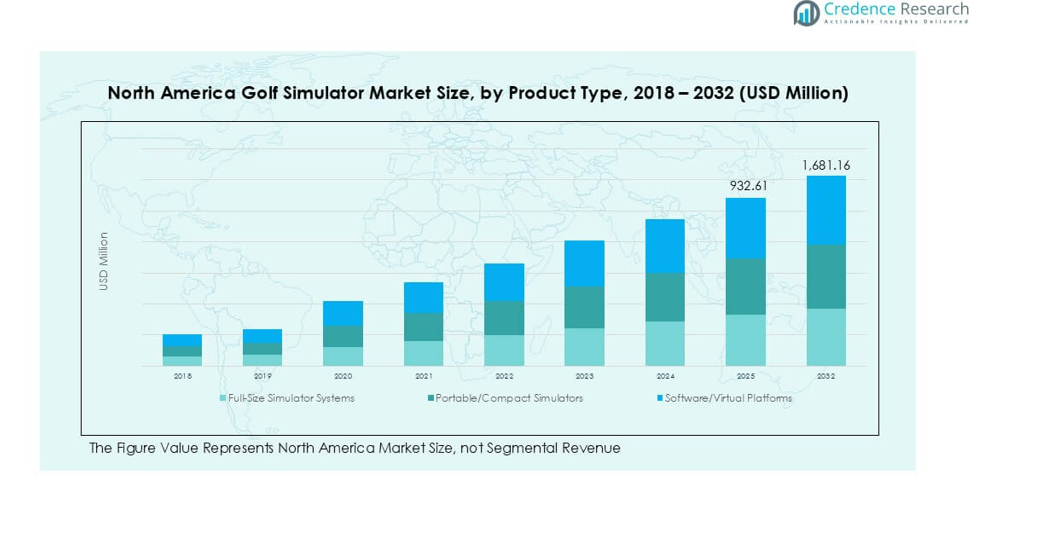
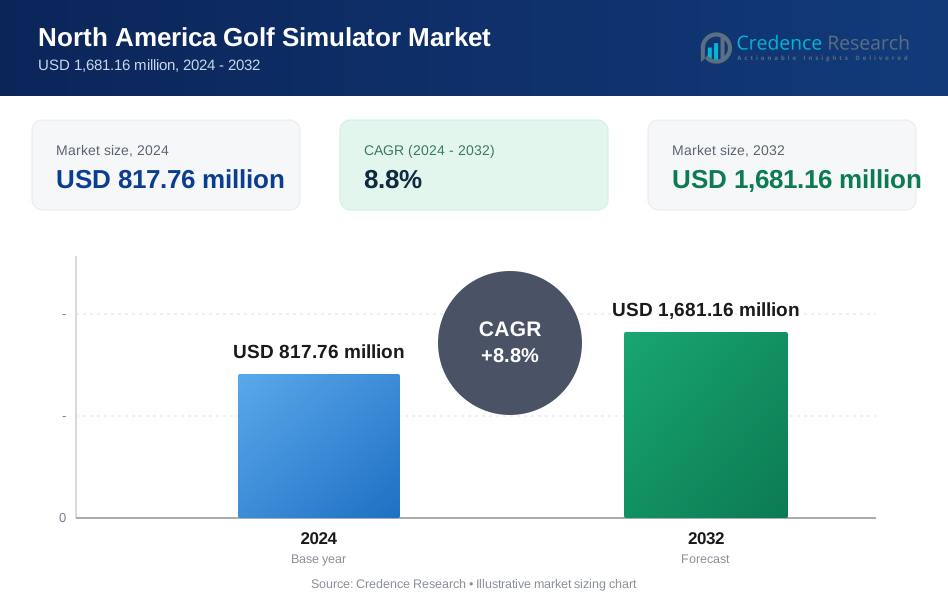
The North America golf simulator market was valued at USD 492.25 million in 2018 and reached USD 817.76 million in 2024. It is projected to reach USD 1,681.16 million by 2032, growing at a CAGR of 8.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Golf Simulator Market Size 2024 | USD 817.76 million |
| North America Golf Simulator Market, CAGR | 8.8% |
| North America Golf Simulator Market Size 2032 | USD 1,681.16 million |
The North America golf simulator market is led by key players including Foresight Sports, Full Swing Golf, TruGolf, SkyTrak, OptiShot Golf, and Golfzon, which collectively hold over 60% market share in 2024. These companies dominate through advanced tracking technologies, realistic simulation software, and strong distribution networks. Foresight Sports leads with camera-based precision systems, while Full Swing Golf excels in commercial entertainment installations. TruGolf and SkyTrak focus on affordable, portable solutions catering to home users. The United States accounts for over 70% of regional revenue, driven by strong golf participation rates, commercial simulator adoption, and rising demand for indoor training facilities.
Market Insights
- The North America golf simulator market was valued at USD 817.76 million in 2024 and is projected to reach USD 1,681.16 million by 2032, growing at a CAGR of 8.8%.
- Rising demand for indoor golfing, technological innovations in swing tracking, and growth of commercial golf entertainment venues are key drivers boosting market expansion.
- Trends include the adoption of camera-based and hybrid tracking technologies, VR integration, and increasing home simulator installations supported by portable and affordable solutions.
- The market is moderately consolidated, with Foresight Sports, Full Swing Golf, TruGolf, SkyTrak, and Golfzon holding over 60% share and competing on accuracy, content, and pricing.
- United States leads with over 70% market share, followed by Canada with 20% and Mexico with 10%; full-size simulator systems dominate product segments, accounting for more than 50% of total installations across residential and commercial applications.
Market Segmentation Analysis:
By Product Type
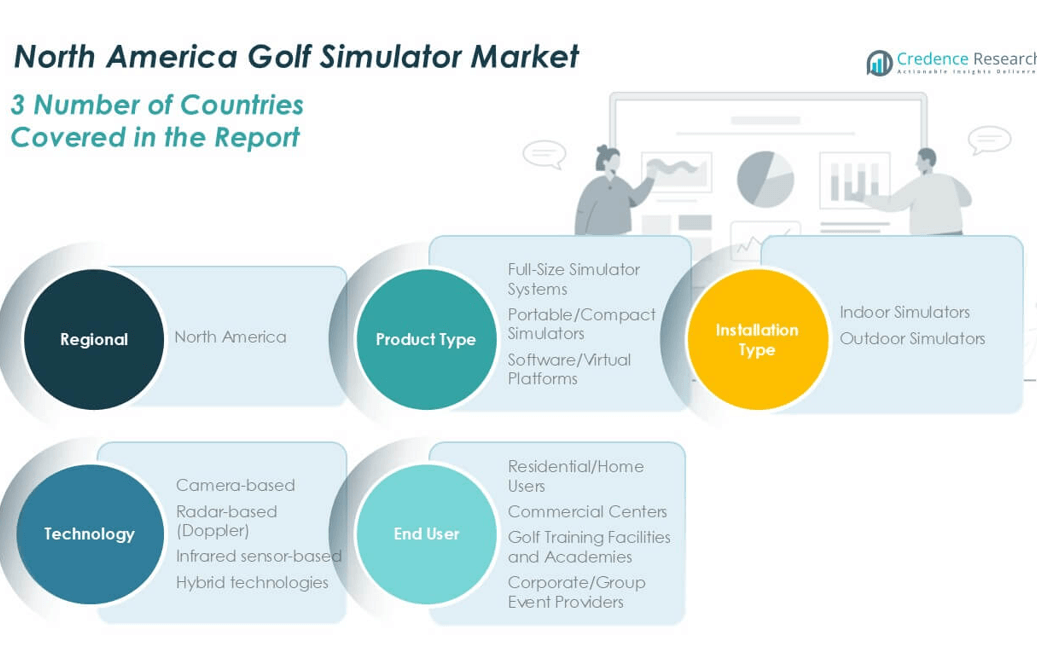
Full-size simulator systems dominated the North America golf simulator market in 2024, capturing over 50% market share. These systems are favored by commercial venues, training academies, and premium home users for their realistic experience and advanced features. They offer large hitting screens, multi-course libraries, and accurate swing analytics, which appeal to professional and enthusiast golfers. Growth is supported by rising adoption in indoor golf clubs, corporate entertainment centers, and luxury residences. Portable simulators and software platforms are gaining traction among casual golfers seeking affordable, space-saving, and subscription-based practice solutions.
- For instance, TrackMan’s simulator system supports over 300 virtual courses and measures more than 40 club and ball data points per swing with sub-1° accuracy.
By Installation Type I
ndoor simulators accounted for more than 65% of installations in 2024, making them the leading segment. The popularity of indoor setups is driven by weather independence, which allows year-round practice, especially in colder regions of North America. Indoor simulators are widely adopted in commercial facilities, fitness clubs, and residential basements. Technological upgrades such as high-speed projectors, realistic turf, and interactive multiplayer modes further boost demand. Outdoor simulators remain a niche choice, used mainly in golf resorts and driving ranges, but face limitations due to weather sensitivity and space requirements.
- For instance, Five Iron Golf has rapidly expanded to at least 32 locations across 13 U.S. states, with additional international facilities. While the number of simulator bays varies by location (some have 6–10, others have more, such as 17 at a Dubai venue), each facility is capable of hosting a large number of players daily.
By Technology
Camera-based technology led the market with over 45% share in 2024, driven by its superior swing and ball-tracking accuracy. High-speed cameras capture clubface angle, spin rate, and launch angle, making them ideal for professional training and coaching centers. Radar-based (Doppler) systems are growing quickly, favored for outdoor use due to their ability to track ball flight over longer distances. Infrared sensor-based systems remain a cost-effective option for recreational users, while hybrid technologies combining multiple tracking methods are emerging to deliver ultra-realistic simulations and improved precision for competitive players.
Market Overview
Rising Popularity of Indoor Golf and Year-Round Play
The increasing demand for indoor golfing experiences is a major driver of the North America golf simulator market. Consumers are seeking entertainment options that are not limited by weather or seasonal constraints, particularly in regions with long winters such as Canada and the northern United States. Golf simulators provide a controlled, climate-independent environment, allowing players to practice and enjoy the game year-round. Commercial adoption is rising in sports bars, hotels, and training facilities offering immersive experiences. Residential installations are also gaining momentum, supported by rising disposable income and home entertainment investments. This trend is reinforced by younger demographics who prefer technology-integrated recreational activities, combining virtual sports with social interaction.
- For instance, X-Golf has expanded to more than 100 simulator venues in the U.S., each venue equipped with auto-tee systems and advanced swing analysis to support league play.
Technological Advancements in Tracking and Simulation
Rapid improvements in tracking technology are enhancing realism and driving adoption of golf simulators. High-speed camera systems, radar-based Doppler tracking, and hybrid solutions now provide precise swing data, ball speed, and shot trajectory analytics, making simulators highly effective for professional training. Software enhancements, including 4K graphics, virtual course libraries, and multiplayer options, improve engagement and replay value. AI-driven analytics allow players to receive detailed feedback for performance improvement, which attracts golf academies and coaches. Integration with smartphones and cloud platforms enables players to track progress over time and compete remotely. As accuracy and immersion levels approach real-course conditions, more golfers view simulators as a legitimate practice tool rather than just entertainment, expanding the addressable market.
- For instance, Foresight Sports’ GCQuad captures 10,000 frames per second and provides ±0.5 mph ball speed accuracy, used by PGA Tour professionals for training.
Growth of Commercial Entertainment and Training Facilities
The expansion of commercial indoor golf venues and entertainment centers is fueling market growth. Businesses like Topgolf Swing Suite, Five Iron Golf, and simulator-based lounges are bringing golf to urban settings, targeting casual players and corporate groups. These facilities combine golf simulators with food, beverages, and social experiences, making golf accessible to a broader audience. Training academies and country clubs are investing in simulators for off-season coaching, junior programs, and club-fitting services. This commercial adoption drives high-value purchases of full-size systems and subscriptions for course content updates. The rising focus on experiential leisure activities and corporate team-building events supports continued investment, strengthening simulator demand across metropolitan areas in North America.
Key Trend & Opportunity
Integration with Virtual Reality and Gamification
A major trend in the market is the integration of virtual reality (VR) and gamified features into golf simulators. VR headsets and immersive projection systems are creating a 360-degree playing experience, making practice more engaging. Gamification elements, such as skill challenges, leaderboards, and multiplayer tournaments, attract younger users and casual players who seek competitive entertainment. Developers are also offering subscription-based content updates, allowing players to access new virtual courses and mini-games regularly. This model creates recurring revenue for manufacturers and operators. As e-sports and digital competitions grow, VR-enabled golf events could create new sponsorship and streaming opportunities, expanding the market beyond traditional golf enthusiasts.
- For instance, Full Swing Golf has previously hosted online seasonal league competitions with prize pools and real-time leaderboards, though participation numbers were significantly lower than 2,000 per event.
Rising Adoption in Home Installations
Home installations represent a growing opportunity, driven by advancements in compact, portable, and affordable simulators. Consumers are converting garages, basements, and spare rooms into practice spaces, supported by DIY installation kits and user-friendly software. The COVID-19 pandemic accelerated the trend toward home entertainment investments, and the momentum continues as households seek private, convenient ways to stay active. Manufacturers are offering entry-level models with flexible pricing, attracting hobbyists and beginners. Integration with smart home devices and fitness tracking apps further enhances appeal. This segment also opens opportunities for subscription-based coaching platforms, virtual competitions, and personalized improvement plans, creating long-term customer engagement.
Key Challenge
High Initial Cost of Advanced Simulator Systems
One of the primary barriers to market growth is the high cost of full-size golf simulator setups. Premium systems with advanced sensors, high-speed cameras, and 4K projectors can cost tens of thousands of dollars, limiting adoption to commercial facilities and high-income households. Even mid-range solutions may be out of reach for casual golfers, slowing mass-market penetration. Financing options and subscription-based models are helping reduce upfront costs, but affordability remains a critical challenge for widespread adoption. Price sensitivity is especially relevant in residential markets, where buyers compare simulator investment with other leisure or fitness equipment.
Space Requirements and Installation Complexity
Golf simulators often require significant space for proper installation, including ceiling height, hitting area, and projection distance. This creates a challenge for urban apartments or smaller homes where space is limited. Installation can also be complex, requiring professional setup to ensure accurate calibration and safety, which adds to the total cost. Portable and compact simulators are emerging as a solution, but they may compromise accuracy or immersion. Overcoming this challenge will require continued innovation in space-efficient designs, foldable hitting bays, and plug-and-play systems to appeal to a wider customer base.
Regional Analysis
United States The United States dominated the North America golf simulator market in 2024, accounting for over 70% market share. High adoption of full-size simulators in commercial entertainment centers, golf clubs, and luxury residences drives demand. The country benefits from a strong golfing culture, with over 15,000 golf courses and a growing base of recreational players. Rising popularity of indoor golf venues, such as Topgolf Swing Suite and Five Iron Golf, further supports growth. Technological advancements and the availability of premium training facilities are accelerating adoption in both urban and suburban regions, making the U.S. the primary revenue contributor.
Canada Canada held nearly 20% of the market share in 2024, driven by growing demand for year-round golf experiences in regions with extended winters. Indoor simulator installations in residential basements, golf academies, and sports lounges are rising, allowing players to practice despite weather limitations. Canadian golf associations and training facilities are increasingly using simulators for coaching programs and junior golfer development. The market is also seeing growth in portable simulator adoption, catering to casual players. Technological improvements and increasing affordability are expected to boost simulator penetration in both metropolitan areas and smaller towns across Canada in the coming years.
Mexico Mexico accounted for around 10% market share in 2024, representing a smaller but steadily growing segment. Rising disposable incomes and expanding interest in golf among younger demographics are fueling adoption. Luxury resorts and high-end residential communities are key buyers, using simulators to attract visitors and homeowners. Growth is also supported by the development of golf tourism hubs in regions like Los Cabos and Riviera Maya. While the market is still nascent compared to the U.S. and Canada, increasing awareness, new commercial simulator installations, and entry-level product availability are expected to accelerate demand over the forecast period.
Market Segmentations:
By Product Type
- Full-Size Simulator Systems
- Portable/Compact Simulators
- Software/Virtual Platforms
By Installation Type
- Indoor Simulators
- Outdoor Simulators
By Technology
- Camera-based
- Radar-based (Doppler)
- Infrared sensor-based
- Hybrid technologies
By End User
- Residential/Home Users
- Commercial Centers
- Golf Training Facilities and Academies
- Corporate/Group Event Providers
By Geography
- United States
- Canada
- Mexico
Competitive Landscape
The North America golf simulator market is moderately consolidated, with leading players such as Foresight Sports, Full Swing Golf, TruGolf, SkyTrak, and Golfzon holding a combined share of over 60% in 2024. These companies compete on technology innovation, pricing, and course content libraries to attract both commercial and residential customers. Foresight Sports leads with advanced camera-based systems and analytics-driven solutions for professional training, while Full Swing Golf is strong in commercial installations and premium home setups. TruGolf and SkyTrak focus on affordability and portable systems, appealing to hobbyists and casual players. New entrants and software-focused companies are offering subscription models, adding competitive pressure. Strategic partnerships with golf clubs, resorts, and entertainment venues are common, enabling wider customer reach. Continuous R&D investments, integration of AI-driven analytics, and immersive VR experiences are shaping competition, with players focusing on delivering realistic, data-rich, and user-friendly simulator solutions to sustain market share.
Key Player Analysis
- Foresight Sports
- Full Swing Golf
- TruGolf
- SkyTrak
- OptiShot Golf
- Ernest Sports
- Golfzon
- HD Golf
- AboutGolf
- GolfIn
- X-Golf America
Recent Developments
- In May 2025, IdeasLab launched XView AI, a markerless app that provides real-time, offline analysis of the full golf swing by tracking body, shaft, and club movement. This app is available on the iPhone App Store.
- In May 2025, Golf VX, a provider of indoor golf simulators, announced the opening of its newest franchise location, Golf VX Boston. This marks the company’s second U.S. agreement after the launch of Golf VX Arlington Heights in 2024.
- In April 2025, TruGolf and Digital Legends announced a partnership to launch an advanced golf simulator experience. It is built on TruGolf's Apex platform, featuring AI-driven recreations of legendary players such as Ben Hogan. The simulator will enable users to compete with historic golf figures, receive AI-powered coaching, and engage in tournaments on modern courses.
- In February 2025, Canopy, a remote monitoring and management software provider, partnered with Full Swing Golf. This collaboration allows Full Swing’s support and software teams to leverage Canopy’s platform to enhance the performance, reliability, and remote management of their global simulator fleet.
- In November 2024, Smartgolf LLC launched Smartgolf AI Coach, an advanced device aimed at enhancing golf performance through precise skill improvement. The device uses AI to analyze swing metrics such as speed, distance, angle, and direction, providing instant, detailed feedback via a connected app.
- In January 2022, Golfzon Newdin Group announced an expansion with Leadbetter academies to open high-tech indoor golf facilities in the U.S. in 2022.
Report Coverage
The research report offers an in-depth analysis based on Product Type Installation Type, Technology, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily, driven by rising demand for indoor golf facilities.
- Technological advancements will improve simulator accuracy and realism for professional training.
- Camera-based and hybrid technologies will see wider adoption in commercial and residential setups.
- Home installations will expand as portable and affordable systems gain popularity.
- Integration of AI analytics and VR features will enhance user engagement and learning outcomes.
- Commercial entertainment venues will invest more in simulators to attract younger audiences.
- Subscription-based content and virtual tournaments will create recurring revenue opportunities.
- Manufacturers will focus on space-saving and easy-to-install solutions for urban households.
- Competition will intensify as new players offer innovative, low-cost software platforms.
- The United States will continue to dominate regional demand, supported by strong golf culture.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for North America Golf Simulator market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America Golf Simulator market projected to grow between 2025 and 2032?
Which North America Golf Simulator market segment held the largest share in 2024?
What are the primary factors fueling the growth of the North America Golf Simulator market?
Who are the leading companies in the North America Golf Simulator market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 North America Golf Simulator Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global North America Golf Simulator Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 817.76 million → 2032: USD 1,681.16 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 North America Golf Simulator Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. North America Golf Simulator Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 North America Golf Simulator Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 North America Golf Simulator Market Drivers
- 3.3 North America Golf Simulator Market Restraints & Challenges
- 3.4 North America Golf Simulator Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 North America Golf Simulator Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 North America Golf Simulator Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, North America Golf Simulator category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 North America Golf Simulator Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. North America Golf Simulator Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the North America Golf Simulator market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 North America Golf Simulator Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 North America Golf Simulator Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 North America Golf Simulator Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in North America Golf Simulator (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New North America Golf Simulator Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global North America Golf Simulator Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America North America Golf Simulator Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe North America Golf Simulator Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific North America Golf Simulator Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America North America Golf Simulator Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East North America Golf Simulator Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa North America Golf Simulator Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. North America Golf Simulator Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
