
Market Overview:
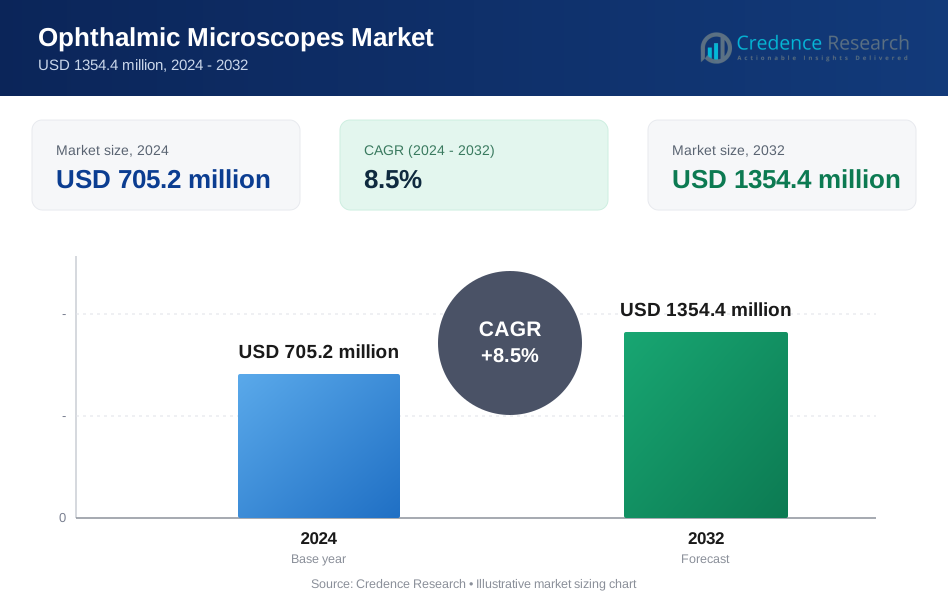
The Ophthalmic Microscopes Market size was valued at USD 705.2 million in 2024 and is anticipated to reach USD 1354.4 million by 2032, at a CAGR of 8.5% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ophthalmic Microscopes Market Size 2024 | USD 705.2 million |
| Ophthalmic Microscopes Market, CAGR | 8.5% |
| Ophthalmic Microscopes Market Size 2032 | USD 1354.4 million |
The ophthalmic microscopes market is witnessing steady growth, supported by the rising prevalence of eye disorders including cataracts, glaucoma, and macular degeneration. Increasing surgical volumes and a growing elderly population are creating consistent demand for advanced ophthalmic surgical solutions. The adoption of minimally invasive procedures and integration of technologies such as 3D imaging, OCT, AI, and augmented reality are further strengthening the market landscape by enhancing surgical precision and patient outcomes. Healthcare providers are prioritizing these solutions to reduce complications and improve recovery, thereby driving continuous investment in innovative microscopy systems.
North America holds the dominant position in the market due to strong healthcare infrastructure, favorable reimbursement frameworks, and the presence of established ophthalmic device manufacturers. The region benefits from early adoption of advanced medical technologies and high patient awareness, which together contribute to widespread usage of ophthalmic microscopes across healthcare facilities. Meanwhile, Asia Pacific is emerging as the fastest-growing region, propelled by increasing surgical outreach in large populations, improving healthcare access, and government support for vision care programs. Growing investment in healthcare infrastructure in countries such as India and China is creating significant opportunities, establishing the region as a key growth hub for ophthalmic microscope adoption.

Market Insights:
- The ophthalmic microscopes market is expected to grow from USD 705.2 million in 2024 to USD 1354.4 million by 2032, driven by rising eye disorder prevalence.
- North America dominates the market with 40% market share, supported by strong healthcare infrastructure and high adoption of advanced technologies.
- Europe holds 30% of the market share, with significant demand fueled by the aging population and continuous technological advancements in surgical procedures.
- Asia-Pacific is the fastest-growing region, accounting for 20% of the market share, driven by healthcare investments and increasing awareness of eye health.
- The growing preference for minimally invasive procedures continues to boost market demand, as ophthalmic microscopes offer essential precision for such surgeries.
- Technological innovations, such as 3D imaging, AI, and optical coherence tomography (OCT), are reshaping the ophthalmic microscopes market, improving surgical accuracy and patient outcomes.
- Regulatory hurdles and high equipment costs are significant challenges, limiting market accessibility, particularly in developing regions.
Market Drivers:
Increasing Prevalence of Eye Disorders
The ophthalmic microscopes market is significantly driven by the rising global prevalence of eye disorders such as cataracts, glaucoma, and macular degeneration. These conditions often require complex and precise surgical interventions, where ophthalmic microscopes play a crucial role. The aging population is particularly vulnerable to such eye diseases, leading to a higher demand for effective diagnostic and surgical solutions. With these conditions affecting millions worldwide, ophthalmic microscopes have become essential for accurate diagnoses and enhanced surgical outcomes.
- For instance, a 36-month real-world study of Sight Sciences’ OMNI Surgical System, involving 230 eyes, demonstrated a significant mean reduction in intraocular pressure of 5.6 to 7.1 mmHg for patients with primary open-angle glaucoma.
Demand for Minimally Invasive Procedures
Minimally invasive surgeries have become increasingly popular due to their numerous benefits, including shorter recovery times, reduced risk of complications, and improved patient satisfaction. Ophthalmic microscopes are a key tool in facilitating these types of surgeries, particularly in ophthalmology, where precision is paramount. With a growing preference for minimally invasive techniques, healthcare providers are investing more in advanced microscopes to enhance surgical accuracy. This trend continues to drive market expansion as it aligns with the overall shift toward less invasive, more effective medical procedures.
- For instance, the American Academy of Ophthalmology’s IRIS Registry, the world's largest comprehensive eye disease database, validates minimally invasive procedures using data from over 79 million unique patients.
Technological Advancements in Ophthalmic Microscopes
Technological innovations are reshaping the ophthalmic microscopes market, with advanced features like 3D imaging, optical coherence tomography (OCT), and artificial intelligence (AI) enhancing surgical precision. These cutting-edge technologies allow surgeons to visualize the surgical site with greater clarity and make more accurate decisions during operations. AI and augmented reality have further refined microscope functionality, enabling better diagnosis and treatment. Such advancements in ophthalmic microscopes continue to elevate their value in medical practices, driving adoption across various regions.
Expanding Healthcare Infrastructure in Developing Regions
Healthcare infrastructure improvements, particularly in emerging economies, are fueling the growth of the ophthalmic microscopes market. As developing regions expand access to healthcare services, including ophthalmic care, the demand for high-quality medical equipment rises. Governments and healthcare organizations in these regions are investing heavily in modernizing facilities, including the acquisition of advanced surgical tools like ophthalmic microscopes. This expansion is creating significant opportunities for market growth, particularly in countries with large populations, such as India and China.
Market Trends:
Adoption of Advanced Digital Technologies
The ophthalmic microscopes market is experiencing a significant shift towards the integration of advanced digital technologies, which are transforming surgical practices. The incorporation of 3D imaging, Optical Coherence Tomography (OCT), and artificial intelligence (AI) has improved the precision of eye surgeries, enabling better visualization and real-time decision-making. These innovations enhance not only the surgical process but also diagnostic capabilities, allowing for earlier detection of eye diseases. The growing adoption of augmented reality in ophthalmology is another trend, offering surgeons a more immersive experience during procedures. These advancements not only improve surgical outcomes but also reduce the risk of complications, contributing to higher patient satisfaction and faster recovery times.
- For instance, Altris AI's platform, which has received FDA 510(k) clearance, can detect over 70 distinct retinal pathologies and biomarkers from OCT scans, and is implemented in more than 500 eye care clinics globally.
Growing Focus on Microscope Portability and User-Friendly Designs
There is a noticeable shift towards making ophthalmic microscopes more portable and user-friendly. With an increasing number of ophthalmologists and surgeons performing procedures in various settings, such as ambulatory surgical centers and smaller clinics, demand for compact and easy-to-use microscopes is growing. These microscopes are designed to offer flexibility without compromising on performance, making them suitable for both complex surgeries and routine check-ups. Simplified controls, ergonomic designs, and wireless connectivity features are increasingly integrated into new models. This trend is opening up opportunities for manufacturers to cater to a broader market, including those in underserved regions with limited access to traditional, bulky equipment. The focus on portability and ease of use is reshaping the landscape of the ophthalmic microscopes market.
- For instance, Prescott's Featherlite surgical microscope is designed for mobile physicians and can be fully disassembled in less than 5 minutes, allowing it to be transported in two provided luggage cases for transit.
Market Challenges Analysis:
High Cost and Accessibility Barriers
One of the key challenges facing the ophthalmic microscopes market is the high cost of advanced equipment, which limits accessibility, especially in developing regions. These microscopes often feature cutting-edge technologies, such as 3D imaging and AI, that drive up production costs. Smaller clinics and healthcare providers may struggle to afford these sophisticated devices, which hampers their adoption in underserved areas. High initial costs, coupled with ongoing maintenance and calibration expenses, make it difficult for many healthcare facilities to upgrade to the latest models. This pricing barrier restricts market penetration and slows the adoption of advanced ophthalmic technologies.
Regulatory and Compliance Issues
The ophthalmic microscopes market also faces challenges related to stringent regulatory requirements and compliance standards. Manufacturers must adhere to complex guidelines set by global health authorities, including the U.S. FDA and the European Medicines Agency, for approval and certification. These regulations can delay product launches and increase development costs. Additionally, maintaining compliance with evolving standards across different regions can be resource-intensive for companies. These regulatory hurdles create challenges for manufacturers, particularly smaller players, in entering new markets and expanding their product reach.
Market Opportunities:
Expansion in Emerging Markets
The ophthalmic microscopes market presents significant growth opportunities in emerging markets, where healthcare infrastructure is rapidly improving. Countries in regions like Asia-Pacific, Latin America, and the Middle East are investing heavily in modernizing their healthcare facilities, driving demand for advanced medical equipment. With increasing healthcare budgets, government initiatives, and growing patient awareness, these regions offer substantial growth potential for ophthalmic microscopes. Manufacturers can tap into these markets by offering affordable, yet advanced, solutions tailored to local needs. Increased urbanization and a rising middle class further boost opportunities, allowing for greater adoption of high-quality medical devices.
Integration of AI and Digital Advancements
Another opportunity for the ophthalmic microscopes market lies in the continued integration of artificial intelligence (AI) and other digital advancements into microscopes. AI-powered systems can help improve diagnostic accuracy and predict surgical outcomes, making them invaluable tools in ophthalmology. Integrating digital technologies such as augmented reality and enhanced imaging techniques into ophthalmic microscopes can provide a competitive edge. These innovations allow for better real-time decision-making during surgeries, improving both patient outcomes and procedural efficiency. As demand for such advanced, data-driven technologies increases, manufacturers who invest in these innovations stand to capture a growing market share.
Market Segmentation Analysis:
By Modality:
The ophthalmic microscopes market is primarily segmented into manual microscopes and digital microscopes. Manual microscopes dominate the market due to their reliability and long-standing presence in surgical environments. However, digital microscopes are gaining traction due to their advanced features, such as 3D imaging, real-time diagnostics, and integration with AI for better decision-making during surgeries. This segment is expected to see robust growth as digital technology becomes more accessible and integrated into ophthalmology practices.
- For instance, the ZEISS ARTEVO 850 digital microscope provides superior color representation by using more than 1 billion colors to display the surgical field on its high-dynamic-range monitor, enabling true-to-life visualization of anatomical details.
By Application:
The market is also categorized based on its application, including cataract surgery, retinal surgery, and other eye surgeries. Cataract surgery holds the largest share of the application segment due to the increasing prevalence of cataracts among aging populations. Retinal surgery is another significant segment, driven by the rising incidence of retinal disorders, including diabetic retinopathy and macular degeneration. The demand for advanced ophthalmic microscopes in these applications is further fueled by the need for precision and enhanced surgical outcomes.
- For instance, Alcon's LuxOR Ophthalmic Microscope, designed for cataract procedures, features patented ILLUMIN-i technology that produces a red reflex zone 6 times larger than that of a traditional microscope, providing surgeons with a more stable and expansive view.
By End-Use:
The end-use segment of the ophthalmic microscopes market includes hospitals, ambulatory surgical centers, and clinics. Hospitals account for the largest market share, supported by high volumes of surgical procedures and the presence of specialized ophthalmology departments. Ambulatory surgical centers are experiencing faster growth, driven by the demand for outpatient surgeries and cost-effective treatment options.
Segmentations:
By Modality:- Manual Microscopes
- Digital Microscopes
- Cataract Surgery
- Retinal Surgery
- Other Eye Surgeries
- Hospitals
- Ambulatory Surgical Centers
- Clinics
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America: Leading Market Share with Advanced Healthcare Systems
North America holds the largest market share in the ophthalmic microscopes market, accounting for 40%. The U.S. and Canada benefit from well-established healthcare systems, high healthcare expenditures, and a strong presence of leading medical device manufacturers. These factors facilitate the adoption of advanced ophthalmic technologies. The aging population further drives demand for precision eye surgeries, including cataract and retinal procedures. Hospitals and ambulatory surgical centers are the primary end-users, contributing to the region's market dominance.
Europe: Strong Demand Driven by Aging Population and Technological Advancements
Europe accounts for 30% of the global ophthalmic microscopes market share, with countries like Germany, the UK, and France leading in adoption. The aging population increases the prevalence of age-related eye diseases, necessitating advanced surgical interventions. Technological advancements, such as 3D imaging and AI integration, enhance surgical precision and outcomes. Robust healthcare infrastructure and favorable reimbursement policies further support market growth.
Asia-Pacific: Rapid Growth with Expanding Healthcare Access
The Asia-Pacific region holds 20% of the global ophthalmic microscopes market share, exhibiting the fastest market growth. Significant healthcare investments in countries like China and India drive this expansion. Rising awareness of eye health and an increasing prevalence of ocular diseases propel the demand for ophthalmic microscopes. Government initiatives and private sector investments contribute to the expansion of surgical centers and clinics, fostering market growth.
Key Player Analysis:
- Alcon, Inc.
- Seiler Instrument Inc.
- Rexxam Co., Ltd.
- haag-streit.com (Metall Zug Group)
- Leica Microsystems (Danaher Corporation)
- Topcon Corporation
- Karl Kaps GmbH & Co. KG
- Carl Zeiss AG
- Inami & CO., Ltd
- Takagi Seiko Co., Ltd.
Competitive Analysis:
The ophthalmic microscopes market is competitive, with several key players leading the industry. Companies such as Alcon, Carl Zeiss Meditec AG, Leica Microsystems (Danaher Corporation), Topcon Corporation, and Haag-Streit Holding are at the forefront, offering advanced ophthalmic surgical microscopes. These companies emphasize innovation by integrating features like 3D imaging, optical coherence tomography (OCT), and artificial intelligence (AI) to improve surgical outcomes. Strategic mergers, acquisitions, and partnerships help expand product portfolios and global reach. For instance, Carl Zeiss Meditec AG’s acquisition of the Dutch Ophthalmic Research Center (D.O.R.C.) strengthened its position in the retinal surgery segment. Leica Microsystems introduced the Proveo 8x, a 3D digital ophthalmic microscope, highlighting the trend toward digital technologies in the market. The competitive dynamics of the ophthalmic microscopes market are influenced by regulatory approvals, reimbursement policies, and healthcare infrastructure developments across regions. To maintain their competitive edge, companies focus on continuous innovation and strategic collaborations.
Recent Developments:
- In August 2025, Alcon announced the acquisition of STAAR Surgical in its second-quarter report.
- In September 2024, Alcon introduced the SMARTCataract DX and NGENUITY 1.5 in Europe at the ESCRS conference, expanding their Vision Suite. These digital innovations offer improved clinic-to-OR connectivity and advanced 3D visualization for cataract surgeries.
- In April 2025, Topcon launched the CR-H1, a handheld reality capture solution that integrates with an iPhone's LiDAR capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Modality, Application, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The ophthalmic microscopes market will see continued adoption of digital technologies, enhancing surgical precision and outcomes.
- Integration of artificial intelligence and augmented reality will drive demand for more advanced, data-driven ophthalmic microscopes.
- Increasing global awareness of eye health will lead to higher demand for ophthalmic surgeries and related equipment.
- Aging populations in developed regions will continue to be a key driver for the growth of the market.
- Emerging markets, particularly in Asia-Pacific, will experience rapid adoption due to expanding healthcare infrastructure.
- The demand for minimally invasive surgeries will further boost the market, with ophthalmic microscopes playing a crucial role in such procedures.
- Advancements in portability and user-friendly designs will expand the adoption of ophthalmic microscopes in smaller healthcare facilities and outpatient centers.
- Growing healthcare investments in developing regions will increase access to advanced ophthalmic technologies.
- The rise in retinal disorders and cataract surgeries will continue to dominate the application segment, ensuring steady market demand.
- Enhanced regulatory frameworks and better reimbursement policies will support market expansion in various global regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ophthalmic Microscopes, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ophthalmic Microscopes market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Ophthalmic Microscopes market?
Who are the leading companies in the Ophthalmic Microscopes market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ophthalmic Microscopes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ophthalmic Microscopes Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 705.2 million → 2032: USD 1354.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ophthalmic Microscopes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ophthalmic Microscopes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ophthalmic Microscopes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ophthalmic Microscopes Market Drivers
- 3.3 Ophthalmic Microscopes Market Restraints & Challenges
- 3.4 Ophthalmic Microscopes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ophthalmic Microscopes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ophthalmic Microscopes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ophthalmic Microscopes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ophthalmic Microscopes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ophthalmic Microscopes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ophthalmic Microscopes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ophthalmic Microscopes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ophthalmic Microscopes Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ophthalmic Microscopes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ophthalmic Microscopes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ophthalmic Microscopes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ophthalmic Microscopes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ophthalmic Microscopes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ophthalmic Microscopes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ophthalmic Microscopes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ophthalmic Microscopes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ophthalmic Microscopes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ophthalmic Microscopes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ophthalmic Microscopes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
