
Market Overview
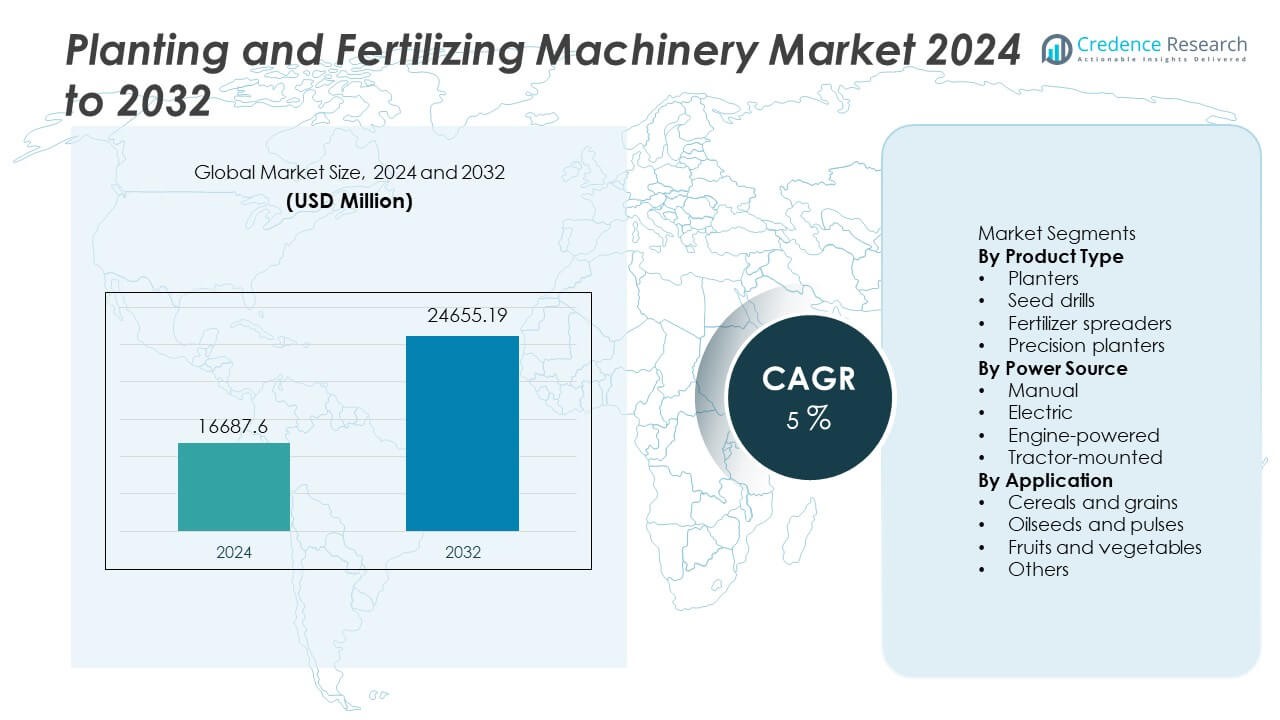
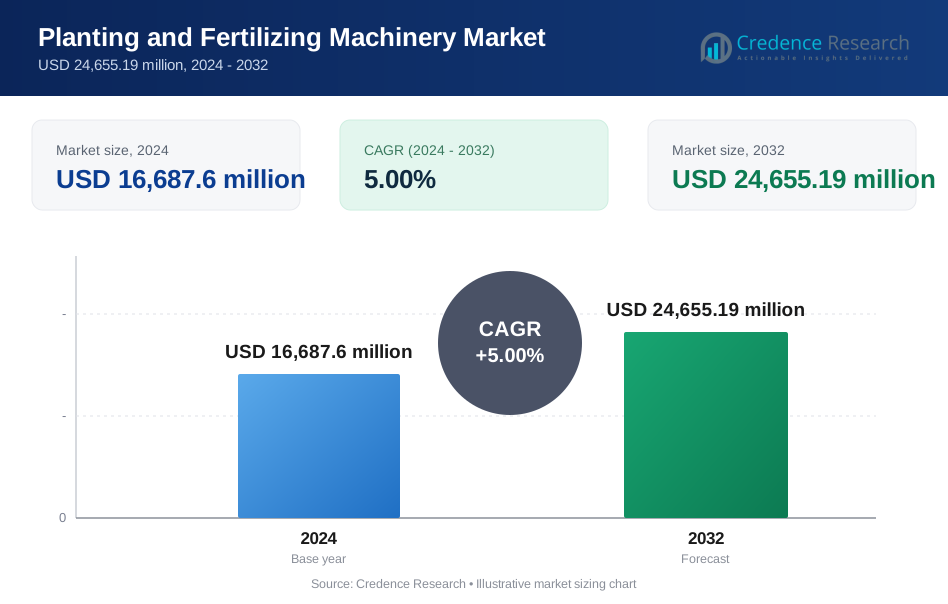
The Planting and Fertilizing Machinery Market was valued at USD 16,687.6 million in 2024 and is projected to reach USD 24,655.19 million by 2032, registering a CAGR of 5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Planting and Fertilizing Machinery Market Size 2024 | USD 16,687.6 Million |
| Planting and Fertilizing Machinery Market, CAGR | 5% |
| Planting and Fertilizing Machinery Market Size 2032 | USD 24,655.19 Million |
John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, CLAAS, Amazone, Mahindra & Mahindra, Great Plains Manufacturing, Kverneland Group, and Yanmar lead the Planting and Fertilizing Machinery market with strong portfolios across planters, fertilizer spreaders, and precision farming tools. These companies invest in GPS-enabled systems, variable rate technologies, and automated planting platforms that support high productivity across large agricultural zones. Asia Pacific remains the leading region with a 33% share due to extensive cereal and grain cultivation, government mechanization programs, and growing adoption of tractor-mounted machinery across major agricultural economies.
Market Insights
- The Planting and Fertilizing Machinery market reached USD 16,687.6 million in 2024 and is projected to reach USD 24,655.19 million by 2032 at a CAGR of 5.
- Rising need for higher productivity and reduced labour drives adoption of planters, while planters hold a 39% share due to large-scale cereal cultivation across major farming regions.
- Key trends include GPS-enabled machinery, variable rate fertilization, sustainability-focused features, and digital platforms that improve seed spacing and soil nutrient management.
- Competition intensifies as John Deere, CNH Industrial, AGCO, Kubota, and other manufacturers introduce precision systems, automated spreaders, and remote monitoring to increase field efficiency and reduce downtime.
- Asia Pacific leads with a 33% share, followed by North America at 29% and Europe at 27%, while tractor-mounted platforms hold a 52% share due to strong integration in modern farming operations and high field coverage in commercial farms.
 Market Segmentation Analysis:
By Product Type
Planters hold a 39% share of the product segment and remain the most used machinery due to large-scale planting of cereals and row crops in commercial farms. Planters increase planting accuracy, reduce manual labour, and support higher seed placement efficiency. Seed drills also expand adoption in emerging markets due to crop diversification and the need for uniform seed distribution. Fertilizer spreaders grow through rising nutrient-management practices and higher fertiliser application in intensive farming. Precision planters see strong interest due to digital metering and reduced seed wastage, especially in high-value crops. Planters maintain dominance due to broad field suitability and high productivity across regions.
- For instance, John Deere’s ExactEmerge planter places seeds at speeds up to 10 miles per hour with brush belt delivery and active downforce. The system uses brush-type meters that keep seed spacing uniform at high travel speeds.
By Power Source
Tractor-mounted machinery accounts for a 52% share of the power source segment and leads due to strong usage in medium and large farms. Tractor-mounted systems offer higher field coverage and greater operational efficiency, especially for row crops that require precise planting. Engine-powered equipment remains relevant for smaller farms needing portable machines. Electric systems grow through sustainability goals and reduced maintenance cost, particularly in greenhouse or controlled farming. Manual tools persist in smallholder agriculture across developing regions. Tractor-mounted platforms remain dominant since they integrate easily with modern tractors and support high-capacity field operations during peak planting seasons.
- For instance, CNH Industrial’s Magnum tractors deliver substantial torque that supports high-capacity planter attachments under heavy soil load, with some models offering best-in-class pulling power and a generous torque reserve.
By Application
Cereals and grains command a 57% share of the application segment and remain the major user group because global production of wheat, rice, and corn requires large-area planting and timely fertilisation cycles. Rising population and food-security programs support continuous demand in Asia and Africa. Oilseeds and pulses show expansion through global demand for soybeans and protein crops. Fruits and vegetables adopt advanced planters for precision placement in high-value farming. Other crops gain traction through diversified farm income strategies. Cereals maintain leadership due to wide cultivation area, government support for staple crops, and continuous mechanisation across developing agricultural economies.
Key Growth Drivers
Increasing Farm Mechanization Across Developing Regions
Developing markets increase spending on agricultural machinery to reduce labour dependence and improve planting efficiency. Governments encourage farm upgrades through subsidies and credit programs. Rapid population growth increases demand for staple crops, making mechanization necessary for timely planting. Rising rural wages and scarcity of skilled labour drive adoption of planters and fertilizer spreaders. Commercial farms expand operations to meet rising crop demand. Sustainable farming models further support machinery investment, especially for large acreage crops in Asia and Africa.
- For instance, Mahindra & Mahindra reported delivery of a significant volume of tractors in India during that period, which supported the ongoing mechanization in northern and central states.
Rising Demand for Higher Crop Productivity
Farmers use mechanized planters and spreaders to reduce seed wastage and improve nutrient absorption. Increasing adoption of precision fertilizer placement enhances crop yield and soil performance. Mechanized planting reduces planting time and supports large-scale harvesting cycles. Agribusinesses focus on technology to meet global food demand and improve farm profitability. Adoption of enhanced seed technologies encourages corresponding machinery investments. Continuous yield improvement remains a central priority in global farming.
- For instance, AGCO’s Precision Planting vApplyHD liquid control manages a wide range of flow rates per row unit for accurate nutrient dosing based on soil conditions. The system is designed to handle everything from very low in-furrow starter rates to much higher sidedressing rates across the full range of operating speeds, ensuring precise application without the need for manual adjustments or orifices.
Government Incentives for Modern Agriculture
Several countries run subsidy programs for agricultural machinery and promote mechanization of cereal and oilseed farming. Tax benefits, low-interest loans, and agricultural modernization policies encourage purchase of new machinery. Import duty reductions support access to advanced planting equipment. National food security programs also drive adoption of efficient planting systems for large farmlands. Policy support improves technology penetration in rural regions.
Key Trends and Opportunities
Adoption of Precision Farming and Digital Equipment
Farmers use GPS-enabled planters and variable rate fertilizing systems to control seed depth, spacing, and fertilizer placement. Digital meters improve field accuracy and reduce resource waste. Smart monitoring platforms help track soil health and plant growth. Demand for connected machinery grows across large farms focused on efficiency and sustainability goals. Precision farming supports long-term yield and promotes selective fertilizer use.
- For instance, Trimble’s Autopilot steering technology delivers 1.2 centimeter repeatable accuracy during contour planting with RTK corrections.
Growing Integration of Sustainable Fertilizing Practices
Manufacturers introduce machinery that supports nutrient-use efficiency and balanced soil fertility. Controlled fertilizer placement helps reduce environmental risks and improve plant absorption. Farmers adopt sustainable fertilizing equipment to support regenerative agriculture, water conservation, and reduced input reliance. Food companies encourage sustainable farming through chain-of-supply partnerships.
- For instance, Amazone's ZG-TX fertiliser spreader supports section control while reducing overlap in field trials from the DLG Test Center.
Key Challenges
High Initial Investment and Ownership Costs
Planting and fertilizing machinery requires high upfront investment, limiting adoption for small farmers. Maintenance cost, spare parts, and fuel usage increase ownership burden. Financial barriers remain common in developing markets without strong credit access. These costs slow technology penetration in rural regions.
Limited Technical Skills for Advanced Equipment
Modern planters and precision fertilizer systems require operational skills that smallholder farmers often lack. Limited training resources restrict wider adoption, especially in remote areas. Lack of skilled operators reduces efficiency, increasing breakdown risks and reducing return on investment. Training and service networks remain a key requirement for sustained growth.
Regional Analysis
North America
North America holds a 29% share of the Planting and Fertilizing Machinery market supported by modern mechanization, precision farming adoption, and strong commercial agriculture across the United States and Canada. Large farms invest in advanced seed drills, planters, and fertilizing tools for row crops including corn and soybean. Rising demand for higher crop yields and reduced nutrient wastage supports the use of precision fertilizer systems. Growing awareness of soil health and regulated fertilizer application strengthens equipment adoption. Agricultural technology companies expand partnerships with farmers for connected machinery and digital services across regional farms.
Europe
Europe accounts for a 27% share driven by sustainability regulations and increased demand for precision fertilizer placement to reduce emission impact. Countries such as Germany, France, and Italy support agricultural modernization through subsidies and technology grants. Precision planters and fertilizer spreaders gain adoption due to focus on soil management and water-efficient farming. EU policies encourage lower chemical discharge and precision nutrient control. Farmers adopt GPS-guided systems and connected machinery to meet production standards. Continuous investment in agricultural machinery manufacturing supports long-term use of automated equipment across European farmlands.
Asia Pacific
Asia Pacific holds a 33% share due to large-scale agricultural production across China, India, and Southeast Asia, supported by mechanization programs promoting planters and fertilizer spreaders in staple crop farming. Rice, wheat, and corn cultivation demand larger planting capacity and timely field operations. Governments implement farm mechanization subsidies to improve productivity and reduce labour costs. Commercial farming expands through high-yield seed programs and precision spreading tools. Rising food security priorities encourage sustainable fertilizing practices. Strong local manufacturing and supply chains strengthen machinery adoption across rural regions.
Latin America
Latin America holds a 6% share with rising mechanization across Brazil, Argentina, and Mexico supported by expanding soybean, corn, and sugarcane cultivation. Large farms integrate tractor-mounted planters and fertilizer spreaders for field coverage and planting efficiency. Export-oriented agriculture drives investment in high-capacity machinery. Precision farming tools increase yield potential and fertilizer use efficiency. Governments offer credit lines for agricultural modernization programs. Rising focus on soil management and input optimization influences machinery choice in major producing zones.
Middle East and Africa
The Middle East and Africa represent a 5% share driven by gradual farm modernization and rising food security programs targeting cereal and grain farming. Investments increase in tractor-mounted machinery to support mechanized planting in arid and semi-arid environments. International partnerships introduce modern spreaders and planters into regional markets. Limited skilled labour encourages automated machinery adoption. Water-scarce regions focus on precision fertilizer placement to minimize resource loss. Governments encourage agricultural imports and localized manufacturing to support future mechanization needs.
Market Segmentations:
By Product Type
- Planters
- Seed drills
- Fertilizer spreaders
- Precision planters
By Power Source
- Manual
- Electric
- Engine-powered
- Tractor-mounted
By Application
- Cereals and grains
- Oilseeds and pulses
- Fruits and vegetables
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape or analysis in the market is John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, CLAAS, Amazone, Mahindra & Mahindra, Great Plains Manufacturing, Kverneland Group, and Yanmar dominate the competitive landscape of the Planting and Fertilizing Machinery market. These companies invest in precision planting systems, variable rate fertilizer spreaders, and digital guidance solutions that improve seed placement accuracy and minimize input costs for farmers. Leading players focus on connected machinery equipped with GPS, sensors, and remote monitoring, enabling real-time control of planting and nutrient application. Manufacturers expand regional presence through localized production and dealership networks to support after-sales service and spare parts availability. Companies also integrate sustainability features that support nutrient-efficient farming, soil health, and reduced emissions in line with global agricultural regulations. Rising demand for high-capacity machines encourages continuous innovation in tractor-mounted planters designed for large farmlands.
Key Player Analysis
- John Deere
- CNH Industrial
- AGCO Corporation
- Kubota Corporation
- CLAAS
- Amazone
- Mahindra & Mahindra
- Great Plains Manufacturing
- Kverneland Group
- Yanmar
Recent Developments
- In September 2025, Kubota Corporation introduced its new “Grand L70 Series” compact tractors (at Kubota Connect), signalling expansion of their small-farm planting/utility offerings.
- In February 2025, Kinze announced a new dual-product liquid fertilizer system for their existing 5900 series front-fold planters.
- In 2025, AGCO (via its PTx/Trimble-linked division) displayed a new autonomous fertilizer-application solution - pointing to growing use of automation in fertilizing.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Power Source, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Precision planting systems will expand through GPS and sensor integration.
- Automated fertilizer spreaders will support nutrient efficiency and soil protection.
- Demand will rise for tractor-mounted platforms in large commercial farms.
- Electric machinery will gain interest due to lower emissions and maintenance.
- Digital monitoring tools will assist in real-time planting and field mapping.
- Sustainable fertilizing practices will push controlled application technologies.
- Farmers will adopt variable rate systems to reduce waste and input costs.
- Government subsidy programs will continue supporting mechanization upgrades.
- Local manufacturing will increase machinery availability in developing regions.
- Robotics and autonomous planters will emerge in advanced agriculture markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Planting and Fertilizing Machinery market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Planting and Fertilizing Machinery market projected to grow between 2024 and 2032?
Which Planting and Fertilizing Machinery market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Planting and Fertilizing Machinery market?
Who are the leading companies in the Planting and Fertilizing Machinery market?
Which region commanded the largest share of the Planting and Fertilizing Machinery market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Planting and Fertilizing Machinery Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Planting and Fertilizing Machinery Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 16,687.6 million → 2032: USD 24,655.19 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Planting and Fertilizing Machinery Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Planting and Fertilizing Machinery Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Planting and Fertilizing Machinery Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Planting and Fertilizing Machinery Market Drivers
- 3.3 Planting and Fertilizing Machinery Market Restraints & Challenges
- 3.4 Planting and Fertilizing Machinery Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Planting and Fertilizing Machinery Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Planting and Fertilizing Machinery Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Planting and Fertilizing Machinery category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Planting and Fertilizing Machinery Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Planting and Fertilizing Machinery Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Planting and Fertilizing Machinery market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Planting and Fertilizing Machinery Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Planting and Fertilizing Machinery Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Planting and Fertilizing Machinery Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Planting and Fertilizing Machinery (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Planting and Fertilizing Machinery Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Planting and Fertilizing Machinery Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Planting and Fertilizing Machinery Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Planting and Fertilizing Machinery Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Planting and Fertilizing Machinery Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Planting and Fertilizing Machinery Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Planting and Fertilizing Machinery Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Planting and Fertilizing Machinery Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Planting and Fertilizing Machinery Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
