
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Point of Care Cholesterol Monitoring Device Market Size 2024 | USD 3,002.25 Million |
| Point of Care Cholesterol Monitoring Device Market, CAGR | 7.8% |
| Point of Care Cholesterol Monitoring Device Market Size 2032 | USD 5,475.16 Million |
Market Overview
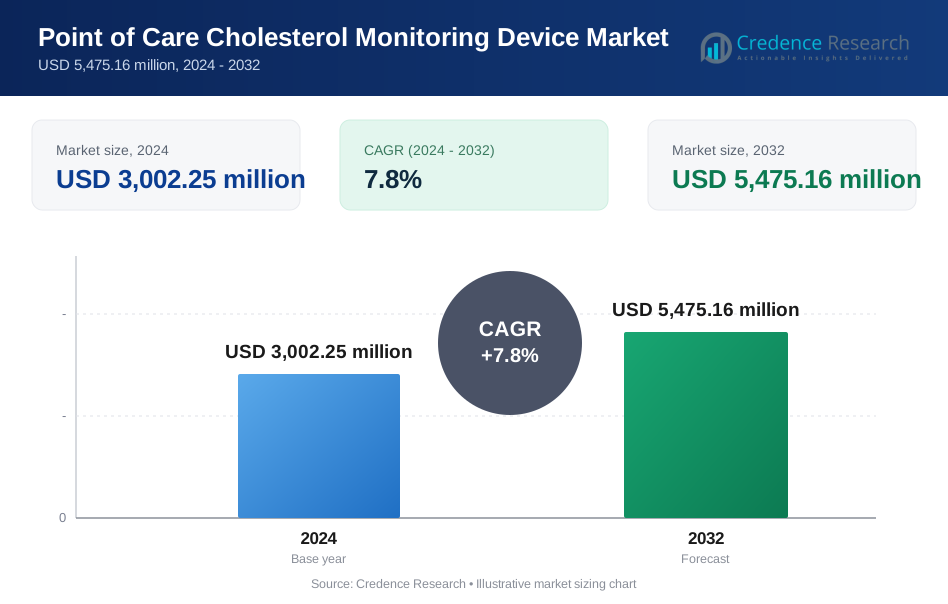
The Point of Care Cholesterol Monitoring Device Market is expected to grow from USD 3,002.25 million in 2024 to USD 5,475.16 million by 2032, reflecting a CAGR of 7.8%.
The growth of the Point of Care Cholesterol Monitoring Device market is driven by the increasing demand for rapid and convenient diagnostic solutions in both healthcare facilities and home settings. Advancements in technology have led to the development of more accurate, user-friendly, and cost-effective devices, enhancing patient monitoring capabilities. Additionally, the rising prevalence of cardiovascular diseases and the growing awareness of cholesterol-related health risks are fueling market expansion. The shift toward preventive healthcare, where individuals monitor their cholesterol levels regularly, further supports market growth. Furthermore, the adoption of these devices by healthcare professionals for real-time testing and diagnosis, along with the increasing healthcare expenditure in emerging economies, is contributing to the market’s upward trajectory. Market trends also include the integration of mobile health applications with cholesterol monitoring devices, offering patients seamless access to health data and fostering personalized care. These factors are expected to drive sustained market growth in the coming years.
The geographical analysis of the Point of Care (POC) cholesterol monitoring device market reveals significant growth across North America, Europe, and the Asia Pacific region. North America is a major market due to its advanced healthcare infrastructure, high awareness of cardiovascular diseases, and a growing preference for home-based testing. Europe is also seeing strong adoption, driven by aging populations and increasing demand for self-monitoring devices. The Asia Pacific region, particularly in countries like China and India, is experiencing rapid growth due to improving healthcare access, rising disposable incomes, and increasing awareness of chronic diseases. Key players in the POC cholesterol monitoring market include F. Hoffmann-La Roche Ltd., Abbott Laboratories, Beckman Coulter Inc. (Sub of Danaher Corporation), ACON Laboratories, Bioptik Technology, Inc., PTS Diagnostics, and SD Biosensor, Inc. These companies are focusing on innovation, expanding product portfolios, and strengthening distribution networks to cater to the growing demand for cholesterol monitoring devices globally.
Market Insights
- The Point of Care (POC) cholesterol monitoring device market is valued at USD 3002.25 million in 2024 and is expected to reach USD 5475.16 million by 2032, growing at a CAGR of 7.8%.
- Increasing prevalence of cardiovascular diseases (CVDs) is driving demand for cholesterol monitoring solutions.
- Aging populations in developed regions are leading to higher demand for frequent cholesterol testing.
- Technological advancements in device accuracy and portability are fueling market growth.
- High initial costs and long-term testing expenses may limit the adoption of POC cholesterol devices, especially in low-income regions.
- Limited reimbursement for POC tests in certain countries presents a challenge for widespread adoption.
- North America dominates the market with a 45% market share, driven by advanced healthcare systems and high awareness, while Asia Pacific holds a 30% market share, driven by rising healthcare access and increasing chronic disease prevalence.
Market Drivers
Rising Prevalence of Cardiovascular Diseases (CVDs)
Cardiovascular diseases (CVDs) continue to be a leading cause of death globally, driving the demand for early detection and proactive management of cholesterol levels. For instance, the World Heart Federation reports that CVDs are responsible for an estimated 18.6 million deaths each year. High cholesterol is a major risk factor for heart attacks and strokes, making its early identification critical for preventing these life-threatening events. Point of Care (POC) cholesterol monitoring devices offer the advantage of frequent, at-home monitoring, enabling individuals to track their cholesterol levels and make necessary lifestyle modifications. This ability to monitor and intervene regularly enhances patient outcomes and reduces the overall burden of CVDs on healthcare systems.
Increasing Geriatric Population
As the global population ages, the incidence of high cholesterol and cardiovascular diseases increases, particularly among older adults. For instance, the proportion of the world's population over 65 years of age is expected to exceed 16% by 2050. Age-related health risks, including higher cholesterol levels, make the elderly a key demographic for cholesterol monitoring. POC devices offer a practical solution for older individuals, allowing them to monitor their cholesterol levels independently and manage their health more effectively. These devices empower seniors to take control of their well-being, ensuring they remain informed and proactive in making health decisions, thus improving overall quality of life.
Growing Healthcare Awareness
The growing awareness of the importance of preventive healthcare and regular check-ups is encouraging individuals to take a more active role in their health management. People are increasingly recognizing the value of early diagnosis and cholesterol monitoring as part of a proactive health strategy. POC devices facilitate self-testing, allowing individuals to monitor their cholesterol levels at their convenience, without needing to rely solely on healthcare providers. This shift towards self-management is expanding the adoption of these devices, contributing to the market's growth.
Technological Advancements
Technological innovation has significantly enhanced the capabilities of cholesterol monitoring devices. The miniaturization of these devices has made them more portable and accessible, allowing users to perform tests at home easily. Advances in accuracy ensure that these devices provide reliable results, while user-friendly interfaces cater to a broad demographic, including individuals with limited technical expertise. As technology continues to evolve, POC devices are becoming more efficient, contributing to their widespread adoption and the growth of the market.
Market Trends
Increasing Demand for Early Detection and Convenient Testing Solutions
The rising prevalence of cardiovascular diseases (CVDs) globally has heightened awareness of their risk factors, particularly high cholesterol. For instance, the American Heart Association reports that nearly 94 million U.S. adults have total cholesterol levels above 200 mg/dL, which is considered high. There is an increasing emphasis on early detection and prevention, as early intervention plays a critical role in reducing the incidence of heart attacks and strokes. As a result, there is a growing demand for frequent monitoring of cholesterol levels, which Point of Care (POC) devices are well-positioned to meet. The aging population, which is more susceptible to high cholesterol and CVDs, further drives this demand for accessible and convenient testing solutions. Older adults, in particular, are looking for ways to easily monitor their cholesterol levels at home without relying solely on healthcare professionals. Technological advancements have significantly improved POC devices, making them more portable, accurate, and user-friendly. These devices are now equipped with miniaturized components and enhanced sensitivity, providing reliable results with simple interfaces. Additionally, the integration of digital connectivity has made it easier for users to track their health data and share it with healthcare providers remotely.
Shift Towards Home-Based Testing and Personalized Healthcare
There is a growing trend towards home-based testing, driven by the desire for convenience, privacy, and empowerment in health management. Patients are increasingly seeking devices that allow them to monitor their cholesterol levels from the comfort of their homes, without the need for clinic visits. For instance, a study by the Journal of Medical Internet Research found that home-based cholesterol testing is associated with higher patient satisfaction and adherence to monitoring schedules. This trend is complemented by the rise of telehealth and remote monitoring, which enables real-time data sharing between patients and healthcare providers. This integration ensures that patients adhere to treatment plans and receive timely interventions based on the data collected. Additionally, the emerging markets are witnessing an increase in healthcare infrastructure, rising disposable incomes, and growing awareness of chronic diseases, which makes home-based testing more accessible. In line with these trends, there is a growing focus on affordable, cost-effective POC devices. With favorable regulatory frameworks and reimbursement policies in place, healthcare systems are increasingly adopting these devices. Furthermore, the integration of personalized medicine, using genetic information and other biomarkers, is further enhancing the value of POC cholesterol testing, allowing for more tailored treatment strategies that improve patient outcomes.
Market Challenges Analysis
Accuracy, Reliability, and Cost-Effectiveness Challenges
One of the key challenges faced by the Point of Care (POC) cholesterol monitoring market is ensuring the accuracy and reliability of test results. Variations in cholesterol levels across different individuals can lead to discrepancies in results, making it crucial for devices to maintain consistent accuracy. External factors such as user error, environmental conditions, and improper device calibration can further impact test outcomes. To address these concerns, manufacturers must develop devices that minimize the potential for inaccuracies and offer consistent performance. Additionally, while POC devices offer convenience, their initial costs, including the price of devices and test strips, can be prohibitive, particularly in low-income regions. Long-term costs associated with regular testing may deter some individuals from adopting these devices, limiting their widespread use. These cost-related challenges make it difficult for certain populations to access and benefit from cholesterol monitoring, especially in developing countries with limited healthcare budgets.
Regulatory and Educational Barriers to Widespread Adoption
Another significant hurdle is the complex regulatory landscape for medical devices. POC cholesterol monitors must adhere to stringent regulations in different markets, which can increase both development costs and the time-to-market for these devices. For instance, the U.S. FDA categorizes In Vitro Diagnostics (IVDs) by complexity, requiring different levels of certification and compliance. Obtaining regulatory approvals from multiple countries adds an additional layer of complexity, particularly when requirements vary widely across regions. In parallel, user education and training remain critical to ensuring that devices are used correctly. Many consumers may not fully understand how to operate the devices or interpret the results accurately, which can lead to errors and unreliable outcomes. Proper training and support are necessary to address these issues and ensure consistent adherence to testing protocols. Moreover, limited reimbursement for POC cholesterol tests in many healthcare systems further complicates affordability, as individuals may struggle to cover the costs of regular testing. According to a report by the National Community Pharmacists Association (NCPA), pharmacies need to complete specific applications to register as CLIA-waived testing sites, which can be a barrier for widespread adoption. Data integration also presents challenges, as integrating POC device data with electronic health records (EHRs) and telemedicine platforms is often difficult due to technical and privacy concerns. Lastly, consumer acceptance and awareness must be improved to overcome misconceptions about the reliability of POC devices, ensuring wider adoption. Effective distribution and supply chain management are essential to ensure the timely availability of devices and consumables, especially in remote areas where access to healthcare services may be limited.
Market Opportunities
The growing global focus on preventive healthcare presents significant market opportunities for Point of Care (POC) cholesterol monitoring devices. With an increasing awareness of the health risks associated with high cholesterol, individuals are more inclined to adopt regular monitoring practices to prevent cardiovascular diseases. This trend is particularly evident in aging populations, where the risk of high cholesterol and related health issues such as heart disease and stroke is higher. The demand for convenient, user-friendly devices that allow for real-time, at-home cholesterol testing is expected to grow, especially as people seek to take proactive control over their health. This shift towards self-management is reinforced by advancements in technology, including the miniaturization and accuracy improvements in POC devices, which make cholesterol testing more accessible and reliable. Emerging markets represent a promising growth area for POC cholesterol monitoring devices. As healthcare infrastructure improves and disposable incomes rise in developing economies, there is an increased demand for affordable healthcare solutions, including home-based diagnostic tools. POC devices can cater to this need by offering cost-effective, reliable, and easily accessible cholesterol testing solutions. Additionally, the rise of telehealth and remote monitoring further enhances market opportunities, as POC devices can integrate with digital health platforms, allowing for real-time data sharing between patients and healthcare providers. This trend aligns with the increasing adoption of telemedicine, offering a streamlined, comprehensive approach to managing cholesterol levels, particularly in remote and underserved areas. These developments not only broaden the market reach but also enable personalized care, ensuring that individuals receive timely and tailored health interventions.
Market Segmentation Analysis:
By Product:
The Point of Care (POC) cholesterol monitoring device market is primarily segmented by product type, including instruments and testing kits. Instruments further split into table-top analyzers and hand-held analyzers, catering to different needs across healthcare settings. Table-top analyzers are generally used in clinical environments, providing high-throughput and accurate results. These devices are ideal for hospitals, clinics, and other healthcare facilities that require consistent and reliable cholesterol measurement for multiple patients. On the other hand, hand-held analyzers are portable and designed for personal use, offering convenience for home testing. These devices have gained popularity due to their ease of use, cost-effectiveness, and compact design, enabling individuals to monitor their cholesterol levels regularly without visiting a healthcare facility. Testing kits also play a significant role in the market, offering an affordable and practical solution for at-home testing. These kits typically include test strips, reagents, and other necessary materials for performing cholesterol tests, driving the demand for self-monitoring solutions.
By Technology:
The technology segment of the POC cholesterol monitoring device market is primarily categorized into electrochemical biosensors and reflectance photometry. Electrochemical biosensors are widely used due to their precision, sensitivity, and quick results. These devices work by detecting chemical reactions through an electrical signal, making them highly effective for cholesterol monitoring, especially in hand-held and portable devices. Electrochemical biosensors are particularly valued in clinical settings for their accuracy and ability to provide real-time data, aiding in timely decision-making. Reflectance photometry, on the other hand, uses light reflection to detect cholesterol levels and is commonly found in less complex and lower-cost testing solutions. This technology is often utilized in home-based testing kits, providing an affordable option for users who require frequent cholesterol monitoring. Both technologies offer distinct advantages, with electrochemical biosensors focusing on precision and reliability, while reflectance photometry emphasizes simplicity and cost-effectiveness. Together, these technologies cater to the diverse needs of healthcare professionals and consumers.
Segments:
Based on Product:
- Instruments
- Table-top Analyzers
- Hand-held Analyzers
- Testing Kits
Based on Technology:
- Electrochemical Biosensor
- Reflectance Photometry
Based on Application:
- Dyslipidemia
- Atherosclerosis
- Hypercholestrolemia
- Hypocholesterolimea
- Others
Based on End User:
- Hospitals
- Diagnostics centers & Laboratory
- Ambulatory surgical centers
- Home care sittings
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the Point of Care (POC) cholesterol monitoring device market, accounting for approximately 45% of the global market. This is primarily due to the region’s advanced healthcare infrastructure, high healthcare expenditure, and a growing focus on preventive healthcare. The United States, in particular, is the largest market within North America, driven by increasing awareness of cardiovascular diseases (CVDs) and the need for regular cholesterol monitoring. The aging population in the U.S. is more susceptible to high cholesterol and related health issues, creating a substantial demand for cholesterol monitoring devices. Furthermore, advancements in technology, including improved accuracy and the miniaturization of POC devices, have contributed to market growth. The integration of POC devices with telehealth platforms has also gained traction in North America, enhancing remote patient monitoring and providing patients with the ability to manage their cholesterol levels independently. Reimbursement policies and a favorable regulatory environment further support the growth of the POC cholesterol monitoring market in this region. As a result, North America is expected to continue leading the market due to ongoing technological innovations, healthcare accessibility, and increasing consumer demand for self-monitoring solutions.
Asia-Pacific
The Asia Pacific region is the second-largest market for Point of Care (POC) cholesterol monitoring devices, capturing around 30% of the global market share. This growth can be attributed to the region’s rapidly developing healthcare infrastructure, rising disposable incomes, and increasing awareness of chronic diseases like cardiovascular disorders. Countries such as China, India, and Japan are at the forefront of this expansion, driven by large populations, urbanization, and the increasing prevalence of lifestyle-related diseases such as high cholesterol. As these countries see improved healthcare access, there is a growing demand for cost-effective and convenient cholesterol monitoring solutions, especially in rural and underserved areas. The rise of home-based testing, powered by affordable and portable POC devices, is especially popular in these regions due to the convenience and privacy it offers. Moreover, the growing middle class in these countries is driving demand for better healthcare products, including cholesterol monitoring devices. In addition, governmental initiatives and investments in healthcare infrastructure are expected to further boost the adoption of POC cholesterol testing across the Asia Pacific region. With the increasing healthcare awareness and a shift towards preventive care, the Asia Pacific region is projected to see continued growth in the POC cholesterol monitoring market in the coming years.
Key Player Analysis
- Abbott Laboratories
- Hoffmann-La Roche Ltd.
- Beckman Coulter Inc. (Sub of Danaher Corporation)
- ACON Laboratories
- Bioptik Technology, Inc.
- PTS Diagnostics
- Jant Pharmacal Corporation, Inc.
- DiaSys Diagnostic Systems GmbH
- Nova Biomedical Corporation
- SD Biosensor, Inc.
- SAMSUNG HEALTH CARE, Inc.
- Abaxis, Inc. (Sub of Zoetis Inc.)
Competitive Analysis
The competitive landscape of the Point of Care (POC) cholesterol monitoring device market is marked by significant activity from leading players such as F. Hoffmann-La Roche Ltd., Abbott Laboratories, Beckman Coulter Inc. (Sub of Danaher Corporation), ACON Laboratories, Bioptik Technology, Inc., PTS Diagnostics, Jant Pharmacal Corporation, Inc., DiaSys Diagnostic Systems GmbH, Nova Biomedical Corporation, SD Biosensor, Inc., and SAMSUNG HEALTH CARE, Inc. Leading companies in the market are investing heavily in research and development to improve the accuracy, portability, and ease of use of their devices. Technological advancements, such as the miniaturization of devices, enhanced sensor technologies, and integration with digital platforms for remote monitoring, are driving market growth. Additionally, companies are focusing on providing cost-effective solutions, particularly for home-based testing, to cater to the increasing demand for convenient and accessible cholesterol monitoring options. In clinical settings, there is a continued emphasis on high-precision devices capable of delivering fast and reliable results, meeting the needs of healthcare professionals. The competition is further intensifying as firms are forming strategic partnerships, collaborations, and acquisitions to expand their product portfolios and strengthen distribution networks. Furthermore, with the growing trend of telehealth and remote patient monitoring, players are increasingly integrating their devices with digital health platforms to offer patients real-time data sharing and improve adherence to treatment plans. These strategies are expected to maintain the competitiveness and market presence of leading companies in the POC cholesterol monitoring device market.
Recent Developments
- In May 2023, bioMérieux received the US FDA CLIA-waiver for the BIOFIRE SPOTFIRE Respiratory (R) Panel Mini,a second multiplex PCR-based test cleared for use on the BIOFIRE SPOTFIRE System
- In August 2023, BD received the US FDA approval for its BD Respiratory Viral Panel (RVP) for BD MAX System, a single molecular diagnostic combination test that identifies & distinguishes SARS-CoV-2, influenza A, influenza B, and Respiratory Syncytial Virus (RSV) in ~ 2 hours.
- In December 2023, Thermo Fisher Scientific Inc. and Project HOPE, a leading global health and humanitarian organization, partnered to expand the accessibility of HIV testing services offered by Thermo Fisher among HIV Positive Youth in Sub-Saharan Africa.
- In October 2022 Genes2Me Pvt. Ltd launched Rapi-Q- Point of Care RT PCR solution for human papillomavirus (HPV) and tuberculosis. The device is easy to use and gives faster results in less than 45 minutes. This CE-IVD-marked POC solution delivers superior performance, high sensitivity, and stable detection.
- In March 2022, Visby Medical announced that it received funding of USD 25.5 million from the U.S. Biomedical Advanced Research and Development Authority to develop a rapid flu-COVID-19 PCR test for home use. At present, the test is in the under-developing phase, and the design is ready as a PCR device that can detect COVID-19, influenza A, and B from a single sample.
Market Concentration & Characteristics
The Point of Care (POC) cholesterol monitoring device market exhibits a moderate level of market concentration, with a mix of established multinational corporations and smaller, specialized players. Large companies hold a significant share of the market, driven by their established brand presence, extensive distribution networks, and robust research and development capabilities. These players focus on offering high-precision, technologically advanced devices that cater to both clinical and home settings. On the other hand, smaller companies are focusing on providing affordable and portable solutions, tapping into the growing demand for self-testing devices, especially in emerging markets. The market characteristics include rapid innovation, with constant advancements in device miniaturization, sensor technology, and digital integration. Companies are emphasizing the development of user-friendly devices with enhanced accuracy, faster testing times, and seamless connectivity with mobile applications for remote monitoring. Furthermore, the market is seeing an increased shift toward home-based testing, as patients and healthcare providers look for more convenient and accessible ways to manage cholesterol levels. There is also a growing trend towards integrating POC cholesterol monitoring with telehealth and remote patient management systems. As a result, competition remains strong, with players leveraging technology, affordability, and convenience to differentiate themselves in this evolving market.
Report Coverage
The research report offers an in-depth analysis based on Product, Technology, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market for Point of Care (POC) cholesterol monitoring devices is expected to grow significantly, driven by the increasing prevalence of cardiovascular diseases and a rising awareness of cholesterol management.
- Advancements in technology will continue to improve the accuracy, speed, and portability of POC devices, enhancing user experience and increasing adoption.
- The demand for home-based testing solutions will increase as consumers seek more convenient and private ways to monitor their health.
- Integration with digital health platforms and telemedicine will play a critical role in remote monitoring and improving patient outcomes.
- As the aging population grows globally, there will be a higher demand for POC devices to manage age-related health risks, including high cholesterol.
- The market will see continued innovation in sensor technologies, enabling more precise cholesterol level detection with minimal user input.
- Regulatory frameworks are expected to evolve, offering clearer guidelines and support for the adoption of POC devices in various regions.
- Cost-effective solutions will emerge, making cholesterol monitoring devices more accessible to underserved populations, especially in emerging markets.
- Strategic partnerships between device manufacturers and healthcare providers will drive further expansion and distribution of POC devices.
- Increased government initiatives aimed at promoting preventive healthcare will further boost the adoption of POC cholesterol monitoring devices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases (CVDs)
The global increase in cardiovascular diseases is fueling demand for early detection and ongoing management of cholesterol levels, making point of care cholesterol monitoring devices essential for both clinical and home use.
Aging Population
As the proportion of elderly individuals grows worldwide, the incidence of high cholesterol and related health risks rises, driving demand for accessible, frequent cholesterol testing solutions that POC devices provide.
Technological Advancements in Device Accuracy and Portability
Continuous innovation has led to more accurate, user-friendly, and portable cholesterol monitoring devices, making it easier for patients and healthcare professionals to conduct reliable tests in various settings.
Shift Toward Preventive and Home-Based Healthcare
Increasing awareness of preventive healthcare and the convenience of home-based testing are encouraging more individuals to self-monitor cholesterol levels, expanding the adoption of POC devices.
Growing Healthcare Infrastructure and Expenditure in Emerging Markets
Improved healthcare access, rising disposable incomes, and government initiatives in emerging economies are boosting the uptake of cost-effective POC cholesterol monitoring devices.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Point of Care Cholesterol Monitoring Device Market?
What factors are driving the growth of the Point of Care Cholesterol Monitoring Device Market?
What are the key segments within the Point of Care Cholesterol Monitoring Device Market?
What are some challenges faced by the Point of Care Cholesterol Monitoring Device Market?
Who are the major players in the Point of Care Cholesterol Monitoring Device Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Table-top Analyzers
- 1.2.2 Hand-held Analyzers
- 1.2.3 Testing Kits
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Diagnostics Centers & Laboratory
- 1.3.3 Ambulatory Surgical Centers
- 1.3.4 Home Care Settings
- 1.4 By Technology
- 1.4.1 Electrochemical Biosensor
- 1.4.2 Reflectance Photometry
- 1.5 By Application
- 1.5.1 Dyslipidemia
- 1.5.2 Atherosclerosis
- 1.5.3 Hypercholesterolemia
- 1.5.4 Hypocholesterolemia
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,002.25 million → 2032: USD 5,475.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Point of Care Cholesterol Monitoring Device Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Point of Care Cholesterol Monitoring Device Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Point of Care Cholesterol Monitoring Device Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Point of Care Cholesterol Monitoring Device Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Point of Care Cholesterol Monitoring Device Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Point of Care Cholesterol Monitoring Device Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Point of Care Cholesterol Monitoring Device Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Point of Care Cholesterol Monitoring Device Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,002.25 million → 2032: USD 5,475.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Point of Care Cholesterol Monitoring Device Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Table-top Analyzers
- 12.3.7.2 Hand-held Analyzers
- 12.3.7.3 Testing Kits
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Diagnostics Centers & Laboratory
- 12.4.7.3 Ambulatory Surgical Centers
- 12.4.7.4 Home Care Settings
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electrochemical Biosensor
- 12.5.7.2 Reflectance Photometry
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Dyslipidemia
- 12.6.7.2 Atherosclerosis
- 12.6.7.3 Hypercholesterolemia
- 12.6.7.4 Hypocholesterolemia
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Point of Care Cholesterol Monitoring Device End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Point of Care Cholesterol Monitoring Device Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Point of Care Cholesterol Monitoring Device Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Point of Care Cholesterol Monitoring Device Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 F. Hoffmann-La Roche Ltd.
- 18.4 Beckman Coulter Inc. (Danaher Corporation)
- 18.5 ACON Laboratories
- 18.6 Bioptik Technology, Inc.
- 18.7 PTS Diagnostics
- 18.8 SD Biosensor, Inc.
- 18.9 Jant Pharmacal Corporation, Inc.
- 18.10 DiaSys Diagnostic Systems GmbH
- 18.11 Nova Biomedical Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

