
Point-of-Use Water Treatment Systems Market Overview:
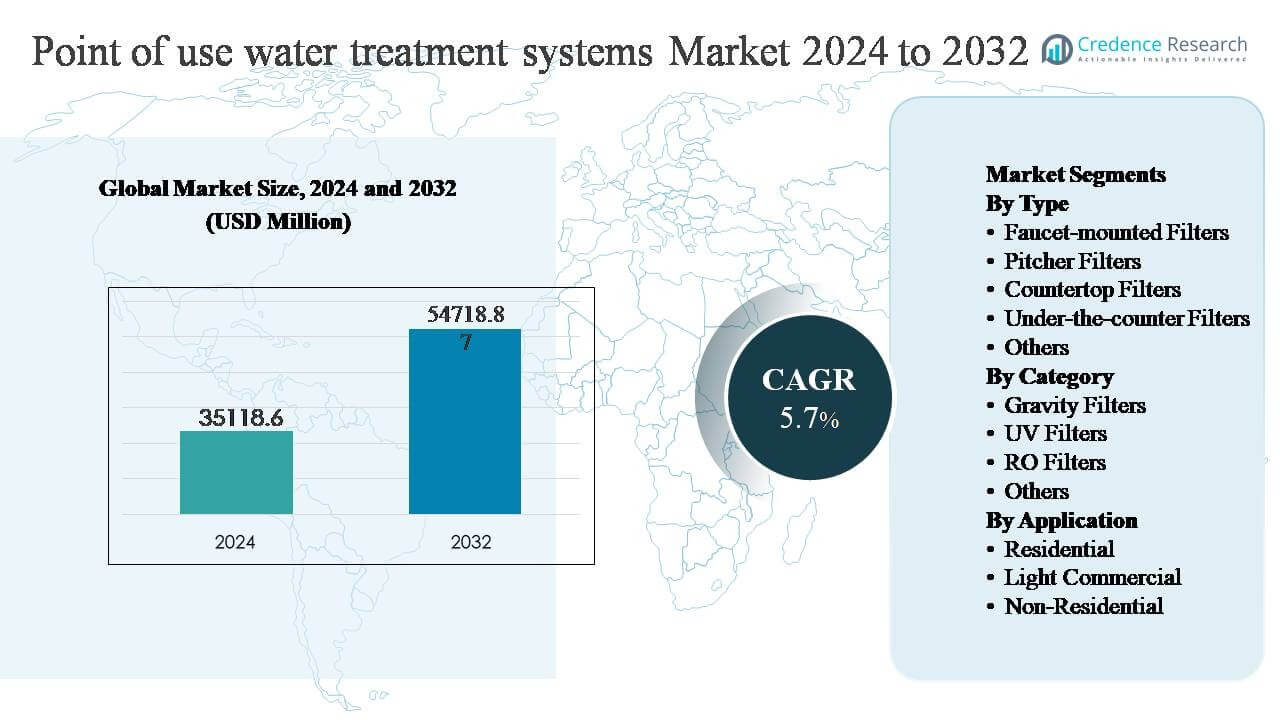
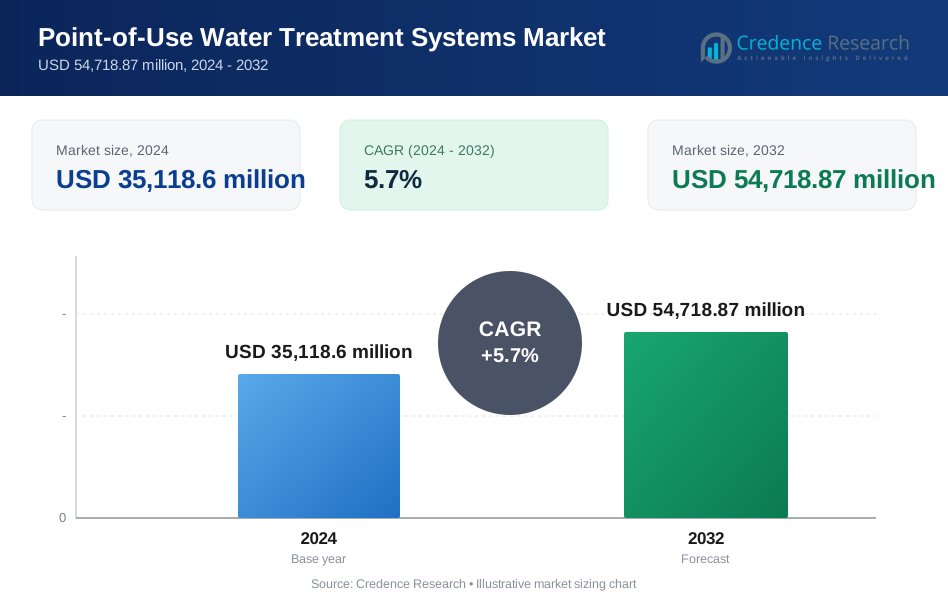
The global point of use (POU) water treatment systems market was valued at USD 35,118.6 million in 2024 and is projected to reach USD 54,718.87 million by 2032, expanding at a CAGR of 5.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Point-of-Use Water Treatment Systems Market Size 2024 | USD 35,118.6 million |
| Point-of-Use Water Treatment Systems Market, CAGR | 5.7% |
| Point-of-Use Water Treatment Systems Market Size 2032 | USD 54,718.87 million |
Point-of-Use Water Treatment Systems Market Insights
- Rising concerns over drinking water contamination, aging municipal infrastructure, and increasing health awareness are driving strong demand, with residential applications accounting for the dominant share due to widespread household adoption of RO- and UV-based systems.
- Key market trends include growing preference for under-the-counter systems as the leading type segment, dominance of RO technology by category, and rising adoption of smart, connected purifiers offering filter-life monitoring and improved efficiency.
- The competitive landscape features global electronics brands and specialized water purification companies competing on technology innovation, brand trust, pricing, and after-sales service, with strong emphasis on multi-stage and energy-efficient systems.
- Asia Pacific leads with approximately 34% market share, followed by North America at 32% and Europe at 26%, while Latin America and Middle East & Africa together contribute the remaining share, constrained by affordability and infrastructure challenges.
Point-of-Use Water Treatment Systems Market Segmentation Analysis:
By Type:
By type, under-the-counter filters represent the dominant sub-segment in the point of use water treatment systems market, accounting for the largest market share due to their high purification efficiency, concealed installation, and suitability for multi-stage filtration. These systems are widely adopted in urban households seeking consistent, high-volume purified water without occupying countertop space. Strong demand is driven by increasing awareness of dissolved solids, heavy metals, and microbial contamination, along with rising preference for long-term, low-maintenance solutions. Faucet-mounted and pitcher filters maintain steady uptake for affordability and portability, while countertop systems cater to renters and small offices.
- For instance, Kent RO Systems’ under-the-counter RO units integrate up to 8-stage purification with a rated capacity of 20 liters per hour, combining RO, UV, and UF modules to address dissolved solids and pathogens in a single installation.
By Category:
By category, RO filters dominate the market with the highest share, supported by their proven ability to remove dissolved salts, arsenic, fluoride, nitrates, and other contaminants prevalent in municipal and groundwater sources. RO systems are especially favored in regions facing high total dissolved solids (TDS) levels and inconsistent water quality. Growth is reinforced by continuous improvements in membrane efficiency, water recovery rates, and compact system designs. UV filters hold strong relevance as complementary technologies for microbial disinfection, while gravity filters remain popular in electricity-constrained areas due to low operating costs and ease of use.
- For instance, Coway has introduced compact RO modules integrating booster pumps delivering 6-0.8 MPa operating pressure, allowing stable purification performance even in low-pressure household supply conditions while reducing overall unit footprint.
By Application:
By application, the residential segment holds the dominant market share, driven by rising health consciousness, growing urban populations, and increasing penetration of household water purifiers in both developed and emerging economies. Households increasingly invest in POU systems to ensure safe drinking water amid concerns over aging infrastructure and variable municipal treatment quality. Light commercial applications, including offices, clinics, cafés, and educational institutions, are expanding steadily due to hygiene standards and employee welfare initiatives. Non-residential adoption remains niche, primarily focused on targeted point installations rather than whole-facility treatment systems.
Key Growth Driver
Rising Concerns Over Drinking Water Quality and Health Safety
Growing awareness of waterborne diseases and long-term health risks linked to contaminants such as heavy metals, pathogens, and chemical residues is a primary growth driver for point of use water treatment systems. Aging municipal infrastructure, industrial discharge, agricultural runoff, and intermittent water supply quality have increased consumer distrust in centralized treatment systems. As a result, households and small commercial users increasingly adopt POU systems to ensure water safety at the point of consumption. Heightened media coverage of contamination incidents and stronger public health advocacy further reinforce demand. Consumers now prioritize preventive health investments, positioning POU systems as essential household appliances rather than discretionary products.
- For instance, NSF International testing protocols (Standards 53 and 58) used by brands such as Aquasana and 3M validate POU systems for lead reduction to levels at or below 5 micrograms per liter (µg/L). This threshold is twice as stringent as the previous 10 µg/L benchmark to ensure compliance with the most rigorous drinking water safety standards.
Urbanization and Growth of Residential Infrastructure
Rapid urbanization and expansion of residential construction, particularly in emerging economies, significantly support the adoption of point of use water treatment systems. High-density housing, apartment living, and mixed-use developments favor compact, easy-to-install filtration solutions that do not require centralized plumbing changes. Developers increasingly incorporate POU systems into residential projects as value-added features to enhance living standards. Rising disposable incomes and improved access to organized retail and e-commerce platforms further facilitate product penetration. This urban lifestyle shift continues to strengthen demand for under-the-counter and countertop POU systems designed for modern kitchens.
- For instance, Panasonic’s residential under-the-counter water purifiers (such as the TK-CB430) are designed for urban apartments with a tankless, compact profile featuring installation depths as shallow as 125 mm.
Technological Advancements and Product Innovation
Continuous innovation in filtration technologies is accelerating market growth by improving performance, efficiency, and user experience. Advancements in reverse osmosis membranes, UV disinfection modules, and multi-stage filtration systems enhance contaminant removal while reducing water wastage and energy consumption. Compact system designs, longer filter life, and modular configurations increase adoption across space-constrained urban settings. Smart features such as filter life indicators, digital monitoring, and automated maintenance alerts further improve consumer confidence and convenience. These technological enhancements broaden the appeal of POU systems across diverse consumer segments.
Key Trend & Opportunity
Integration of Smart and Connected Water Purification Systems
The integration of smart technologies presents a significant growth opportunity in the point of use water treatment systems market. Manufacturers increasingly incorporate IoT-enabled sensors, digital displays, and mobile app connectivity to monitor water quality, system performance, and filter replacement cycles. These features enhance transparency and user control, aligning with broader smart home adoption trends. Smart systems also enable predictive maintenance and improve long-term system reliability. As consumers seek intelligent appliances that offer convenience and data-driven insights, smart POU systems are positioned to command premium pricing and drive brand differentiation.
- For instance, Coway’s IoCare-enabled RO purifiers track real-time water consumption and filter life which, depending on the model, can reach up to 10,000 liters or 24 months and automatically generate replacement alerts and performance reports through cloud-linked smart diagnostics."
Expansion in Light Commercial and Institutional Applications
Beyond residential use, expanding adoption in light commercial and institutional settings presents strong growth opportunities. Offices, clinics, cafés, schools, and small hospitality establishments increasingly install POU systems to meet hygiene standards and ensure safe drinking water for employees and customers. Rising regulatory scrutiny on water safety in public and semi-public spaces further supports this trend. POU systems offer a cost-effective alternative to bottled water and centralized treatment, reducing operational costs and plastic waste. This diversification of end-use applications strengthens long-term market resilience.
- For instance, Best Water Technology (BWT) supplies under-sink and freestanding POU systems for offices and cafés equipped with RO membranes rated at 150-300 liters per hour, supporting continuous dispensing during peak operational hours.
Key Challenge
High Maintenance Requirements and Filter Replacement Costs
Despite strong demand, high maintenance requirements remain a key challenge for point of use water treatment systems. Regular filter and membrane replacement is essential to maintain purification efficiency, yet many users underestimate ongoing maintenance costs. Delayed replacements can compromise water quality, reduce system performance, and negatively impact consumer satisfaction. In price-sensitive markets, recurring costs discourage long-term adoption, particularly for advanced RO-based systems. Manufacturers face the challenge of balancing high filtration performance with lower lifecycle costs while improving consumer education on maintenance practices.
Water Wastage and Environmental Concerns
Water wastage associated with certain POU technologies, particularly reverse osmosis systems, presents a significant challenge amid growing sustainability concerns. High reject water ratios strain household water consumption, especially in water-scarce regions. Environmental awareness among consumers and increasing regulatory pressure push manufacturers to improve water recovery rates and develop eco-efficient solutions. Failure to address these concerns may limit adoption in sustainability-focused markets. Developing low-waste filtration technologies and promoting responsible water usage remain critical to overcoming this challenge and sustaining long-term market growth.
Regional Analysis
North America:
North America holds a significant share of the point of use water treatment systems market, accounting for approximately 32% of global revenue. Strong consumer awareness of water quality, widespread adoption of advanced filtration technologies, and high penetration of under-the-counter and RO systems drive regional demand. Aging water infrastructure in several U.S. cities has reinforced household reliance on POU systems for drinking and cooking water. The region also benefits from strong presence of established manufacturers, rapid adoption of smart and connected purifiers, and steady replacement demand across residential and light commercial applications.
Europe:
Europe represents around 26% of the global market share, supported by stringent water quality regulations, high health awareness, and strong adoption of sustainable household appliances. Countries such as Germany, the U.K., France, and Italy show consistent demand for countertop and under-the-counter filtration systems, particularly those focused on taste improvement and contaminant reduction. Environmental consciousness encourages reduced bottled water consumption, indirectly supporting POU system uptake. Growth is further supported by modernization of residential infrastructure and increasing adoption in offices, schools, and hospitality settings across Western and Northern Europe.
Asia Pacific:
Asia Pacific is the largest regional market, accounting for approximately 34% of global share, driven by rapid urbanization, population growth, and inconsistent municipal water quality in several countries. High prevalence of groundwater contamination and elevated TDS levels significantly boost demand for RO-based POU systems. China and India lead regional consumption, supported by rising disposable incomes, expanding middle-class populations, and strong government focus on safe drinking water. The region also benefits from competitive pricing, strong domestic manufacturing bases, and fast-growing penetration in both residential and light commercial segments.
Latin America:
Latin America accounts for around 5% of the global point of use water treatment systems market, with growth supported by urban expansion and increasing concerns over water safety in metropolitan areas. Countries such as Brazil, Mexico, and Chile are witnessing rising adoption of gravity-based and RO systems due to uneven municipal water treatment quality. Economic recovery trends and growing consumer focus on household health support steady demand. However, price sensitivity and limited awareness in rural areas constrain faster adoption, keeping penetration concentrated in urban residential and small commercial applications.
Middle East & Africa:
The Middle East & Africa region holds approximately 3% of the global market share, driven primarily by water scarcity, desalination reliance, and high salinity levels in water supply. Gulf Cooperation Council countries show stronger adoption of advanced RO and multi-stage filtration systems in residential and commercial buildings. In Africa, demand is concentrated in urban centers, with gravity and basic filtration systems more prevalent due to affordability considerations. Infrastructure gaps and limited consumer awareness moderate growth, but long-term demand remains supported by chronic water quality challenges.
Point-of-Use Water Treatment Systems Market Segmentations:
By Type
- Faucet-mounted Filters
- Pitcher Filters
- Countertop Filters
- Under-the-counter Filters
- Others
By Category
- Gravity Filters
- UV Filters
- RO Filters
- Others
By Application
- Residential
- Light Commercial
- Non-Residential
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the point of use water treatment systems market is characterized by the presence of established multinational brands alongside strong regional players competing on technology, product reliability, and distribution reach. Leading companies focus on advanced filtration technologies, particularly reverse osmosis, UV, and multi-stage hybrid systems, to strengthen product differentiation. Continuous investment in research and development supports improvements in membrane efficiency, water recovery, and compact system design.
Market participants also emphasize brand trust, after-sales service networks, and filter replacement programs to secure long-term customer loyalty. Strategic partnerships with real estate developers, commercial establishments, and e-commerce platforms enhance market penetration. Additionally, companies increasingly expand their portfolios with smart and connected purification systems to address evolving consumer preferences. Competitive intensity remains high, with pricing strategies, product innovation, and geographic expansion serving as key levers to maintain and grow market share across residential and light commercial segments.
Key Player Analysis
- LG Electronics
- Panasonic Corporation
- Coway Co. Ltd.
- Eureka Forbes Ltd.
- Kent RO Systems Ltd.
- Best Water Technology Group
- Helen of Troy Ltd.
- Katadyn Group
- Global Water Solutions Ltd.
- General Ecology Inc.
Recent Developments
- In September 2025, Coway’s Icon Pro Water Purifier was honored at the 2025 International Design Excellence Awards (IDEA), recognized for its innovative full-screen LCD display that provides intuitive control and real-time system information highlighting design and usability achievements for advanced home water purification.
- In April 2024, Panasonic (through Panasonic Manufacturing Malaysia Berhad) introduced an all-new Central Water Purification System (POE) to the Indonesian market, equipped with proprietary high-speed oxidation coagulation technology and a backwash function for iron and muddy element removal.
Report Coverage
The research report offers an in-depth analysis based on Type, Category, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for point of use water treatment systems will continue to rise as consumers prioritize safe and reliable drinking water at the household level.
- Technological innovation will focus on improving filtration efficiency, water recovery, and compact system design.
- Smart and connected purification systems will gain wider adoption, driven by integration with digital monitoring and maintenance alerts.
- Residential applications will remain the primary growth engine, supported by urbanization and expanding housing infrastructure.
- Light commercial adoption will increase across offices, healthcare facilities, and hospitality establishments.
- Reverse osmosis systems will retain a leading position, supported by hybrid configurations combining UV and carbon filtration.
- Manufacturers will emphasize sustainability through reduced water wastage and longer filter life.
- E-commerce and direct-to-consumer channels will play a larger role in product distribution and customer engagement.
- Emerging economies will offer strong growth opportunities due to inconsistent municipal water quality.
- Competitive intensity will remain high, with product differentiation and after-sales service shaping long-term market success.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Point of Use Water Treatment Systems, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Point of Use Water Treatment Systems market projected to grow between 2024 and 2032?
Which Point of Use Water Treatment Systems segment held the largest share in 2024?
What are the primary factors fueling the growth of the Point of Use Water Treatment Systems market?
Who are the leading companies in the Point of Use Water Treatment Systems market?
Which region commanded the largest share of the Point of Use Water Treatment Systems market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Point-of-Use Water Treatment Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Point-of-Use Water Treatment Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 35,118.6 million → 2032: USD 54,718.87 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Point-of-Use Water Treatment Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Point-of-Use Water Treatment Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Point-of-Use Water Treatment Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Point-of-Use Water Treatment Systems Market Drivers
- 3.3 Point-of-Use Water Treatment Systems Market Restraints & Challenges
- 3.4 Point-of-Use Water Treatment Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Point-of-Use Water Treatment Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Point-of-Use Water Treatment Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Point-of-Use Water Treatment Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Point-of-Use Water Treatment Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Point-of-Use Water Treatment Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Point-of-Use Water Treatment Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Point-of-Use Water Treatment Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Point-of-Use Water Treatment Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Point-of-Use Water Treatment Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Point-of-Use Water Treatment Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Point-of-Use Water Treatment Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Point-of-Use Water Treatment Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Point-of-Use Water Treatment Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Point-of-Use Water Treatment Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Point-of-Use Water Treatment Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Point-of-Use Water Treatment Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Point-of-Use Water Treatment Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Point-of-Use Water Treatment Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Point-of-Use Water Treatment Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
