
Market Overview
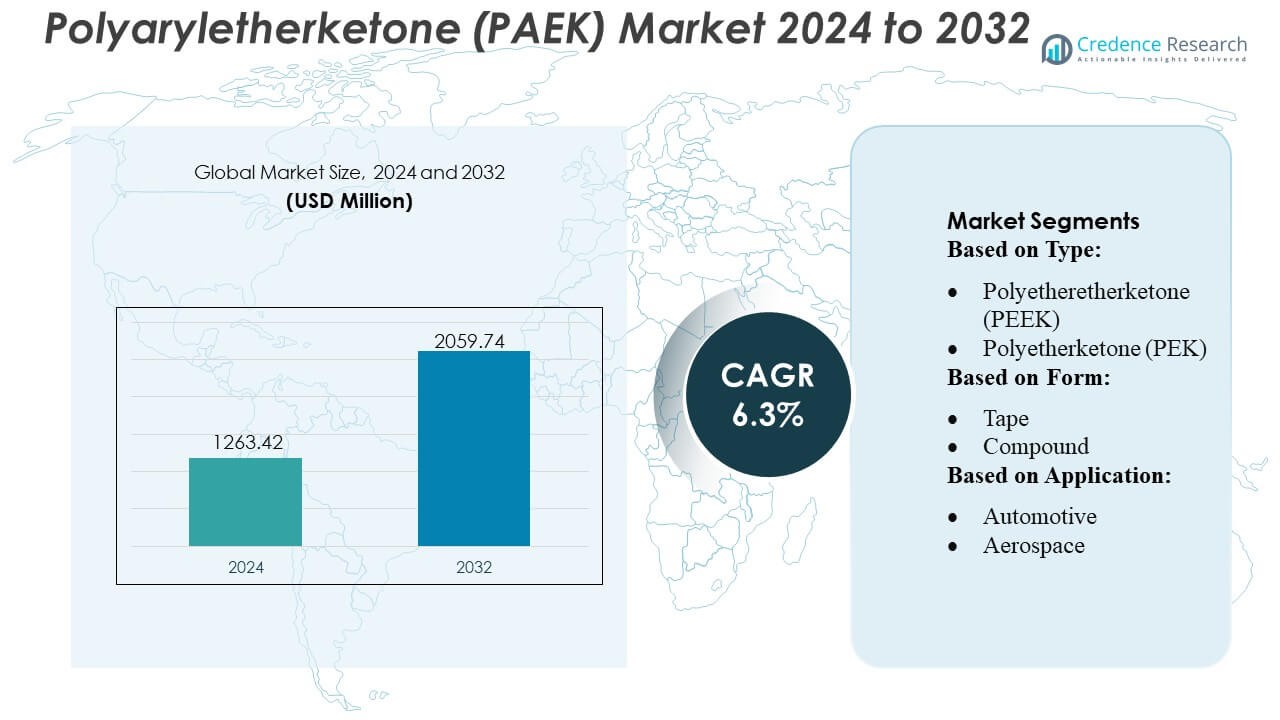
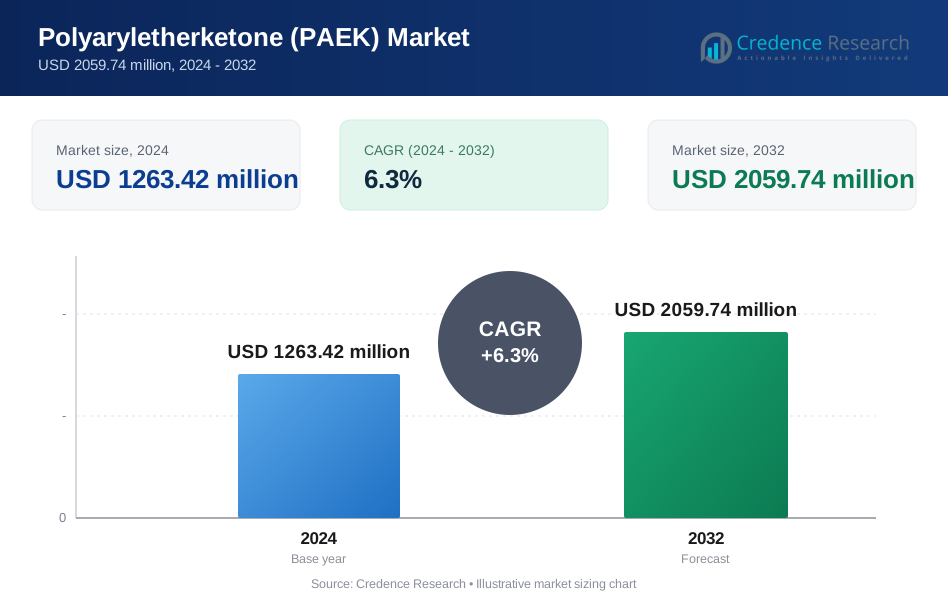
Polyaryletherketone (PAEK) Market size was valued USD 1263.42 million in 2024 and is anticipated to reach USD 2059.74 million by 2032, at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polyaryletherketone (PAEK) Market Size 2024 | USD 1263.42 Million |
| Polyaryletherketone (PAEK) Market, CAGR | 6.3% |
| Polyaryletherketone (PAEK) Market Size 2032 | USD 2059.74 Million |
The Polyaryletherketone (PAEK) market is highly competitive, led by prominent players such as Arkema, RTP Company, Evonik Industries, Gharda Chemicals Ltd, Mitsubishi Chemical Advanced Materials, Solvay, Akro Plastic GmbH, Ensinger, Victrex plc, and SABIC. These companies focus on innovation, advanced polymer processing, and strategic expansions to strengthen their global presence. North America and Europe remain key markets, with Europe leading the global PAEK market, accounting for approximately 38% of total revenue. The region benefits from mature aerospace, automotive, and medical industries, coupled with stringent quality standards that drive high adoption of high-performance polymers. Companies continue to invest in research and development to deliver customized, high-performance PAEK solutions, address specific industry requirements, and expand production capacities, positioning themselves to capture growing demand across aerospace, automotive, electronics, and healthcare sectors worldwide.
Market Insights
- The Polyaryletherketone (PAEK) market was valued at USD 1263.42 million in 2024 and is expected to reach USD 2059.74 million by 2032, growing at a CAGR of 6.3% during the forecast period.
- Market growth is driven by rising demand in aerospace, automotive, medical devices, and electronics, where high-performance, heat-resistant, and lightweight polymers are increasingly required.
- Trends include the adoption of advanced polymer processing technologies, development of customized PAEK solutions, and increasing use in 3D printing and additive manufacturing applications.
- The market is highly competitive, with key players focusing on innovation, capacity expansion, strategic collaborations, and global presence to capture demand across major industries.
- Regionally, Europe leads with approximately 38% market share, followed by North America and Asia-Pacific, while segments such as PEEK dominate by type, and tape and sheets lead by form, reflecting industry-specific application preferences.
Market Segmentation Analysis:
By Type
In the PAEK market, Polyetheretherketone (PEEK) dominates the type segment, capturing a significant market share due to its exceptional thermal stability, chemical resistance, and mechanical strength. PEKK and PEK are gaining traction in high-performance applications, but PEEK remains preferred in aerospace, medical, and automotive industries. The growth is driven by increasing demand for lightweight, durable materials capable of withstanding extreme conditions. For instance, PEEK is widely adopted in aerospace structural components and medical implants, supporting prolonged service life and reduced maintenance requirements, making it the cornerstone of the PAEK type segment.
- For instance, PEEK typically features a melting point of about 343 °C and sustains continuous service temperatures up to ~260 °C without significant loss of mechanical integrity.
By Form
Among various forms, PAEK compounds and sheets are the leading sub-segments, offering versatility in processing and manufacturing. Compounds provide tailored mechanical and thermal properties suitable for high-load applications, while sheets enable precision machining for complex parts. Tape and fiber forms are witnessing increased adoption in additive manufacturing and reinforced composites. Growth is fueled by the need for high-performance, lightweight components across automotive and aerospace sectors. For instance, PAEK sheets are extensively used in aircraft interior panels, combining strength with weight reduction, establishing compounds and sheets as dominant in the form segment.
- For instance, RTP Company’s PEEK‑based structural compounds with carbon fiber reinforcement have demonstrated tensile strength around 172 MPa and flexural strength near 252 MPa when injection‑molded, validating their suitability for demanding applications requiring durability and stiffness under load.
By Application
In the filler segment, carbon-filled PAEK leads the market due to enhanced mechanical strength, stiffness, and wear resistance, crucial for demanding applications like aerospace and automotive structural components. Glass-filled PAEK provides improved dimensional stability and heat resistance, while unfilled PAEK remains preferred for medical and chemical applications requiring purity and biocompatibility. Market expansion is driven by increasing demand for materials capable of replacing metals in high-performance engineering applications. For instance, carbon-filled PAEK composites are used in engine components and lightweight structural parts, accounting for the largest share in the filler segment.
Key Growth Drivers
- Rising Demand in Aerospace and Automotive Sectors The PAEK market is driven by increasing adoption in aerospace and automotive industries, where lightweight, high-strength, and heat-resistant materials are essential. PAEK’s ability to replace metals in structural components reduces weight while maintaining durability, enhancing fuel efficiency and performance. For instance, PEEK-based composites are used in aircraft interior panels and engine components, offering long-term reliability under extreme temperatures. Expanding production of electric vehicles also fuels demand, as PAEK materials support high-performance battery housings and motor components, further propelling market growth.
- For instance, Evonik’s VESTAKEEP PEEK perform exceptionally under rigorous aerospace and automotive demands. For instance, VESTAKEEP PEEK exhibits a continuous‑use temperature above 260 °C and retains mechanical integrity even after long exposure to steam, hot oil, or gamma sterilization.
- Growth of Medical and Healthcare Applications Medical applications significantly contribute to PAEK market growth due to the material’s biocompatibility, chemical resistance, and sterilization capability. PAEK-based implants, surgical instruments, and dental devices are increasingly preferred over traditional metals and polymers. For instance, PEEK spinal implants are widely used for their durability and reduced risk of rejection, ensuring long-term patient outcomes. The rising geriatric population and advancements in minimally invasive surgical techniques further drive adoption, positioning medical applications as a key growth catalyst in the global PAEK market.
- For instance, Gharda Chemicals’ G‑PAEK™ grades support more than 1,000 autoclave sterilization cycles while retaining mechanical integrity and dimensional stability, making them suitable for reusable surgical instruments and medical device housings.
- Advancements in Additive Manufacturing and Processing Technologies Technological innovations in 3D printing and polymer processing are expanding PAEK applications across industries. High-performance PAEK filaments and powders enable complex, lightweight, and customized components with reduced production time and cost. For instance, aerospace manufacturers are increasingly using PEKK-based 3D-printed parts for structural and functional components, achieving precise tolerances and high mechanical strength. Continuous improvements in processing methods, such as injection molding and extrusion, enhance material efficiency, surface finish, and dimensional accuracy, driving broader adoption and accelerating market growth.
Key Trends & Opportunities
- Expansion in Electrical and Electronics Applications The PAEK market is witnessing growth in electronics, driven by increasing demand for high-performance insulating materials in semiconductors, connectors, and circuit boards. Its thermal stability, dielectric strength, and flame retardancy make it ideal for compact and high-temperature electronic devices. For instance, PEEK films are utilized in flexible circuits and high-speed connectors, enhancing reliability and performance. Rising adoption of miniaturized devices, EV components, and advanced consumer electronics offers substantial opportunities for market players to diversify applications and strengthen presence in the electrical and electronics segment.
- For instance, Mitsubishi Chemical Advanced Materials offers PEEK‑based films that deliver a dielectric strength of about 18.9 kV/mm (short-term, ASTM D149) ensuring robust insulation even under high-voltage stress.
- Integration of Sustainable and Recyclable Materials Sustainability trends present opportunities for PAEK producers to innovate with recyclable and environmentally friendly materials. PAEK’s durability and reusability reduce lifecycle environmental impact compared to metals. For instance, some manufacturers are developing recyclable PEEK and PEKK compounds suitable for automotive and aerospace components, aligning with circular economy goals. Increasing regulatory focus on reducing industrial carbon footprints encourages adoption of high-performance recyclable polymers, providing a competitive advantage for companies emphasizing sustainable materials in engineering and high-performance applications.
- For instance, Solvay’s in Georgia now source 100% renewable electricity for production of PEEK base polymers, underlining the company’s commitment to lowering carbon footprint in manufacturing.
 Key Challenges
- High Raw Material and Manufacturing Costs The high cost of monomers and complex processing methods limits PAEK adoption, particularly in cost-sensitive applications. Manufacturing PAEK components involves specialized equipment, high-temperature processing, and precision control, which increase production expenses. For instance, PEEK compounding and machining require advanced facilities to maintain mechanical integrity, constraining entry for smaller manufacturers. These costs restrict use in mass-market applications, compelling companies to focus on high-value industries like aerospace, automotive, and medical devices, which can absorb the premium pricing of PAEK materials.
- Limited Awareness and Technical Expertise Limited awareness of PAEK’s properties and insufficient technical expertise pose barriers to market expansion, particularly in emerging regions. End-users may prefer conventional polymers or metals due to familiarity and lower processing complexity. For instance, designers in industrial sectors often lack knowledge of PAEK’s high-temperature tolerance, chemical resistance, and mechanical advantages, leading to underutilization. Addressing these knowledge gaps through technical training, collaborative projects, and demonstration of material benefits is critical for accelerating adoption and maximizing the market potential globally.
Regional Analysis
North America
North America holds approximately 33% of the global PAEK market, driven by robust demand in aerospace, automotive, medical devices, and electronics. The United States dominates the region, supported by advanced manufacturing capabilities, extensive R&D investments, and a strong focus on innovation in high-performance materials. Aerospace manufacturers increasingly use PAEK for lightweight and heat-resistant components, while medical device producers adopt it for surgical instruments and implants due to biocompatibility. Stringent regulatory frameworks and industry standards ensure high-quality production, supporting sustained growth. The region also benefits from collaborations between material suppliers and end-use industries, strengthening market penetration and technological adoption.
Europe
Europe is the largest PAEK market globally, holding around 38% of total revenue. Key countries such as Germany, France, and the UK lead demand, driven by mature automotive and aerospace sectors that require lightweight, heat-resistant, and durable materials. The medical device industry also contributes significantly due to strict quality and certification standards. European manufacturers emphasize research and development to enhance polymer performance, durability, and cost efficiency. Adoption of PAEK in precision engineering, industrial machinery, and electronics is rising steadily. Strong environmental regulations and initiatives to reduce carbon footprint further support PAEK usage in lightweight and energy-efficient components.
Asia-Pacific
Asia-Pacific represents about 24% of the global PAEK market and is the fastest-growing region. Growth is led by China, Japan, South Korea, and India, where increasing industrialization, expanding automotive and electronics manufacturing, and rising medical device production fuel demand. Governments’ focus on high-tech industries, including aerospace and renewable energy, promotes adoption of high-performance polymers like PAEK. Industrial sectors increasingly utilize PAEK for thermal, chemical, and mechanical stability in demanding applications. Rapid infrastructure development, coupled with a rising middle class and urbanization, further encourages polymer adoption. Local manufacturing and collaborations with global suppliers strengthen the region’s position in the global market.
Latin America
Latin America accounts for a smaller share of the PAEK market, though demand is gradually increasing. Brazil leads the region in automotive, aerospace, and industrial equipment applications, supported by expanding industrial and infrastructure projects. Growing investments in high-performance polymers aim to improve manufacturing efficiency and product durability. Adoption is also influenced by rising awareness of lightweight materials for energy-efficient vehicles and aerospace components. Limited local production is supplemented by imports, creating opportunities for global suppliers. Regional governments’ focus on industrial modernization and technological upgrades is expected to drive further PAEK adoption over the coming years, despite current market penetration being modest.
Middle East & Africa
The Middle East and Africa currently hold a minor share of the PAEK market. Key demand stems from oil & gas infrastructure, industrial equipment, and medical applications in countries such as Saudi Arabia, UAE, and South Africa. Industries are increasingly seeking high-performance, heat- and corrosion-resistant polymers for demanding operational environments. Market growth is supported by government investments in industrial modernization and infrastructure expansion. While adoption remains limited compared to North America, Europe, and Asia-Pacific, strategic partnerships with global polymer suppliers and increasing awareness of PAEK’s advantages suggest a gradual rise in market presence in the region over the next several years.
Market Segmentations:
By Type:
- Polyetheretherketone (PEEK)
- Polyetherketone (PEK)
By Form:
- Tape
- Compound
By Application:
- Automotive
- Aerospace
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Polyaryletherketone (PAEK) market include Arkema, RTP Company, Evonik Industries, Gharda Chemicals Ltd, Mitsubishi Chemical Advanced Materials, Solvay, Akro Plastic GmbH, Ensinger, Victrex plc, and SABIC. the Polyaryletherketone (PAEK) market is driven by innovation, technological advancements, and strategic expansion initiatives. Companies are investing heavily in research and development to enhance polymer performance, including thermal stability, chemical resistance, and mechanical strength, catering to demanding applications in aerospace, automotive, medical devices, and electronics. Market participants are also focusing on expanding manufacturing capacities and adopting advanced processing techniques to meet rising global demand efficiently. Strategic collaborations, partnerships, and acquisitions are increasingly used to strengthen market presence, access new technologies, and enter emerging regional markets. Additionally, the development of customized PAEK solutions for specific end-use requirements and the emphasis on sustainability and energy-efficient production processes are shaping competition. Continuous innovation and responsiveness to evolving industry needs remain key differentiators, ensuring companies maintain a competitive edge in this high-performance polymer market.
Key Player Analysis
- Arkema
- RTP Company
- Evonik Industries
- Gharda Chemicals Ltd
- Mitsubishi Chemical Advanced Materials
- Solvay
- Akro Plastic GmbH
- Ensinger
- Victrex, plc
- SABIC
Recent Developments
- In November 2024, Avient Corporation launched Colorant Chromatics Transcend, featuring new biocompatible PEEK (Polyether-ether-ketone) compounds and colorants for high-performance medical devices, highlighting their focus on healthcare innovation and sustainable materials.
- In April 2024, 3D Systems, Inc., an additive manufacturing solutions supplier, announced receiving Food and Drug Administration (FDA) 510(k) clearance for the VSP PEEK Cranial Implant. This newly designed offering comprises a patient-specific cranial implant that features Evonik VESTAKEEP i4 3DF Polyetheretherketone (PEEK).
- In October 2023, Evonik introduces the world's first carbon-fiber reinforced PEEK filament for long-term 3D printed medical implants VESTAKEEP® i4 3DF Implant, for long-term 3D printed medicinal implants.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for PAEK is expected to grow steadily across aerospace, automotive, and electronics sectors.
- Increasing adoption in medical devices and surgical instruments will drive market expansion.
- Asia-Pacific is likely to emerge as a high-growth region due to industrialization and infrastructure development.
- Technological advancements in polymer processing will enhance product performance and application scope.
- Manufacturers will focus on developing customized PAEK solutions for specific industry requirements.
- Strategic collaborations and partnerships will strengthen global market presence and innovation capabilities.
- Rising demand for lightweight and energy-efficient materials will support PAEK adoption in transportation.
- Expansion of production capacities will ensure better supply and meet growing industrial needs.
- Sustainability initiatives and environmentally friendly production processes will influence market strategies.
- Continuous R&D investments will drive the development of advanced, high-performance PAEK materials.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polyaryletherketone (PAEK) Market and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polyaryletherketone (PAEK) Market projected to grow between 2025 and 2032?
Which Polyaryletherketone (PAEK) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polyaryletherketone (PAEK) Market?
Who are the leading companies in the Polyaryletherketone (PAEK) Market?
Which region commanded the largest share of the Polyaryletherketone (PAEK) Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Polyaryletherketone (PAEK) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Polyaryletherketone (PAEK) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1263.42 million → 2032: USD 2059.74 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Polyaryletherketone (PAEK) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Polyaryletherketone (PAEK) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Polyaryletherketone (PAEK) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Polyaryletherketone (PAEK) Market Drivers
- 3.3 Polyaryletherketone (PAEK) Market Restraints & Challenges
- 3.4 Polyaryletherketone (PAEK) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Polyaryletherketone (PAEK) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Polyaryletherketone (PAEK) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Polyaryletherketone (PAEK) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Polyaryletherketone (PAEK) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Polyaryletherketone (PAEK) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Polyaryletherketone (PAEK) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Polyaryletherketone (PAEK) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Polyaryletherketone (PAEK) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Polyaryletherketone (PAEK) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Polyaryletherketone (PAEK) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Polyaryletherketone (PAEK) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Polyaryletherketone (PAEK) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Polyaryletherketone (PAEK) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Polyaryletherketone (PAEK) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Polyaryletherketone (PAEK) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Polyaryletherketone (PAEK) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Polyaryletherketone (PAEK) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Polyaryletherketone (PAEK) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Polyaryletherketone (PAEK) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
