
Market Overview:
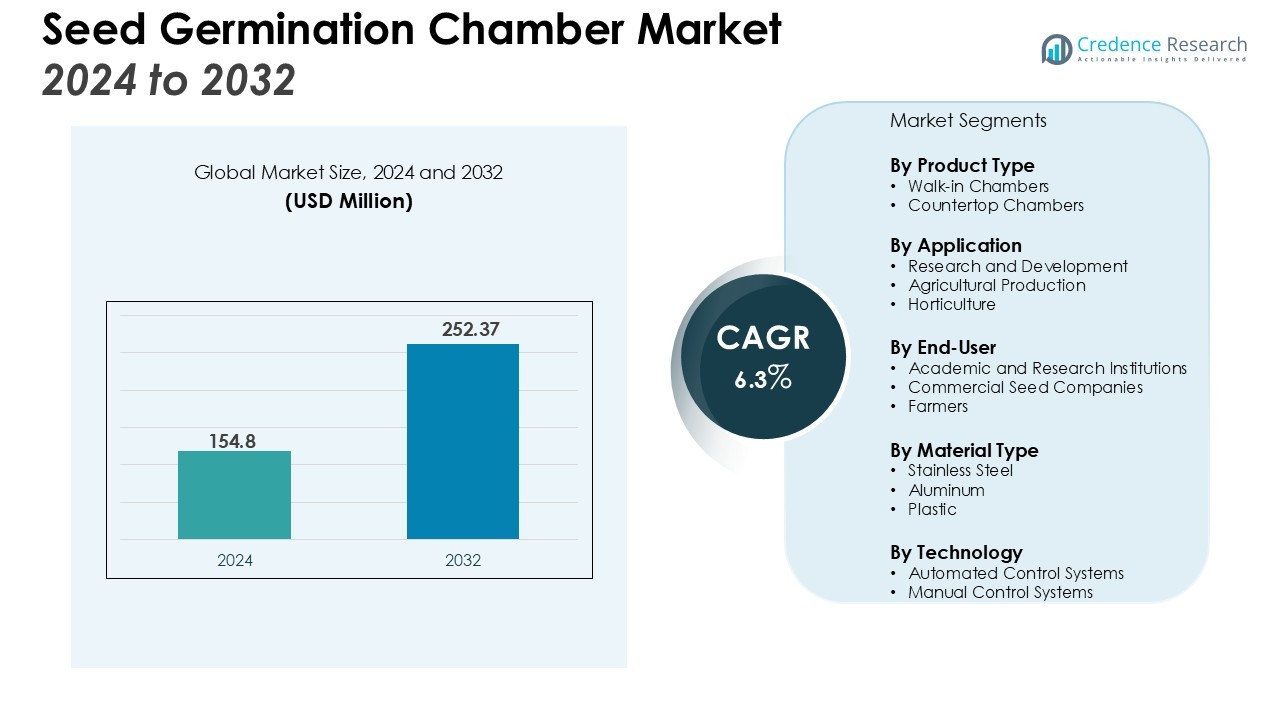
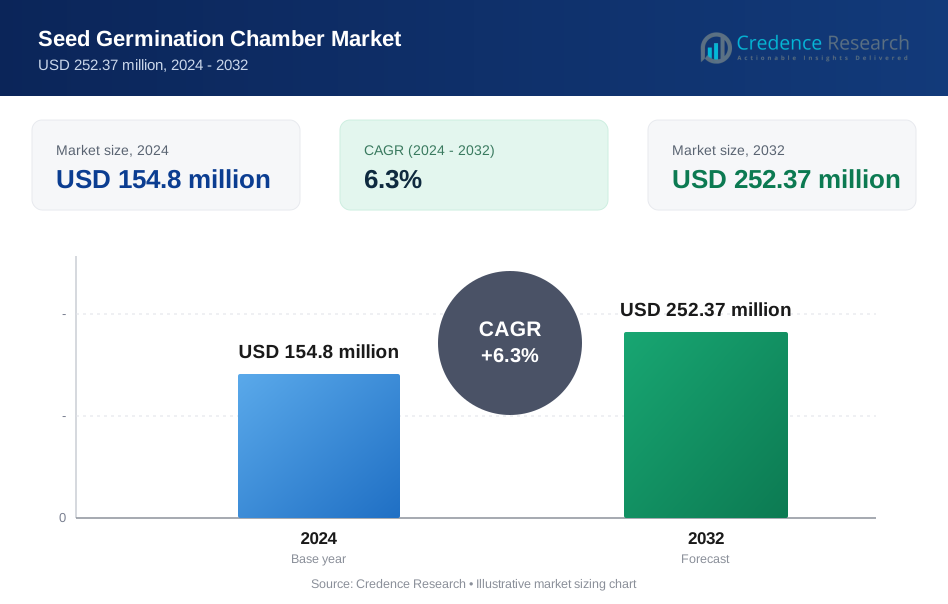
The Seed Germination Chamber Market size was valued at USD 154.8 million in 2024 and is anticipated to reach USD 252.37 million by 2032, at a CAGR of 6.3 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Seed Germination Chamber Market Size 2024 | USD 154.8 Million |
| Seed Germination Chamber Market, CAGR | 6.3 % |
| Seed Germination Chamber Market Size 2032 | USD 252.37 Million |
Key drivers of market growth include the rising global need for food security, which demands high-quality seeds for improved crop yields. The increasing focus on agricultural research and development and the growing trend of urban farming and vertical agriculture are also fueling market expansion. Furthermore, the development of eco-friendly and energy-efficient seed germination chambers is attracting attention from both commercial and research sectors, contributing to sustainable farming practices.
Regionally, North America holds the largest share in the Seed Germination Chamber market, driven by advancements in agricultural technology and strong research and development activities. Europe follows with substantial demand for these chambers, especially in agricultural research. The Asia-Pacific region is expected to witness the highest growth, attributed to the rising agricultural practices in countries like China and India, which are investing heavily in modern farming technologies.
Market Insights:
- The Seed Germination Chamber market size was valued at USD 154.8 million in 2024 and is expected to reach USD 252.37 million by 2032, growing at a CAGR of 6.3%.
- The growing demand for high-quality seeds to improve crop yields is driving the market’s expansion, as chambers ensure consistent and efficient seed germination.
- Agricultural research and technological advancements significantly boost the demand for seed germination chambers to improve seed resilience and crop genetics.
- The rise of urban farming and sustainable agriculture is increasing the adoption of seed germination chambers for efficient food production in urban environments.
- Government initiatives and funding for agricultural innovation are fostering market growth, especially in developing regions aiming to modernize farming techniques.
- High initial investment and operational costs remain a challenge, particularly for small-scale farmers and regions with limited access to capital.
- North America leads the market with a 30% share, followed by Europe at 25%, and the Asia Pacific region is witnessing significant growth with a 20% share.
Market Drivers:
Increasing Global Demand for High-Quality Seeds for Enhanced Crop Yields
The growing need for high-quality seeds to improve agricultural productivity is a primary driver for the Seed Germination Chamber market. These chambers provide controlled environments that optimize seed growth, ensuring better quality seeds that can withstand varying environmental conditions. As the global population rises, the demand for efficient and high-yield crops is escalating, prompting the adoption of advanced technologies like seed germination chambers. These technologies ensure uniform germination rates, which are critical for maximizing crop productivity.
- For instance, Thermo Fisher Scientific's Model 846 Plant Growth Chamber provides a 396-liter capacity for botanical research and seed germination studies.
Focus on Agricultural Research and Technological Advancements
The expansion of agricultural research and development significantly impacts the Seed Germination Chamber market. With the increasing emphasis on improving crop genetics and resilience, controlled seed germination environments play a crucial role in experimentation. Research institutions and universities rely on seed germination chambers to replicate various environmental conditions, enhancing the development of seeds that are resistant to pests, diseases, and extreme climates. Innovations in chamber technologies, such as automation and precision controls, further drive the demand for these chambers.
- For instance, Conviron’s GEN1000-GE seed germinator offers a 781-liter capacity for high-throughput research applications.
Rise of Urban Farming and Sustainable Agriculture Practices
Urban farming and the growing interest in sustainable agriculture are also contributing to the market’s growth. Seed germination chambers are becoming essential for urban farmers who lack traditional soil-based cultivation methods. These chambers facilitate the indoor cultivation of seeds in a controlled environment, supporting local food production in urban areas. The increasing focus on sustainable farming practices encourages the adoption of energy-efficient and eco-friendly seed germination technologies, thereby boosting the market demand.
Government Initiatives Supporting Agricultural Innovation
Governments worldwide are investing in agricultural innovation to ensure food security and enhance farming efficiency. Various policies and initiatives, such as subsidies and funding for research projects, promote the adoption of advanced agricultural technologies, including seed germination chambers. These initiatives encourage the use of technology-driven solutions that improve crop production and farming sustainability. The support from government bodies accelerates the market growth, especially in developing regions where agricultural modernization is underway.
Market Trends:
Technological Advancements and Integration of Automation in Seed Germination Chambers
The Seed Germination Chamber market is experiencing significant technological advancements, particularly in automation and digitalization. Chambers now feature automated temperature, humidity, and light control systems that offer precise regulation of environmental conditions, improving seed germination consistency. The integration of IoT (Internet of Things) technologies allows real-time monitoring and remote control of these parameters, enhancing operational efficiency. These innovations contribute to better energy efficiency and lower operational costs, appealing to commercial growers and research institutions looking to optimize resources. With advanced sensors and automated systems, these chambers also ensure reproducibility in experiments, supporting breakthroughs in agricultural research and development.
- For instance, a new automatic monitoring system for seed germination tests, based on deep learning, was designed to improve breeding efficiency and can deliver detection results at a frame rate of not less than 10 frames per second.
Shift Towards Energy-Efficient and Sustainable Solutions in Seed Germination Chambers
Energy efficiency and sustainability are key trends shaping the Seed Germination Chamber market. Manufacturers are increasingly focusing on developing eco-friendly and energy-efficient chambers to align with the growing demand for sustainable agriculture practices. These chambers are designed to reduce energy consumption while maintaining optimal conditions for seed growth. The use of renewable energy sources, such as solar-powered systems, is gaining traction in these products, further promoting sustainability in agriculture. As environmental regulations become stricter and the global push for green technologies strengthens, demand for these energy-efficient seed germination chambers continues to rise.
- For instance, Conviron's GEN1000-ECO model is engineered for energy efficiency and rejects only 2,824 BTU/hr of heat into the surrounding room, which lessens the strain on a facility's air conditioning system.
Market Challenges Analysis:
High Initial Investment and Operational Costs
One of the primary challenges in the Seed Germination Chamber market is the high initial investment required for purchasing and setting up these systems. While the technology offers significant benefits in seed quality and yield, the upfront costs can be prohibitive for small-scale farmers and research institutions. The operational costs associated with maintaining optimal conditions, such as electricity consumption for temperature control and lighting, also add to the financial burden. These costs can deter potential buyers from adopting seed germination chambers, especially in developing regions where access to capital is limited. The market’s growth could be constrained by this financial barrier.
Lack of Awareness and Limited Access in Emerging Markets
In emerging markets, limited awareness about the benefits of seed germination chambers poses a significant challenge. Many farmers in these regions continue to rely on traditional farming methods, unaware of the advantages that controlled seed germination can offer. The lack of proper education, training, and access to modern agricultural technologies hampers market adoption. Furthermore, limited access to suppliers and service providers in these regions can make it difficult for potential users to invest in these systems, slowing the market's expansion in these key areas.
Market Opportunities:
Growing Adoption of Urban Farming and Controlled Agriculture
The Seed Germination Chamber market has significant growth potential due to the increasing adoption of urban farming and controlled agriculture. As cities grow and available agricultural land decreases, urban farming has emerged as a viable solution for local food production. Seed germination chambers are integral to urban farms, providing the ideal environment for seed growth in limited spaces. These chambers allow urban farmers to grow crops efficiently indoors, making them a key component of sustainable food systems. The expansion of urban farming in cities worldwide presents a substantial opportunity for the seed germination chamber market, especially as consumers demand fresh, locally grown produce.
Rising Demand for Sustainable and Eco-Friendly Farming Solutions
Sustainable farming practices are gaining traction globally, offering new opportunities for the Seed Germination Chamber market. The increasing emphasis on environmentally friendly agriculture and eco-conscious practices has led to a greater demand for energy-efficient and sustainable farming technologies. Seed germination chambers that use renewable energy sources or employ energy-saving designs are in high demand. These systems support environmentally sustainable farming while enhancing seed germination rates, making them attractive to growers and research institutions aiming to reduce their environmental footprint. This trend towards sustainability presents a significant opportunity for the market to cater to a growing base of environmentally conscious consumers.
Market Segmentation Analysis:
By Product Type
The Seed Germination Chamber market is primarily segmented into walk-in chambers and countertop chambers. Walk-in chambers dominate the market due to their ability to accommodate larger seed quantities and provide controlled environments for diverse applications. Countertop chambers are gaining traction in research and educational sectors for their compact design and cost-effectiveness, catering to smaller-scale operations.
By Application
Key applications of seed germination chambers include research and development, agricultural production, and horticulture. Research and development hold the largest share, as these chambers are essential for testing seeds, studying genetics, and advancing agricultural technologies. Agricultural production uses seed germination chambers to enhance seed quality, ensuring higher crop yields. Horticulture also plays a significant role, as these chambers support seedling growth and plant propagation in controlled environments.
- For instance, for high-throughput research applications, Conviron's GEN1000-GE chamber can be equipped with up to 15 total shelves to maximize seed testing capacity.
By End-User
End-users in the Seed Germination Chamber market include academic and research institutions, commercial seed companies, and farmers. Research institutions are the largest consumers, utilizing these chambers for extensive studies on seed behavior and growth. Commercial seed companies rely on seed germination chambers to improve seed quality and productivity. Increasingly, farmers, particularly those involved in urban and vertical farming, are adopting these chambers to optimize crop production in limited spaces.
- For instance, Neversink Tools offers a tabletop germination chamber with an 8-gallon water reservoir, which is designed for professional gardeners and small-scale commercial growers.
Segmentations:
By Product Type
- Walk-in Chambers
- Countertop Chambers
By Application
- Research and Development
- Agricultural Production
- Horticulture
By End-User
- Academic and Research Institutions
- Commercial Seed Companies
- Farmers
By Material Type
- Stainless Steel
- Aluminum
- Plastic
By Technology
- Automated Control Systems
- Manual Control Systems
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America: Market Leadership and Technological Advancements
North America holds the largest share of the Seed Germination Chamber market, accounting for 30%. The United States and Canada are key contributors, driven by advanced agricultural practices and strong research infrastructure. Numerous research institutions and commercial seed companies utilize seed germination chambers to enhance seed quality and crop yields. The region's focus on sustainable agriculture and technological innovation further supports market growth.
Europe: Strong Research Infrastructure and Adoption
Europe commands a significant portion of the Seed Germination Chamber market, contributing 25%. Countries like Germany, France, and the Netherlands are at the forefront, with robust agricultural research facilities and a high adoption rate of advanced agricultural technologies. The region's emphasis on sustainability and precision agriculture drives the demand for controlled-environment solutions like seed germination chambers.
Asia Pacific: Emerging Market with High Growth Potential
The Asia Pacific region holds a growing share of the Seed Germination Chamber market, with 20%. Countries such as China and India are investing heavily in agricultural innovation to meet the demands of their large populations. The increasing focus on food security, climate-resilient crops, and sustainable farming practices contributes to the rising adoption of seed germination chambers in the region.
Key Player Analysis:
- Phytotronics
- LEEC Limited
- Percival Scientific
- Conviron
- Biochambers
- Mech Air Industries
- Amax Scientific Instruments
- CARON Products
- Bionics Scientific
- Acmas Technologies
- Percival Scientific
Competitive Analysis:
The Seed Germination Chamber market is highly competitive, with key players like Conviron, Thermo Fisher Scientific, Percival Scientific, BINDER GmbH, and Weiss Technik leading the charge. These companies focus on product innovation, incorporating advanced features such as automated environmental controls, energy-efficient systems, and smart technology for real-time monitoring. To maintain competitive positioning, these firms pursue strategies like mergers, acquisitions, and technology integration, offering solutions that cater to the growing demand for sustainable and precise agricultural research. North America leads the market due to its strong research infrastructure, while the Asia-Pacific region is rapidly growing, driven by increased investments in modern farming technologies. Companies must adapt to these regional dynamics and technological trends to strengthen their presence in the evolving market.
Recent Developments:
- In April 2025, LEEC Limited launched its new Eco Drying Cabinets, which feature a 5-inch color touchscreen display.
- In June 2025, Bioness Medical, Inc. announced its acquisition of the assets and business of Harmonic Bionics, Inc., a move intended to enhance its portfolio of neuro-rehabilitation robotics.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, End-User, Material Type, Technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for seed germination chambers is expected to increase as the global focus on food security intensifies.
- Advancements in automation and smart technologies will drive the development of more efficient and user-friendly seed germination chambers.
- Increasing adoption of vertical and urban farming practices will further fuel the need for compact and energy-efficient chambers.
- Growing awareness about sustainable farming practices will lead to higher demand for eco-friendly and energy-efficient solutions.
- The agricultural sector's push toward climate-resilient crops will increase the need for controlled-environment solutions for seed germination.
- Research institutions will continue to be major end-users, as they require precise conditions for seed testing and genetic studies.
- Commercial seed companies will increasingly adopt these chambers to enhance seed quality and productivity across diverse crops.
- The expansion of agriculture in emerging markets, particularly in Asia Pacific, will contribute to significant market growth.
- Government support for agricultural innovation will create a favorable environment for the adoption of seed germination chambers in developing regions.
- Continued investments in technology, such as IoT integration and automated systems, will make seed germination chambers more affordable and accessible for small-scale farmers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Seed Germination Chamber, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Seed Germination Chamber market projected to grow between 2024 and 2032?
Which Seed Germination Chamber market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Seed Germination Chamber market?
Who are the leading companies in the Seed Germination Chamber market?
Which region commanded the largest share of the Seed Germination Chamber market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Seed Germination Chamber Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Seed Germination Chamber Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 154.8 million → 2032: USD 252.37 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Seed Germination Chamber Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Seed Germination Chamber Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Seed Germination Chamber Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Seed Germination Chamber Market Drivers
- 3.3 Seed Germination Chamber Market Restraints & Challenges
- 3.4 Seed Germination Chamber Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Seed Germination Chamber Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Seed Germination Chamber Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Seed Germination Chamber category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Seed Germination Chamber Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Seed Germination Chamber Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Seed Germination Chamber market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Seed Germination Chamber Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Seed Germination Chamber Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Seed Germination Chamber Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Seed Germination Chamber (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Seed Germination Chamber Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Seed Germination Chamber Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Seed Germination Chamber Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Seed Germination Chamber Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Seed Germination Chamber Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Seed Germination Chamber Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Seed Germination Chamber Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Seed Germination Chamber Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Seed Germination Chamber Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
