
Market Overview
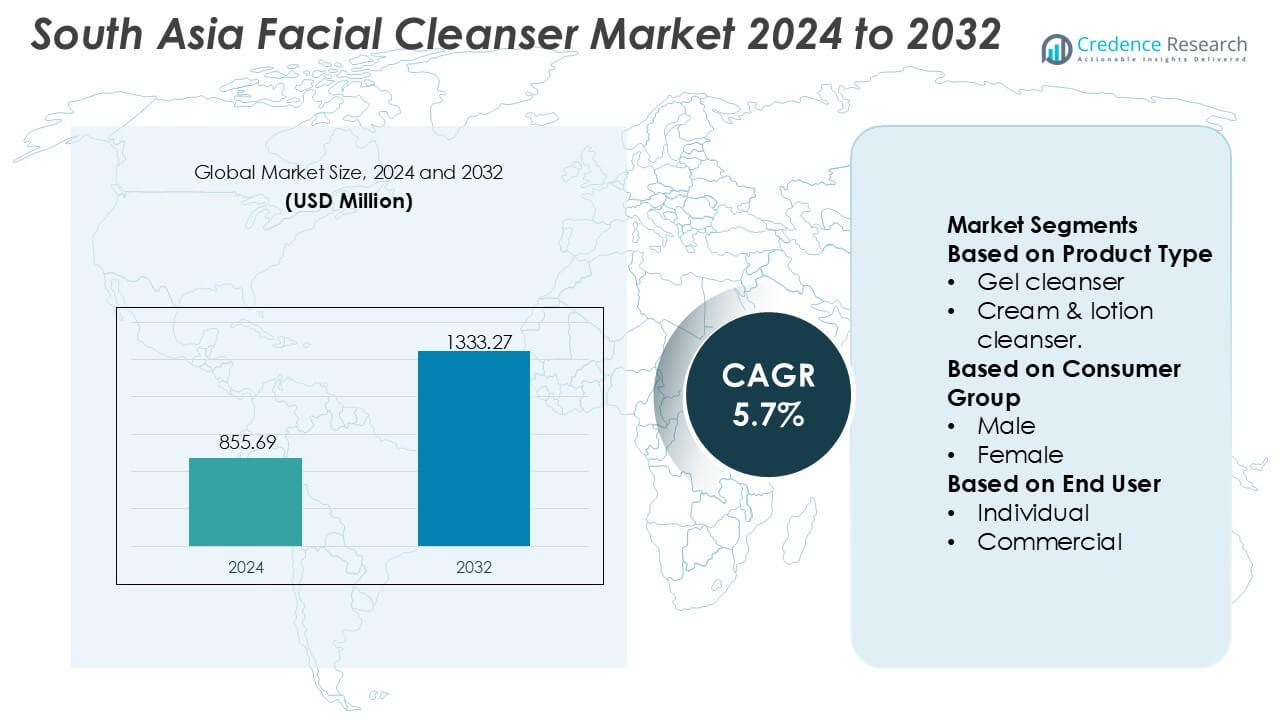
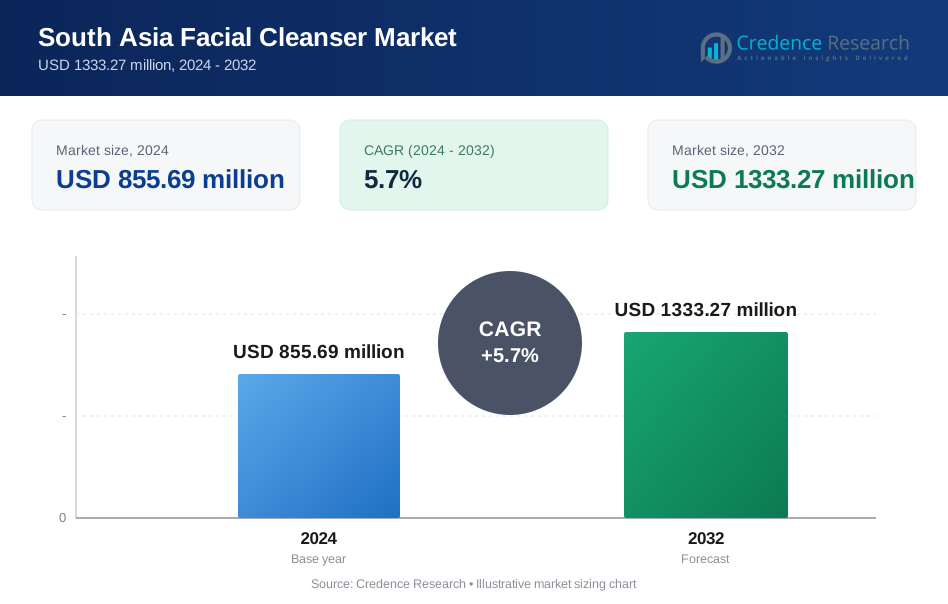
South Asia Facial Cleanser Market size was valued USD 855.69 million in 2024 and is anticipated to reach USD 1333.27 million by 2032, at a CAGR of 5.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Asia Facial Cleanser Market Size 2024 | USD 855.69 Million |
| South Asia Facial Cleanser Market, CAGR | 5.7% |
| South Asia Facial Cleanser Market Size 2032 | USD 1333.27 Million |
The South Asia Facial Cleanser Market features a competitive mix of global beauty conglomerates and regional personal-care manufacturers that strengthen product innovation, distribution depth, and brand visibility across diverse consumer groups. Leading companies leverage dermatologically tested formulations, natural ingredient portfolios, and e-commerce acceleration to enhance market penetration, while premium, mass, and herbal skincare segments continue to expand across urban and semi-urban areas. India holds the leading regional position with an exact 42% market share, supported by its large population base, fast-growing middle-income consumer segment, and strong retail infrastructure spanning modern trade, specialty beauty stores, and digital platforms.
Market Insights
- South Asia Facial Cleanser Market was valued at USD 855.69 million in 2024 and is projected to reach USD 1333.27 million by 2032 at a CAGR of 5.7%.
- Rising demand for herbal, gentle, and dermatologically tested formulations drives strong category uptake, with gel cleansers holding the dominant segment share due to their suitability for humid regional climates.
- Premiumization trends accelerate as consumers shift toward multifunctional and active-ingredient cleansers, while online channels expand accessibility and influence brand discovery across major cities.
- Competitive intensity increases as global and regional players strengthen R&D, expand natural ingredient lines, and deepen omnichannel strategies to capture higher-volume youth and working-professional segments.
- India leads the regional landscape with an exact 42% share, supported by diverse retail penetration and high skincare adoption, while Bangladesh and Sri Lanka show rising momentum driven by expanding urban middle-class populations and growing interest in affordable skincare solutions.
Market Segmentation Analysis:
By Product Type
Gel cleanser holds the dominant position with an estimated 34–36% share, supported by strong consumer preference for lightweight, non-comedogenic formats suited to humid South Asian climates and acne-prone skin profiles. Its compatibility with active ingredients such as salicylic acid and niacinamide strengthens adoption among young urban consumers seeking targeted solutions. Foaming cleansers follow closely due to their deep-cleansing appeal, while cream and lotion cleansers grow steadily among sensitive-skin users. Bar cleansers and other alternative formats maintain niche penetration, driven by affordability and rising interest in sustainable, low-waste packaging.
- For instance, Charlotte Tilbury validated the performance of its dual-phase cleansing system through a controlled user trial involving 209 participants, demonstrating measurable improvements in skin smoothness and residue removal, supported by laboratory assessments using 3 calibrated imaging devices to track texture refinement.
By Consumer Group
The female segment leads with roughly 55–57% market share, driven by high engagement with skincare routines, expanding premium beauty retail, and strong adoption of targeted formulations offering brightening, hydrating, and anti-pollution benefits. Rising social media influence, K-beauty trends, and increased dermatology consultations further reinforce segment dominance. The male category grows rapidly as grooming awareness improves and brands launch oil-control and active-rich cleansers tailored for thicker and more sebaceous skin. Unisex products gain traction among price-sensitive and minimalist consumers seeking versatile solutions, supported by e-commerce visibility and influencer-driven marketing.
- For instance, Shiseido validated the efficacy of its cleansing and skin-conditioning technologies through a controlled clinical study involving 116 women, supported by data generated from over 1,500 active global patents and more than 1,000 in-house researchers advancing skin biology and formulation science.
By End-User
The individual segment dominates with about 82–84% share, supported by rising daily skincare adoption, higher disposable incomes, and strong penetration of both mass and premium cleanser formats across urban and semi-urban markets. Personal-use consumption increases as consumers prioritize preventive skincare, anti-pollution cleansing, and active-based formulations suited for tropical conditions. The commercial segment including salons, dermatology clinics, and beauty service chains expands gradually as professional facial treatments gain popularity and branded cleansing systems become integrated into standardized service protocols, particularly in India, Sri Lanka, and Bangladesh.
Key Growth Drivers
Rapid Expansion of Skincare Awareness and Routine Adoption
Growing consumer awareness of structured skincare routines significantly strengthens facial cleanser demand across South Asia. Urban millennials and Gen Z increasingly adopt multi-step regimens influenced by dermatology guidance, beauty influencers, and K-beauty education. Rising concerns about pollution-induced dullness, acne, and oil imbalance accelerate daily cleansing habits. Expanding access to affordable mass-market products in India, Bangladesh, and Sri Lanka drives wider penetration, while premium international brands capture aspirational consumers seeking active-rich formulations designed for deep cleansing and surface barrier protection.
- For instance, Unilever advanced its cleanser performance research through a microbiome study involving 110 human volunteers and supported by its R&D network of five global research centres and more than 700 active skincare-related patents, enabling measurable improvements in barrier-friendly cleansing formulations.
Surge in E-Commerce and Digital Beauty Retail Penetration
Widespread smartphone adoption and rapid e-commerce expansion amplify cleanser accessibility across metros, tier-2 cities, and emerging peri-urban markets. Online platforms offer broader product variety, transparent reviews, and personalized recommendations that influence purchase decisions. Digital-first beauty brands scale quickly using influencer partnerships, sampling programs, and subscription-based delivery models. Algorithm-driven product matching and virtual skin diagnostics enhance consumer confidence, enabling targeted purchase behavior. This digital transformation boosts market efficiency, accelerates premiumization, and broadens reach across South Asia’s fragmented retail ecosystem.
- For instance, Kao Corporation strengthened its digital skincare ecosystem through its Sensai and Curél technology platforms, supported by over 1,000 active patents in skin science and AI-enabled diagnostics, and validated through internal usability testing involving more than 200 participants to refine algorithm-driven skin assessment accuracy.
Rising Demand for Dermatology-Backed and Active-Based Formulations
Growing skin concerns such as hyperpigmentation, acne, and sensitivity promote strong demand for dermatology-endorsed cleanser formats. Consumers increasingly prefer formulations featuring salicylic acid, niacinamide, hyaluronic acid, and ceramides tailored to tropical climates and humidity-driven sebum imbalance. Dermatologist-led content and clinical claims strengthen category credibility, encouraging adoption of pH-balanced and mild surfactant systems. Pharmaceutical skincare brands expand their presence in retail and e-commerce, reinforcing the shift toward performance-based cleansers that support long-term skin health and preventive care.
Key Trends & Opportunities
Premiumization and Clean Beauty Acceleration
Premium facial cleansers gain traction as consumers seek elevated sensorial experiences, safe formulations, and clinically validated outcomes. The shift toward sulfate-free, paraben-free, and fragrance-free products fuels clean-beauty momentum across South Asia. Brands invest in botanical extracts, microbiome-friendly ingredients, and transparent labeling to meet rising expectations around purity and safety. This trend creates strong opportunities for global and regional brands to introduce high-margin lines positioned around skin barrier repair, pollution defense, and sustainable ingredient sourcing.
- For instance, L’Oréal Group advanced clean-beauty formulation science through its Green Sciences program, supported by over 4,000 researchers and more than 500 green-chemistry patents, and validated cleanser efficacy using instrumental testing with 12 high-precision biometrology devices to quantify improvements in skin tolerance and barrier function.
Growing Adoption of Men’s Grooming and Unisex Formulations
Male grooming evolves rapidly as men increasingly prioritize oil control, acne reduction, and deep cleansing solutions suited to active lifestyles and humid climatic conditions. Brands introduce dedicated men’s cleanser lines supported by sports endorsements and targeted digital campaigns. At the same time, demand for unisex cleansers increases among minimalistic consumers seeking simplified routines and cost-efficient skincare products. This dual trend offers opportunities for portfolio diversification, enabling brands to address both gender-specific solutions and universal, multi-skin-type formulations.
- For instance, Amorepacific enhanced its men’s and unisex formulation platforms through clinical evaluations involving 72 male participants and instrumental sebum–reduction testing conducted with four high-resolution dermatological imaging systems, supported by the company’s R&D infrastructure of over 500 active skin science patents.
Expansion of Dermatology Clinics and Professional Skincare Services (Optional third trend)
Professional skincare services expand in major South Asian cities, strengthening demand for specialized cleansing systems used in salons, aesthetic clinics, and dermatology centers. Increased adoption of facials, chemical peels, and deep-cleansing treatments promotes the need for high-performance professional-grade cleansers. This ecosystem enables brands to partner with clinics, build credibility, and influence consumer product choices post-treatment.
Key Challenges
Price Sensitivity and Limited Premium Penetration in Rural Markets
High price sensitivity in rural and semi-urban areas restricts widespread adoption of premium or active-rich cleansers. Consumers in these regions prefer multifunctional or traditional cleansing solutions such as soap bars due to affordability and familiarity. Limited awareness of ingredient benefits and lower retail availability further restrict premium segment growth. Brands must adapt pricing strategies, invest in localized education, and expand distribution networks to improve penetration and strengthen consumer trust.
Intense Competition and Product Saturation Across Price Tiers
The market faces heavy competition from multinational brands, regional manufacturers, and rapidly emerging D2C players, leading to overcrowded product portfolios across all price points. Frequent launches of similar formulations challenge differentiation and compress margins. High promotional intensity on e-commerce platforms drives pricing pressure, reducing long-term profitability. Brands must focus on innovation, clinical validation, and targeted positioning to stand out within a saturated landscape and sustain consumer loyalty.
Regional Analysis
North America
North America holds an estimated 18–20% share of the global facial cleanser landscape, driven by high adoption of dermatology-backed formulations and premium skincare routines. Consumers prioritize gentle, pH-balanced cleansers with clinically validated actives such as ceramides and AHAs, aligning with rising concerns around dryness, sensitivity, and pollution exposure. Strong retail penetration across pharmacies, specialty beauty stores, and e-commerce platforms strengthens category accessibility. Clean beauty, fragrance-free innovation, and dermatologist-recommended brands accelerate premium growth. The region’s mature regulatory environment and high disposable income further promote demand for advanced formulations and multifunctional cleansing systems.
Asia Pacific
Asia Pacific leads the global market with a dominant 42–45% share, supported by dense population clusters, strong beauty culture, and accelerated skincare adoption across China, India, Japan, and Southeast Asia. Rapid urbanization and pollution-driven skin concerns heighten interest in gel, foaming, and brightening cleansers. K-beauty and J-beauty trends heavily influence ingredient choices, encouraging demand for mild surfactants, botanical extracts, and active-based formulations. Expanding e-commerce ecosystems and influencer-driven discovery significantly boost consumer engagement. The region’s large youth demographic, along with growing male grooming participation, reinforces long-term growth momentum.
Europe
Europe accounts for roughly 20–22% market share, anchored by strong regulatory standards, high consumer awareness, and consistent demand for dermatologically tested formulations. Consumers prioritize skin-barrier-friendly cleansers free from sulfates, parabens, and synthetic fragrances, supporting the dominance of pharmacy-led brands. Heightened interest in sustainability encourages adoption of eco-friendly packaging and biodegradable surfactant systems. Mature retail infrastructure—including drugstores, supermarkets, and specialty beauty chains—supports stable category penetration. Rising preference for microbiome-focused and sensitive-skin formulations further shapes innovation pipelines across Western and Northern Europe.
Latin America
Latin America maintains an estimated 7–8% share, driven by growing skincare education and rising urban middle-class spending power. Consumers in Brazil, Mexico, and Argentina increasingly adopt daily cleansing routines to address oiliness, acne, and sensitivity caused by humid climates. Affordable mass-market gel and foaming cleansers remain dominant, while premium products gain traction through social media influence and dermatology-led recommendations. Expanding pharmacy retail, e-commerce access, and local beauty brands strengthen market presence. Economic fluctuations and price sensitivity, however, influence purchasing patterns, prompting brands to balance innovation with cost efficiency.
Middle East & Africa
The Middle East & Africa region captures around 6–7% market share, supported by rising disposable income, strong beauty consciousness, and expanding modern retail in GCC nations. High temperatures and pollution levels drive demand for deep-cleansing and oil-control formulations, particularly gel and foaming cleansers. Premium international brands benefit from strong penetration in UAE and Saudi Arabia, while emerging African markets adopt cleansers gradually through pharmacies and online platforms. Halal-certified skincare, fragrance-free options, and formulations tailored for sensitive and melanin-rich skin tones represent key growth opportunities across the region.
Market Segmentations:
By Product Type
- Gel cleanser
- Cream & lotion cleanser.
By Consumer Group
- Male
- Female
By End User
- Individual
- Commercial
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The South Asia Facial Cleanser Market is shaped by a diverse competitive ecosystem led by Charlotte Tilbury, Shiseido Company, Limited, Unilever, Kao Corporation, L’Oréal Group, Amorepacific, e.l.f. Cosmetics, Procter & Gamble, L'Occitane Groupe S.A., and Estée Lauder Companies, Inc. The South Asia Facial Cleanser Market features an increasingly competitive environment shaped by global beauty majors, regional manufacturers, and fast-growing digital-first brands. Companies strengthen their positions through continuous innovation in gel, foaming, and active-based formulations tailored to the region’s humid climate and pollution-driven skin concerns. Premiumization intensifies competition as consumers seek dermatologist-tested, pH-balanced, and clean-label products that deliver visible results. E-commerce platforms amplify this rivalry by enabling rapid product launches, influencer-led discovery, and algorithm-driven personalization. Local brands compete effectively through value-driven pricing and culturally relevant formulations, while professional skincare channels further influence consumer preferences. This dynamic landscape drives faster innovation cycles, diversified product portfolios, and deeper retail penetration across South Asia.
Key Player Analysis
- Charlotte Tilbury
- Shiseido Company, Limited
- Unilever
- Kao Corporation
- L’Oréal Group
- Amorepacific
- l.f. Cosmetics
- Procter & Gamble
- L'Occitane Groupe S.A.
- Estée Lauder Companies, Inc.
Recent Developments
- In May 2025, Meta was developing "super sensing" for its next-gen smart glasses (codenamed Aperol/Bellini), an AI feature allowing cameras/sensors to stay on, enabling real-time recognition of people/objects, and offering context-aware reminders like finding keys or reminding about groceries, though battery drain was a challenge.
- In May 2025, New Orleans Police Department (NOPD) was in the news for using and seeking to expand its facial recognition (FRT) system, primarily through the private Project NOLA network, scanning faces for criminal suspects, sparking debate over its effectiveness, privacy violations, potential for bias, and its role in driving the broader FRT market, despite significant civil liberties concerns and existing city ordinances.
- In June 2024, Google's Security & Resilience Services (GSRS) team began testing a facial tracking system at its Kirkland, Washington, campus to identify unauthorized individuals and enhance security, comparing live feeds to employee badge photos, a move that sparked employee privacy concerns despite Google's assurances that data isn't stored long-term.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Consumer Group, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market expands steadily as daily skincare routines become more entrenched across urban and semi-urban populations.
- Demand for dermatologist-tested and active-based cleansers strengthens as consumers seek targeted solutions for acne, pigmentation, and sensitivity.
- Clean beauty and sulfate-free, pH-balanced formulations gain broader traction as safety and transparency influence purchasing behavior.
- E-commerce platforms play a larger role in product discovery, personalization, and rapid adoption of new formulations.
- Premiumization accelerates as consumers shift toward clinically validated, high-performance cleansing systems.
- Male grooming continues to grow, driving demand for oil-control and deep-cleansing formats tailored to regional climatic conditions.
- Niche segments such as microbiome-friendly, vegan, and eco-certified cleansers witness rising interest among younger consumers.
- Brands expand localized formulations to address humidity, pollution, and tropical skin concerns across diverse markets.
- Professional skincare channels influence product credibility and stimulate demand for science-backed cleanser ranges.
- Competitive intensity increases as global, regional, and digital-first brands expand portfolios and strengthen omnichannel reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the South Asia Facial Cleanser Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the South Asia Facial Cleanser Market projected to grow between 2024 and 2032?
Which South Asia Facial Cleanser Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the South Asia Facial Cleanser Market?
Who are the leading companies in the South Asia Facial Cleanser Market?
Which region commanded the largest share of the South Asia Facial Cleanser Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 South Asia Facial Cleanser Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global South Asia Facial Cleanser Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 855.69 million → 2032: USD 1333.27 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 South Asia Facial Cleanser Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. South Asia Facial Cleanser Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 South Asia Facial Cleanser Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 South Asia Facial Cleanser Market Drivers
- 3.3 South Asia Facial Cleanser Market Restraints & Challenges
- 3.4 South Asia Facial Cleanser Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 South Asia Facial Cleanser Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 South Asia Facial Cleanser Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, South Asia Facial Cleanser category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 South Asia Facial Cleanser Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. South Asia Facial Cleanser Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the South Asia Facial Cleanser market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 South Asia Facial Cleanser Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 South Asia Facial Cleanser Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 South Asia Facial Cleanser Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in South Asia Facial Cleanser (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New South Asia Facial Cleanser Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global South Asia Facial Cleanser Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America South Asia Facial Cleanser Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe South Asia Facial Cleanser Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific South Asia Facial Cleanser Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America South Asia Facial Cleanser Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East South Asia Facial Cleanser Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa South Asia Facial Cleanser Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. South Asia Facial Cleanser Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
