
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Casino Tourism Market Size 2024 | USD 15,472 million |
| UK Casino Tourism Market, CAGR | 6.4% |
| UK Casino Tourism MarketSize 2032 | USD 25,414 million |
Market Overview
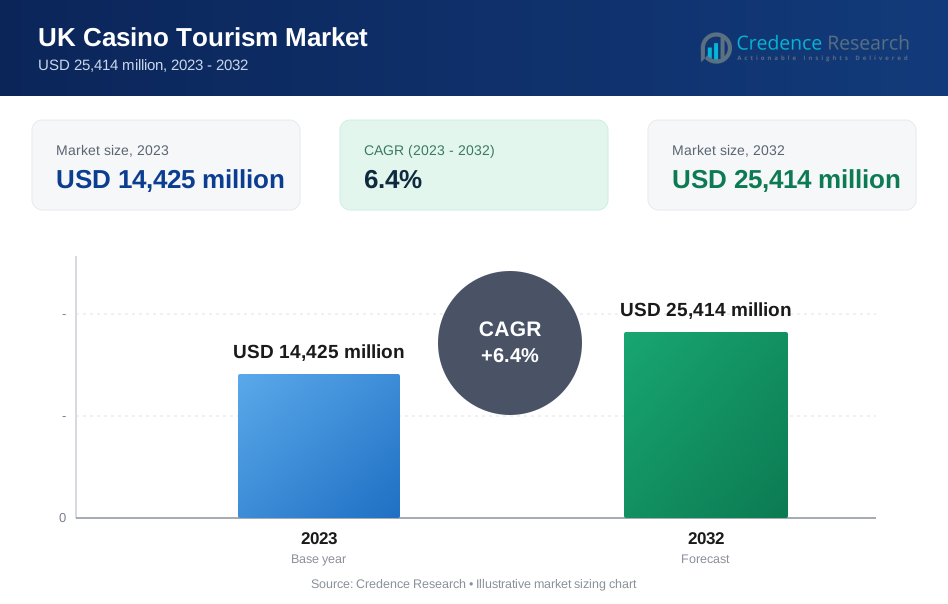
The UK Casino Tourism Market is projected to grow from USD 15,472 million in 2024 to an estimated USD 25,414 million based on 2032, with a compound annual growth rate (CAGR) of 6.4% from 2025 to 2032.
Key drivers supporting this growth include the rising acceptance of gambling as mainstream entertainment, expansion of integrated resort casinos, and supportive government policies that enhance tourism infrastructure. Trends such as the incorporation of digital technologies, including virtual reality gaming and cashless payment systems, are transforming visitor experiences. Additionally, the combination of gaming with cultural events, nightlife, and culinary attractions is boosting the appeal of UK casino destinations to a wider audience, particularly among younger travelers and high-net-worth individuals.
Regionally, London remains the hub of casino tourism, driven by its luxury resorts and accessibility to international travelers. Other cities such as Birmingham, Manchester, and Edinburgh are also witnessing rising demand due to localized investments and urban redevelopment. Key players shaping the UK casino tourism market include The Rank Group, Aspers Group, Genting Casinos UK, Caesars Entertainment EMEA, and Metropolitan Gaming. These firms are leveraging modern amenities and strategic partnerships to enhance visitor engagement and capitalize on the growing influx of global tourists seeking premium gaming experiences.
Market Insights
- The UK Casino Tourism Market is projected to grow from USD 15,472 million in 2024 to USD 25,414 million by 2032, at a CAGR of 6.4% from 2025 to 2032.
- Growing demand for integrated resort experiences combining gaming, luxury accommodations, and entertainment boosts market expansion.
- Government support for tourism infrastructure and relaxed regulations strengthens investor confidence and promotes growth.
- Increased acceptance of gambling among younger demographics and high-net-worth individuals supports wider market appeal.
- Stringent licensing regulations and high compliance costs challenge new entrants and limit rapid expansion.
- Economic pressures and cost-of-living concerns may reduce discretionary spending on casino tourism.
- England dominates with over 65% market share, led by London, while growth is emerging in cities like Birmingham, Manchester, and Edinburgh.
Market Drivers
Rising Popularity of Integrated Resorts Enhancing Visitor Appeal
The UK Casino Tourism Market benefits significantly from the expansion of integrated resorts that combine gaming with entertainment, hospitality, and retail. These venues attract tourists by offering a complete leisure experience, including fine dining, live performances, and luxury accommodations. This convergence of services creates high visitor engagement and encourages extended stays, increasing overall tourism revenue. Operators continue to invest in property upgrades and diversified attractions to remain competitive. The integration of wellness centers, shopping experiences, and event spaces into casino resorts supports broad consumer appeal. It positions the UK as a dynamic destination for both gaming and non-gaming tourists.
- For instance, The Hippodrome Casino in London welcomed over 1,000,000 visitors in a single year following the addition of new entertainment venues and dining options, showcasing the draw of integrated resort experiences
Government Support and Infrastructure Improvements Fuel Market Expansion
Public and private investments in transport connectivity, urban redevelopment, and cultural promotion strengthen the UK Casino Tourism Market. Government initiatives to stimulate inbound tourism and support entertainment-based economies have made licensing and compliance frameworks more efficient. Improved airport access, rail links, and digital infrastructure enhance the overall tourist journey. Regulatory transparency increases investor confidence, encouraging new casino developments and foreign partnerships. Events like the London Tourism Recovery Plan also stimulate targeted marketing efforts to draw international visitors. These efforts create a favorable environment for sustainable market growth.
- For instance, the UK government’s London Tourism Recovery Plan included over 50 new infrastructure and marketing projects launched in 2024 to boost international visitor arrivals and support casino tourism growth
Shifting Consumer Preferences Toward Experiential Tourism
The UK Casino Tourism Market aligns with evolving traveler preferences that favor immersive, personalized experiences over traditional sightseeing. Casinos increasingly incorporate unique entertainment formats, exclusive memberships, and interactive gaming zones. This shift responds to a new generation of tech-savvy and experience-driven tourists. Experiences such as themed gaming nights, culinary festivals, and esports tournaments enhance engagement. Casinos position themselves not only as gambling venues but also as cultural and entertainment hubs. This evolution reflects changing consumer expectations and drives consistent tourist interest.
Technology Integration Elevating Customer Experience
Innovation in casino operations and customer engagement plays a crucial role in shaping the UK Casino Tourism Market. Properties deploy advanced technologies like digital table games, mobile-based rewards, and facial recognition for seamless access and personalization. These tools increase operational efficiency and elevate guest satisfaction. The use of big data analytics helps casinos tailor services based on visitor behavior and spending patterns. Cashless payment systems and digital booking platforms enhance convenience and appeal to international travelers. By embracing technology, the market continues to attract a diverse and modern audience.
Market Trends
Growing Demand for Luxury Casino Experiences Among International Tourists
The UK Casino Tourism Market is witnessing increased demand for high-end, luxury experiences tailored to affluent travelers. International visitors seek premium gaming environments that offer exclusivity, privacy, and upscale services. Casinos are responding by introducing VIP lounges, private gaming suites, and concierge services that elevate the visitor experience. High-spending tourists from the Middle East, Asia, and North America are driving growth in this segment. These travelers often combine casino visits with cultural exploration and luxury shopping. The trend strengthens the market's position within the global premium tourism sector.
- For instance, international tourists now account for approximately 30 out of every 100 casino visitors in the UK, with London’s Hippodrome Casino reporting thousands of VIP bookings annually from travelers originating in the US, China, and the Gulf States
Expansion of Non-Gaming Attractions Enhancing Market Reach
Casinos in the UK increasingly diversify their offerings by incorporating non-gaming entertainment to appeal to broader audiences. The UK Casino Tourism Market benefits from the integration of live music venues, fine dining restaurants, and art exhibitions. These attractions draw visitors who may not be primarily interested in gambling but seek a well-rounded entertainment experience. It supports longer guest stays and boosts ancillary revenues. Family-friendly facilities and seasonal events also expand the demographic profile of casino visitors. This trend broadens market reach and enhances brand loyalty.
- For instance, the non-remote casino sector in the UK generated £810.4 million in gross gambling yield in the latest reporting period, with a notable increase attributed to expanded offerings such as live music and themed events at major venues.
Adoption of Digital Technology Transforming Guest Engagement
Technology plays a growing role in shaping customer interactions and operational efficiency within the UK Casino Tourism Market. Casinos adopt mobile apps for loyalty programs, digital check-ins, and in-venue navigation. Virtual and augmented reality features add interactive elements to gaming and entertainment. It creates immersive experiences that resonate with younger, tech-savvy travelers. Online booking tools and dynamic pricing models also optimize guest traffic. This digital shift supports enhanced customer service and sustained visitor interest.
Rise of Sustainable and Responsible Tourism Practices
Environmental and social responsibility trends influence business strategies in the UK Casino Tourism Market. Operators adopt eco-friendly practices including energy-efficient lighting, waste reduction, and sustainable sourcing. Responsible gambling programs are now integrated into customer service strategies to promote safe gaming. It improves public perception and strengthens community relations. Green certifications and transparent sustainability reports help casinos align with evolving consumer values. These practices appeal to environmentally conscious tourists and improve long-term brand credibility.
Market Challenges
Regulatory Restrictions and Licensing Complexity Hindering Market Agility
The UK Casino Tourism Market faces significant challenges from complex regulatory frameworks and licensing procedures. Frequent policy reviews and stringent compliance requirements slow down new project approvals and deter smaller operators. It limits flexibility for casinos to quickly adapt to changing consumer expectations or introduce innovative offerings. Taxation policies on gambling revenues also reduce profitability margins, impacting investment decisions. Local opposition to casino expansion in certain regions further complicates market penetration. These factors collectively create barriers to growth and delay modernization efforts.
- For instance, in 2024, over 60% of new casino license applications in the UK faced delays exceeding 6 months due to regulatory reviews, while Remote Gaming Duty collected from gambling operators reached £1.2 billion, and in 2023, 25% of proposed casino expansions were rejected by local councils due to community opposition.
Economic Volatility and Shifts in Consumer Spending Patterns
Economic uncertainty and fluctuating disposable income levels influence the performance of the UK Casino Tourism Market. High inflation, currency volatility, and cost-of-living pressures affect both domestic and international tourist spending behavior. It leads to more cautious travel budgets and reduced expenditure on premium leisure activities such as casino visits. Unforeseen events like geopolitical tensions or pandemics disrupt travel flows and business continuity. Rising operational costs for labor, utilities, and security further strain profit margins. These economic dynamics force operators to reassess pricing, promotions, and investment plans.
Market Opportunities
Rising International Tourist Influx Creating Revenue Growth Potential
The UK Casino Tourism Market stands to benefit from the steady increase in international tourist arrivals driven by relaxed visa rules, improved air connectivity, and global marketing campaigns. Tourists from Asia and the Middle East show strong interest in premium leisure and gaming experiences. It creates an opportunity to design culturally tailored services and multilingual support systems. London remains a top destination, but emerging interest in secondary cities can diversify revenue sources. Targeted promotional packages and casino-tourism bundles can attract high-value travelers. This trend supports expansion beyond traditional markets and strengthens the UK's global tourism position.
Digital Integration and Data Analytics Enhancing Customer Experience
Adopting digital technologies offers new growth avenues for the UK Casino Tourism Market. It can use customer data analytics to personalize services, optimize loyalty programs, and refine marketing strategies. The integration of mobile apps, virtual concierge systems, and automated service tools enhances visitor convenience. These innovations appeal to younger demographics and encourage repeat visits. Developing partnerships with fintech and travel platforms can streamline payment processes and improve booking experiences. Embracing digital transformation helps casinos remain competitive in a fast-evolving tourism environment.
Market Segment Analysis
By Casino Type
The UK Casino Tourism Market shows strong dominance in the land-based casino segment, supported by established venues in cities like London, Manchester, and Birmingham. It attracts both domestic and international visitors with premium services and luxury environments. Cruise ship casinos contribute niche growth by offering gaming as part of high-end travel experiences. Online casinos are gaining momentum with digital transformation, appealing to tourists who seek remote access to casino entertainment. The segment allows operators to engage with travelers before and after physical visits.
- For instance, in the fiscal year ending March 2023, the UK’s land-based gambling sector generated £4.5 billion in gross gambling yield, with 186 fewer land-based premises compared to the previous year, highlighting the strength and resilience of established physical casinos despite market consolidation
By Target Audience
High-net-worth individuals drive substantial revenue through exclusive gaming packages, personalized services, and VIP programs. The mass market tourist segment maintains volume growth through broad accessibility and value-based offerings. Business travelers contribute to weekday footfall, often visiting casinos during conferences or corporate events. The UK Casino Tourism Market caters to diverse traveler profiles with tailored experiences and pricing strategies. Each audience segment plays a critical role in balancing revenue across seasons.
- For instance, as of April 2025, there are approximately 29 million active gamblers in the UK engaging in various forms of online and offline gambling, reflecting the broad reach and diversity of the casino tourism audience
By Purpose of Visit
Gaming and entertainment remains the leading purpose of visit, supported by high-quality game offerings and immersive environments. Socializing and networking draw tourists to casinos hosting events, performances, and private gatherings. Relaxation and leisure appeal to travelers seeking integrated resorts with spas, dining, and wellness options. It enables casinos to position themselves beyond gaming hubs. These varied visit purposes enhance guest retention and length of stay.
By Gaming Preference
Table games such as roulette and blackjack continue to dominate due to their cultural appeal and interactive nature. Slot machines offer accessibility and quick engagement for casual visitors. Video poker attracts experienced players seeking strategic gameplay. Sports betting grows with increasing demand for live event experiences and mobile integration. The UK Casino Tourism Market benefits from offering a diverse gaming mix that caters to all levels of player interest.
Segments
Based on Casino Type
- Land-Based Casinos
- Cruise Ship Casinos
- Online Casinos
Based on Target Audience
- High-Net-Worth Individuals
- Mass Market Tourists
- Business Travelers
Based on Purpose of Visit
- Gaming and Entertainment
- Socializing and Networking
- Relaxation and Leisure
Based on Gaming Preference
- Table Games (e.g., roulette, blackjack)
- Slot Machines
- Video Poker
Based on Region
- England
- Scotland
- Wales
- Northern Ireland
Regional Analysis
England Casino Tourism Market
England holds the largest share of the UK Casino Tourism Market, accounting for nearly 68% of total market revenue. London remains the central hub, home to prestigious venues such as The Ritz Club and Empire Casino. The city's appeal lies in its combination of luxury gaming, cultural heritage, and strong international connectivity. England attracts a diverse audience, including high-net-worth individuals and mass-market tourists. Strong infrastructure, hotel partnerships, and airport access support consistent tourist inflow. It continues to drive growth through integrated resorts and high-end services.
Scotland Casino Tourism Market
Scotland represents around 14% of the UK Casino Tourism Market and shows steady growth supported by major cities such as Edinburgh and Glasgow. Casinos in this region combine gaming with historic and scenic appeal, drawing cultural and leisure travelers. Operators in Scotland focus on personalized services, themed nights, and local entertainment to differentiate offerings. The market benefits from strong domestic tourism and government support for hospitality development. It attracts both short-stay visitors and longer leisure travelers. The segment’s contribution reflects its ability to blend tourism and entertainment.
Wales Casino Tourism Market
Wales accounts for approximately 9% of the UK Casino Tourism Market, supported by urban centers such as Cardiff and Swansea. The region targets mass-market tourists and regional travelers seeking accessible gaming options. Casinos here often integrate with entertainment venues and waterfront developments. Limited international reach restricts rapid growth, but domestic visitor engagement remains strong. It shows potential for future development through improved infrastructure and marketing. The Welsh government’s tourism strategies may unlock further opportunities.
Northern Ireland Casino Tourism Market
Northern Ireland contributes about 5% to the UK Casino Tourism Market and remains a small but emerging segment. Belfast serves as the focal point, offering mid-sized casino facilities and hospitality services. The region focuses on combining nightlife with casual gaming to attract younger demographics. Licensing regulations have restricted expansion compared to mainland UK, limiting operator presence. Tourist interest continues to grow through cultural festivals and sports tourism. It holds potential with policy reforms and strategic investments.
Key players
- SJM Holdings Limited
- Caesars Entertainment Corporation
- Las Vegas Sands Corp.
- Suncity Group Holdings Limited
- Macau Legend Development Limited
- Crown Resorts Limited
- Venetian Macau
- City of Dreams Macau
- Melco Resorts Entertainment Limited
- Marina Bay Sands
- Genting Berhad
- Galaxy Entertainment Group Limited
- MGM Resorts International
- Wynn Resorts, Limited
- NagaCorp Ltd.
Competitive Analysis
The UK Casino Tourism Market features increasing international competition, driven by global brands expanding presence through partnerships and licensing agreements. Major players such as Caesars Entertainment, Genting Berhad, and MGM Resorts International operate premium facilities or collaborate with UK-based establishments to access local demand. These companies differentiate through VIP offerings, integrated resorts, and loyalty programs. Domestic operators focus on regulatory alignment and personalized guest experiences to retain market share. The entry of Asian-based groups like Melco Resorts and Galaxy Entertainment indicates strategic interest in the European market. It remains competitive with innovation in customer engagement, technology integration, and high service standards defining long-term positioning.
Recent Developments
- In March 2025, SJM Holdings Limited reported a 35.9% year-on-year increase in gross gaming revenue, reaching USD 3.6 billion in 2024. This growth was primarily driven by the strong performance of Grand Lisboa Palace Resort Macau.
- In Q1 2025, MGM Resorts International reported an 8% increase in Las Vegas Strip casino revenue, supported by strong hotel performance and recovery in international visitation.
- In February 2025, Caesars Entertainment announced a $1 billion redevelopment plan for its Flamingo casino-hotel in Las Vegas. This plan focuses on enhancing the resort's appeal to experience-focused tourists, shifting the focus beyond traditional gaming. The redevelopment includes a new GO Pool, a $20 million renovation, targeting high-energy parties, and other potential amenities.
- In May 2025, Macau Legend Development Limited filed for an extension to continue operating its satellite casinos in Macau beyond the March 2025 regulatory deadline.
Market Concentration and Characteristics
The UK Casino Tourism Market exhibits moderate market concentration, with a mix of global brands and regional operators competing for diverse customer segments. It features a fragmented landscape where luxury casino resorts coexist with mid-size and boutique establishments. The market is characterized by high regulatory oversight, a strong emphasis on responsible gambling, and integration with broader tourism and hospitality sectors. Operators focus on personalized services, technology-driven experiences, and entertainment offerings to differentiate in a competitive environment. International collaborations and licensing agreements influence brand visibility and geographic reach. The market supports both high-end clientele and mass-market tourists, contributing to balanced revenue streams.
Report Coverage
The research report offers an in-depth analysis based on Casino Type, Target Audience, Purpose of Visit, Gaming Preference and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Operators will invest in large-scale integrated resorts combining casinos with hotels, shopping, and entertainment to attract broader tourist segments and boost longer stays.
- Partnerships with global brands will increase, allowing UK casinos to access international loyalty networks and enhance their appeal to overseas visitors.
- High-net-worth individuals will drive demand for exclusive gaming suites, personalized concierge services, and tailored luxury offerings across key casino destinations.
- Digital tools such as mobile gaming platforms, virtual reality features, and automated check-ins will improve customer convenience and operational efficiency.
- The legal sports betting segment will expand, while esports events integrated with casino venues will attract younger, tech-savvy travelers seeking entertainment diversity.
- Regions outside London, such as Manchester, Birmingham, and Glasgow, will experience increased investment in casino tourism infrastructure and localized marketing.
- Operators will adopt sustainable practices including green energy usage, waste reduction, and environmental certifications to align with evolving consumer values.
- Casinos will offer packages that include cultural experiences, fine dining, and wellness services to meet the growing preference for experiential travel.
- Government support for tourism and potential streamlining of licensing regulations may create new entry points for investors and accelerate market growth.
- The UK Casino Tourism Market will target a more diverse visitor base, including digital nomads, business travelers, and multi-generational tourist groups seeking leisure and gaming.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the UK Casino Tourism Market in 2023, and what are its projections for 2032 and CAGR?
What factors are driving the growth of the UK Casino Tourism Market?
How is technology impacting the UK Casino Tourism Market?
Who are the major players in the UK Casino Tourism Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Casino Tourism Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Casino Tourism Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 14,425 million → 2032: USD 25,414 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Casino Tourism Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Casino Tourism Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Casino Tourism Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Casino Tourism Market Drivers
- 3.3 UK Casino Tourism Market Restraints & Challenges
- 3.4 UK Casino Tourism Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Casino Tourism Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Casino Tourism Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Casino Tourism category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Casino Tourism Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Casino Tourism Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Casino Tourism market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Casino Tourism Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Casino Tourism Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Casino Tourism Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Casino Tourism (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Casino Tourism Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Casino Tourism Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Casino Tourism Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Casino Tourism Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Casino Tourism Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Casino Tourism Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Casino Tourism Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Casino Tourism Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Casino Tourism Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
