
Market Overview:
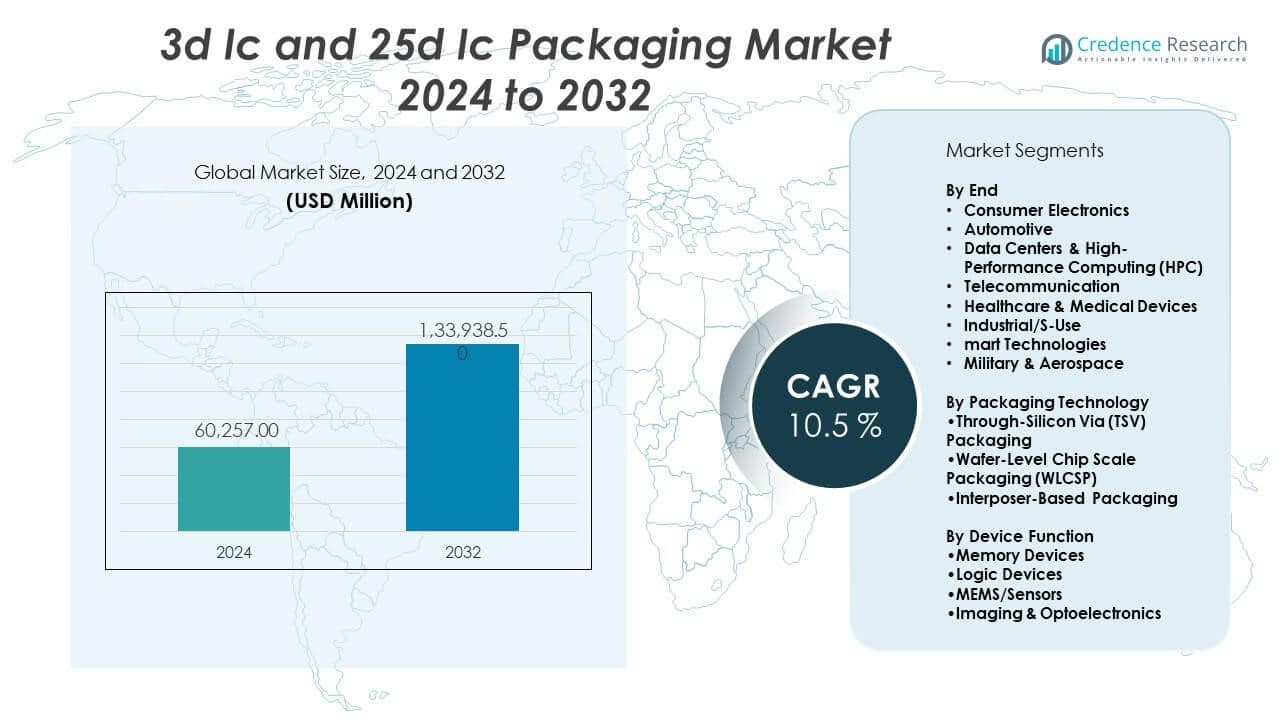
The 3D IC and 2.5D IC Packaging Market is projected to grow from USD 60,257 million in 2024 to an estimated USD 133938.5 million by 2032, with a compound annual growth rate (CAGR) of 10.5% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| 3D IC and 2.5D IC Packaging Market Size 2024 | USD 60,257 Million |
| 3D IC and 2.5D IC Packaging Market, CAGR | 10.5% |
| 3D IC and 2.5D IC Packaging Market Size 2032 | USD 133938.5 Million |
The 3D IC and 2.5D IC Packaging Market is fueled by rising demand for compact, high-performance electronics across mobile devices, data centers, and AI applications. Manufacturers are increasingly adopting advanced packaging techniques to overcome interconnect bottlenecks and enhance signal integrity. The proliferation of high-bandwidth memory and logic-memory integration also encourages the deployment of 2.5D interposers and 3D stacked die. The shift toward heterogeneous integration and low power consumption continues to accelerate investment in this sector. Ongoing R&D, growing chiplet usage, and demand for high-performance computing solutions significantly support this growth.
The 3D IC and 2.5D IC Packaging Market exhibits strong growth in Asia-Pacific, driven by leading semiconductor production in China, South Korea, Taiwan, and Japan. North America follows, supported by significant technological advancement and investment in AI and HPC infrastructure. Europe demonstrates steady demand fueled by the automotive and industrial sectors' push for compact, reliable electronics. Emerging regions in Latin America and the Middle East are witnessing growing interest due to expanding ICT infrastructure and industrial digitization efforts.
Market Insights:
- The 3D IC and 2.5D IC Packaging Market is projected to grow from USD 60,257 million in 2024 to an estimated USD 133938.5 million by 2032, with a compound annual growth rate (CAGR) of 10.5% from 2024 to 2032.
- High-performance computing and chiplet trends drive demand for advanced heterogeneous packaging.
- Thermal management and cost remain key challenges, especially in 3D stacked die production.
- Asia-Pacific leads the market, while North America is the fastest-growing due to AI and defense sectors.
- Fan-out and panel-level packaging techniques gain momentum for cost-effective scaling.
- Emerging markets invest in domestic semiconductor packaging ecosystems to boost self-reliance.
- AI-driven EDA and design automation tools enhance productivity in 3D and 2.5D IC packaging workflows.
Market Drivers:
Demand for Miniaturization:
The 3D IC and 2.5D IC Packaging Market is driven by the push for smaller, faster, and more efficient electronic devices. Consumer electronics and mobile devices demand compact solutions that integrate more functionality in smaller footprints. These advanced packaging formats enable stacking multiple dies vertically, improving speed and reducing power consumption. By integrating memory and logic components, manufacturers address space constraints without compromising performance. 3D IC technology is particularly beneficial for applications requiring low latency and high data throughput. 2.5D ICs, using interposers, provide a cost-effective middle ground with simplified thermal management. The growing deployment of IoT and wearable technology amplifies this demand. As more industries prioritize efficient, multi-functional chips, the market gains robust momentum.
- For instance, AMD’s Ryzen 7 5800X3D processor implements TSMC’s 3D V-Cache technology, stacking an additional 64MB of L3 cache vertically atop the chip, resulting in a total of 100MB cache capacity without increasing footprint or height.
High-Performance Computing Growth:
The 3D IC and 2.5D IC Packaging Market benefits from expanding applications in artificial intelligence, data centers, and advanced graphics processing. These technologies require massive parallel processing and high interconnect bandwidth. Traditional packaging technologies face limitations in meeting these demands. 3D ICs offer shorter interconnects, which enhance data transmission rates and reduce signal delay. The growing demand for chiplets and multi-die integration in GPUs and AI accelerators supports market expansion. 2.5D packaging, often used in FPGAs and ASICs, facilitates rapid communication between high-speed components. With continued advancements in machine learning workloads, semiconductor companies are heavily investing in this technology. Such investments underscore the critical role of advanced packaging in achieving computational efficiency.
- For instance, NVIDIA A100 Tensor Core GPUs utilize 2.5D packaging via TSMC’s CoWoS technology, bonding the GPU die with eight HBM2 memory stacks through an interposer.
Rising Use in Automotive Electronics:
The automotive sector increasingly incorporates 3D IC and 2.5D IC technologies in electric vehicles (EVs), ADAS systems, and in-vehicle infotainment. These applications require compact packaging solutions that ensure reliability under harsh environmental conditions. 3D ICs provide superior performance density needed for real-time data processing in autonomous systems. Thermal stability and signal integrity offered by advanced packaging address safety-critical automotive standards. As OEMs expand their electrification efforts, demand for semiconductors with greater functionality and less board space continues to grow. 2.5D ICs offer modularity and ease of testing, valuable traits for automotive-grade electronics. With growing regulatory support and rising EV sales, the adoption of these technologies in vehicles is accelerating. The automotive shift toward digital architectures directly supports this market’s development.
Integration with AI and Edge Devices:
The 3D IC and 2.5D IC Packaging Market aligns with the evolution of edge computing and AI-based devices. Devices deployed in smart homes, healthcare, and industrial settings demand high performance with localized data processing. 3D IC architecture enables AI accelerators to process data faster with reduced latency. This supports real-time analytics without relying on cloud connectivity. 2.5D ICs also contribute by allowing chiplets to integrate into application-specific solutions for inference engines. Faster data exchange between memory and processing units boosts energy efficiency and response time. With AI workloads shifting to the edge, packaging technologies are key enablers of innovation. This trend opens significant opportunities for tailored, scalable semiconductor solutions.
Market Trends:
Shift Toward Chiplet Architectures:
The 3D IC and 2.5D IC Packaging Market is seeing rapid adoption of chiplet-based designs to improve flexibility and reduce costs. By disaggregating SoCs into smaller chiplets, designers can use different process nodes in one package. This trend improves manufacturing yield and design modularity while supporting high-bandwidth die-to-die interconnects. 2.5D packaging allows chiplets to communicate via silicon interposers, reducing latency and increasing performance. Major players are investing in chiplet ecosystems to meet diverse application requirements. The reuse of proven chiplets accelerates time to market and reduces development risks. Chiplet standardization initiatives are also gaining momentum across industry consortia. This trend positions advanced packaging as essential for scalable semiconductor integration.
- For instance, Intel’s Foveros 3D packaging is at the core of its Meteor Lake processors, providing sub-50μm bump pitch and more than 400-1,600 micro-bump density per mm². Foveros allows heterogeneous chiplet integration with high interconnect density and low energy consumption, supporting integration of tiles built on different process nodes for scalability and modularity.
Adoption of Heterogeneous Integration:
The 3D IC and 2.5D IC Packaging Market is experiencing growth through heterogeneous integration, where logic, memory, RF, and analog components are co-packaged. This approach enables customization and performance optimization for specific use cases. 3D packaging supports stacking dissimilar technologies, essential for AI and sensor fusion applications. 2.5D ICs with passive and active interposers facilitate high-speed connections across different dies. The ability to blend diverse IP blocks enhances system capabilities without redesigning the entire SoC. This trend is especially strong in data centers and consumer electronics. Heterogeneous systems also support innovations in biomedical and industrial electronics. It expands the functional scope of packaged ICs while reducing board complexity.
- For instance, Xilinx (now AMD) utilizes 2.5D silicon interposer technology in its Virtex UltraScale+ FPGAs, connecting four FPGA dies and multiple HBM2 memory stacks, providing up to 460 GB/s aggregate memory bandwidth for cloud and networking workloads.
Growth in Fan-Out Packaging Techniques:
The 3D IC and 2.5D IC Packaging Market benefits from innovations in fan-out wafer-level packaging (FOWLP) and fan-out panel-level packaging (FOPLP). These approaches increase I/O density without relying on costly interposers. FOWLP enhances electrical performance while maintaining a small form factor. Fan-out technologies are ideal for mobile applications, sensors, and high-frequency RF components. 2.5D configurations also leverage fan-out to improve design flexibility and reduce thermal resistance. Panel-level packaging reduces cost per unit by using larger substrates. These advancements improve yield and simplify process flows in volume production. Their growing application base supports broader adoption across verticals.
AI-Driven Design and Testing Tools:
The 3D IC and 2.5D IC Packaging Market is incorporating AI-based tools in design, layout, and testing workflows. These tools improve efficiency by optimizing die placement, routing paths, and thermal management. AI enhances failure detection and yield prediction, reducing development cycles. Machine learning models support predictive analytics for packaging reliability under stress. 3D IC architectures benefit from simulation-assisted stacking alignment and TSV planning. EDA companies are developing specialized tools for packaging co-design across chip and system levels. AI integration into testing enables faster validation of heterogeneous packages. These tools are critical for maintaining quality standards while scaling production complexity.
Market Challenges Analysis:
High Cost and Manufacturing Complexity Limit Adoption:
The 3D IC and 2.5D IC Packaging Market faces significant cost barriers, especially for small- and mid-size semiconductor manufacturers. Fabrication of Through-Silicon Vias (TSVs), wafer thinning, and precise die stacking require advanced and expensive infrastructure. Yield loss during production, driven by defects in multi-die integration, raises total cost of ownership. Tooling, testing, and rework processes are more complex than in traditional packaging. For 2.5D ICs, high-quality interposers and alignment mechanisms also demand considerable investment. These factors limit widespread adoption and slow the transition from conventional system-on-chip designs. Efforts to reduce cost per package are ongoing, but ROI remains a challenge for entry-level adopters.
Thermal Management and Reliability Concerns Persist:
The 3D IC and 2.5D IC Packaging Market contends with issues related to heat dissipation and mechanical stress. Vertically stacked dies in 3D ICs generate hotspots that are difficult to cool using traditional heat sinks. Temperature gradients between layers can lead to thermal mismatch and impact long-term reliability. 2.5D ICs offer some relief due to planar design but still require careful thermal interface design. Failure mechanisms such as electromigration and delamination must be addressed in early design stages. Material choices, packaging layout, and TSV placement all influence reliability under operational stress. Advanced thermal modeling tools and materials are needed to ensure package stability across applications.
Market Opportunities:
Expansion into Emerging End-Use Sectors:
The 3D IC and 2.5D IC Packaging Market presents growth opportunities in underpenetrated sectors such as aerospace, healthcare, and defense. Applications in space electronics, implantable devices, and military-grade systems demand compactness and high reliability. Advanced packaging meets these demands by enabling multi-functional integration and low power consumption. Customized chiplets and stacked architectures support specific mission-critical tasks without redesigning the full package. OEMs in these verticals seek solutions that perform under extreme conditions and enable secure data processing. Regulatory bodies are endorsing semiconductor innovation for these sectors, further opening market entry points. Favorable R&D incentives and collaborations with specialized fabs are boosting the technology’s penetration. These factors signal a diversification in market use beyond consumer electronics.
Increased Investment in Domestic Semiconductor Ecosystems:
The 3D IC and 2.5D IC Packaging Market benefits from regional efforts to localize semiconductor supply chains. Government-backed funding programs in the U.S., EU, India, and Southeast Asia are driving investment in packaging innovation. These initiatives focus on building advanced packaging facilities as part of strategic independence goals. Domestic players are entering joint ventures and licensing deals to access mature 2.5D and 3D packaging capabilities. Such investments reduce reliance on traditional foundry hubs and mitigate geopolitical supply risks. Technology transfers and workforce development are strengthening local capabilities in high-density packaging. This creates an enabling environment for long-term growth and regional diversification. The market stands to benefit from sustained global funding into this critical area of semiconductor innovation.
Market Segmentation Analysis:
By End-Use
The 3D IC and 2.5D IC Packaging Market sees strong demand from consumer electronics, where smartphones, tablets, and wearables require compact, high-performance packaging. Automotive applications use it in ADAS, EVs, and autonomous systems to meet reliability and processing needs. Data centers and HPC leverage the technology to support high-bandwidth memory and reduce latency. In telecommunications, 5G infrastructure accelerates adoption due to bandwidth and efficiency demands. Healthcare benefits from miniaturized packaging for diagnostics and monitoring. Industrial automation and smart technologies prioritize space efficiency and durability. Military and aerospace sectors adopt these solutions for rugged, high-performance electronics.
- For instance, Samsung's Exynos chipsets for 5G smartphones utilize 2.5D packaging with ePoP (embedded Package on Package) technology, stacking DRAM and NAND on logic chips within a height of 1.4mm, bringing high performance and low power to compact devices.
By Packaging Technology
Through-Silicon Via (TSV) Packaging supports dense vertical interconnects essential for performance scaling in 3D and 2.5D ICs. Wafer-Level Chip Scale Packaging (WLCSP) enables compact, high-speed integration for consumer and industrial applications. Interposer-Based Packaging plays a central role in 2.5D designs, allowing efficient communication between logic and memory dies and supporting chiplet-based architectures.
- For instance, SK hynix’s HBM3 memory modules employ Through-Silicon Via (TSV) technology to achieve up to 819GB/s per 24GB stack at 6.4GT/s transfer speed and 1,024-bit interface. This dramatic bandwidth increase is essential for AI accelerators and high-performance computing, and HBM3 modules are now standard in flagship GPUs from NVIDIA and other leaders.
By Device Function
Memory devices, particularly HBM and DRAM, use both 3D and 2.5D configurations to enhance performance and reduce footprint. Logic devices, including CPUs and FPGAs, benefit from high interconnect density and power efficiency. MEMS and sensors integrated in medical, automotive, and mobile devices rely on these packaging methods to achieve miniaturization and durability. Imaging and optoelectronics combine multiple components, such as processors and sensors, into single modules using these advanced packaging approaches.
Segmentation:
By End-Use
- Consumer Electronics
- Automotive
- Data Centers & High-Performance Computing (HPC)
- Telecommunication
- Healthcare & Medical Devices
- Industrial/Smart Technologies
- Military & Aerospace
By Packaging Technology
- Through-Silicon Via (TSV) Packaging
- Wafer-Level Chip Scale Packaging (WLCSP)
- Interposer-Based Packaging
By Device Function
- Memory Devices
- Logic Devices
- MEMS/Sensors
- Imaging & Optoelectronics
By Region
- Asia-Pacific
- North America
- Europe
Regional Analysis:
Asia-Pacific:
Asia-Pacific leads the 3D IC and 2.5D IC Packaging Market with a market share of 38.5%. It benefits from robust semiconductor manufacturing infrastructure in Taiwan, South Korea, China, and Japan. Massive investments in consumer electronics, 5G infrastructure, and AI drive demand. Foundries such as TSMC and Samsung advance regional capabilities. This region remains the innovation hub for packaging R&D and high-volume production.
North America:
North America holds a 28.3% share in the 3D IC and 2.5D IC Packaging Market, with leadership in HPC, AI, and defense applications. The U.S. drives adoption via fabless design innovation and government support for semiconductor self-reliance. Leading players and consortia such as Intel and DARPA accelerate packaging advancements. With increasing domestic investment, the region is poised to expand its role in global value chains.
Europe and Rest of World:
Europe holds 17.2% market share, backed by automotive and industrial semiconductor consumption. Germany and France lead in automotive ADAS system demand using advanced packaging. Rest of the world, including Latin America and the Middle East, accounts for 16% share with growing telecom and defense investments. Emerging fabrication centers and tech alliances open future growth corridors for the global market.
Key Player Analysis:
- Taiwan Semiconductor Manufacturing Company (TSMC)
- Samsung Electronics
- Intel Corporation
- ASE Technology Holding Co., Ltd. (Advanced Semiconductor Engineering)
- Amkor Technology
- Broadcom
- Texas Instruments
- United Microelectronics Corporation (UMC)
- Siliconware Precision Industries Co., Ltd. (SPIL)
- JCET Group Co., Ltd.
- Powertech Technology Inc.
- ChipMOS Technologies
Competitive Analysis:
The 3D IC and 2.5D IC Packaging Market is moderately consolidated, with a mix of IDMs, foundries, and OSATs. Key players include TSMC, Intel, Samsung, ASE Group, Amkor Technology, and JCET. These firms invest in TSV, chiplet integration, and interposer solutions to capture demand from AI and high-performance computing. Collaborations with EDA vendors and system integrators enhance design-to-production workflows. The market relies heavily on vertical integration, IP portfolios, and geographic manufacturing strength to maintain competitiveness.
Recent Developments:
- In March 2025,Amkor Technology showcased its latest S-Connect™ packaging technology at IMAPS Device Packaging Conference. This solution allows seamless integration of multiple silicon dies within a single package, advancing miniaturization, flexibility, and performance for AI, 5G, and high-speed consumer applications.
- In early 2025,ASE Technology Holding Co. (Advanced Semiconductor Engineering) introduced new high-density fan-out packaging solutions for 2.5D/3D IC die stacking, particularly targeting high-performance computing and AI applications. ASE’s innovations enable greater bandwidth and integration flexibility for heterogeneous designs and chiplet architectures.
Market Concentration & Characteristics:
The 3D IC and 2.5D IC Packaging Market exhibits moderate concentration, with innovation driven by leading semiconductor companies and packaging specialists. It is characterized by high R&D investment, technological convergence, and intensive capital requirements. Entry barriers include fabrication complexity and ecosystem interdependencies. Product life cycles are shortening, increasing pressure for rapid prototyping and scalable packaging designs. The market reflects ongoing competition across chiplet design, TSV optimization, and fan-out integration.
Report Coverage:
The research report offers an in-depth analysis based on End-Use, Packaging Technology and Device Function. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. The report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The 3D IC and 2.5D IC Packaging Market is poised for substantial growth by 2032, driven by rising demand across mobile, AI, and high-performance computing (HPC) sectors.
- AI-driven co-design platforms will streamline packaging workflows, reducing time to market for complex chipsets.
- Adoption of chiplets and modular integration will accelerate, enabling cost-effective, customizable SoC alternatives.
- Emerging nations will develop domestic packaging infrastructure, reducing reliance on East Asian foundries.
- Electric and autonomous vehicles will drive demand for rugged, compact packaging with superior thermal stability.
- Packaging for AI at the edge will prioritize energy-efficient formats, with high-bandwidth memory integration.
- Panel-level fan-out packaging will scale to mass production, reducing unit costs and improving assembly yield.
- Collaborative R&D among EDA, fabless, and OSAT companies will foster innovation in 3D TSV reliability.
- New materials such as low-k dielectrics and advanced substrates will enhance signal integrity and package density.
- Government semiconductor subsidy programs will boost regional capabilities in advanced packaging solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Miniaturization and High-Performance Devices
The push for smaller, faster, and more efficient electronics in consumer, mobile, and IoT devices is driving adoption of 3D IC and 2.5D IC packaging, which enables vertical stacking and integration of multiple dies, improving speed and reducing power consumption without increasing device footprint.
Growth in High-Performance Computing and AI Applications
Expanding applications in AI, data centers, and advanced graphics processing require massive parallel processing and high interconnect bandwidth, which 3D and 2.5D packaging technologies provide through shorter interconnects and chiplet integration, supporting the needs of GPUs, AI accelerators, and HPC systems.
Automotive Electronics and Electrification
The automotive sector's shift toward electric vehicles, ADAS, and autonomous systems demands compact, reliable, and high-performance packaging solutions, with 3D and 2.5D ICs offering the performance density and thermal stability required for real-time data processing and safety-critical applications.
Proliferation of Chiplet and Heterogeneous Integration
The industry trend toward chiplet-based architectures and heterogeneous integration allows manufacturers to combine different process nodes and functionalities within a single package, improving flexibility, yield, and performance while reducing costs and accelerating time to market.
Regional Investment in Semiconductor Ecosystems
Government-backed funding and strategic initiatives in the U.S., EU, India, and Asia-Pacific are boosting domestic advanced packaging capabilities, reducing reliance on traditional foundry hubs, and fostering innovation and supply chain resilience in the 3D IC and 2.5D IC packaging market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the 3D IC and 2.5D IC Packaging Market?
What factors are driving the growth of the 3D IC and 2.5D IC Packaging Market?
What are the key segments within the 3D IC and 2.5D IC Packaging Market?
What are some challenges faced by the 3D IC and 2.5D IC Packaging Market?
Who are the major players in the 3D IC and 2.5D IC Packaging Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Consumer Electronics
- 1.2.2 Automotive
- 1.2.3 Data Centers & High-Performance Computing (HPC)
- 1.2.4 Telecommunication
- 1.2.5 Healthcare & Medical Devices
- 1.2.6 Industrial/Smart Technologies
- 1.2.7 Military & Aerospace
- 1.3 By Device Function
- 1.3.1 Memory Devices
- 1.3.2 Logic Devices
- 1.3.3 MEMS/Sensors
- 1.3.4 Imaging & Optoelectronics
- 1.4 By Packaging Technology
- 1.4.1 Through-Silicon Via (TSV) Packaging
- 1.4.2 Wafer-Level Chip Scale Packaging (WLCSP)
- 1.4.3 Interposer-Based Packaging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 60,257 million → 2032: USD 133,938.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 3D IC and 2.5D IC Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 3D IC and 2.5D IC Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 3D IC and 2.5D IC Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 3D IC and 2.5D IC Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 3D IC and 2.5D IC Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 3D IC and 2.5D IC Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global 3D IC and 2.5D IC Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 3D IC and 2.5D IC Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 60,257 million → 2032: USD 133,938.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 3D IC and 2.5D IC Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer Electronics
- 12.3.7.2 Automotive
- 12.3.7.3 Data Centers & High-Performance Computing (HPC)
- 12.3.7.4 Telecommunication
- 12.3.7.5 Healthcare & Medical Devices
- 12.3.7.6 Industrial/Smart Technologies
- 12.3.7.7 Military & Aerospace
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Device Function - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Memory Devices
- 12.4.7.2 Logic Devices
- 12.4.7.3 MEMS/Sensors
- 12.4.7.4 Imaging & Optoelectronics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Through-Silicon Via (TSV) Packaging
- 12.5.7.2 Wafer-Level Chip Scale Packaging (WLCSP)
- 12.5.7.3 Interposer-Based Packaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global 3D IC and 2.5D IC Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 3D IC and 2.5D IC Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 3D IC and 2.5D IC Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 3D IC and 2.5D IC Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Taiwan Semiconductor Manufacturing Company (TSMC)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Samsung Electronics
- 18.4 Intel Corporation
- 18.5 ASE Technology Holding Co., Ltd.
- 18.6 Amkor Technology
- 18.7 Broadcom
- 18.8 Texas Instruments
- 18.9 United Microelectronics Corporation (UMC)
- 18.10 Siliconware Precision Industries Co., Ltd. (SPIL)
- 18.11 JCET Group Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

