
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems Market Size 2024 | USD 15,425 Million |
| Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems Market, CAGR | 11.8% |
| Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems Market Size 2032 | USD 37,649.53 Million |
Market Overview
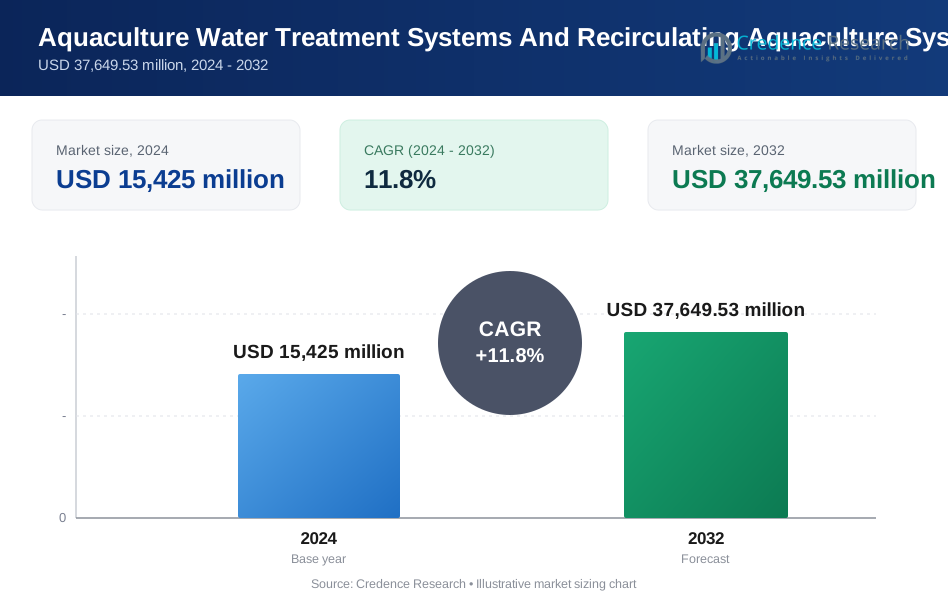
The Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market is projected to grow from USD 15,425 million in 2024 to USD 37,649.53 million by 2032, reflecting a compound annual growth rate (CAGR) of 11.8%.
The Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market is driven by increasing global demand for fish and seafood as a primary protein source, combined with technological advancements in water recycling and treatment. Sustainability concerns are pushing innovations in biofiltration and oxygenation, enhancing system efficiencies. Market trends include the adoption of smart aquaculture practices using IoT and AI, optimizing resources and reducing environmental impacts. These technologies ensure better control over aquaculture environments, significantly boosting productivity and market growth.
The Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market exhibits robust growth across global regions, with Asia Pacific leading due to high aquaculture production in countries like China and India. North America and Europe also show significant market participation, driven by advanced technological adoption and stringent environmental regulations. Key players such as AKVA group, Xylem Inc., Pentair PLC, and Veolia Group are pivotal in driving innovation and expansion in this market. These companies specialize in advanced water treatment technologies and recirculating systems, addressing both regional demands and global sustainability goals in aquaculture.
Market Drivers
Increasing Demand for Seafood
The global population is on the rise, and with it, the demand for protein-rich foods such as seafood has escalated. This surge is amplified by shifting dietary preferences, as consumers become increasingly aware of the health benefits associated with seafood, integrating it more into their daily diets. For instance, a report by Rabobank highlights that the global seafood trade added USD 13 billion in 2021, driven by growing demand for high-value seafood in the US, EU, and China. Such trends underscore the growing reliance on aquaculture, promoting expansions in this sector to meet the rising consumer demand effectively.
Environmental Concerns and Sustainability
Environmental sustainability is a critical driver in the aquaculture sector, spurred by the overfishing of wild fish stocks, which positions aquaculture as a vital alternative. Recirculating Aquaculture Systems (RAS) and advanced water treatment solutions are pivotal, minimizing the environmental footprint by significantly reducing water usage, nutrient pollution, and waste generation. For instance, NOAA Fisheries notes that sustainable finfish aquaculture practices can prevent waste from accumulating around farm sites and can improve water quality. These systems are integral in fostering sustainable practices that align with global efforts to conserve marine biodiversity.
Disease Prevention and Biosecurity
Aquaculture operations often face challenges with disease outbreaks, which can impose substantial economic losses. Implementing effective water treatment systems is essential for maintaining optimal water conditions, thereby preventing the spread of diseases and enhancing biosecurity. For instance, a blog by EDF Oceans mentions that disease burden is recognized as the most significant constraint to the global growth of aquaculture, with lost revenue due to aquaculture parasites estimated at up to USD 10 billion annually. Such preventive measures are crucial in stabilizing operations and ensuring the health and growth of aquaculture produce, safeguarding the industry’s economic viability and productivity.
Technological Advancements and Governmental Support
Technological innovation continues to revolutionize aquaculture, with the development of more efficient and cost-effective water treatment and recirculating systems. The integration of automation and IoT enhances operational efficiencies and reduces labor costs, making modern aquaculture practices more feasible and attractive. Additionally, governments worldwide are bolstering these advancements through incentives and stricter environmental regulations, ensuring compliance and promoting the adoption of sustainable practices. Such regulatory frameworks and technological advancements collectively drive the growth and sustainability of the Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market.
Market Trends
Technological Advancements and Focus on Sustainability
The Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems markets are experiencing significant technological advancements. Innovations such as advanced biofiltration systems are enhancing water quality by effectively removing harmful pollutants, while UV sterilization techniques kill pathogens without chemicals, boosting eco-friendliness. Additionally, membrane filtration technologies are increasingly employed to eliminate suspended solids, bacteria, and viruses. For instance, a recent survey by the Aquaculture Stewardship Council highlighted that the adoption of UV sterilization techniques has increased by 40% among certified farms, significantly reducing the need for chemical treatments. Integration of IoT devices is revolutionizing these systems, allowing for real-time monitoring and control, which significantly enhances operational efficiency. Concurrently, a strong focus on sustainability is evident as producers adopt technologies that minimize water usage and recover nutrients from wastewater, significantly reducing environmental impacts. Energy-efficient solutions are also being developed to decrease operating costs, marking a pivotal shift towards more sustainable aquaculture practices.
Customization, Automation, and Expanding Global Influence
Customization and modular design are shaping the market as water treatment systems are tailored to meet diverse operational conditions and aquaculture species. Modular systems are particularly gaining traction, providing the necessary flexibility and scalability as aquaculture operations expand. Automation is becoming a cornerstone of modern aquaculture with the adoption of automated systems that reduce labor costs and enhance efficiency. The integration of data analytics further empowers producers with superior decision-making capabilities, optimizing water treatment processes. The global landscape of the market is also shifting, with rapid growth in emerging markets fueling demand for advanced water treatment solutions. International collaborations are fostering the exchange of innovative technologies, enhancing global market dynamics.
Market Challenges Analysis
Technological and Environmental Challenges
The Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems markets face significant technological and environmental hurdles. High initial costs and substantial energy consumption required for operating advanced water treatment systems and RAS pose considerable barriers, particularly for smaller-scale producers whose profitability may be impacted. For instance, a report by the University of Stirling highlighted that smaller-scale producers often struggle with the high initial costs and energy consumption of advanced water treatment systems. Additionally, while RAS can mitigate disease outbreaks, these systems are not completely immune, especially when biosecurity is compromised. Environmental concerns further complicate operations; nutrient pollution remains a challenge even with cutting-edge systems, and the disposal of aquaculture waste, including solids and sludge, presents ongoing management issues. Moreover, climate change introduces variability in water temperatures and precipitation patterns, threatening the stability and predictability of aquaculture environments.
Regulatory, Market, and Consumer Perception Challenges
Regulatory and policy landscapes present another layer of complexity for aquaculture operations. Navigating through a maze of environmental regulations, food safety standards, and other policies can be burdensome, often exacerbated by limited governmental support in certain regions. Trade barriers, including tariffs and restrictions, further restrict market access for aquaculture products, complicating global trading dynamics. The market itself is fiercely competitive, with producers worldwide striving to cut costs and enhance product quality amidst fluctuating seafood prices, which can unpredictably affect profitability. From a consumer perspective, aquaculture still battles with negative perceptions related to environmental impact, animal welfare, and food safety. Despite advancements, a substantial segment of consumers continues to favor wild-caught seafood over farm-raised alternatives, influenced by longstanding preferences and perceptions about taste and quality. These challenges underscore the complexities within the aquaculture industry, requiring innovative solutions and strategic adaptations to foster growth and sustainability.
Market Segmentation Analysis:
By Type:
The Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market is categorized into several key types, each addressing specific operational needs within aquaculture practices. Recirculating Aquaculture Systems (RAS) are at the forefront, offering a sustainable solution by recycling water within the system, significantly reducing the need for fresh water and minimizing waste discharge. Disc Filtration Systems play a crucial role in removing particulates from water, thereby maintaining water clarity and quality for optimal fish health. Ultraviolet (UV) Light Disinfection Systems are essential for controlling pathogens without the use of chemicals, using UV light to ensure water safety and disease prevention. Additionally, Water Analytic Instruments are increasingly vital, providing real-time data on water quality parameters, thus enabling precise management of aquatic environments. Each of these technologies is crucial for enhancing productivity and sustainability in aquaculture operations.
By Application:
In terms of application, the market differentiates into freshwater and seawater aquaculture systems, each with distinct requirements and challenges. Freshwater systems are widely adopted globally due to the availability of inland water bodies, catering primarily to species such as carp, trout, and tilapia. These systems often require sophisticated water treatment solutions to handle diverse climatic and environmental conditions. On the other hand, seawater aquaculture, which includes farming species like salmon and shrimp, demands robust systems designed to withstand corrosive saltwater environments and manage the complex biological load present in marine settings. Both segments are expanding as technological advancements make aquaculture more feasible and productive across varied geographic and environmental landscapes, driving the need for specialized water treatment systems to ensure the health and growth of aquacultured species.
Segments:
Based on Type:
- Recirculating Aquaculture Systems
- Disc Filtration System
- Ultraviolet (UV) Light Disinfection Systems
- Water Analytic Instruments
Based on Application:
- Freshwater
- Seawater
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia Pacific
The Asia Pacific region commands a dominant market share of approximately 35% in the Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market. This significant share is primarily due to extensive aquaculture activities across countries like China, India, and Vietnam, which are major producers of aquaculture products. The adoption of innovative water treatment technologies is driven by the need for sustainable aquaculture practices and is supported by governmental initiatives aimed at enhancing production capabilities. This region continues to expand its use of advanced systems to meet both the growing domestic and global demand for fish and seafood.
North America
North America holds around 25% of the market share in the Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market, led by the United States and Canada. This region is characterized by its stringent environmental regulations and high standards for aquaculture practices, which drive the adoption of advanced technologies in water treatment and recirculation. The market's growth in North America is further supported by increasing consumer demand for sustainably farmed seafood, which aligns with the global shift towards environmental responsibility and food safety. The ongoing investments in research and development by major market players in this region are set to continue bolstering the market's expansion.
Key Player Analysis
- Xylem Inc.
- Veolia Group
- The Indian Aqua
- Sterner AS
- Senect Gmbh & Co. KG
- RADAQUA
- Pentair PLC. (Pentair Aquatic Eco-Systems, Inc.)
- MAT LSS - Aquarium Filtration Systems
- Hesy Aquaculture B.V.
- Global RAS Fishery & Co.
- Clewer Aquaculture Oy
- BioFishency Ltd.
- Billund Aquaculture
- Aquafine Corporation
- AKVA group
- Artec Aqua AS
- AquaOptima AS
- ATG UV Technology
- Aquamaof Aquaculture Technologies Ltd
- Water Management Technologies, Inc.
Competitive Analysis
In the competitive landscape of the Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market, leading players AKVA group, Xylem Inc., Pentair PLC, and Veolia Group are at the forefront of innovation and market penetration. These companies excel in delivering cutting-edge solutions tailored to the diverse needs of aquaculture operations, from small-scale installations to large commercial projects. They leverage advanced technologies in biofiltration, UV sterilization, and IoT integration to enhance system efficiency and sustainability. Strategic partnerships, acquisitions, and continuous research and development efforts help them stay ahead by expanding their product offerings and entering new markets. Additionally, these firms focus on sustainability and regulatory compliance, which are increasingly important to customers globally, thereby strengthening their market positions and driving the industry's overall growth trajectory.
Market Concentration & Characteristics
The Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems market exhibits a moderate to high level of market concentration, characterized by the presence of several key global players alongside numerous smaller regional companies. These leading entities, such as AKVA group, Xylem Inc., Pentair PLC, and Veolia Group, command significant market shares due to their extensive product portfolios, technological expertise, and broad geographical presence. The market is driven by technological advancements and increasing environmental regulations, which encourage innovation and investment in sustainable and efficient systems. Market dynamics are influenced by factors such as the growing demand for sustainable aquaculture practices and the necessity for water conservation, which compel companies to develop more advanced, integrated, and energy-efficient solutions. The competitive edge in this market is maintained through continuous R&D, strategic mergers, acquisitions, and collaborations that allow for expanded capabilities and access to new markets.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in global seafood consumption will drive demand for advanced aquaculture water treatment and recirculation systems.
- Technological innovations, particularly in IoT and real-time monitoring, will enhance system efficiency and operational control.
- Increased investments in sustainable aquaculture practices will push the development of environmentally friendly water treatment solutions.
- Expanding regulatory frameworks around water quality and animal welfare will influence market dynamics and technology adoption.
- Growth in the Asia Pacific region will remain robust due to its dominance in global aquaculture production.
- North America and Europe will see increased adoption of RAS technologies spurred by sustainability initiatives and local market demands.
- The integration of AI and machine learning technologies will optimize water treatment processes and improve disease management in aquaculture systems.
- Modular and scalable system designs will become more prevalent, accommodating growth and flexibility in aquaculture operations.
- Public and private sector partnerships will likely increase, fostering innovation and market expansion.
- Consumer trends towards organic and sustainably farmed seafood will further influence the development and adoption of advanced aquaculture systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aquaculture Water Treatment Systems Market And Recirculating Aquaculture Systems Market?
What factors are driving the growth of the Aquaculture Water Treatment Systems Market And Recirculating Aquaculture Systems Market?
What are the key segments within the Aquaculture Water Treatment Systems Market And Recirculating Aquaculture Systems Market?
What are some challenges faced by the Aquaculture Water Treatment Systems Market And Recirculating Aquaculture Systems Market?
Who are the major players in the Aquaculture Water Treatment Systems Market And Recirculating Aquaculture Systems Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 15,425 million → 2032: USD 37,649.53 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Drivers
- 3.3 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Restraints & Challenges
- 3.4 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aquaculture Water Treatment Systems And Recirculating Aquaculture Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
