
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Architectural Services Market Size 2024 | USD 387985 Million |
| Architectural Services Market, CAGR | 5.9% |
| Architectural Services Market Size 2032 | USD 613736.64 Million |
Market Overview:
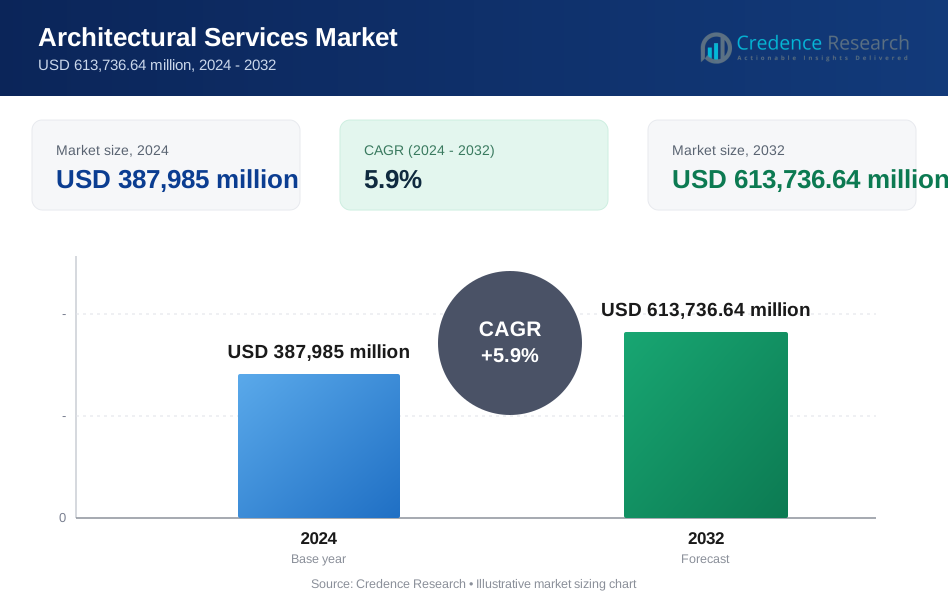
The Architectural Services Market is projected to grow from USD 387985 million in 2024 to an estimated USD 613736.64 million by 2032, with a compound annual growth rate (CAGR) of 5.9% from 2024 to 2032.
The rise in urbanization, especially in emerging economies, is a key driver of the architectural services market. Governments and private sectors are investing heavily in infrastructure projects, such as commercial buildings, residential complexes, and public facilities, which is fueling demand for architectural expertise. Additionally, the growing emphasis on sustainable construction and eco-friendly designs is pushing architectural firms to incorporate green building standards and energy-efficient practices into their projects. The increasing adoption of Building Information Modeling (BIM) technology is enhancing collaboration among stakeholders, improving project efficiency, and reducing costs. Furthermore, the shift towards modular and prefabricated construction techniques is also influencing the demand for architectural services, as these methods require precise and innovative design solutions to meet modern construction requirements.
North America holds a significant share of the architectural services market, driven by strong investments in commercial and residential construction, as well as advancements in sustainable building practices. The U.S., in particular, is a key player due to its high demand for urban development and modernization of infrastructure. Europe follows closely, with a focus on green buildings and energy-efficient structures, particularly in countries like Germany, the U.K., and France. The Asia Pacific region is expected to witness the fastest growth during the forecast period, fueled by rapid urbanization and infrastructure development in countries like China, India, and Southeast Asian nations. Government initiatives supporting smart cities and industrial development are further driving the demand for architectural services in the region. Additionally, Latin America and the Middle East & Africa are showing steady growth as they modernize their urban infrastructure and adopt sustainable building practices.
Market Drivers:
Increasing Urbanization and Infrastructure Development:
The architectural services market is primarily driven by the rapid pace of urbanization and infrastructure development, particularly in emerging economies. As cities expand and populations grow, the need for modern housing, commercial buildings, transportation systems, and public infrastructure has surged. Governments and private developers are investing heavily in large-scale projects, creating substantial demand for architectural services. Architectural firms are increasingly tasked with designing innovative, functional, and sustainable spaces that cater to the growing urban population while addressing the challenges of limited space and environmental concerns. This trend is expected to continue as urban migration intensifies globally.
Rising Demand for Sustainable and Green Buildings:
Sustainability has become a central focus in the architectural services market, with increasing demand for green buildings and eco-friendly design solutions. As concerns over climate change and environmental degradation rise, both public and private sectors are seeking to minimize their carbon footprint. Architectural firms are adopting sustainable practices such as energy-efficient designs, use of eco-friendly materials, and the integration of renewable energy sources into their projects. The global push for environmental sustainability, coupled with regulatory frameworks like LEED (Leadership in Energy and Environmental Design) certification, is driving architects to innovate and prioritize green building standards in their designs.
Technological Advancements in Design and Construction:
Technological innovations, particularly in Building Information Modeling (BIM) and virtual reality (VR), are reshaping the architectural services market. BIM technology enables architects, engineers, and construction professionals to collaborate more effectively by providing a digital representation of a building’s characteristics. This leads to improved efficiency, reduced costs, and enhanced project management. Additionally, advancements in virtual reality and 3D modeling are allowing architects to visualize and present designs in a more immersive and interactive manner, improving client engagement and decision-making. For instance, MRV has saved $20 million in two years by converting physical apartments into virtual ones. The adoption of these advanced technologies is becoming essential for architectural firms to stay competitive and meet the demands of increasingly complex projects.
Growing Popularity of Modular and Prefabricated Construction:
The shift towards modular and prefabricated construction methods is another significant driver of the architectural services market. These construction techniques, which involve assembling building components off-site, have gained popularity due to their cost-effectiveness, time efficiency, and reduced environmental impact. Modular construction allows for more precision and standardization in design, which is driving the need for architectural expertise to develop detailed, innovative, and flexible designs suited for prefabrication. For example, BOXX Modular offers prefab commercial buildings ranging from 200 square feet to 30,000 square feet. As developers seek to accelerate construction timelines and reduce labor costs, architectural firms are playing a crucial role in integrating modular and prefabricated elements into both residential and commercial projects. This trend is expected to grow as the construction industry embraces more efficient and sustainable practices.
Market Trends:
Adoption of Smart Technologies in Architectural Design:
The integration of smart technologies into architectural design is a major trend shaping the architectural services market. As buildings become more intelligent, architects are increasingly incorporating smart systems into their designs to enhance functionality, energy efficiency, and sustainability. This includes smart lighting, heating, ventilation, and air conditioning (HVAC) systems, as well as IoT-enabled devices that allow for real-time monitoring and control. The adoption of smart building technology is particularly prominent in commercial and high-rise residential projects, where there is a growing demand for energy-efficient, automated, and user-friendly spaces. Architectural firms are now expected to collaborate with technology providers to create buildings that leverage the benefits of automation and smart infrastructure.
Increased Focus on Sustainable and Resilient Design:
The architectural services market is seeing a strong push toward sustainable and resilient design, driven by the growing emphasis on environmental responsibility and climate change adaptation. Governments and organizations are implementing stricter building codes and sustainability certifications, such as LEED, to reduce the environmental impact of new construction. Architects are responding by integrating renewable energy solutions, using sustainable materials, and designing buildings that minimize energy consumption and reduce carbon emissions. For example, Skanska has committed to achieving net-zero carbon emissions by 2045. Additionally, resilient design, which focuses on building structures that can withstand natural disasters and changing climate conditions, is becoming a priority in regions prone to extreme weather events. This trend reflects a shift toward architecture that not only benefits the environment but also ensures long-term durability.
Growth of Modular and Prefabricated Construction:
Modular and prefabricated construction methods are becoming increasingly popular in the architectural services market due to their ability to speed up construction processes, reduce costs, and limit environmental waste. These methods involve creating building components off-site and then assembling them on-site, allowing for greater precision and efficiency. Architectural firms are increasingly required to design structures that can accommodate these prefabricated elements while maintaining aesthetic appeal and functionality. This trend is gaining momentum in both residential and commercial sectors, where developers are looking to meet tight construction timelines and reduce labor-intensive work. For instance, AMANA Investments has completed over 150 modular construction projects in the Gulf Cooperation Council (GCC) region. The modular construction approach is particularly appealing in regions experiencing rapid urbanization, where the need for quick, affordable, and sustainable building solutions is high.
Emphasis on Collaborative and Integrated Design Approaches:
Architectural services are increasingly moving toward collaborative and integrated design approaches, fueled by the adoption of Building Information Modeling (BIM) technology. BIM allows for seamless collaboration among architects, engineers, contractors, and other stakeholders throughout the project lifecycle. This integration leads to improved accuracy in design, reduced project risks, and enhanced communication between teams. As projects become more complex, the demand for multidisciplinary collaboration is growing, requiring architectural firms to work closely with other professionals to deliver comprehensive, well-coordinated solutions. The shift toward integrated design is driving higher project efficiency and quality, making it a critical trend in the architectural services market.
Market Restraints and Challenges:
High Cost of Advanced Technology Integration:
One of the key challenges facing the architectural services market is the high cost of integrating advanced technologies such as Building Information Modeling (BIM), virtual reality (VR), and smart building systems. While these technologies significantly improve project efficiency and design accuracy, their implementation often requires substantial investment in software, training, and infrastructure. Smaller architectural firms, in particular, may struggle to afford the upfront costs associated with adopting these tools, limiting their ability to compete with larger, well-funded firms. This financial barrier can slow the pace of technological advancement within the market, particularly for smaller players.
Regulatory Complexity and Compliance Issues:
The architectural services market also faces challenges related to regulatory complexity and compliance with evolving building codes and sustainability standards. Regulations surrounding environmental impact, energy efficiency, and safety are becoming increasingly stringent, especially in regions with a strong focus on sustainable development. Architects must navigate these complex regulations while ensuring that designs remain innovative and cost-effective. This can create additional layers of complexity in project planning and execution, leading to increased time and resource expenditure. Non-compliance or delays in regulatory approval can also significantly impact project timelines and budgets.
Skilled Labor Shortage:
A shortage of skilled professionals is another significant restraint in the architectural services market. The growing demand for specialized knowledge in areas such as sustainable design, smart technologies, and BIM requires architects and designers to continuously upgrade their skills. However, the talent pool of professionals trained in these advanced areas is limited, creating a skills gap in the industry. This shortage can lead to project delays, higher labor costs, and increased pressure on architectural firms to retain and develop talent. Firms unable to access skilled labor may find it difficult to meet the growing demand for complex, technology-driven projects.
Market Segmentation Analysis:
By Service type, the market includes architectural advisory services, construction and project management services, engineering services, interior designing services, and urban planning services. Architectural advisory services play a critical role in providing design consultation and feasibility studies, while construction and project management services focus on overseeing projects from inception to completion. Engineering services ensure that structural integrity and compliance are maintained, while interior designing services enhance functionality and aesthetics within spaces. Urban planning services cater to large-scale projects that require city or community-wide development strategies.
By End user, the market is segmented into education, government, healthcare, hospitality, industrial, residential, and retail sectors. The residential segment holds a significant portion of the market due to rising demand for housing in urban areas. The government sector drives growth through infrastructure and public facility projects, while the healthcare and education sectors require specialized designs that meet regulatory and operational needs. The hospitality and retail sectors emphasize unique, innovative designs to enhance customer experiences, while the industrial segment focuses on efficient, large-scale facility design to support manufacturing and logistics. Each segment contributes to the overall growth and diversification of the architectural services market.
Segmentation:
By Service Type
- Architectural Advisory Services
- Construction and Project Management Services
- Engineering Services
- Interior Designing Services
- Urban Planning Services
By End User
- Education
- Government
- Healthcare
- Hospitality
- Industrial
- Residential
- Retail
- North America
- US
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
Regional Analysis:
North America
North America holds a dominant position in the global architectural services market, accounting for approximately 35% of the total market share. This strong presence is largely driven by the region’s well-developed infrastructure and high demand for both commercial and residential construction projects. The United States, in particular, plays a leading role in this market, driven by significant investments in urban development, green building practices, and modernization of aging infrastructure. The region is also characterized by early adoption of advanced technologies like Building Information Modeling (BIM) and sustainable design solutions, which further fuels demand for architectural services. As environmental regulations tighten, the focus on energy-efficient and eco-friendly buildings is expected to drive market growth in North America.
Europe
Europe follows closely, holding around 25% of the global architectural services market share. The region’s growth is primarily driven by stringent regulations concerning sustainability and energy efficiency, with countries like Germany, the United Kingdom, and France at the forefront of green building practices. The European market is seeing a growing demand for innovative and sustainable architectural designs, particularly in sectors such as residential housing, healthcare, and commercial buildings. Additionally, urban regeneration and redevelopment projects are on the rise in Europe, further boosting the demand for architectural services. The increasing adoption of smart technologies and the focus on reducing carbon footprints are also contributing to market growth in this region.
Asia Pacific
Asia Pacific is the fastest-growing region in the architectural services market, holding approximately 20% of the global market share. The region's rapid growth is driven by increased urbanization, industrialization, and infrastructure development in countries such as China, India, and Japan. Government initiatives promoting smart cities, sustainable urban planning, and large-scale infrastructure projects are key drivers of growth. The rising demand for affordable housing and commercial spaces, coupled with the adoption of modern construction practices, is significantly boosting the demand for architectural services. Additionally, the expansion of manufacturing industries and public infrastructure in emerging economies is expected to further propel the market in Asia Pacific.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively hold around 10% of the market share. In Latin America, countries like Brazil and Mexico are witnessing steady growth due to rising urbanization and increased investment in infrastructure projects. In the Middle East & Africa, government-led initiatives to modernize urban infrastructure and build smart cities are driving market growth. The demand for high-end architectural services in luxury hospitality and commercial sectors, particularly in the Gulf region, is also contributing to market expansion. However, economic volatility and geopolitical factors may pose challenges to sustained growth in these regions.
Key Player Analysis:
- AECOM
- CannonDesign
- Foster + Partners
- Gensler
- HDR, Inc.
- HKS Inc
- HOK
- IBI Group
- Jacobs
- NBBJ
- Nikken Sekkei Ltd.
- Perkins and Will
- Perkins Eastman
- Stantec
- Zaha Hadid Architects
Competitive Analysis:
The architectural services market is highly competitive, with a mix of large global firms and regional players shaping the landscape. Major companies such as Gensler, AECOM, Foster + Partners, HDR Inc., and Perkins & Will dominate the market due to their expansive portfolios and expertise in handling large-scale, complex projects across various sectors. These firms leverage advanced technologies like Building Information Modeling (BIM) and sustainable design practices to maintain their competitive edge. Smaller regional firms, however, compete by offering specialized services tailored to local needs, often focusing on niche markets like residential or commercial interiors. The market is driven by innovation, sustainability, and technological integration, with firms continually enhancing their service offerings to meet evolving client demands. Strategic partnerships, mergers, and acquisitions are common, as companies seek to expand their market presence and strengthen their capabilities. As demand for sustainable and smart building solutions grows, competition in the market is expected to intensify.
Recent Developments:
- In May 2024, Gensler expanded its sports venue design practice by opening a new office in Kansas City, Missouri. This expansion underscores Gensler’s growing focus on sports and entertainment design, a practice the firm has developed over the past 15 years. The Kansas City office will leverage local talent to create innovative, human-centric sports and entertainment districts in response to increasing demand for immersive in-person experiences.
- In December 2023, HDR, Inc. acquired City Point Partners, a Massachusetts-based construction services provider. The acquisition strengthens HDR’s capabilities in program management, project controls, public outreach, and construction services. The two firms have previously collaborated on projects, including work with the Massachusetts Bay Transportation Authority, enhancing their combined expertise in public infrastructure projects.
- In November 2023, AECOM signed a Memorandum of Understanding (MoU) with Boryspil International Airport, positioning itself as a reconstruction partner for the airport’s redevelopment. AECOM will provide comprehensive infrastructure consulting services, including capability assessment, asset condition analysis, design, and construction management. Additionally, AECOM will support the broader reconstruction efforts of Ukraine’s aviation industry by developing program management capabilities.
Market Concentration & Characteristics:
The architectural services market is moderately fragmented, with a combination of large multinational firms and smaller regional players. Major companies like Gensler, AECOM, HDR Inc., and Perkins & Will hold significant market share due to their ability to handle large-scale, complex projects across various sectors such as commercial, residential, and public infrastructure. These firms benefit from their global presence, extensive expertise, and adoption of advanced technologies like Building Information Modeling (BIM). At the same time, smaller firms compete by offering specialized and niche services, often focusing on local markets and customized solutions. The market is characterized by increasing demand for sustainable design, smart building integration, and the use of technology to enhance project efficiency and reduce costs. As sustainability and regulatory compliance become more critical, architectural firms are adapting their service offerings to meet evolving client needs, contributing to the competitive nature of the market.
Report Coverage:
The research report offers an in-depth analysis based on By Service Type and By End User
It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased demand for sustainable and green building designs will drive market growth as environmental regulations tighten globally.
- The adoption of Building Information Modeling (BIM) will continue to grow, enhancing project collaboration and efficiency.
- Rapid urbanization, particularly in emerging markets, will fuel the need for residential and commercial architectural services.
- Modular and prefabricated construction methods will gain popularity, reducing project timelines and costs.
- Smart building technologies will become a key focus, integrating IoT and automation into architectural designs.
- The rising demand for renovation and retrofitting of aging infrastructure will expand opportunities in developed markets.
- The growth of mixed-use developments will increase, driven by the desire for urban space optimization.
- Architectural firms will increasingly incorporate AI and data analytics to improve design precision and decision-making.
- The healthcare and education sectors will see a rise in demand for specialized architectural services due to expansion and modernization needs.
- Global competition will intensify as both large firms and regional players seek to capitalize on evolving market trends.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the architectural services market?
What is driving the growth of the architectural services market?
Which regions dominate the architectural services market?
What are the challenges faced by the architectural services market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Architectural Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Architectural Services Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 387,985 million → 2032: USD 613,736.64 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Architectural Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Architectural Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Architectural Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Architectural Services Market Drivers
- 3.3 Architectural Services Market Restraints & Challenges
- 3.4 Architectural Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Architectural Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Architectural Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Architectural Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Architectural Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Architectural Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Architectural Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Architectural Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Architectural Services Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Architectural Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Architectural Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Architectural Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Architectural Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Architectural Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Architectural Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Architectural Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Architectural Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Architectural Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Architectural Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Architectural Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
