
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dehydration Monitoring Systems Market Size 2024 | USD 477.46 million |
| Dehydration Monitoring Systems Market, CAGR | 7.21% |
| Dehydration Monitoring Systems Market Size 2032 | USD 831.04 million |
Market Overview:
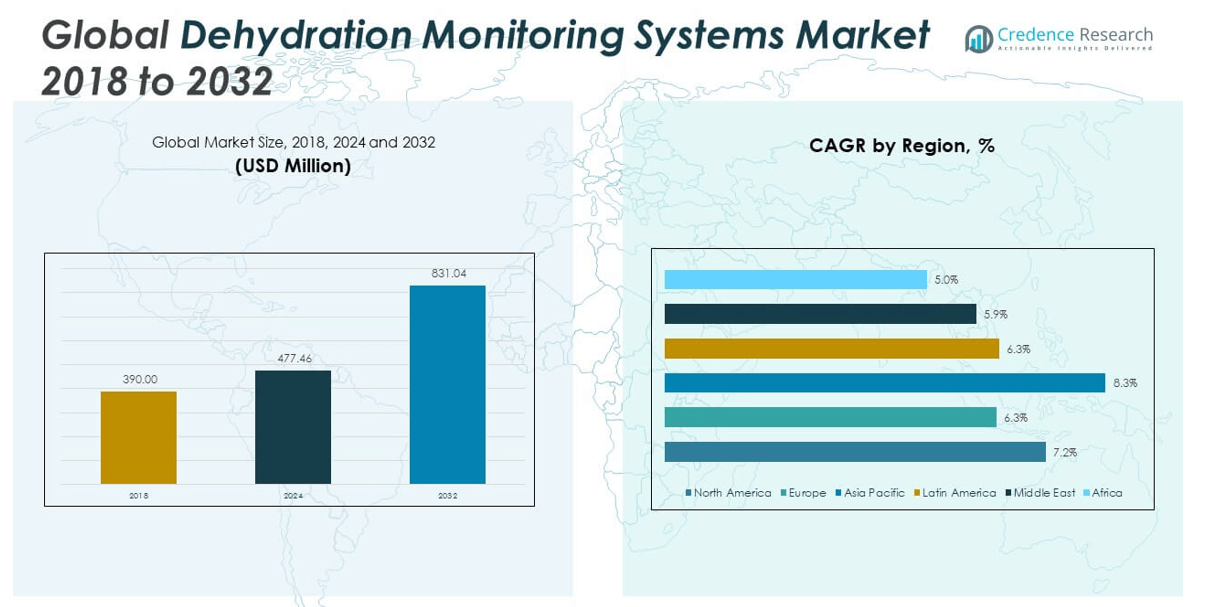
The Global Dehydration Monitoring Systems Market size was valued at USD 390.00 million in 2018 to USD 477.46 million in 2024 and is anticipated to reach USD 831.04 million by 2032, at a CAGR of 7.21% during the forecast period.
One of the primary factors driving the growth of the Global Dehydration Monitoring Systems Market is the increasing public awareness of the health risks associated with dehydration and the growing demand for real-time hydration tracking. The prevalence of dehydration-related complications-such as urinary tract infections, kidney stones, cognitive impairment, and heatstroke-has led to heightened demand for preventive measures in both clinical and non-clinical environments. Furthermore, advancements in sensor technologies have made it feasible to develop accurate, user-friendly, and cost-effective devices that provide real-time hydration data. These innovations include sweat analysis systems, bio-impedance devices, optical sensors, and smartphone-integrated hydration tools. In parallel, the rising use of wearable fitness and health monitoring devices is contributing to market expansion, as consumers increasingly prefer multifunctional solutions that track hydration along with heart rate, sleep, and physical activity. The healthcare sector is also actively integrating dehydration monitoring into chronic care programs, geriatric management systems, and telemedicine platforms, thereby enhancing its clinical utility.
Regionally, North America dominates the Global Dehydration Monitoring Systems Market due to its advanced healthcare infrastructure, high healthcare expenditure, and early adoption of innovative medical technologies. The United States, in particular, is a key contributor, driven by a well-established ecosystem of healthcare providers, technology developers, and fitness-focused consumers. Europe holds the second-largest market share, supported by favorable government policies, a growing geriatric population, and increasing investment in digital health solutions. Countries such as Germany, the United Kingdom, and France are leading in terms of product innovation and healthcare integration. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth rate during the forecast period. Factors such as increasing awareness of dehydration’s health impact, rising healthcare investments, and expanding adoption of wearable health technologies are driving demand in countries like China, Japan, India, and South Korea. The region's large population base, coupled with a growing middle class and expanding fitness culture, further supports this trend. Latin America and the Middle East & Africa represent emerging markets with substantial potential.
Market Insights:
- The market grew from USD 390.00 million in 2018 to USD 477.46 million in 2024 and is projected to reach USD 831.04 million by 2032, supported by rising global health awareness and the need for preventive hydration solutions.
- Increasing demand for real-time, non-invasive hydration tracking is driving adoption across elder care, chronic illness management, sports, and home health environments.
- Technological innovations such as biosensors, sweat analysis, mobile integration, and cloud-based data access are expanding device functionality and user convenience.
- Use cases are expanding across sports, military, and occupational health, where dehydration risks are high and continuous monitoring supports safety and performance.
- Public health campaigns and government-backed initiatives are promoting early dehydration detection, especially in climate-vulnerable and disease-prone regions.
- High device costs and lack of reimbursement policies are limiting widespread adoption in resource-constrained areas and among lower-income patient groups.
- Complex regional regulations and evolving data security laws increase compliance burdens, requiring manufacturers to invest heavily in certifications and cybersecurity measures.
Market Drivers:
Growing Emphasis on Preventive Healthcare and Fluid Balance Management:
The increasing global focus on preventive healthcare has elevated the importance of maintaining proper hydration levels. Health systems are encouraging the use of technologies that help detect early signs of dehydration and electrolyte imbalance. Dehydration monitoring systems support this shift by enabling real-time, non-invasive assessments. These devices have been particularly effective in managing patients with chronic kidney disease, diabetes, and cardiovascular conditions. With rising healthcare costs, stakeholders are investing in solutions that reduce hospital readmissions and improve at-home disease management.
- For instance,Baxter’s Starling™ Fluid Management Monitoring System was shown to reduce hospital readmissions for heart failure patients by 45%, and decrease in-hospital fluid overload events by 60% in a multicenter, peer-reviewed study published in JACC: Heart Failure (2022).
Technological Advancements and Integration with Mobile Health Platforms:
Innovations in biosensor design, wireless connectivity, and mobile health integration have transformed dehydration monitoring from a clinical procedure into a consumer-friendly solution. Modern devices can now analyze sweat composition, skin impedance, and temperature to assess hydration levels with high precision. Integration with smartphones and cloud platforms enables remote access to hydration data by healthcare providers and caregivers. This accessibility is increasing device usage in both professional healthcare environments and personal wellness routines, expanding the addressable market.
- For instance, The Kenzen Eco Smart Patch uses biosensors to analyze sweat composition-including electrolytes and glucose-in real time via a smartphone app. The patch, tested with professional athletes such as the San Francisco 49ers, delivers clinically relevant measurements of hydration and has been developed with support from medical research and sports performance specialists.
Expanding Applications in Military, Athletics, and Occupational Health:
The Global Dehydration Monitoring Systems Market is expanding its application base beyond hospitals and into specialized fields such as sports performance, defense operations, and industrial safety. Military personnel deployed in high-heat zones, athletes during endurance events, and workers in physically demanding occupations all face significant dehydration risks. Continuous monitoring helps mitigate these risks by providing actionable data to optimize fluid intake and performance. Employers and sports organizations are investing in these devices to enhance safety and productivity.
Regulatory Push and Public Health Initiatives:
Government agencies and healthcare organizations are increasingly supporting the adoption of dehydration monitoring systems through public health campaigns and regulatory frameworks. Initiatives promoting early diagnosis and preventive care have led to funding for remote monitoring technologies, particularly for high-risk populations. International health organizations are recognizing dehydration as a public health concern, especially in regions prone to heatwaves, water scarcity, or infectious diseases that cause fluid loss. These initiatives are improving access to monitoring technologies and encouraging innovation.
Market Trends:
Development of AI-Powered Hydration Monitoring Solutions:
Artificial intelligence is transforming the functionality of dehydration monitoring systems by enabling predictive analytics and personalized hydration recommendations. AI algorithms analyze continuous data streams to identify patterns and forecast potential dehydration episodes before symptoms manifest. These capabilities are particularly beneficial in intensive care, geriatrics, and chronic disease management, where timely interventions are critical. Manufacturers are embedding machine learning models into software platforms to differentiate their products and provide added clinical value.
- For instance, Medtronic Guardian™ Connect System: In multi-center clinical evaluations, the Guardian Connect CGM system-integrated with the Sugar.IQ AI diabetes assistant-produced predictive alerts that reduced instances of hypoglycemic (low glucose) episodes by nearly two-fold and hyperglycemic (high glucose) episodes by four-fold in real-world use for type 1 diabetes patients.
Adoption of Skin-Adherent Wearables and Flexible Sensors:
Skin-adherent patches and flexible wearables are emerging as a key trend in the market. These compact, comfortable devices can be worn discreetly and are designed for long-term use. They measure sweat rate, electrolyte levels, and skin temperature to assess hydration status without interfering with daily activities. This trend is making hydration tracking more accessible to a broader user base, including pediatric and geriatric patients, where traditional monitors may be uncomfortable or impractical.
- For instance, Developed in partnership with PepsiCo/Gatorade and tested with more than 300 athletes, Gx Sweat Patch captures sweat rate and sodium composition during exercise using microfluidic technology.
Integration with Comprehensive Health Ecosystems:
The Global Dehydration Monitoring Systems Market is moving toward integration within broader health monitoring ecosystems. Devices now often come with API access and compatibility with platforms tracking heart rate, sleep, stress, and glucose levels. This interoperability allows for a holistic approach to health monitoring and care delivery. Healthcare providers and insurers are showing interest in bundled solutions that include hydration monitoring as part of larger wellness or chronic disease management programs.
Commercialization of Disposable Monitoring Devices:
To address hygiene concerns and reduce cross-contamination risks in multi-user environments, companies are developing disposable dehydration monitoring devices. These single-use or short-term wearables are gaining traction in hospitals, eldercare facilities, and sports clinics. They lower maintenance costs and eliminate the need for device sterilization, making them ideal for high-volume or high-risk applications. This trend supports increased deployment in resource-limited settings where long-term device maintenance is challenging.
Market Challenges Analysis:
High Costs and Reimbursement Gaps:
Cost remains a significant barrier to widespread adoption of dehydration monitoring systems. Advanced biosensors and continuous monitoring capabilities raise the price point of these devices, making them less accessible in cost-sensitive markets. Many health insurance providers do not yet reimburse for dehydration monitoring, limiting adoption in both clinical and consumer segments. This financial hurdle particularly affects small clinics, rural health centers, and lower-income patients.
Regulatory and Data Security Complexities:
The Global Dehydration Monitoring Systems Market must navigate a complex regulatory landscape across different regions. Devices used in clinical environments must comply with standards such as the FDA, CE marking, and ISO certifications. Additionally, systems transmitting hydration data over cloud networks are subject to data privacy regulations like HIPAA in the U.S. and GDPR in Europe. Ensuring compliance with these evolving regulations requires significant investment in cybersecurity and legal oversight, which can delay product launches and market entry.
Market Opportunities:
Rising Demand for Smart, Integrated Healthcare Solutions:
The Global Dehydration Monitoring Systems Market is well positioned to benefit from the increasing demand for smart and integrated healthcare technologies. Consumers and healthcare providers are prioritizing solutions that combine hydration data with other health indicators for a more comprehensive health profile. Devices that offer seamless integration with electronic health records, telehealth platforms, and mobile applications create stronger value propositions. It allows continuous patient monitoring, early intervention, and improved clinical decision-making. Developers that focus on connectivity, interoperability, and user-friendly interfaces will capture greater interest across both medical and consumer segments. The shift toward personalized and preventive healthcare further strengthens demand for integrated hydration monitoring tools.
Untapped Potential in Emerging Economies and Pediatric Care:
The Global Dehydration Monitoring Systems Market has significant growth opportunities in emerging economies, where rising healthcare investments and digital health adoption are accelerating. Governments and private healthcare providers are exploring scalable, low-cost monitoring solutions that can serve remote or underserved populations. It creates demand for compact, durable, and affordable devices that do not require specialized infrastructure. Another opportunity lies in pediatric care, where early detection of dehydration is critical but often overlooked. Devices tailored for infants and children can address a major gap in the current market. Expanding product portfolios to include solutions for these underserved segments will drive long-term market expansion.
Market Segmentation Analysis:
By Device Type
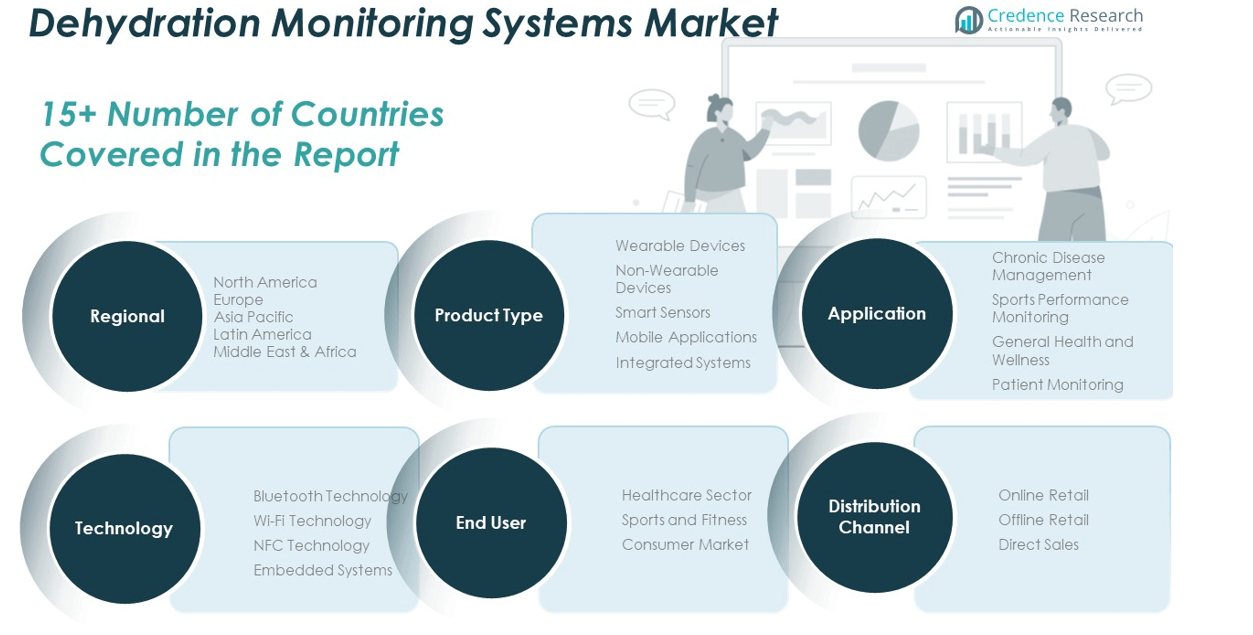
The Global Dehydration Monitoring Systems Market includes five major device categories: wearable devices, non-wearable devices, smart sensors, mobile applications, and integrated systems. Wearable devices dominate due to their ability to provide continuous hydration monitoring during physical activity or daily use. Non-wearable devices are more common in clinical environments, while integrated systems support broader hospital workflows. Mobile applications offer accessibility through smartphones, making them popular in personal wellness. Smart sensors underpin most product types, enabling accurate real-time fluid level tracking.
- For instance, The Nix Hydration Biosensor uses electrochemical sweat analysis, with validation studies showing an accuracy of over 82.8% (MAPE 17.2%) compared to the gold standard of body mass change during workouts.
By Application
Key application areas include chronic disease management, sports performance monitoring, general health and wellness, and patient monitoring. Chronic disease management leads this segment, driven by the need for long-term hydration monitoring in patients with kidney disorders, diabetes, and cardiovascular issues. Sports performance monitoring continues to grow due to demand from athletes and fitness professionals. General health and patient monitoring also see steady uptake across outpatient and home care settings.
- For instance,Sibel Health’s ANNE One wireless monitoring system was validated in hospital trials across Northwestern Medicine in 2024 for continuous patient hydration assessment, where it supported a 48% reduction in dehydration incidence among post-surgical patients.
By Technology
The market is segmented into Bluetooth, Wi-Fi, NFC, and embedded systems. Bluetooth and Wi-Fi technologies hold the largest share, commonly integrated into wearables and mobile devices. Embedded systems are critical in clinical-grade devices, valued for reliability and precision. NFC technology is still emerging, with niche use in contactless health data sharing.
By End User
End users include the healthcare sector, sports and fitness, and the broader consumer market. Healthcare dominates with widespread deployment in hospitals and elder care. Sports and fitness applications are rising rapidly, especially among organized teams and performance coaches. The consumer segment is expanding as wellness-focused users adopt hydration tracking tools.
By Distribution Channel
Distribution channels include online retail, offline retail, and direct sales. Online retail is growing fastest due to consumer demand for convenience and broader product access. Offline retail maintains relevance in medical supply stores and fitness outlets. Direct sales are favored for B2B transactions, particularly by device manufacturers selling to hospitals or clinics.
Segmentation:
By Device Type
- Wearable Devices
- Non-Wearable Devices
- Smart Sensors
- Mobile Applications
- Integrated Systems
By Application
- Chronic Disease Management
- Sports Performance Monitoring
- General Health and Wellness
- Patient Monitoring
By Technology
- Bluetooth Technology
- Wi-Fi Technology
- NFC Technology
- Embedded Systems
By End User
- Healthcare Sector
- Sports and Fitness
- Consumer Market
By Distribution Channel
- Online Retail
- Offline Retail
- Direct Sales
By Region and Country
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Dehydration Monitoring Systems Market size was valued at USD 143.44 million in 2018 to USD 173.51 million in 2024 and is anticipated to reach USD 301.59 million by 2032, at a CAGR of 7.2% during the forecast period. North America holds the highest share of the global market due to early adoption of healthcare innovations, strong hospital networks, and advanced insurance infrastructure. U.S.-based start-ups and academic institutions are heavily investing in biosensor R&D. Consumer awareness, coupled with regulatory support, drives higher adoption rates across sports, hospitals, and elderly care.
Europe
The Europe Dehydration Monitoring Systems Market size was valued at USD 83.15 million in 2018 to USD 96.91 million in 2024 and is anticipated to reach USD 157.03 million by 2032, at a CAGR of 6.3%. Europe is experiencing steady growth supported by public healthcare systems and an aging population. Germany, France, and the UK are the leading markets with significant investments in digital health solutions. Policies promoting telemedicine and home-based care contribute to growing interest in wearable hydration monitoring.
Asia Pacific
The Asia Pacific Dehydration Monitoring Systems Market size was valued at USD 111.93 million in 2018 to USD 142.21 million in 2024 and is anticipated to reach USD 269.51 million by 2032, at a CAGR of 8.3%. Asia Pacific is the fastest-growing regional market due to population growth, urbanization, and government support for digital health. China, Japan, India, and South Korea are key players driving adoption through hospital upgrades and increasing sports participation. Affordability and mobile compatibility are crucial features for success in this region.
Latin America
The Latin America Dehydration Monitoring Systems Market size was valued at USD 26.99 million in 2018 to USD 32.75 million in 2024 and is anticipated to reach USD 53.24 million by 2032, at a CAGR of 6.3%. Brazil and Mexico lead the region with active digital health pilot programs. Rising awareness of occupational health and sports medicine is creating demand for hydration monitoring systems. Government interest in public-private health partnerships is helping overcome infrastructural barriers.
Middle East
The Middle East Dehydration Monitoring Systems Market size was valued at USD 15.29 million in 2018 to USD 17.57 million in 2024 and is anticipated to reach USD 27.68 million by 2032, at a CAGR of 5.9%. Countries like UAE and Saudi Arabia are investing in smart hospitals and wellness initiatives. Hydration monitoring is increasingly used in labor-intensive sectors such as construction and oil extraction. The region’s hot climate heightens the risk of dehydration, supporting market demand.
Africa
The Africa Dehydration Monitoring Systems Market size was valued at USD 9.20 million in 2018 to USD 14.52 million in 2024 and is anticipated to reach USD 22.00 million by 2032, at a CAGR of 5.0%. Africa remains underpenetrated but holds long-term potential. Mobile-based solutions with minimal infrastructure requirements are gaining traction. International aid programs and NGO-led health initiatives are introducing dehydration monitors to rural clinics and disaster-prone regions.
Key Player Analysis:
- Koninklijke Philips N.V.
- Baxter International Inc.
- Hill-Rom Holdings, Inc.
- Masimo Corporation
- Otsuka Holdings Co., Ltd.
- Abbott Laboratories
- GE HealthCare
- Medtronic plc
- Siemens Healthineers
- ZOLL Medical Corporation
Competitive Analysis:
The Global Dehydration Monitoring Systems Market features a moderately competitive landscape with a mix of established medical device companies and emerging health tech startups. Leading players such as Koninklijke Philips N.V., Abbott Laboratories, Masimo Corporation, and Baxter International Inc. focus on product innovation, strategic collaborations, and integration with digital health platforms. It reflects a growing emphasis on real-time monitoring, mobile connectivity, and sensor accuracy. Smaller firms are entering the market with wearable solutions that target niche segments such as sports performance and pediatric care. Companies are investing in R&D to improve device precision, miniaturization, and usability. Partnerships with healthcare providers and fitness organizations are helping accelerate product adoption. The Global Dehydration Monitoring Systems Market is witnessing increased interest in home-based and remote care applications, driving competition in the consumer segment. Regulatory compliance and data privacy standards remain critical factors influencing the pace of market entry and product expansion strategies.
Recent Developments:
- In July 2025, Otsuka Holdings launched POCARI SWEAT in India. This ready-to-drink health product is engineered to replenish water and electrolytes lost through sweat-directly supporting dehydration prevention in hot climates and among at-risk populations. In January 2025, Otsuka Pharmaceutical Factory also switched the 300 mL PET bottles for OS-1 Oral Rehydration Solution to 100% recycled PET, underscoring the company’s commitment to sustainability within its hydration portfolio.
- In June 2025, Koninklijke Philips N.V. expanded its long-term partnership with Medtronic through a new multi-year agreement. This collaboration aims to streamline and integrate advanced patient monitoring technologies-including dehydration and fluid management devices-by bundling Philips monitoring systems with Medtronic’s monitoring consumables and supplies. This strategic initiative focuses on simplifying procurement and enhancing clinical workflow efficiency for healthcare providers, beginning in North America with plans for global rollout.
- In April 2025, Medtronic plc expanded its Acute Care & Monitoring portfolio through an exclusive U.S. distribution agreement for the Argos™ cardiac output monitor with Retia Medical. Argos™ uses advanced hemodynamic algorithms to provide critical data on circulatory status, supporting personalized hydration and fluid management for surgical and critically ill patients in real time.
Market Concentration & Characteristics:
The Global Dehydration Monitoring Systems Market exhibits moderate market concentration, with a few dominant players holding significant shares and several emerging companies contributing to innovation. It is characterized by steady technological advancement, strong demand for non-invasive monitoring, and increasing integration with mobile health platforms. The market favors companies with robust R&D capabilities and the ability to comply with strict regulatory standards. Product differentiation is driven by device accuracy, user-friendliness, and compatibility with digital ecosystems. It continues to evolve with the growing emphasis on preventive care and remote health management. The presence of both established healthcare firms and agile startups creates a dynamic environment where innovation and strategic partnerships define competitive advantage.
Report Coverage:
The research report offers an in-depth analysis based on Device Type, Application, Technology and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global awareness of hydration-related health risks will drive broader adoption across clinical and consumer settings.
- Increasing prevalence of chronic conditions will boost demand for continuous fluid monitoring in home and hospital care.
- Wearable device innovation will enhance user engagement through improved comfort, real-time data, and mobile integration.
- Expansion of remote care and telehealth will position dehydration monitoring as a core tool in virtual patient management.
- Growth in sports science and performance tracking will increase uptake among athletes and fitness professionals.
- Emerging markets will contribute significantly, supported by healthcare infrastructure development and mobile health adoption.
- Advancements in sensor miniaturization and energy efficiency will improve device accessibility and lifespan.
- Strategic collaborations between tech firms and healthcare providers will accelerate market penetration.
- Regulatory clarity and stronger reimbursement frameworks will encourage adoption in both public and private sectors.
- AI-driven analytics will enhance diagnostic accuracy and personalize hydration insights across user groups.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Emphasis on Preventive Healthcare and Fluid Balance Management
Healthcare systems are prioritizing early detection and management of dehydration, especially for chronic disease and elderly populations, to reduce hospital readmissions and improve at-home care outcomes. This is driving adoption of real-time, non-invasive dehydration monitoring systems.
Technological Advancements and Mobile Health Integration
Innovations in biosensors, wireless connectivity, and smartphone integration have made dehydration monitoring more accurate, user-friendly, and accessible, expanding use beyond clinical settings into consumer wellness and sports applications.
Expanding Applications in Sports, Military, and Occupational Health
High-risk groups such as athletes, military personnel, and industrial workers are increasingly using dehydration monitoring systems to optimize performance and safety, fueling demand in these specialized segments.
Regulatory Push and Public Health Initiatives
Government-backed campaigns and regulatory frameworks are promoting early dehydration detection and preventive care, especially in climate-vulnerable and disease-prone regions, increasing market penetration and funding for monitoring technologies.
Integration with Comprehensive Health Ecosystems
The trend toward holistic health monitoring is driving demand for dehydration monitoring systems that can seamlessly integrate with platforms tracking other health metrics, enhancing their value in chronic care, telemedicine, and wellness programs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Dehydration Monitoring Systems Market?
What are the key segments within the Global Dehydration Monitoring Systems Market?
What are some challenges faced by the Global Dehydration Monitoring Systems Market?
Who are the major players in the Global Dehydration Monitoring Systems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Healthcare Sector
- 1.2.2 Sports and Fitness
- 1.2.3 Consumer Market
- 1.3 By Technology
- 1.3.1 Bluetooth Technology
- 1.3.2 Wi-Fi Technology
- 1.3.3 NFC Technology
- 1.3.4 Embedded Systems
- 1.4 By Application
- 1.4.1 Chronic Disease Management
- 1.4.2 Sports Performance Monitoring
- 1.4.3 General Health and Wellness
- 1.4.4 Patient Monitoring
- 1.5 By Device Type
- 1.5.1 Wearable Devices
- 1.5.2 Non-Wearable Devices
- 1.5.3 Smart Sensors
- 1.5.4 Mobile Applications
- 1.5.5 Integrated Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 477.46 million → 2032: USD 831.04 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dehydration Monitoring Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dehydration Monitoring Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dehydration Monitoring Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dehydration Monitoring Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dehydration Monitoring Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dehydration Monitoring Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dehydration Monitoring Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dehydration Monitoring Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 477.46 million → 2032: USD 831.04 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dehydration Monitoring Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Healthcare Sector
- 12.3.7.2 Sports and Fitness
- 12.3.7.3 Consumer Market
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bluetooth Technology
- 12.4.7.2 Wi-Fi Technology
- 12.4.7.3 NFC Technology
- 12.4.7.4 Embedded Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Chronic Disease Management
- 12.5.7.2 Sports Performance Monitoring
- 12.5.7.3 General Health and Wellness
- 12.5.7.4 Patient Monitoring
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Device Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Wearable Devices
- 12.6.7.2 Non-Wearable Devices
- 12.6.7.3 Smart Sensors
- 12.6.7.4 Mobile Applications
- 12.6.7.5 Integrated Systems
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dehydration Monitoring Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dehydration Monitoring Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dehydration Monitoring Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dehydration Monitoring Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Koninklijke Philips N.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Baxter International Inc.
- 18.4 Hill-Rom Holdings, Inc.
- 18.5 Masimo Corporation
- 18.6 Otsuka Holdings Co., Ltd.
- 18.7 Abbott Laboratories
- 18.8 GE HealthCare
- 18.9 Medtronic plc
- 18.10 Siemens Healthineers
- 18.11 ZOLL Medical Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

