
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
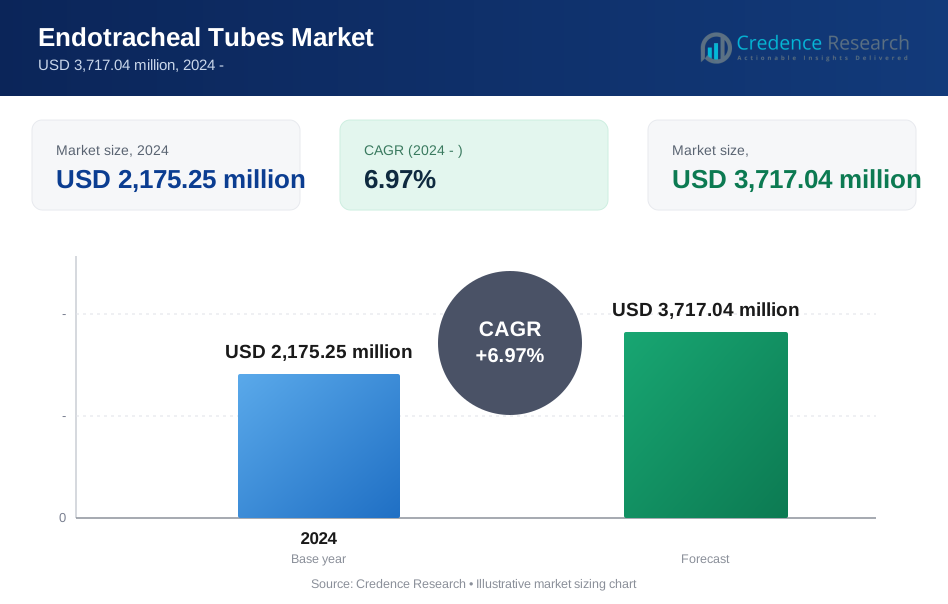
| Endotracheal Tube Market Size 2024 | USD 2,175.25 million |
| Endotracheal Tube Market, CAGR | 6.97% |
| Endotracheal Tube Market Size 2032 | USD 3,717.04 million |
Market Overview
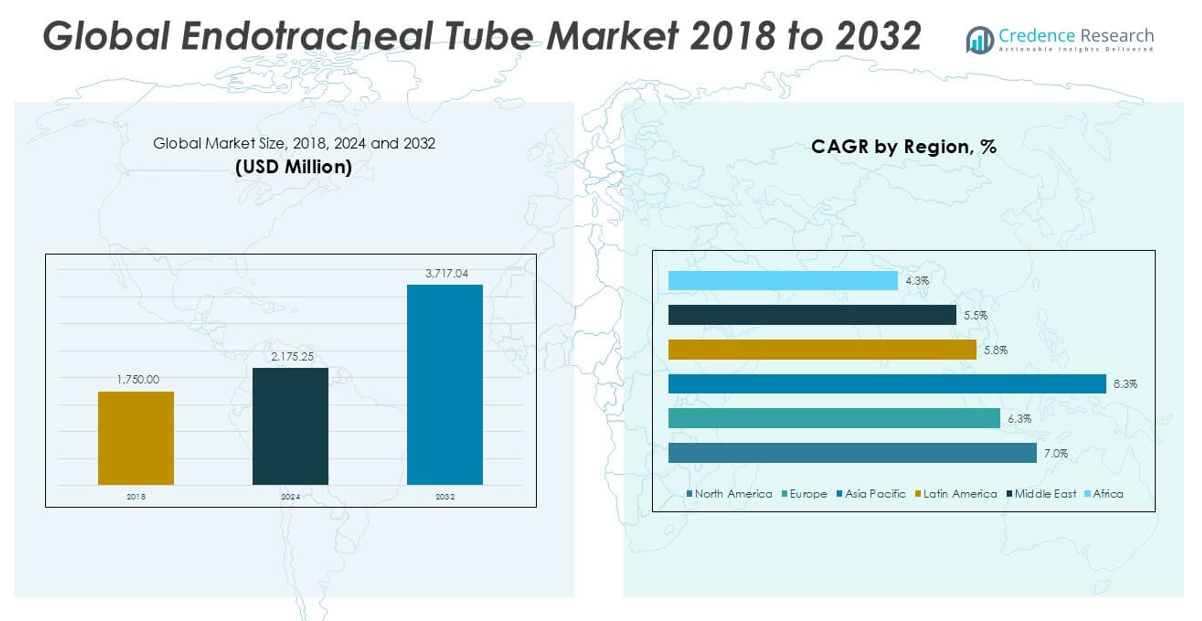
The Endotracheal Tube Market size was valued at USD 1,750.00 million in 2018, reached USD 2,175.25 million in 2024, and is anticipated to reach USD 3,717.04 million by 2032, at a CAGR of 6.97% during the forecast period.
The Endotracheal Tube market is highly competitive, with key players such as Medtronic (Covidien), Teleflex Incorporated, ICU Medical, Inc., BD (BESDATA), Angiplast Pvt Ltd, Advin Health Care, and BRIO DEVICE, LLC. driving market growth through product innovation, strategic collaborations, and global expansion. These companies focus on enhancing tube designs to improve patient safety and reduce ventilator-associated complications. North America leads the global market, holding a dominant share of 34.1% in 2024, supported by advanced healthcare infrastructure, a high volume of surgical procedures, and increasing adoption of technologically advanced medical devices. The region's strong regulatory framework and emphasis on infection control further reinforce its leadership position.
Market Insights
- The Endotracheal Tube market was valued at USD 2,175.25 million in 2024 and is expected to reach USD 3,717.04 million by 2032, growing at a CAGR of 6.97% during the forecast period.
- The increasing number of surgical procedures, rising cases of respiratory diseases, and growing emergency care admissions are key factors driving market growth globally.
- There is a strong trend towards the adoption of disposable endotracheal tubes and advanced tubes with antimicrobial coatings, aiming to minimize infection risks and improve patient outcomes.
- The market is highly competitive, with major players like Medtronic, Teleflex, and ICU Medical focusing on product innovation and strategic expansions, while smaller players offer cost-effective regional solutions.
- North America holds the largest regional share at 34.1% in 2024, followed by Europe and Asia Pacific at 27.4% each, with the hospital segment leading the end-use category due to high surgical volumes and emergency treatments.
Market Segmentation Analysis:
By Product
In the Endotracheal Tube market, the Regular Endotracheal Tube segment holds the largest market share due to its widespread use in routine surgical procedures and critical care settings. These tubes are preferred for their ease of use, availability in various sizes, and cost-effectiveness, making them a standard choice across healthcare facilities. The growing number of surgical interventions and increasing demand for airway management in emergency cases are key factors driving this segment's dominance. Additionally, advancements in tube material and design to reduce airway complications further support the market growth of this product category.
- For instance, Teleflex’s Hudson RCI® brand offers more than 25 different endotracheal tube configurations, including safety-oriented designs such as Murphy eye and Magill-type tubes, supporting their widespread applicability in varied clinical settings.
By Application
Emergency Treatment is the dominant sub-segment within the application category, accounting for the largest share in the Endotracheal Tube market. The high incidence of trauma cases, cardiac arrests, and respiratory failures requiring immediate airway management is a significant driver for this segment’s growth. Hospitals and emergency services prioritize rapid intubation to stabilize patients, which boosts the demand for endotracheal tubes in emergency scenarios. Additionally, increasing awareness about advanced life support techniques and the need for quick airway access in critical situations further propel the expansion of this segment.
- For instance, Medtronic’s Shiley™ emergency endotracheal tubes are widely used in pre-hospital emergency settings and have been implemented in over 5,000 EMS units across North America, demonstrating their critical role in life-saving procedures.
By End-use
Among end-users, Hospitals represent the largest market share in the Endotracheal Tube market, driven by the high volume of surgical procedures and emergency admissions requiring intubation. Hospitals are equipped with intensive care units, advanced surgical departments, and emergency services, making them primary users of endotracheal tubes. The rising prevalence of chronic respiratory diseases and the growing elderly population contribute to the increased demand within hospital settings. Moreover, the availability of skilled healthcare professionals and supportive healthcare infrastructure strengthens the segment’s dominant position in the overall market.
Market Overview
Rising Incidence of Chronic Respiratory Diseases
The increasing prevalence of chronic respiratory conditions such as chronic obstructive pulmonary disease (COPD), asthma, and respiratory infections is a primary driver for the Endotracheal Tube market. These conditions often require prolonged airway management, particularly in severe cases, thus boosting the demand for endotracheal tubes in both emergency and critical care settings. Additionally, the growing geriatric population, which is more prone to respiratory complications, further escalates the need for effective intubation solutions, driving steady market growth across global healthcare systems.
- For instance, ICU Medical’s portfolio includes over 10 million endotracheal tubes supplied globally for chronic respiratory management, especially supporting long-term ventilated patients in intensive care units.
Expanding Surgical Volume Worldwide
The rise in the number of surgical procedures globally, particularly in fields like cardiology, orthopedics, and oncology, significantly contributes to the increasing demand for endotracheal tubes. These tubes are essential for airway management during surgeries performed under general anesthesia. The expansion of healthcare infrastructure, coupled with greater access to surgical care in emerging economies, amplifies this trend. Moreover, advancements in surgical techniques and postoperative care further encourage the use of safe and reliable intubation devices, thereby supporting the growth of the endotracheal tube market.
- For instance, BD (Becton, Dickinson and Company) manufactures more than 15 million endotracheal tubes annually to meet the increasing demands of global surgical procedures, with significant supply contracts in high-volume surgical centers.
Technological Advancements in Tube Design
Continuous innovations in endotracheal tube design, such as the development of reinforced tubes, anti-microbial coatings, and subglottic secretion drainage systems, are propelling the market forward. These advancements aim to reduce the risks of ventilator-associated pneumonia (VAP) and improve patient comfort and safety. The adoption of specialized tubes for specific clinical scenarios also supports procedural efficiency and patient outcomes. Manufacturers are focusing on enhancing tube performance through improved materials and advanced designs, which is encouraging healthcare providers to upgrade their existing airway management devices.
Key Trends & Opportunities
Growing Demand for Disposable Endotracheal Tubes
There is a notable shift towards the use of disposable endotracheal tubes due to increasing concerns regarding cross-contamination and hospital-acquired infections. Disposable variants offer enhanced infection control and are gaining preference in both developed and developing markets. This trend aligns with stringent healthcare regulations emphasizing patient safety and hygiene. The rising awareness among healthcare providers about the risks of reusable medical devices further accelerates the adoption of disposable tubes, presenting a significant growth opportunity for manufacturers focusing on cost-effective, single-use solutions.
- For instance, Well Lead Medical Co., Ltd. reported the production of over 20 million single-use endotracheal tubes annually, meeting international demand, with their products supplied to more than 90 countries focusing on infection prevention protocols.
Expansion in Emerging Markets
Emerging economies in Asia-Pacific, Latin America, and the Middle East present substantial growth opportunities for the Endotracheal Tube market. Rapid urbanization, improving healthcare infrastructure, and increasing healthcare spending in these regions are driving higher demand for advanced airway management products. Additionally, governments and private healthcare providers in these markets are investing in expanding surgical and emergency care capabilities. As access to critical care improves and awareness of modern medical practices increases, the market is poised to grow significantly in these underpenetrated regions.
- For instance, Angiplast Pvt Ltd has expanded its manufacturing capacity by establishing a 50,000 sq. ft. medical device production plant in Ahmedabad, India, targeting increased supply to emerging markets across Asia and the Middle East.
Key Challenges
Risk of Ventilator-Associated Complications
Despite technological improvements, endotracheal intubation remains associated with significant clinical risks, including ventilator-associated pneumonia (VAP), airway injuries, and tube displacement. These complications can lead to extended hospital stays, increased treatment costs, and higher patient morbidity. Such risks often drive healthcare professionals to seek alternative airway management methods when feasible, potentially limiting the overall adoption of endotracheal tubes. Mitigating these clinical risks remains a key challenge for both manufacturers and healthcare providers aiming to improve patient safety.
High Cost of Advanced Endotracheal Tubes
While technological advancements in tube design offer improved patient outcomes, they also contribute to higher product costs. Advanced features such as antimicrobial coatings and subglottic drainage systems can make these tubes significantly more expensive than standard versions. In cost-sensitive markets, especially in low- and middle-income countries, hospitals may prefer more affordable options, which could restrict the adoption of premium products. Balancing cost and innovation is a continuing challenge for manufacturers targeting global market expansion.
Stringent Regulatory Approvals
Endotracheal tubes are classified as critical medical devices and are subject to strict regulatory approvals across various regions. Compliance with evolving safety standards and clinical performance requirements can extend product development timelines and increase operational costs for manufacturers. Regulatory hurdles can delay market entry and limit the availability of new products, particularly in highly regulated markets like the United States and Europe. Navigating these complex approval processes while ensuring product quality remains a significant barrier to growth.
Regional Analysis
North America
North America dominated the Endotracheal Tube market in 2024, holding the largest market share of approximately 34.1%, with a market size of USD 741.75 million, up from USD 604.45 million in 2018. The region is projected to reach USD 1,265.66 million by 2032, growing at a CAGR of 7.0%. The market's strong position is driven by the high volume of surgical procedures, advanced healthcare infrastructure, and growing awareness of infection control. Additionally, the increasing prevalence of chronic respiratory diseases and the rapid adoption of technologically advanced intubation devices further support regional growth.
Europe
Europe accounted for approximately 27.4% of the Endotracheal Tube market in 2024, with its market size rising from USD 497.00 million in 2018 to USD 595.52 million in 2024. It is expected to reach USD 965.51 million by 2032, progressing at a CAGR of 6.3% during the forecast period. The region’s growth is driven by well-established healthcare systems, a rising number of geriatric patients, and increasing surgical volumes. Moreover, stringent regulatory frameworks promoting the use of high-quality, infection-resistant medical devices contribute to the adoption of advanced endotracheal tubes across European healthcare facilities.
Asia Pacific
The Asia Pacific Endotracheal Tube market has shown strong momentum, securing a market share of approximately 27.4% in 2024, with a value of USD 577.41 million, growing from USD 445.55 million in 2018. The market is anticipated to reach USD 1,089.41 million by 2032, expanding at the fastest CAGR of 8.3% among all regions. The region’s rapid growth is supported by increasing healthcare investments, expanding surgical infrastructure, and rising awareness about infection control. Additionally, a growing population base, particularly in China and India, coupled with rising cases of respiratory illnesses, drives robust demand.
Latin America
Latin America represented around 5.4% of the global Endotracheal Tube market in 2024, with a market size of USD 117.44 million, up from USD 95.55 million in 2018. The market is forecasted to reach USD 183.88 million by 2032, growing at a CAGR of 5.8%. Regional growth is supported by the gradual improvement in healthcare infrastructure, rising adoption of emergency care services, and increasing surgical procedures. However, budget constraints in public healthcare settings may limit rapid adoption of premium products. Still, the market shows steady progress, especially in major economies like Brazil and Mexico.
Middle East
The Middle East accounted for approximately 4.4% of the global Endotracheal Tube market in 2024, increasing from USD 60.38 million in 2018 to USD 69.81 million. It is expected to reach USD 106.33 million by 2032, growing at a CAGR of 5.5%. Growth in this region is supported by increasing investments in hospital infrastructure and expanding access to advanced surgical care. Additionally, rising awareness regarding airway management and a growing number of trauma and emergency cases contribute to market expansion. However, the market faces challenges due to limited availability of specialized healthcare professionals.
Africa
Africa held the smallest share in the Endotracheal Tube market, with approximately 3.4% of the global market in 2024. The market grew from USD 47.08 million in 2018 to USD 73.31 million in 2024 and is projected to reach USD 106.25 million by 2032, expanding at a CAGR of 4.3%. The market's growth is primarily driven by gradually improving access to healthcare facilities, increasing awareness of emergency airway management, and expanding surgical capacity in key urban centers. Despite these advancements, the region’s growth is somewhat restrained by limited healthcare budgets and uneven healthcare accessibility across rural areas.
Market Segmentations:
By Product
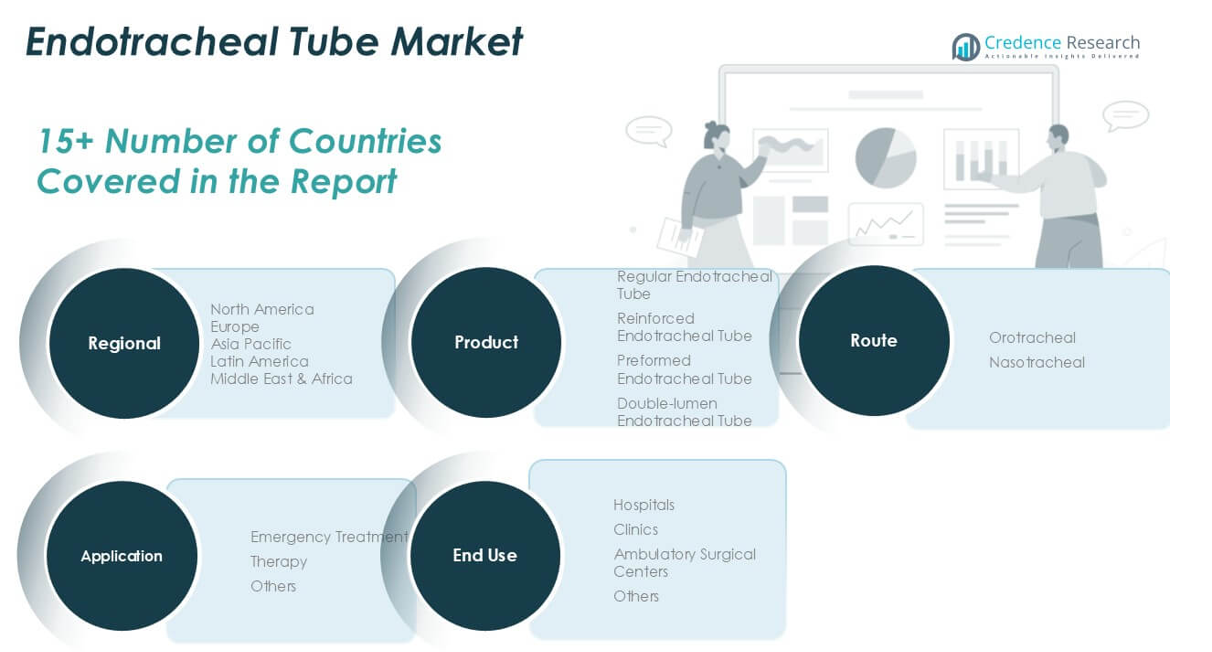
- Regular Endotracheal Tube
- Reinforced Endotracheal Tube
- Preformed Endotracheal Tube
- Double-lumen Endotracheal Tube
By Application
- Emergency Treatment
- Therapy
- Others
By End-use
- Hospitals
- Clinics
- Ambulatory Surgical Centers
- Others
By Route
- Orotracheal
- Nasotracheal
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Endotracheal Tube market is highly competitive, with several key players actively focusing on product innovation, strategic partnerships, and geographic expansion to strengthen their market presence. Major companies such as Medtronic (Covidien), Teleflex Incorporated, ICU Medical, Inc., and BD (BESDATA) dominate the market through their extensive product portfolios and strong distribution networks. These players invest significantly in research and development to introduce advanced features like anti-microbial coatings and subglottic suction capabilities that enhance patient safety and reduce ventilator-associated complications. Additionally, emerging companies such as Angiplast Pvt Ltd, Advin Health Care, and BRIO DEVICE, LLC. are contributing to market growth by offering cost-effective and specialized solutions, particularly targeting developing regions. Strategic mergers, acquisitions, and collaborations remain common as companies seek to expand their global footprint and diversify their product offerings. The competitive environment is further shaped by increasing regulatory scrutiny and the growing demand for single-use, infection-resistant endotracheal tubes across healthcare settings.
Key Player Analysis
- Angiplast Pvt Ltd
- Advin Health Care
- Sterimed Group
- ICU Medical, Inc.
- Medtronic (Covidien)
- Van Oostveen Medical B.V.
- Teleflex Incorporated
- Convatec Inc.
- Fuji Systems Corp
- SEWOON MEDICAL Co., Ltd.
- Mercury Medical
- Hollister Incorporated
- Well Lead Medical Co., Ltd
- Viggo Medical Devices
- ARMSTRONG MEDICAL
- Medline
- BD (BESDATA)
- BRIO DEVICE, LLC.
- pfm medical ag
Recent Developments
- In 2024, Angiplast Pvt Ltd focused on expanding its product line and integrating advanced manufacturing techniques to improve the safety and infection control of its medical tubes.
- In 2024, Advin Health Care strategically focused on new product launches and regional expansion to solidify its presence in the global endotracheal tube market. This aligns with broader trends in the market, including the increasing demand for endotracheal tubes due to rising respiratory diseases and technological advancements in patient ventilation.
- In 2024, Sterimed Group was actively involved in launching new products and expanding its market reach through collaborations and partnerships. Specifically, Starpharma reported clinical validation of their DEP® technology with over 350 patients treated, demonstrating promising anti-cancer activity and improved tolerability. Additionally, Sterimed Group continues to invest in R&D and quality assurance to design and develop new products. The company also restructured its capital base, welcoming new partners including IK Partners alongside existing investors.
- In 2024, Teleflex Incorporated continued its innovation in endotracheal tubes by integrating smart features like cuff pressure monitoring and infection control enhancements. They offer a range of clinically differentiated endotracheal tubes, including Sheridan® and Rüsch® brands, designed to improve procedural efficiency and patient safety during intubation.
Market Concentration & Characteristics
The Endotracheal Tube Market shows moderate to high market concentration, with a few dominant global players holding significant shares. Companies such as Medtronic, Teleflex Incorporated, and ICU Medical maintain strong positions through extensive product portfolios, technological advancements, and established distribution networks. The market favors manufacturers capable of delivering high-quality, infection-resistant, and cost-effective products. It demonstrates steady demand across developed regions due to the increasing number of surgeries and the need for advanced airway management. Emerging economies contribute to market expansion by adopting modern healthcare practices and improving surgical infrastructure. The market is characterized by continuous innovation focused on patient safety, reduced ventilator-associated complications, and improved material quality. Regulatory compliance remains critical, as stringent approval processes define entry barriers for new players. Pricing sensitivity persists in developing regions, encouraging the demand for affordable yet reliable endotracheal tubes. The preference for single-use products continues to rise, driven by the need to control hospital-acquired infections. It experiences stable procurement from hospitals, clinics, and ambulatory surgical centers, which value product reliability and clinical effectiveness. Strategic partnerships, mergers, and acquisitions remain key approaches for market participants aiming to strengthen their competitive edge and geographic reach.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-use, Route and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The endotracheal tube market is expected to witness steady growth driven by increasing surgical procedures worldwide.
- Rising demand for emergency and critical care services will continue to support market expansion.
- Technological advancements in tube design will focus on reducing infection risks and improving patient comfort.
- Disposable and single-use endotracheal tubes will gain higher adoption due to infection control practices.
- The prevalence of respiratory diseases and the growing geriatric population will drive consistent demand.
- Emerging markets in Asia Pacific and Latin America will offer significant growth opportunities for manufacturers.
- Regulatory bodies will continue to emphasize stringent quality and safety standards for endotracheal tubes.
- Market players will increasingly invest in strategic collaborations and geographic expansion to strengthen their position.
- Healthcare providers will prefer advanced tubes with features like subglottic suction and antimicrobial coatings.
- Price-sensitive regions will drive the demand for cost-effective and high-quality endotracheal tube solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Endotracheal tube market?
What factors are driving the growth of the Endotracheal tube market?
What are some challenges faced by the Endotracheal tube market?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Endotracheal Tubes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Endotracheal Tubes Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 2,175.25 million → forecast year: USD 3,717.04 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Endotracheal Tubes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Endotracheal Tubes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Endotracheal Tubes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Endotracheal Tubes Market Drivers
- 3.3 Endotracheal Tubes Market Restraints & Challenges
- 3.4 Endotracheal Tubes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Endotracheal Tubes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Endotracheal Tubes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Endotracheal Tubes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Endotracheal Tubes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Endotracheal Tubes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Endotracheal Tubes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Endotracheal Tubes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Endotracheal Tubes Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Endotracheal Tubes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Endotracheal Tubes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Endotracheal Tubes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Endotracheal Tubes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Endotracheal Tubes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Endotracheal Tubes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Endotracheal Tubes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Endotracheal Tubes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Endotracheal Tubes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Endotracheal Tubes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Endotracheal Tubes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
