
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hydrometallurgical Recycling Market Size 2024 | USD 1,432.0 million |
| Hydrometallurgical Recycling Market, CAGR | 15.40% |
| Hydrometallurgical Recycling Market Size 2032 | USD 4,503.9 million |
Market Overview
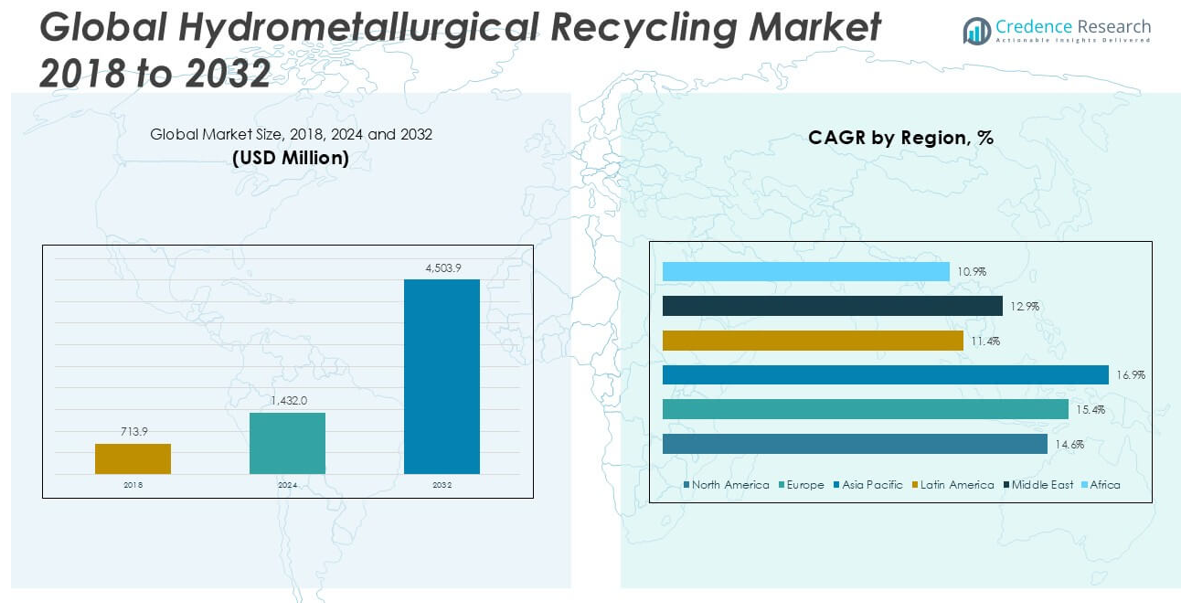
The Hydrometallurgical Recycling market size was valued at USD 713.9 million in 2018, grew to USD 1,432.0 million in 2024, and is anticipated to reach USD 4,503.9 million by 2032, at a CAGR of 15.40% during the forecast period.
The hydrometallurgical recycling market is driven by top players such as Li-Cycle, Umicore, BASF SE, Redwood Materials, Glencore, GEM Co., Ltd., American Battery Technology Company (ABTC), and RecycLiCo Battery Materials Inc. These companies lead the market through advanced recycling technologies, strategic capacity expansions, and strong global partnerships. Asia Pacific dominates the market with a leading share of approximately 36% in 2024, supported by the presence of major battery manufacturers, rapid electric vehicle adoption, and strong governmental support for sustainable recycling initiatives. Europe holds the second-largest share at around 29%, driven by stringent environmental regulations and well-established recycling infrastructure. North America follows closely, accounting for 26% of the market share, benefiting from rising EV penetration and significant investments in battery recycling facilities. These leading regions and key companies collectively shape the competitive landscape, focusing on high-efficiency metal recovery and sustainable waste management practices.
Market Insights
- The Hydrometallurgical Recycling market was valued at USD 1,432.0 million in 2024 and is projected to reach USD 4,503.9 million by 2032, growing at a CAGR of 15.40% during the forecast period.
- Market growth is driven by increasing electric vehicle adoption and strict environmental regulations promoting sustainable battery recycling and resource recovery.
- The market is witnessing trends like the development of advanced hydrometallurgical processes, rising strategic partnerships, and growing investment in closed-loop recycling systems.
- Key players such as Li-Cycle, Umicore, BASF SE, and Glencore are focusing on technological advancements and expanding recycling capacities, while high operational costs and complex battery chemistries remain major restraints.
- Asia Pacific leads the market with a 36% share in 2024, followed by Europe at 29% and North America at 26%; by battery chemistry, the Lithium-nickel Manganese Cobalt (Li-NMC) segment dominates due to its widespread use in electric vehicles.
Market Segmentation Analysis:
By Battery Chemistry:
In the Hydrometallurgical Recycling market, the Lithium-nickel Manganese Cobalt (Li-NMC) segment dominates, accounting for the largest market share in 2024. Li-NMC batteries are widely used due to their high energy density, long cycle life, and balanced performance, making them a preferred choice in electric vehicles (EVs) and portable electronics. The growing adoption of EVs globally significantly drives the demand for Li-NMC recycling, as manufacturers aim to recover valuable metals like nickel, cobalt, and lithium to reduce raw material dependency and production costs. The push for sustainable battery management further supports segment growth. The Lithium-iron Phosphate (LFP) segment is also gaining traction, driven by its increasing application in commercial vehicles and stationary energy storage systems. LFP batteries offer better thermal stability, lower cost, and longer safety margins, which make them attractive for utility and industrial uses. The recycling of LFP batteries is growing steadily, supported by rising installations of renewable energy storage systems. Other chemistries like Lithium-manganese Oxide (LMO), Lithium-titanate Oxide (LTO), and Lithium-nickel Cobalt Aluminum Oxide (NCA) contribute smaller shares but show growth potential with advancements in recycling technology and increasing volume of end-of-life batteries across multiple sectors.
- For instance, BASF's Schwarzheide plant in Germany processes LFP batteries using hydrometallurgical methods to efficiently extract lithium with recovery yields reaching over 90% in pilot-scale operations.
By End Use
The automotive segment leads the Hydrometallurgical Recycling market, holding the largest market share in 2024, driven by the rapid expansion of the electric vehicle (EV) industry. The substantial rise in EV adoption generates a growing volume of spent batteries, prompting recycling to recover valuable metals and support circular economy initiatives. Automakers are actively collaborating with recycling companies to ensure efficient battery lifecycle management and compliance with environmental regulations. This focus on sustainable sourcing and cost-effective raw material recovery significantly strengthens the dominance of the automotive sector. The industrial segment is also witnessing strong growth, fueled by the increasing demand for energy storage solutions in manufacturing, data centers, and heavy machinery. Industrial batteries are now being recycled at a faster rate due to the cost benefits of metal recovery and the environmental push to minimize hazardous waste. The power segment, driven by grid-scale energy storage projects, and the marine segment, with rising electrification in marine transport, are emerging areas that offer future opportunities. However, automotive applications remain the primary growth engine of the Hydrometallurgical Recycling market.
- For instance, Glencore processes large-format industrial lithium-ion batteries, recovering over 12,000 metric tons of cobalt annually through hydrometallurgical recycling in its European plants.
Market Overview
Rising Electric Vehicle Adoption
The rapid expansion of the electric vehicle (EV) market significantly drives the hydrometallurgical recycling market. Increasing EV production leads to a surge in spent lithium-ion batteries, creating a critical need for efficient recycling solutions. Hydrometallurgical recycling offers a sustainable method to recover valuable metals like lithium, nickel, and cobalt, reducing raw material dependency. Automakers and governments are investing heavily in battery recycling infrastructure to meet environmental regulations and promote a circular economy, further accelerating market growth.
- For instance, American Battery Technology Company (ABTC) processed over 20,000 lithium-ion battery cells from EV sources in 2023, successfully recovering high-purity battery-grade nickel and cobalt through its hydrometallurgical process.
Supportive Environmental Regulations
Stringent environmental regulations worldwide encourage the adoption of hydrometallurgical recycling processes. Governments in key regions are enforcing policies to limit hazardous waste and promote sustainable battery disposal methods. Hydrometallurgical recycling is favored due to its lower emissions and reduced environmental impact compared to traditional pyrometallurgical processes. Regulatory support through subsidies, tax benefits, and recycling targets is driving companies to adopt advanced recycling technologies, creating long-term growth opportunities in the market.
- For instance, Fortum’s hydrometallurgical recycling operations in Finland meet the strict EU environmental directives and successfully process over 3,000 tonnes of EV batteries per year with compliance to end-of-life recycling targets set by the European Commission.
Increasing Raw Material Scarcity
The rising scarcity and price volatility of critical raw materials like lithium, cobalt, and nickel are major growth drivers for the hydrometallurgical recycling market. Mining new materials is expensive, time-consuming, and environmentally damaging, making recycling a cost-effective and sustainable alternative. Battery manufacturers and end users are increasingly focusing on securing a stable supply of secondary raw materials through efficient recycling channels, boosting demand for hydrometallurgical recycling services and technologies.
Key Trends & Opportunities
Technological Advancements in Recycling Processes
Continuous advancements in hydrometallurgical recycling technologies are creating significant growth opportunities. Innovations focused on improving metal recovery rates, reducing processing time, and minimizing chemical waste are enhancing the efficiency and cost-effectiveness of recycling operations. Companies are developing proprietary methods to extract high-purity metals with minimal environmental impact, positioning themselves competitively. This trend supports the broader adoption of hydrometallurgical recycling as the preferred solution for handling end-of-life batteries.
- For instance, RecycLiCo Battery Materials Inc. has achieved laboratory-scale lithium recovery efficiencies of over 99% and has successfully scaled this technology in its demonstration plant with the capability to process 500 kilograms of battery waste per day.
Strategic Collaborations and Capacity Expansion
Strategic partnerships between battery manufacturers, automotive companies, and recycling service providers are emerging as key market trends. Companies are investing in capacity expansions and joint ventures to strengthen recycling networks and improve collection systems. Such collaborations help secure material supply chains and ensure regulatory compliance. The growing focus on closed-loop recycling systems, where recovered materials are reused in battery manufacturing, presents long-term growth potential for industry participants.
- For instance, Umicore signed a long-term agreement with Volkswagen Group to supply recycled battery cathode materials, targeting the annual recycling of up to 150,000 metric tons of battery materials in their upcoming facility in Poland
Key Challenges
High Operational and Capital Costs
One of the major challenges in the hydrometallurgical recycling market is the high initial capital investment required to set up advanced recycling facilities. Operational costs associated with chemical processing, waste treatment, and energy consumption further strain profitability, especially for smaller players. Companies need substantial financial resources to scale operations while maintaining compliance with stringent environmental standards, which can limit market entry for new participants.
Complex Battery Chemistries
The increasing diversity of lithium-ion battery chemistries complicates the recycling process. Different battery types require customized treatment and chemical solutions, making the hydrometallurgical recycling process more complex and resource-intensive. This challenge raises operational costs and necessitates ongoing research to develop flexible and efficient recycling methods capable of handling mixed battery streams without compromising metal recovery rates.
Limited Collection and Logistics Infrastructure
Inadequate collection systems and underdeveloped logistics networks pose significant challenges to the hydrometallurgical recycling market. The collection of spent batteries from end users and the transportation to recycling facilities often lack efficiency and standardization. This results in lower battery recovery rates and increased logistical costs. Building a robust collection framework and expanding transportation capabilities are essential to ensure a steady supply of recyclable batteries and support market growth.
Regional Analysis
North America
In 2024, the North America hydrometallurgical recycling market was valued at USD 372.3 million, accounting for approximately 26% of the global market share. The market is projected to reach USD 1,026.9 million by 2032, growing at a CAGR of 14.6% during the forecast period. North America’s growth is driven by the rapid adoption of electric vehicles (EVs), strict environmental policies, and increasing investment in battery recycling infrastructure. With a market size of USD 203.5 million in 2018, the region has demonstrated steady expansion supported by government initiatives focused on sustainable waste management and the circular economy.
Europe
Europe held around 29% of the global hydrometallurgical recycling market share in 2024, with a market size of USD 415.3 million, up from USD 192.8 million in 2018. The region is expected to reach USD 1,324.1 million by 2032, registering a CAGR of 15.4%. Europe's growth is driven by stringent EU regulations promoting battery recycling, growing EV penetration, and strong manufacturer participation in closed-loop recycling programs. Increasing government subsidies and robust collection infrastructure further support the regional market. Europe’s leadership in sustainable practices and green energy adoption positions it as a critical player in the global recycling landscape.
Asia Pacific
The Asia Pacific region dominated the hydrometallurgical recycling market in 2024 with the largest market share of approximately 36%, valued at USD 515.5 million, rising from USD 251.3 million in 2018. It is projected to reach USD 1,720.5 million by 2032, expanding at a CAGR of 16.9%, the fastest among all regions. The region’s growth is driven by the rapid industrialization, significant electric vehicle production, and the presence of leading battery manufacturers in China, Japan, and South Korea. Government support for battery recycling initiatives and increasing awareness of resource sustainability contribute to Asia Pacific’s market dominance.
Latin America
Latin America accounted for about 3% of the global hydrometallurgical recycling market share in 2024, with a market size of USD 41.5 million, up from USD 19.3 million in 2018. The market is anticipated to grow to USD 153.1 million by 2032, registering a CAGR of 11.4%. The region’s growth is gradually improving due to the increasing adoption of green technologies and expanding renewable energy projects. Although the market size remains comparatively smaller, rising awareness of sustainable waste management and ongoing infrastructure development are expected to provide moderate growth opportunities in the coming years.
Middle East
In 2024, the Middle East hydrometallurgical recycling market was valued at USD 64.4 million, holding nearly 5% of the global market share, up from USD 30.7 million in 2018. The market is forecasted to reach USD 234.2 million by 2032, growing at a CAGR of 12.9%. The region is showing steady progress supported by government efforts to diversify economies and focus on sustainable waste disposal methods. While the Middle East is still developing its battery recycling infrastructure, increasing demand for electric vehicles and renewable energy storage solutions is expected to boost market growth over the forecast period.
Africa
Africa contributed approximately 2% of the global hydrometallurgical recycling market share in 2024, with a market size of USD 22.9 million, increasing from USD 16.4 million in 2018. The market is projected to reach USD 45.0 million by 2032, expanding at a CAGR of 10.9%, the slowest among the regions analyzed. Limited recycling infrastructure and lower adoption of electric vehicles currently restrain the market. However, with gradual improvements in industrialization, growing environmental awareness, and potential international collaborations, Africa is expected to witness steady growth in battery recycling activities over the forecast period.
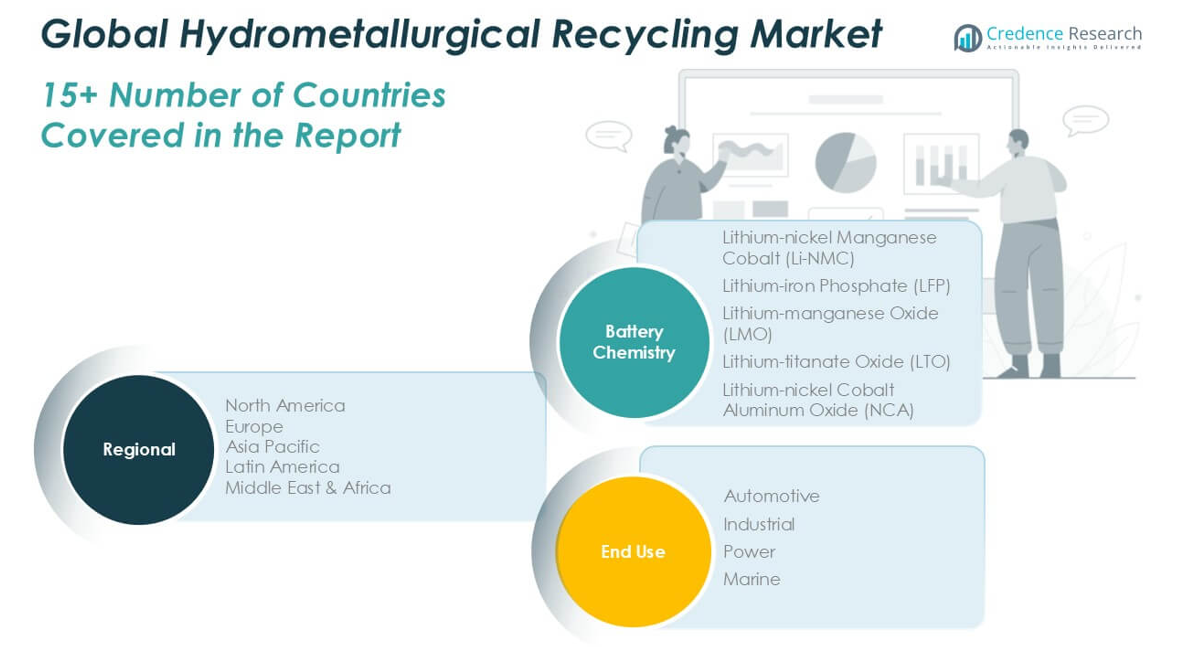
Market Segmentations:
By Battery Chemistry:
- Lithium-nickel Manganese Cobalt (Li-NMC)
- Lithium-iron Phosphate (LFP)
- Lithium-manganese Oxide (LMO)
- Lithium-titanate Oxide (LTO)
- Lithium-nickel Cobalt Aluminum Oxide (NCA)
By End Use:
- Automotive
- Industrial
- Power
- Marine
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The hydrometallurgical recycling market is highly competitive, with key players focusing on technological advancements, capacity expansion, and strategic partnerships to strengthen their market position. Major companies such as Li-Cycle, Umicore, BASF SE, Redwood Materials, and Glencore lead the market with extensive recycling networks and advanced metal recovery processes. These players are investing in research and development to improve extraction efficiency, reduce environmental impact, and handle diverse battery chemistries. Emerging companies like American Battery Technology Company (ABTC) and RecycLiCo Battery Materials Inc. are contributing to the competitive intensity through innovative recycling technologies and regional expansions. Strategic collaborations between battery manufacturers, automakers, and recyclers are shaping the industry, as firms seek to develop closed-loop supply chains. Additionally, companies such as Fortum, TES-AMM, and Duesenfeld GmbH are enhancing their service offerings to meet growing regulatory and environmental demands. The competition is expected to intensify as demand for sustainable battery disposal and material recovery continues to rise globally.
Key Player Analysis
- Li-Cycle
- Umicore
- BASF SE
- Redwood Materials
- Glencore
- GEM Co., Ltd.
- American Battery Technology Company (ABTC)
- RecycLiCo Battery Materials Inc.
- ACCUREC Recycling GmbH
- Fortum
- TES-AMM
- Duesenfeld GmbH
- Ecobat
- Stena Recycling
Recent Developments
- In April 2025, Glencore set a target for 25% recycled content in its battery-grade metals by 2025 as part of its EU critical minerals recycling strategy. Glencore is investing $2.8 billion (15% of 2024 capex) in advanced recycling, focusing on maximizing metal recovery from battery black mass. The company’s modernization of the Sudbury smelter reduced emissions by 22% and increased recycled throughput. While Glencore primarily uses pyrometallurgical routes, it is advancing technical capabilities in hydrometallurgy to support its recycling ambitions.
- In March 2025, Umicore announced the introduction of a new state-of-the-art hydrometallurgical set-up as part of its recycling business. The company’s integrated process recovers 17 metals and is being upgraded to enhance environmental performance, increase yields, and comply with upcoming EU air quality directives. Investments of approximately €400 million are planned by 2030, with €300 million allocated for 2027–2028. The new hydro set-up aims to further reduce emissions, improve process efficiency, and support Umicore’s position as a leading global refiner.
- In November 2023, Redwood Materials announced that its hydrometallurgical process for recycling lithium-ion batteries achieves a 95% lithium recovery rate. This process is notable for eliminating peroxide, operating a zero-liquid-discharge campus, and using a reductive calciner powered by battery energy. The resulting high-purity nickel, lithium, and other metals are then used in new battery production, and Redwood Materials operates the largest such facility in North America.
Market Concentration & Characteristics
The Hydrometallurgical Recycling Market is moderately concentrated, with a mix of established global players and emerging regional companies competing for market share. It is shaped by the presence of key players with strong technological capabilities and significant recycling infrastructure. The market favors companies that offer efficient, high-purity metal recovery processes and can manage complex battery chemistries. Competitive intensity is rising due to increasing demand for sustainable battery disposal and growing environmental regulations. Large firms dominate through vertical integration and strategic partnerships with automotive and battery manufacturers. The market shows high barriers to entry due to substantial capital requirements, strict compliance standards, and the need for advanced chemical processing expertise. It is characterized by steady innovation, with leading companies investing in process improvements to enhance recovery rates and reduce operational costs. The market's growth also depends on the development of reliable collection systems and expanded regional recycling capacities to ensure consistent feedstock supply.
Report Coverage
The research report offers an in-depth analysis based on Battery Chemistry, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The hydrometallurgical recycling market is expected to grow steadily driven by increasing electric vehicle adoption worldwide.
- Demand for efficient battery recycling processes will rise as raw material scarcity becomes a critical global concern.
- Technological advancements will continue to improve metal recovery rates and reduce environmental impact.
- Regulatory support for sustainable recycling practices will further accelerate market expansion in key regions.
- Strategic collaborations between automakers, battery producers, and recyclers will become more common to secure material supply chains.
- Asia Pacific will maintain its leading position due to strong EV production and government-backed recycling initiatives.
- Europe and North America will see stable growth supported by strict environmental policies and established recycling infrastructures.
- Investment in the development of closed-loop recycling systems will increase across the industry.
- Companies will focus on expanding regional collection networks to improve access to end-of-life batteries.
- Market players will continue to face challenges from high operational costs and complex battery chemistries.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Electric Vehicle Adoption
The rapid growth of the electric vehicle (EV) market is generating a surge in spent lithium-ion batteries, creating a critical need for efficient recycling solutions. Hydrometallurgical recycling enables the recovery of valuable metals from these batteries, supporting the circular economy and reducing raw material dependency.
Supportive Environmental Regulations
Stringent environmental policies and recycling mandates in key regions are encouraging the adoption of hydrometallurgical recycling processes. These regulations promote sustainable battery disposal and provide incentives for companies to invest in advanced recycling technologies.
Increasing Raw Material Scarcity
The scarcity and price volatility of critical materials like lithium, cobalt, and nickel are driving manufacturers and recyclers to recover these metals from end-of-life batteries. Hydrometallurgical recycling offers a cost-effective and sustainable alternative to mining, ensuring a stable supply of secondary raw materials.
Technological Advancements in Recycling Processes
Continuous innovation in hydrometallurgical methods is improving metal recovery rates, reducing processing time, and minimizing environmental impact. These advancements make recycling more efficient and economically viable, encouraging broader industry adoption.
Strategic Collaborations and Capacity Expansion
Partnerships between battery manufacturers, automakers, and recyclers are strengthening recycling networks and expanding processing capacities. These collaborations help secure material supply chains and support the development of closed-loop recycling systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hydrometallurgical Recycling Market?
What are the key segments within the Hydrometallurgical Recycling Market?
What are some challenges faced by the Hydrometallurgical Recycling Market?
Who are the major players in the Hydrometallurgical Recycling Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Automotive
- 1.2.2 Industrial
- 1.2.3 Power
- 1.2.4 Marine
- 1.3 By Battery Chemistry
- 1.3.1 Lithium-nickel Manganese Cobalt (Li-NMC)
- 1.3.2 Lithium-iron Phosphate (LFP)
- 1.3.3 Lithium-manganese Oxide (LMO)
- 1.3.4 Lithium-titanate Oxide (LTO)
- 1.3.5 Lithium-nickel Cobalt Aluminum Oxide (NCA)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,432.0 million → 2032: USD 4,503.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hydrometallurgical Recycling Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hydrometallurgical Recycling Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hydrometallurgical Recycling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hydrometallurgical Recycling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hydrometallurgical Recycling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hydrometallurgical Recycling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hydrometallurgical Recycling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hydrometallurgical Recycling Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,432.0 million → 2032: USD 4,503.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hydrometallurgical Recycling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive
- 12.3.7.2 Industrial
- 12.3.7.3 Power
- 12.3.7.4 Marine
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Battery Chemistry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lithium-nickel Manganese Cobalt (Li-NMC)
- 12.4.7.2 Lithium-iron Phosphate (LFP)
- 12.4.7.3 Lithium-manganese Oxide (LMO)
- 12.4.7.4 Lithium-titanate Oxide (LTO)
- 12.4.7.5 Lithium-nickel Cobalt Aluminum Oxide (NCA)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hydrometallurgical Recycling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hydrometallurgical Recycling Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hydrometallurgical Recycling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hydrometallurgical Recycling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Li-Cycle
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Umicore
- 18.4 BASF SE
- 18.5 Redwood Materials
- 18.6 Glencore
- 18.7 GEM Co., Ltd.
- 18.8 American Battery Technology Company (ABTC)
- 18.9 RecycLiCo Battery Materials Inc.
- 18.10 Fortum
- 18.11 TES-AMM
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

