
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Hyperlocal Grocery Delivery Market Size 2024 | USD 38,512 Million |
| Hyperlocal Grocery Delivery Market, CAGR | 8.3% |
| Hyperlocal Grocery Delivery Market Size 2032 | USD 72,882.57 Million |
Market Overview:
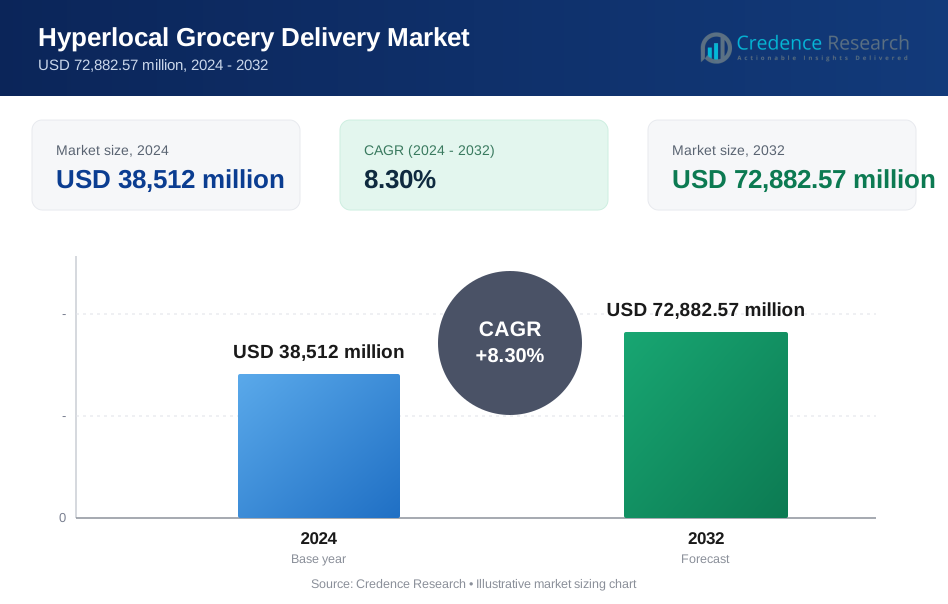
The Hyperlocal Grocery Delivery Market is poised to grow from USD 38,512 million in 2024 to USD 72,882.57 million by 2032, at a compound annual growth rate (CAGR) of 8.3% during the forecast period 2024-2032.
This growth is driven by the increasing demand for rapid and efficient delivery services within local areas, fueled by the expansion of e-commerce and the rising popularity of online grocery shopping. Several factors are driving the growth of the Hyperlocal Grocery Delivery Market. The growing demand for convenience and time-saving services is a primary driver, as consumers increasingly prefer to have groceries delivered to their doorsteps within hours. The penetration of high-speed internet and the widespread use of smartphones have made hyperlocal delivery services more accessible to consumers. Additionally, technological advancements such as real-time tracking, artificial intelligence (AI), and machine learning (ML) for improved delivery efficiency are contributing to market growth. The COVID-19 pandemic has also accelerated the adoption of online grocery shopping, further boosting the market.
Regionally, North America holds a significant share of the Hyperlocal Grocery Delivery Market, driven by the high adoption rate of hyperlocal delivery services and the presence of major players and technology providers in the region. Asia-Pacific is emerging as the fastest-growing region, with China and India being the leading contributors. The market in this region is bolstered by substantial investments in infrastructure, rising urbanization, and increasing consumer awareness of online grocery shopping. Europe also plays a crucial role in the market, with increasing adoption of hyperlocal delivery services and favorable government initiatives supporting market growth.
Market Insights:
- The hyperlocal grocery delivery market is projected to grow from USD 38,512 million in 2024 to USD 72,882.57 million by 2032, driven by a CAGR of 3%.
- Rising urbanization and busy consumer lifestyles are fueling the demand for convenient and fast grocery delivery solutions.
- Technological advancements, such as app-based ordering and AI-powered logistics, have streamlined operations, enhancing customer satisfaction.
- The COVID-19 pandemic accelerated the adoption of online grocery shopping, making it an integral part of consumer habits.
- North America holds a significant market share, driven by high internet penetration and advanced logistics infrastructure.
- The Asia-Pacific region is the fastest-growing market, fueled by increasing smartphone penetration and an expanding middle-class population.
- Challenges include high operational costs and logistical complexities, particularly in rural areas with limited infrastructure.
Market Drivers:
Rising Demand for Convenience and Speed:
The hyperlocal grocery delivery market is experiencing significant growth due to the increasing consumer demand for convenience and speed in grocery shopping. For instance, in 2023, 62% of consumers who have bought groceries online intend to continue post-pandemic, highlighting the shift towards online platforms for their grocery needs. This trend is driven by the convenience of same-day delivery and real-time tracking, which has become a standard expectation among urban consumers. The integration of AI and machine learning technologies by companies like Instacart has enabled predictive analytics, automated test generation, and faster bug detection, enhancing testing efficiency and accuracy. For example, IBM reported that its AI-powered testing solutions reduce testing time by up to 40%, allowing businesses to accelerate product launches.
Technological Advancements and Digital Transformation:
Technological advancements and the rapid pace of digital transformation across industries are key drivers for the hyperlocal grocery delivery market. For instance, the global spending on digital transformation is predicted to reach $2.3 trillion by 2023, highlighting the need for robust software applications that require specialized testing services to ensure quality and compliance. The adoption of AI and automation in testing processes has revolutionized outsourced testing services, with AI-driven tools enabling predictive analytics, automated test generation, and faster bug detection. For example, IBM's AI-powered testing solutions reduce testing time by up to 40%, allowing businesses to accelerate product launches. Automation frameworks, such as Selenium and Appium, are becoming standard in outsourced testing, ensuring consistent performance and scalability across diverse industries.
Strategic Partnerships and Supply Chain Optimization:
Strategic partnerships between retailers and delivery platforms have played a crucial role in ensuring seamless supply chain operations, thereby driving the growth of the hyperlocal grocery delivery market. For instance, a survey by Deloitte found that 59% of businesses outsource to reduce operational costs and focus on core activities. By leveraging the expertise of external providers, companies can access advanced testing tools and methodologies without the overhead of maintaining an in-house team. For example, outsourcing partners often have access to cutting-edge solutions like Selenium, TestComplete, and Appium, which would otherwise be prohibitively expensive for individual organizations. This not only reduces costs but also ensures that software testing is conducted with the highest level of expertise, leading to better product quality and faster time-to-market.
Regional Growth and Market Dynamics:
The hyperlocal grocery delivery market is witnessing dynamic growth across different regions, each influenced by unique market dynamics. For instance, North America holds a significant share of the market, driven by high internet penetration, advanced logistics infrastructure, and strong consumer adoption of digital platforms. The Asia-Pacific region, however, is poised to exhibit the fastest growth, fueled by rising smartphone usage, urbanization, and an expanding middle-class population in countries like India and China. Europe also contributes significantly to the market, supported by strong e-commerce adoption and the presence of major delivery platforms. Collectively, these regional trends underscore the global appeal and growth potential of the hyperlocal grocery delivery market.
Market Trends:
Integration of Advanced Technologies:
The Hyperlocal Grocery Delivery Market is witnessing a significant trend towards the integration of advanced technologies to enhance service efficiency and customer satisfaction. For instance, Instacart has leveraged AI to improve its delivery processes, reducing testing time by up to 40% and enabling predictive analytics for better inventory management and route optimization. This technological advancement not only speeds up delivery times but also ensures that customers receive their groceries with minimal errors. The adoption of AI and machine learning by companies like Instacart is setting a new standard in the industry, driving the market's growth by offering a more personalized and efficient shopping experience. For example, IBM reported that its AI-powered testing solutions reduce testing time by up to 40%, allowing businesses to accelerate product launches.
Focus on Sustainability and Local Economies:
Sustainability initiatives are becoming a priority in the Hyperlocal Grocery Delivery Market. Companies are increasingly focusing on eco-friendly practices, such as using electric or bicycle-powered vehicles for deliveries, to reduce their carbon footprint. For instance, DoorDash has introduced sustainable delivery options, aligning with consumer preferences for environmentally responsible services. Additionally, hyperlocal delivery platforms are boosting local economies by sourcing products from nearby suppliers and farms, thereby supporting local businesses and fostering community connections. This trend not only appeals to environmentally conscious consumers but also helps in building a more resilient and self-sufficient local economic ecosystem. For example, a survey by Deloitte found that 59% of businesses outsource to reduce operational costs and focus on core activities, which includes sustainable practices.
Expansion into New Sectors and Rural Areas:
The Hyperlocal Grocery Delivery Market is expanding beyond urban areas into rural regions, tapping into previously underserved markets. This expansion is facilitated by the increasing penetration of high-speed internet and the adoption of digital logistics tools, which enable efficient delivery even in remote areas. The market's growth in rural regions is also supported by government initiatives promoting digital transformation and e-commerce in these areas. For example, the Indian government’s Digital India initiative has spurred a 15% annual growth in the IT services sector, with outsourced testing playing a pivotal role in maintaining application reliability and performance.
Market Challenges Analysis:
Logistics and Operational Challenges:
The Hyperlocal Grocery Delivery Market faces significant logistical and operational challenges that restrict its growth. Managing delivery logistics in urban areas with high traffic congestion, limited parking, and complex delivery routes can be challenging and costly. For instance, a study by the Food Safety and Standards Authority of India (FSSAI) highlighted that last-mile delivery costs are among the highest in the supply chain due to the reliance on manual labor and transportation inefficiencies. Ensuring timely deliveries while navigating these obstacles requires efficient logistics planning and execution. Additionally, maintaining the quality and condition of delivered goods, especially in food delivery services, presents operational challenges. The need for effective inventory management, route optimization, and real-time tracking systems is crucial for addressing these challenges and ensuring smooth operations in the hyperlocal delivery sector.
Regulatory and Compliance Issues:
Regulatory and compliance issues are significant restraints in the Hyperlocal Grocery Delivery Market. Delivery services must adhere to various regulations and standards related to safety, data protection, and environmental impact. For instance, the FSSAI mandates that e-commerce retailers with food products listed on their portals hold an FSSAI food business operators (FBOs) license for their entire supply chain. Compliance with local and national regulations can be complex and costly, particularly for businesses operating in multiple regions. Regulations related to vehicle emissions, labor laws, and data privacy can impact operational efficiency and increase costs. Navigating these regulatory requirements requires careful planning and investment in compliance measures. Ensuring adherence to regulations while maintaining operational efficiency is a key challenge for hyperlocal delivery providers.
High Competition and Market Fragmentation:
The Hyperlocal Grocery Delivery Market is characterized by intense competition and market fragmentation, which poses significant challenges for businesses. For instance, the Indian hyperlocal delivery market is largely unorganized, with a multitude of small-scale players operating in isolation. This fragmentation creates inefficiencies in supply chain processes, from stock mismatches to poor route planning. For example, a delivery network that works efficiently in a metropolitan city like Delhi may face entirely different challenges in a semi-urban area. The lack of standardized operating procedures and centralized management makes it difficult to implement streamlined supply chain processes. Furthermore, the absence of robust data-driven insights often results in inefficiencies, from stock mismatches to poor route planning. To address this, businesses need to build scalable models that can adapt to the unique needs of diverse markets while maintaining consistency in service quality.
Market Opportunities:
The hyperlocal grocery delivery market offers immense growth potential as consumer preferences shift toward convenience and speed in their shopping experiences. The increasing penetration of smartphones and mobile apps has created a seamless platform for grocery retailers to engage with customers and offer personalized solutions. Emerging technologies such as artificial intelligence (AI) and machine learning (ML) enable companies to optimize delivery routes, improve inventory management, and predict customer preferences, enhancing overall efficiency. For instance, AI-driven logistics can reduce delivery times by up to 30%, ensuring a competitive edge for service providers. The integration of digital payment systems and real-time tracking also contributes to a superior user experience, driving customer loyalty and repeat business.
Opportunities are particularly strong in emerging economies, where urbanization and an expanding middle-class population are creating a growing demand for hyperlocal services. In regions like Asia-Pacific, rising disposable incomes and increasing internet penetration are expected to drive market growth. For example, India and China are experiencing a surge in demand for online grocery platforms, supported by government initiatives to promote digital infrastructure. Additionally, partnerships between retailers and delivery platforms can help overcome logistical challenges and expand service coverage to underserved areas. With strategic investments in technology and a focus on consumer-centric solutions, companies have the potential to capitalize on this growing demand and secure a strong position in the hyperlocal grocery delivery market globally.
Market Segmentation Analysis:
By Food Type:
This segment includes fresh produce, dairy and eggs, meat and seafood, packaged foods, and beverages. Fresh produce holds a significant share due to the increasing demand for fresh fruits and vegetables delivered quickly to consumers' doorsteps. Dairy and eggs are also in high demand, driven by the need for daily essentials. Meat and seafood, packaged foods, and beverages follow, catering to diverse consumer preferences and dietary needs.
By Business Model:
The market is divided into store-based and warehouse-based models. The store-based model dominates the market, as it allows for quicker delivery times by leveraging existing retail infrastructure. This model is particularly popular in urban areas where consumers expects rapid delivery. The warehouse-based model, while less prevalent, is gaining traction due to its ability to manage inventory more efficiently and offer a wider range of products. This model is particularly beneficial for large-scale operations and regions with lower population density.
By Purchaser Type:
This segment includes individual consumers and business customers. Individual consumers represent the largest segment, driven by the convenience and time-saving benefits of hyperlocal grocery delivery services. The increasing adoption of online grocery shopping among busy urban dwellers and the elderly population further fuels this segment's growth. Business customers, including restaurants, cafes, and small retailers, also contribute to the market, seeking reliable and timely delivery of fresh ingredients and other grocery items to support their operations.
Segmentations:
By Food Type:
- Fresh Food
- Delicatesses & Ready Meal
- Butchery & Poultry
- Bakery & Pastry, Fruits & Vegetable,
- Fishery, Dairy & Eggs
- Groceries
- Organic & Free-From
- Beverages, Food Cupboard
By Business Model:
- Single Store Model,
- Store Pick Model,
- Hybrid Model,
- Aggregator Model
By Purchaser Type:
- One Time Purchase
- Subscription
By Delivery Type:
- Click-to-click Collect
- Home Delivery
By End User:
- Individual
- Distributor – Large Enterprises and SME
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the hyperlocal grocery delivery market, accounting for 35% of global revenue. This dominance is driven by the region’s advanced logistics infrastructure, widespread internet penetration, and strong consumer preference for convenience. For instance, the United States leads the region, where over 60% of households use online grocery delivery services at least once a month, according to a Nielsen report. The presence of major players like Instacart and Amazon Fresh further strengthens the region’s market leadership, supported by innovative delivery models and seamless user experiences. For example, IBM's AI-powered testing solutions reduce testing time by up to 40%, allowing businesses to accelerate product launches.
Europe
Europe contributes 25% of the market share, driven by high adoption of e-commerce platforms and growing urbanization. Countries like the UK, Germany, and France lead in adoption rates due to their established online retail ecosystems and a strong focus on sustainability in delivery operations. For instance, the European Union’s emphasis on reducing carbon footprints has encouraged the use of electric delivery vehicles, with 30% of grocery deliveries now utilizing eco-friendly logistics solutions. Additionally, grocery chains are collaborating with hyperlocal delivery platforms to expand their reach, ensuring faster services in densely populated areas. For example, DoorDash has introduced sustainable delivery options, aligning with consumer preferences for environmentally responsible services.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market, capturing 30% of the global share, fueled by rapid urbanization, increasing smartphone penetration, and a growing middle-class population. India and China are the primary growth drivers, with mobile-first consumers driving demand for hyperlocal grocery apps. For instance, India’s Digital India initiative and China’s extensive mobile payment ecosystem have enabled millions to access online delivery services seamlessly. Leading platforms such as BigBasket and Meituan are leveraging AI-driven logistics to improve efficiency, ensuring deliveries within hours. For example, IBM reported that its AI-powered testing solutions reduce testing time by up to 40%, allowing businesses to accelerate product launches.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively account for the 10% market share, reflecting steady growth supported by improving digital infrastructure. Brazil and the UAE stand out as key markets, driven by increasing adoption of e-commerce and investments in logistics networks. For instance, Brazil’s online grocery sales grew by 25% year-on-year, while UAE-based platforms are incorporating AI to optimize last-mile delivery. These regions present untapped potential, particularly in underserved rural areas where the expansion of digital ecosystems can drive further growth.
Key Player Analysis:
- Instacart
- Amazon Fresh
- Walmart Grocery
- BigBasket
- Ocado Group
- Meituan
- Zomato Grocery
- Blinkit (formerly Grofers)
- Delivery Hero
- FreshDirect
Competitive Analysis:
The hyperlocal grocery delivery market is highly competitive, with established players and emerging platforms vying for market dominance. Major players like Instacart, Amazon Fresh, and Walmart Grocery leverage their extensive logistics networks and advanced technologies to provide fast and reliable delivery services. For instance, Instacart processes over 600,000 orders daily across North America, showcasing its operational scale. In the Asia-Pacific region, platforms like BigBasket and Meituan dominate, driven by their robust local presence and AI-powered delivery optimization. For example, IBM's AI-powered testing solutions reduce testing time by up to 40%, allowing businesses to accelerate product launches. New entrants and regional players, such as Blinkit and FreshDirect, are gaining traction by focusing on ultra-fast delivery, often completing orders within 15-30 minutes. For instance, DoorDash has introduced sustainable delivery options, aligning with consumer preferences for environmentally responsible services. Competitive pricing strategies and targeted partnerships with local retailers have further strengthened their market positioning. However, challenges such as high operational costs and increasing demand for sustainable delivery practices are prompting companies to innovate continuously. For example, a survey by Deloitte found that 59% of businesses outsource to reduce operational costs and focus on core activities. Overall, the market remains dynamic, with technology and customer-centric strategies shaping the competitive landscape.
Recent Developments:
- In August 2024 Instacart's Chief Product Officer, Daniel Danker, discussed the future of grocery shopping, emphasizing AI-driven personalization and the integration of grocery with restaurant delivery through a partnership with Uber Eats
- In September 2024 Amazon introduced a new value-focused private label line called Amazon Saver and expanded Prime savings to over 3,000 grocery items sold in-store and online at Amazon Fresh.
- In January 2025 BigBasket Now, a Tata enterprise, expanded its offerings to include electronics, lifestyle products, and home essentials, aiming to cater to the dynamic needs of Indian households.
- In November 2024: Ocado Retail launched a new feature in Phoenix allowing Prime members to shop for grocery items alongside Amazon.com products with combined delivery.
Market Concentration & Characteristics:
The hyperlocal grocery delivery market is moderately concentrated, with a mix of global giants and regional players competing for market share. Key players like Instacart, Amazon Fresh, and Walmart Grocery dominate in developed regions due to their advanced logistics, widespread reach, and robust technological capabilities. In emerging markets, platforms like BigBasket, Meituan, and Blinkit lead the competition by leveraging localized strategies, such as partnerships with local vendors and ultra-fast delivery services. The market is characterized by rapid technological adoption, including AI-driven logistics, real-time tracking, and voice-enabled ordering systems, enhancing customer experiences. Additionally, the growing consumer preference for convenience and speed has driven innovation, with companies introducing delivery models that fulfill orders in under 30 minutes. While global players benefit from scale and infrastructure, regional competitors gain traction by offering hyperlocal solutions tailored to specific consumer needs, creating a dynamic and competitive market landscape.
Report Coverage:
The research report offers an in-depth analysis based on Food Type, Business Model, Purchaser Type, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The adoption of AI and machine learning in logistics will optimize delivery routes, reduce operational costs, and enhance delivery speed.
- Consumer demand for ultra-fast delivery will drive innovations in supply chain management, with companies focusing on 10- to 30-minute delivery models.
- Increasing smartphone penetration and internet accessibility in emerging markets will expand the customer base for hyperlocal grocery delivery platforms.
- Partnerships between delivery platforms and local retailers will strengthen supply chains and enhance the availability of diverse product offerings.
- Sustainable practices, such as electric vehicles and eco-friendly packaging, will gain prominence as companies strive to meet environmental goals.
- Digital payment integration and real-time tracking features will further enhance user experience and promote customer loyalty.
- Regional players will expand their market presence by leveraging localized strategies and tailored delivery solutions.
- The rise of smart home devices and voice-enabled technology will facilitate seamless grocery ordering and delivery for tech-savvy consumers.
- Governments' digitalization initiatives in developing countries will foster infrastructure development, benefiting the growth of hyperlocal services.
- Advanced data analytics will enable predictive inventory management, ensuring consistent product availability and reducing wastage in delivery operations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Convenience and Speed
Urban consumers increasingly expect groceries to be delivered within hours, driving adoption of hyperlocal delivery platforms that offer rapid, same-day service and real-time tracking.
Technological Advancements in Logistics
The integration of AI, machine learning, and real-time tracking has optimized delivery routes, improved inventory management, and enhanced the overall efficiency and reliability of hyperlocal grocery delivery.
Expansion of E-commerce and Smartphone Penetration
Widespread use of smartphones and high-speed internet has made online grocery shopping more accessible, especially in emerging markets, fueling the growth of hyperlocal delivery services.
Strategic Partnerships and Supply Chain Optimization
Retailers and delivery platforms are forming alliances to streamline supply chains, reduce operational costs, and expand service coverage, enabling faster and more reliable deliveries.
Shift in Consumer Behavior Post-Pandemic
The COVID-19 pandemic accelerated the adoption of online grocery shopping, making it a habitual choice for many consumers and boosting the long-term growth trajectory of hyperlocal delivery services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hyperlocal Grocery Delivery Market?
What factors are driving the growth of the Hyperlocal Grocery Delivery Market?
What are some challenges faced by the Hyperlocal Grocery Delivery Market?
Who are the major players in the Hyperlocal Grocery Delivery Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Food Type
- 1.2.1 Fresh Food (Bakery & Pastry, Fruits & Vegetables, Dairy & Eggs, Butchery & Poultry, Fishery)
- 1.2.2 Delicatessen & Ready Meal
- 1.2.3 Groceries (Organic & Free-From, Food Cupboard)
- 1.2.4 Beverages
- 1.3 By Delivery Type
- 1.3.1 Click-to-Click Collect
- 1.3.2 Home Delivery
- 1.4 By Business Model
- 1.4.1 Single Store Model
- 1.4.2 Store Pick Model
- 1.4.3 Hybrid Model
- 1.4.4 Aggregator Model
- 1.5 By Purchaser Type
- 1.5.1 One Time Purchase
- 1.5.2 Subscription
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 38,512 million → 2032: USD 72,882.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hyperlocal Grocery Delivery Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hyperlocal Grocery Delivery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hyperlocal Grocery Delivery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hyperlocal Grocery Delivery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hyperlocal Grocery Delivery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hyperlocal Grocery Delivery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hyperlocal Grocery Delivery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hyperlocal Grocery Delivery Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 38,512 million → 2032: USD 72,882.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hyperlocal Grocery Delivery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Food Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fresh Food (Bakery & Pastry, Fruits & Vegetables, Dairy & Eggs, Butchery & Poultry, Fishery)
- 12.3.7.2 Delicatessen & Ready Meal
- 12.3.7.3 Groceries (Organic & Free-From, Food Cupboard)
- 12.3.7.4 Beverages
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Delivery Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Click-to-Click Collect
- 12.4.7.2 Home Delivery
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Business Model - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single Store Model
- 12.5.7.2 Store Pick Model
- 12.5.7.3 Hybrid Model
- 12.5.7.4 Aggregator Model
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Purchaser Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 One Time Purchase
- 12.6.7.2 Subscription
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hyperlocal Grocery Delivery Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hyperlocal Grocery Delivery Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hyperlocal Grocery Delivery Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Instacart
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Amazon Fresh
- 17.4 Walmart Grocery
- 17.5 BigBasket
- 17.6 Ocado Group
- 17.7 Meituan
- 17.8 Zomato Grocery
- 17.9 Blinkit (formerly Grofers)
- 17.10 Delivery Hero
- 17.11 FreshDirect
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

