
In-display Fingerprint Sensors Market Overview:
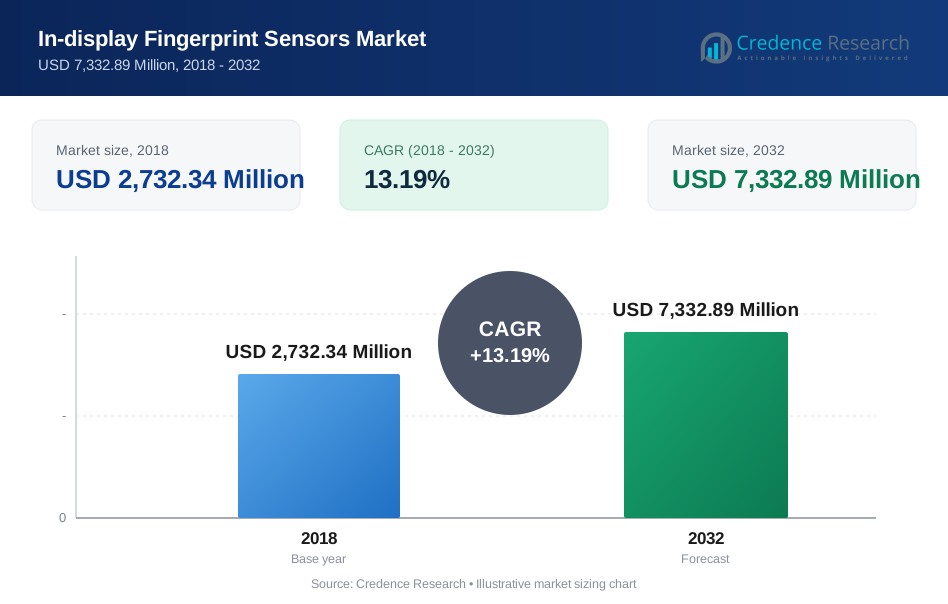
In-display Fingerprint Sensors Market size was valued at USD 1,800.00 Million in 2018 and increased to USD 2,732.34 Million in 2024, and it is anticipated to reach USD 7,332.89 Million by 2032, growing at a CAGR of 13.19% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| In-display Fingerprint Sensors Market Size 2024 | USD 2,732.34 million |
| In-display Fingerprint Sensors Market, CAGR | 13.19% |
| In-display Fingerprint Sensors Market Size 2032 | USD 7,332.89 million |
In-display Fingerprint Sensors Market Insights
- Market overview highlights strong growth driven by rising biometric integration across smartphones, tablets, laptops, and wearables, with the Smartphones segment holding a 72.3% share in 2024 supported by bezel-less design trends and secure authentication demand.
- Market drivers include technological advancement in optical and ultrasonic sensors, enhanced security accuracy, AI-enabled image processing, and rapid adoption across premium and mid-range consumer electronics globally.
- Competition analysis reflects innovation-focused strategies by major players emphasizing sensor reliability, power efficiency, and partnerships with smartphone OEMs to expand deployment across emerging device categories and digital identity ecosystems.
- Regional analysis shows Asia Pacific leading with a 46.38% share in 2024, followed by North America at 23.86% and Europe at 18.38%, while Latin America, Middle East, and Africa exhibit steady growth supported by expanding digital services and increasing biometric-enabled device penetration.

In-display Fingerprint Sensors Market Segmentation Analysis:
By Sensor Type
The In-display Fingerprint Sensors Market by sensor type is led by the Optical segment, which accounted for 48.6% market share in 2024, driven by its lower manufacturing cost, ease of integration in OLED screens, and strong adoption in mid-range and flagship smartphones. Ultrasonic sensors continue to gain traction due to superior accuracy, higher security, and better performance in wet or dirty conditions, supporting premium device adoption. The capacitive segment maintains relevance in select devices requiring faster authentication response, but market momentum remains concentrated toward optical-based innovations and broader OEM deployment.
- For instance, Vivo T4 Ultra employs optical sensing under its 6.67-inch 120Hz AMOLED screen, paired with Dimensity 9300 Plus for reliable performance in flagship devices.
By Application
The market by application is dominated by the Smartphones segment, holding a 72.3% market share in 2024, supported by large-scale consumer electronics production, growing demand for bezel-less displays, and continuous smartphone upgrades in Asia Pacific and North America. Tablets and laptops collectively expand adoption in productivity and enterprise devices, where enhanced biometric security is gaining importance. Wearables and other connected devices represent an emerging growth cluster as OEMs integrate miniature biometric modules to enhance authentication, personalization, and device-level security features in IoT ecosystems and next-generation smart consumer platforms.
- For instance, Goodix Technology supplies capacitive and optical in-display fingerprint sensors to major Android smartphone makers, boosting adoption in Asia-Pacific via seamless under-screen integration.
By End-User
By end-user, the Consumer Electronics segment led the market with a 65.4% market share in 2024, driven by increasing integration of biometric authentication in smartphones, tablets, laptops, and wearable devices. The automotive segment is steadily growing as in-display fingerprint sensors enhance secure vehicle access, driver authentication, and infotainment system protection. Healthcare adoption rises with biometric-enabled medical devices and secure patient identity management systems. Other end-users, including industrial and enterprise electronics, expand demand as organizations prioritize embedded biometric security to support device access control and digital ecosystem protection in connected environments.
Key Growth Drivers
Rising Adoption of Biometric Authentication in Consumer Electronics
The In-display Fingerprint Sensors Market is experiencing strong growth due to the widespread integration of biometric authentication across smartphones, tablets, laptops, and wearables. Consumer preference for secure, contactless, and seamless unlocking features continues to increase, especially as device manufacturers prioritize enhanced user experience and fast authentication speed. The shift toward bezel-less and full-screen display designs has further accelerated the replacement of conventional fingerprint modules with in-display technologies. Continuous innovation in screen materials, compact sensor architecture, and OEM partnerships strengthens deployment across mid-range and premium devices, supporting sustained demand and market expansion.
- For instance, Vivo pioneered mass-produced in-display fingerprint sensors with the X20 Plus UD in 2018, using Synaptics' Clear ID FS9500 optical technology for one-touch unlocking through OLED displays.
Technological Advancements in Optical and Ultrasonic Sensor Architecture
Advancements in optical and ultrasonic fingerprint sensor technology are driving market growth by improving accuracy, security precision, and environmental adaptability. Ultrasonic sensors enable deeper fingerprint mapping and reliable performance in wet or low-light conditions, making them increasingly suitable for premium and rugged devices. Simultaneously, optical sensors benefit from cost-efficient manufacturing, thinner integration profiles, and improved imaging algorithms. Ongoing R&D investment, AI-based image processing, and hardware-software fusion enhance authentication speed and spoof-resistance levels. These innovations enable OEMs to scale adoption across broader device categories while reducing energy consumption and improving durability.
- For instance, Goodix's ultrasonic solution in the vivo X100 Ultra features a high signal-to-noise ratio for clearer images and fast recognition with wet or oily fingers, using low-voltage driving to cut power consumption.
Growing Demand for Contactless and Secure Digital Identity Ecosystems
Expanding digital ecosystems across mobile payments, e-commerce authentication, financial services, and access-controlled applications are significantly boosting the adoption of in-display fingerprint sensors. Users increasingly expect secure identity verification embedded directly into personal devices to safeguard sensitive transactions and data privacy. The technology supports multi-factor authentication frameworks and enhances trust in digital platforms, especially in high-growth regions with rising mobile penetration. Government initiatives promoting secure digital services and enterprise-level identity frameworks further stimulate integration across connected devices, reinforcing the market’s role in scalable, user-centric biometric security infrastructure.

Key Trends & Opportunities
Expansion into Automotive, Healthcare, and IoT-Enabled Devices
A major market opportunity emerges from the integration of in-display fingerprint sensors beyond consumer electronics and into automotive, healthcare, and IoT ecosystems. In vehicles, the technology supports secure driver authentication, personalized cockpit settings, and protected infotainment access. Healthcare devices increasingly adopt biometric verification to strengthen patient identity security and prevent unauthorized device access. Meanwhile, IoT-enabled smart devices and wearables are evolving toward embedded biometric layers to support secure connectivity and digital identity continuity. This cross-industry adoption trend creates new revenue streams and accelerates innovation in compact, power-efficient sensor modules.
- For instance, Hyundai Motor introduced biometric fingerprint authentication in its Santa Fe SUV, enabling encrypted driver verification and automatic adjustment of seat and infotainment preferences.
Transition Toward Multi-Modal Biometric Authentication Platforms
The market is witnessing a strategic shift toward multi-modal biometric authentication systems that combine in-display fingerprint sensors with facial recognition, iris scanning, or behavioral biometrics. This trend enhances security redundancy, improves spoof-resilience, and supports frictionless user authentication across premium devices and enterprise-grade applications. Advancements in AI-powered fusion algorithms enable synchronized identity verification while maintaining real-time performance and user convenience. Device manufacturers are leveraging this opportunity to differentiate product offerings, deliver enhanced digital trust frameworks, and align with security-driven consumer and enterprise adoption requirements across global markets.
- For instance, Fujitsu developed AI-enhanced multimodal authentication combining facial recognition with palm vein scanning, attaining over 99% accuracy even for masked users via data-augmented deep learning.
Key Challenges
High Integration Cost and Manufacturing Complexity
One of the key challenges in the In-display Fingerprint Sensors Market is the high cost of integration and complex manufacturing requirements, particularly for advanced ultrasonic and thin-film optical architectures. Sensor alignment, display compatibility, and calibration precision increase production time and yield risk, especially in flexible and foldable screen devices. These factors affect affordability in entry-level and budget electronics, limiting adoption primarily to mid-range and premium segments. Additionally, supply-chain dependencies on specialized materials and semiconductor components create cost volatility, compelling manufacturers to balance performance innovation with cost-optimized production strategies.
Performance Limitations and Security Vulnerability Concerns
Market growth is challenged by performance constraints related to environmental conditions, screen thickness variations, and fingerprint surface inconsistencies, which may impact accuracy and user confidence in some devices. Concerns regarding spoofing attempts, residual optical glare, or latency during authentication drive ongoing scrutiny of reliability and security standards. Competitive pressure from alternative technologies such as side-mounted or under-button fingerprint modules and advanced facial recognition systems intensifies adoption barriers in specific device categories. Addressing these challenges requires continuous algorithm refinement, material optimization, and compliance with evolving biometric security regulations and certification frameworks.
Regional Analysis
North America
North America represents a strong growth hub in the In-display Fingerprint Sensors Market and accounted for a 23.86% market share in 2024, with the market rising from USD 437.40 Million in 2018 to USD 651.92 Million in 2024, and projected to reach USD 1,745.97 Million by 2032 at a CAGR of 13.2%. Growth is driven by high smartphone penetration, rapid adoption of biometric security, and strong demand across premium consumer electronics. Increasing integration of in-display authentication in laptops and wearables, along with OEM innovation and digital identity adoption, continues to expand the regional revenue base.
Europe
Europe held an 18.38% market share in 2024, with market revenue increasing from USD 349.20 Million in 2018 to USD 502.13 Million in 2024, and expected to reach USD 1,244.78 Million by 2032 at a CAGR of 12.1%. The region benefits from strong consumer adoption of secure mobile authentication, increasing deployment in enterprise mobility devices, and regulatory focus on secure digital identity frameworks. Demand is further supported by premium smartphone sales, growing use of biometric verification in financial and online services, and technology upgrades across Western and Central Europe driving sustained market expansion.
Asia Pacific
Asia Pacific dominated the global market with a 46.38% market share in 2024, rising from USD 815.40 Million in 2018 to USD 1,267.38 Million in 2024, and projected to reach USD 3,595.32 Million by 2032 at a CAGR of 14.0%. The region’s leadership is driven by large-scale smartphone manufacturing, rapid consumer electronics adoption, and strong growth in China, India, South Korea, and Southeast Asia. Expanding production capacity, cost-efficient component sourcing, and increasing integration of biometric authentication in mass-market and premium devices significantly enhance regional demand and reinforce Asia Pacific’s dominant market position.
Latin America
Latin America accounted for a 6.04% market share in 2024, with revenue increasing from USD 109.80 Million in 2018 to USD 165.01 Million in 2024, and forecast to reach USD 409.69 Million by 2032 at a CAGR of 12.1%. Market growth is supported by rising smartphone replacement cycles, expanding mid-range device adoption, and increasing integration of biometric authentication in consumer electronics. Government digitization programs, financial sector security upgrades, and growing demand for secure mobile transactions strengthen adoption, particularly in Brazil, Mexico, and emerging digital economies across the region.
Middle East
The Middle East recorded a 2.86% market share in 2024, with market value increasing from USD 55.80 Million in 2018 to USD 78.13 Million in 2024, and expected to reach USD 184.10 Million by 2032 at a CAGR of 11.4%. Growth is driven by increasing deployment of biometric authentication in premium smartphones, secure enterprise devices, and smart mobility ecosystems. Rising investments in digital security infrastructure, fintech expansion, and smart city initiatives across GCC economies are accelerating demand for in-display authentication technologies and strengthening adoption across consumer and professional applications.
Africa
Africa held a 2.48% market share in 2024, with revenue rising from USD 32.40 Million in 2018 to USD 67.77 Million in 2024, and projected to reach USD 153.03 Million by 2032 at a CAGR of 10.2%. Market expansion is supported by increasing availability of affordable smartphones, gradual shift toward biometric-enabled devices, and growing digital services adoption across urban markets. Telecom growth, mobile-based financial applications, and rising consumer awareness of device security contribute to a steady increase in demand, while technology penetration continues to expand across key African economies.

In-display Fingerprint Sensors Market Segmentations:
By Sensor Type
- Optical
- Ultrasonic
- Capacitive
By Application
- Smartphones
- Tablets
- Laptops
- Wearables
- Others
By End-User
- Consumer Electronics
- Automotive
- Healthcare
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the In-display Fingerprint Sensors Market is shaped by leading players such as Samsung Electronics Co., Ltd., Apple Inc., Synaptics Incorporated, Goodix Technology Inc., Qualcomm Technologies, Inc., Fingerprint Cards AB, Egis Technology Inc., Vivo Communication Technology Co. Ltd., Huawei Technologies Co., Ltd., and Xiaomi Corporation. The market reflects intense innovation-driven rivalry as companies focus on sensor accuracy, power efficiency, durability, and seamless integration with AMOLED and flexible displays. Partnerships between semiconductor suppliers, smartphone OEMs, and display manufacturers strengthen product pipelines and accelerate commercialization of next-generation optical and ultrasonic technologies. Vendors increasingly differentiate through AI-based image processing, enhanced spoof-resistance, and multi-modal authentication support to meet security-centric consumer and enterprise requirements. Pricing strategies, economies of scale, and localization of manufacturing in Asia Pacific significantly influence competition dynamics, while sustained R&D investments and patent development remain critical for technology leadership, premium device penetration, and expansion across emerging device categories and digital identity ecosystems.
Key Player Analysis
- Samsung Electronics Co., Ltd.
- Apple Inc.
- Synaptics Incorporated
- Goodix Technology Inc.
- Qualcomm Technologies, Inc.
- Fingerprint Cards AB
- Egis Technology Inc.
- Vivo Communication Technology Co. Ltd.
- Huawei Technologies Co., Ltd.
- Xiaomi Corporation
- OPPO Electronics Corp.
- LG Electronics Inc.
- Sony Corporation
- IDEX Biometrics ASA
- CrucialTec Co., Ltd.
- MStar Semiconductor, Inc.
Recent Developments
- In November 2025, Synaptics and Qualcomm Technologies announced a strategic engagement to advance touch and fingerprint sensor technology across PC and mobile platforms, combining Synaptics’ touch controllers with Qualcomm’s ultrasonic 3D Sonic sensor technologies.
- In June 2024, Egis Technology entered into an exclusive partnership with Fingerprint Cards AB to integrate Fingerprints’ mobile product lines, patent and technology licensing into Egis’ offerings, strengthening mobile biometric solutions.
- In May 2024, Goodix Technology announced that its proprietary ultrasonic fingerprint solution debuted in the newly launched vivo X100 Ultra smartphone, providing seamless and secure unlocking performance on flagship devices.
Report Coverage
The research report offers an in-depth analysis based on Sensor Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as OEMs continue integrating in-display fingerprint authentication across smartphones, tablets, laptops, and wearables to enhance user security and design flexibility.
- Technology innovation will advance optical and ultrasonic sensor performance, improving accuracy, speed, and reliability across diverse environmental and usage conditions.
- Multi-modal biometric ecosystems will gain traction as in-display fingerprint sensors operate alongside facial recognition and behavioral analytics to strengthen digital identity protection.
- Premium and mid-range consumer electronics will remain the primary growth drivers as manufacturers prioritize seamless screen-embedded authentication experiences.
- Automotive and healthcare applications will emerge as strategic adoption areas, supporting secure access control, personalization, and device authentication functions.
- Manufacturing optimization and supply-chain localization will reduce production complexity and support wider sensor integration across cost-sensitive markets.
- AI-enabled image processing and algorithm refinement will enhance spoof-resistance and elevate biometric security standards globally.
- Growing demand for secure mobile transactions and fintech authentication will reinforce the role of in-display fingerprint technology in digital ecosystems.
- Rising penetration of IoT-connected devices will create opportunities for compact, low-power in-display biometric modules across smart environments.
- Continued R&D investment and strategic industry partnerships will accelerate innovation cycles and expand commercialization of next-generation in-display fingerprint solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the In-display Fingerprint Sensors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the In-display Fingerprint Sensors Market projected to grow between 2024 and 2032?
Which In-display Fingerprint Sensors Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the In-display Fingerprint Sensors Market?
Who are the leading companies in the In-display Fingerprint Sensors Market?
Which region commanded the largest share of the In-display Fingerprint Sensors Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 In-display Fingerprint Sensors Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global In-display Fingerprint Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 2,732.34 Million → 2032: USD 7,332.89 Million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 In-display Fingerprint Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. In-display Fingerprint Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 In-display Fingerprint Sensors Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 In-display Fingerprint Sensors Market Drivers
- 3.3 In-display Fingerprint Sensors Market Restraints & Challenges
- 3.4 In-display Fingerprint Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 In-display Fingerprint Sensors Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 In-display Fingerprint Sensors Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, In-display Fingerprint Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 In-display Fingerprint Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. In-display Fingerprint Sensors Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to In-display Fingerprint Sensors. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 In-display Fingerprint Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 In-display Fingerprint Sensors Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 In-display Fingerprint Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in In-display Fingerprint Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in In-display Fingerprint Sensors
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global In-display Fingerprint Sensors Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America In-display Fingerprint Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe In-display Fingerprint Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific In-display Fingerprint Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America In-display Fingerprint Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East In-display Fingerprint Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa In-display Fingerprint Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. In-display Fingerprint Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
