
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
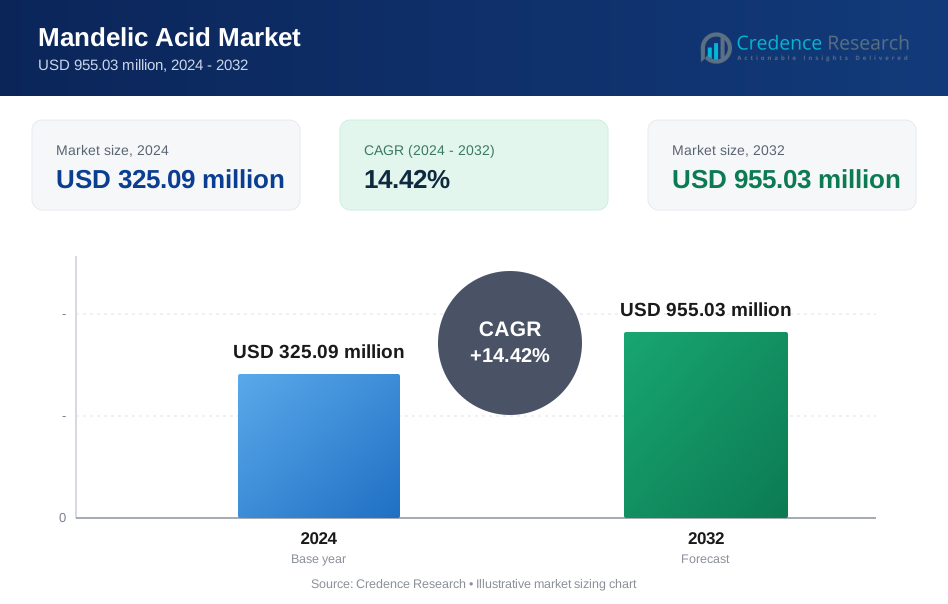
| Mandelic Acid market Size 2024 | USD 325.09 million |
| Mandelic Acid market, CAGR | 14.42% |
| Mandelic Acid market Size 2032 | USD 955.03 million |
Market Overview:
The global Mandelic Acid market is projected to grow significantly, expanding from USD 325.09 million in 2024 to USD 955.03 million by 2032, with a compound annual growth rate (CAGR) of 14.42% over the forecast period. This robust growth is driven by the increasing demand for mandelic acid in the cosmetics and pharmaceutical industries. Mandelic acid, an alpha hydroxy acid (AHA), is highly valued for its exfoliating properties and its ability to treat various skin conditions, such as acne and hyperpigmentation, without causing significant irritation. The rise in consumer awareness regarding skincare, coupled with the growing preference for high-quality, effective ingredients in cosmetic products, is fuelling the demand for mandelic acid. Additionally, the acid's antimicrobial properties make it a crucial ingredient in pharmaceuticals, further driving market expansion.
Several factors are driving the growth of the mandelic acid market. The cosmetics industry's shift towards gentler, yet effective, skincare solutions is a primary driver, as mandelic acid is often favoured over other AHAs for its milder nature and suitability for sensitive skin. The increasing prevalence of skin disorders, particularly in urban areas with high pollution levels, is also contributing to the growing use of mandelic acid in skincare formulations. Moreover, the expansion of the pharmaceutical industry, particularly in developing regions, is boosting the demand for mandelic acid as an active ingredient in various therapeutic products.
Regionally, North America is expected to hold a significant share of the mandelic acid market, driven by the high demand for advanced skincare products and the strong presence of major cosmetic brands in the region. The Asia-Pacific region is anticipated to witness the fastest growth, fuelled by rising disposable incomes, increasing consumer awareness about skincare, and the rapid expansion of the cosmetics and pharmaceutical industries in countries like China, South Korea, and Japan. Europe also holds a substantial share, supported by the region’s well-established cosmetics industry and growing interest in organic and natural skincare products.
Market Drivers:
Growing Demand in the Skincare Industry:
The increasing consumer demand for effective skincare products is a primary driver of the mandelic acid market. As consumers become more knowledgeable about skincare, they seek out products that provide tangible benefits without harsh side effects. Mandelic acid, known for its gentle exfoliating properties, is gaining popularity over other alpha hydroxy acids (AHAs) like glycolic acid, particularly among individuals with sensitive skin. For instance, dermatologists are recommending mandelic acid-based products for treating acne and hyperpigmentation due to its ability to exfoliate the skin without causing significant irritation. This shift towards gentler yet effective skincare solutions is significantly boosting the demand for mandelic acid in the cosmetics industry.
Increasing Prevalence of Skin Disorders:
The rising prevalence of skin disorders, particularly in urban areas with high pollution levels, is another key driver of the mandelic acid market. Environmental factors, such as pollution and UV exposure, contribute to various skin issues, including acne, pigmentation, and premature aging. To combat these issues, consumers are increasingly turning to skincare products that contain active ingredients like mandelic acid. For example, studies have shown that mandelic acid effectively reduces acne lesions and improves skin texture, making it a preferred ingredient in acne treatments. As awareness of the link between environmental factors and skin health grows, the demand for mandelic acid in therapeutic skincare products is expected to rise.
Expansion of the Pharmaceutical Industry:
The expansion of the pharmaceutical industry, particularly in developing regions, is driving the demand for mandelic acid as a key ingredient in various therapeutic products. Mandelic acid’s antimicrobial properties make it valuable in the formulation of treatments for bacterial infections and other skin conditions. For instance, pharmaceutical companies are incorporating mandelic acid into topical antibiotics and treatments for bacterial vaginosis, capitalizing on its effectiveness and low irritation potential. As the pharmaceutical industry continues to grow, particularly in regions like Asia-Pacific, the demand for mandelic acid in medicinal formulations is expected to increase.
Shift Towards Natural and Organic Ingredients:
The global shift towards natural and organic skincare products is also driving the mandelic acid market. Consumers are increasingly seeking out products that are derived from natural sources and are free from synthetic chemicals. Mandelic acid, which is derived from bitter almonds, fits well within this trend. Companies are responding to this demand by formulating skincare products that highlight the natural origins of their ingredients, including mandelic acid. This trend is particularly strong in regions like Europe and North America, where consumers are highly conscious of the ingredients in their skincare products and prefer natural and organic formulations.
Market Trends:
Increasing Popularity of Multi-Functional Skincare Products:
A key trend in the mandelic acid market is the rising demand for multi-functional skincare products. Consumers are increasingly seeking products that offer multiple benefits in a single formulation, such as exfoliation, anti-aging, and brightening effects. For instance, many brands are incorporating mandelic acid into serums and creams that not only exfoliate but also target fine lines and hyperpigmentation. This trend is driven by the convenience factor, as consumers prefer products that simplify their skincare routines while delivering comprehensive results.
Growth of E-Commerce in Skincare:
The growth of e-commerce has significantly influenced the mandelic acid market. With the increasing popularity of online shopping, consumers now have easier access to a wide range of skincare products, including those containing mandelic acid. For example, platforms like Amazon, Sephora, and specialized skincare websites offer a vast selection of mandelic acid-based products, often with detailed customer reviews and ratings. This accessibility has led to greater consumer awareness and adoption of mandelic acid products, particularly in regions where access to specialized skincare products was previously limited.
Rising Trend of Customizable Skincare:
Customizable skincare is an emerging trend that is gaining traction in the mandelic acid market. Consumers are increasingly looking for personalized skincare solutions tailored to their specific skin types and concerns. Companies are responding by offering products that allow consumers to customize the concentration of active ingredients like mandelic acid. For instance, some brands provide options for consumers to adjust the potency of their mandelic acid products based on their skin’s tolerance and needs. This trend towards personalization is enhancing consumer engagement and satisfaction, driving further growth in the market.
Emphasis on Sustainable and Ethical Sourcing:
The emphasis on sustainability and ethical sourcing is another notable trend impacting the mandelic acid market. Consumers are becoming more conscious of the environmental and ethical implications of their skincare choices, leading to a preference for products that are sustainably sourced and cruelty-free. For example, companies are increasingly highlighting the natural origin of mandelic acid, derived from bitter almonds, and ensuring that their sourcing practices are environmentally responsible. This focus on sustainability is resonating with consumers, particularly in regions like Europe and North America, where ethical considerations are becoming a significant factor in purchasing decisions.
Market Challenges Analysis:
High Production Costs and Limited Scalability:
One of the primary restraints in the mandelic acid market is the high production cost associated with its extraction and synthesis. Mandelic acid is typically derived from bitter almonds, and the process of extraction can be expensive, particularly when ensuring the purity and quality required for cosmetic and pharmaceutical applications. Additionally, the synthesis of mandelic acid in laboratories involves complex chemical processes, further driving up production costs. This high cost of production can make mandelic acid-based products less competitive, especially in price-sensitive markets.
Regulatory Hurdles and Compliance Issues:
The mandelic acid market also faces significant regulatory challenges, particularly in the pharmaceutical and cosmetic sectors. Different regions have varying regulations regarding the use of active ingredients in skincare and pharmaceutical products. For instance, the European Union has stringent regulations under its Cosmetics Regulation (EC) No. 1223/2009, which requires rigorous testing and approval processes before products can be marketed. Complying with these regulations can be time-consuming and costly, creating barriers to market entry for smaller companies and limiting the availability of mandelic acid products in certain regions.
Limited Consumer Awareness and Market Penetration:
Despite its benefits, mandelic acid remains relatively less known compared to other alpha hydroxy acids (AHAs) like glycolic acid and lactic acid. Limited consumer awareness poses a challenge to market growth, as many consumers may not be familiar with the specific benefits of mandelic acid or how it differs from other AHAs. This lack of awareness can slow the adoption of mandelic acid-based products, particularly in emerging markets where consumer education on skincare ingredients is still developing.
Competition from Alternative Ingredients:
The mandelic acid market also faces competition from other exfoliating agents and skincare ingredients. Products containing glycolic acid, salicylic acid, and lactic acid are well-established in the market and are often favoured by consumers and dermatologists due to their proven efficacy and widespread availability. This competition from alternative ingredients can limit the market share of mandelic acid, particularly in segments where consumers are looking for cost-effective solutions.
Market Segmentation Analysis:
By Type:
The market is divided into DL Mandelic Acid, L Mandelic Acid, and D Mandelic Acid. Among these, DL Mandelic Acid holds the largest market share, accounting for 50.1% in 2023. This dominance is attributed to its widespread application in pharmaceuticals and skincare products.
By Technology:
The market is segmented based on the technology used in the production and application of mandelic acid. The primary technologies include API synthesis and preservatives. API synthesis is a significant segment due to the increasing demand for mandelic acid in pharmaceutical applications. The preservative segment is also growing, driven by the rising use of mandelic acid in cosmetics and personal care products.
By End User:
The end-user segment includes Pharmaceuticals, Personal Care & Cosmetics, and Others. The Pharmaceuticals segment is the largest, driven by the demand for mandelic acid in API synthesis and as an antimicrobial agent. The Personal Care & Cosmetics segment is also significant, with increasing consumer awareness and expenditure on beauty products. The Others segment includes applications in textiles and dye intermediates, which contribute to the overall market growth.
Segmentations:
By Type
- DL Type
- L Type
- D Type
By Vertical
- Pharmaceutical
- Cosmetics & Personal Care
- Textiles & Dye Intermediates
- Others
By Application
- API Synthesis
- Dye Intermediate
- Others
By Region
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the global mandelic acid market, accounting for approximately 35% of the total market revenue. The region’s dominance is primarily driven by the well-established skincare and pharmaceutical industries in the United States and Canada. In the U.S., the high consumer demand for advanced skincare products, particularly those addressing issues like acne, hyperpigmentation, and anti-aging, has fuelled the growth of the mandelic acid market. The strong presence of major cosmetic brands and extensive R&D activities in the pharmaceutical sector further bolster this market. Additionally, the trend towards natural and organic skincare products, combined with high consumer awareness and spending power, supports the robust demand for mandelic acid in this region.
Europe
Europe represents around 30% of the global mandelic acid market, with countries like Germany, France, and the United Kingdom leading in market share. The European market is characterized by a strong emphasis on sustainability, quality, and natural ingredients, which aligns well with the properties of mandelic acid. The region’s stringent regulations on cosmetic products and the high demand for clean beauty are driving the adoption of mandelic acid in various skincare formulations. Additionally, Europe’s mature pharmaceutical industry, particularly in Germany and Switzerland, contributes to the growing use of mandelic acid in medical applications. The region's consumers are highly knowledgeable about skincare ingredients, which further drives the demand for effective, multi-functional products containing mandelic acid.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market for mandelic acid, holding approximately 25% of the global market share. This growth is fuelled by increasing consumer awareness about skincare and the rising disposable incomes in countries like China, Japan, and South Korea. In these countries, the demand for advanced skincare solutions that address specific concerns such as pigmentation, acne, and aging is on the rise. The popularity of K-beauty and J-beauty trends, which emphasize gentle yet effective skincare routines, is also driving the adoption of mandelic acid in the region. Additionally, the expansion of the pharmaceutical industry in countries like India and China is boosting the demand for mandelic acid in therapeutic applications.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa (MEA) together account for the remaining 10% of the global mandelic acid market. These regions are emerging markets with significant growth potential, driven by increasing urbanization, rising consumer incomes, and growing interest in skincare. In Latin America, Brazil and Mexico are key markets, with a growing demand for effective and affordable skincare solutions. In the MEA region, countries like the UAE and South Africa are seeing increased consumer interest in high-quality skincare products, supported by expanding retail sectors and growing awareness of skincare trends. However, challenges such as economic instability and limited consumer awareness may slow market penetration compared to more developed regions.
Key Player Analysis:
Top Key Players
- Evonik Industries AG
- BASF SE
- Hanhong Scientific
- Merck KGaA
- Alfa Aesar
- Thermo Fisher Scientific Inc.
- CLEARSYNTH
- Biosynth Carbosynth
- Runder Pharmda Technology Co., Ltd.
- BIOTEC
Competitive Analysis:
The mandelic acid market is marked by moderate competition, with several key players driving innovation and market expansion through product development and strategic partnerships. Companies like BASF, Evonik, and Merck KGaA lead the market with their extensive portfolios of high-purity mandelic acid products, catering to both the cosmetics and pharmaceutical industries. These major players leverage advanced research and development capabilities to introduce new formulations that enhance the stability, efficacy, and environmental sustainability of mandelic acid-based products. Additionally, these companies focus on maintaining stringent quality standards and regulatory compliance to meet the growing demand for effective and safe skincare and therapeutic solutions. Emerging players in the market are increasingly focusing on niche segments, such as products for sensitive skin, further intensifying competition and driving innovation in the industry. Overall, the competitive landscape is characterized by continuous innovation, strategic product launches, and a strong emphasis on meeting consumer and regulatory demands.
Recent Developments:
- In 2024 AHA Labs introduced a new line of mandelic acid products designed for sensitive skin. This range is part of their "Sensitive Skin Solutions" portfolio, targeting consumers who seek effective exfoliation without irritation. The company highlighted that these products are formulated with additional soothing agents to enhance user comfort while delivering the benefits of mandelic acid.
- In 2023 BASF launched a new eco-friendly mandelic acid product aimed at the cosmetics industry. This product is sourced from sustainable raw materials and is produced using green chemistry principles. The company emphasized that this launch is in response to the growing demand for environmentally responsible ingredients in skincare products, particularly in the European and North American markets.
- In 2022 Evonik introduced a high-purity mandelic acid specifically designed for advanced dermatological formulations. This product is engineered to offer enhanced stability in complex formulations, making it suitable for both anti-aging and acne treatments. The company reported that this development is part of their broader strategy to expand their presence in the high-performance skincare ingredients market.
- In 2022 Merck KGaA announced the release of a new mandelic acid-based solution for use in pharmaceutical applications. This solution is designed to improve the efficacy of topical treatments for skin conditions such as acne and hyperpigmentation. The company also noted that the product has undergone rigorous testing to ensure its safety and effectiveness in medical-grade formulations.
Market Concentration & Characteristics:
The mandelic acid market exhibits a moderate level of concentration, with a few dominant players such as BASF, Evonik, and Merck KGaA leading the industry through their advanced R&D capabilities and extensive product portfolios. These companies hold a significant share of the market due to their ability to innovate and introduce high-purity, specialized mandelic acid products tailored to both cosmetic and pharmaceutical applications. The market is characterized by continuous technological advancements, particularly in the development of more stable and effective formulations. Additionally, the focus on sustainable and eco-friendly production practices is becoming increasingly prominent as companies respond to consumer demand for environmentally responsible ingredients. Despite the presence of major players, the market also offers opportunities for smaller companies and niche brands to carve out their space by targeting specific consumer needs, such as sensitive skin or organic products.
Report Coverage:
The research report offers an in-depth analysis based on Type, Vertical, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for mandelic acid in skincare will continue to grow, driven by increasing consumer awareness of its gentle exfoliating properties and effectiveness in treating sensitive skin conditions.
- Pharmaceutical applications of mandelic acid are expected to expand, particularly in dermatological treatments for acne and hyperpigmentation.
- The trend towards natural and sustainable ingredients will further boost the use of mandelic acid, given its natural derivation from bitter almonds.
- Technological advancements will lead to more stable and potent formulations, enhancing the efficacy of mandelic acid in both cosmetic and medical products.
- The Asia-Pacific region will see rapid growth in mandelic acid consumption, supported by rising disposable incomes and growing interest in advanced skincare products.
- The expansion of e-commerce platforms will make mandelic acid-based products more accessible to a global consumer base, driving market growth.
- Ongoing research and development will likely result in new applications for mandelic acid in both existing and emerging markets.
- Regulatory approvals and compliance will play a crucial role in determining market penetration, particularly in highly regulated regions like Europe and North America.
- The competitive landscape will intensify as both established players and new entrants innovate to capture market share.
- Collaboration between cosmetic and pharmaceutical companies will likely increase, leading to the development of multifunctional products featuring mandelic acid.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mandelic Acid Market?
What factors are driving the growth of the Mandelic Acid Market?
What are some challenges faced by the Mandelic Acid Market?
Who are the major players in the Mandelic Acid Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mandelic Acid Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mandelic Acid Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 325.09 million → 2032: USD 955.03 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mandelic Acid Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mandelic Acid Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mandelic Acid Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mandelic Acid Market Drivers
- 3.3 Mandelic Acid Market Restraints & Challenges
- 3.4 Mandelic Acid Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mandelic Acid Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mandelic Acid Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mandelic Acid category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mandelic Acid Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mandelic Acid Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mandelic Acid market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mandelic Acid Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mandelic Acid Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mandelic Acid Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mandelic Acid (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mandelic Acid Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mandelic Acid Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mandelic Acid Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mandelic Acid Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mandelic Acid Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mandelic Acid Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mandelic Acid Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mandelic Acid Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mandelic Acid Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
