
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
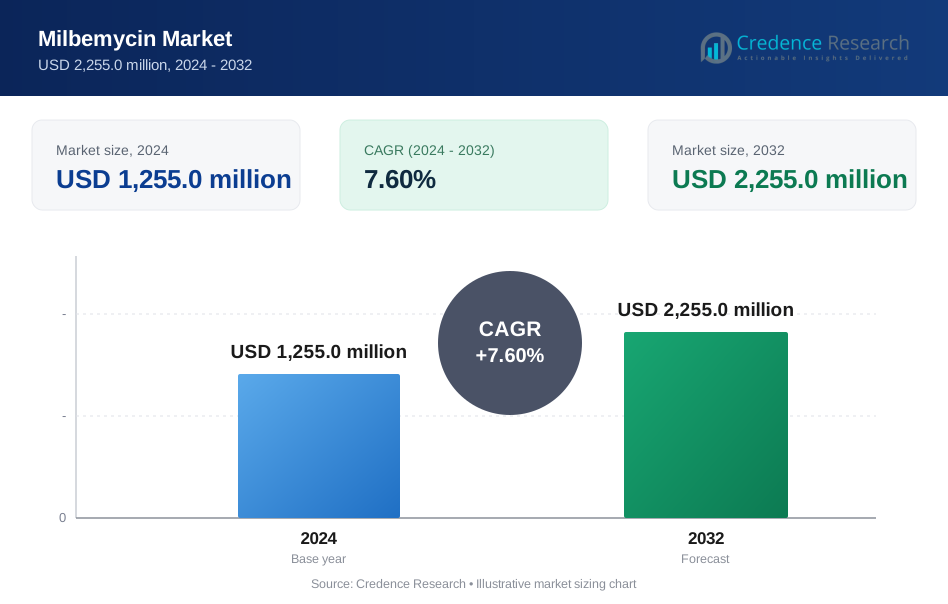
| Milbemycin Market Size 2024 | USD 1,255.0 million |
| Milbemycin Market CAGR | 7.60% |
| Milbemycin Market Size 2032 | USD 2,255.0 million |
Market Overview
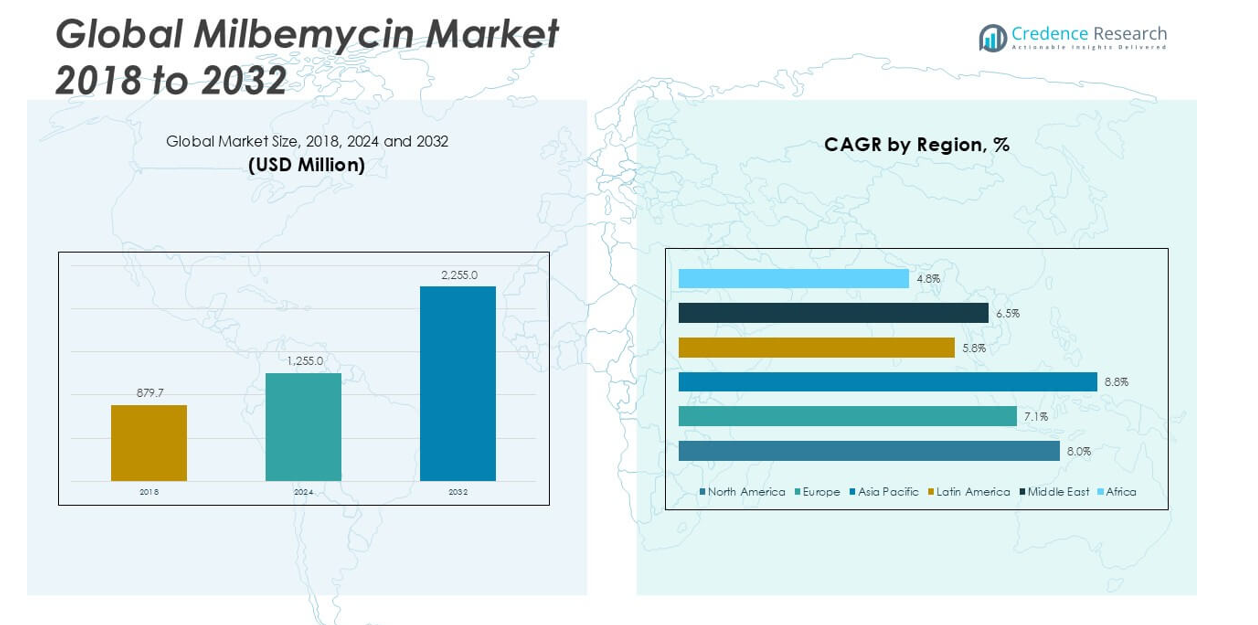
The Milbemycin market size was valued at USD 879.7 million in 2018, reached USD 1,255.0 million in 2024, and is anticipated to reach USD 2,255.0 million by 2032, at a CAGR of 7.60% during the forecast period.
The Milbemycin market features several top players, including Merck & Co. / MSD Animal Health, Elanco Animal Health, Zoetis Inc., Boehringer Ingelheim, and Bayer Animal Health, which collectively command a significant share of the global landscape through innovation, extensive product portfolios, and strong distribution channels. These companies focus on advancing veterinary therapeutics for both companion and livestock animals, enhancing their presence in established and emerging markets. North America leads the market with an exact market share of 34%, supported by advanced animal healthcare infrastructure and rising pet ownership, while Europe and Asia Pacific follow as key regions with 26.5% and 22.7% market shares, respectively.
Market Insights
- The Milbemycin market is projected to grow from USD 1,255.0 million in 2024 to USD 2,255.0 million by 2032, reflecting a CAGR of 7.60% over the forecast period.
- Rising demand for effective parasitic control in both companion and livestock animals continues to drive market growth, with Emulsifiable Concentrate (EC) formulations holding the dominant segment share due to their superior efficacy and convenience.
- Industry trends highlight the growing adoption of combination therapies, advanced formulations, and increased product launches by major players such as Merck & Co., Elanco Animal Health, and Zoetis Inc., enhancing competitiveness and innovation.
- Market expansion faces restraints from stringent regulatory requirements, high development costs, and concerns over parasite resistance and environmental impact, which challenge product approvals and adoption.
- Regionally, North America holds the largest market share at 34%, followed by Europe at 26.5% and Asia Pacific at 22.7%, reflecting strong demand and advanced veterinary healthcare infrastructure.
Market Segmentation Analysis:
By Type
The Emulsifiable Concentrate (EC) segment leads the Milbemycin market by type, capturing the largest market share due to its superior solubility, ease of application, and high efficacy in pest control. EC formulations remain the preferred choice for end-users in agricultural and veterinary sectors, driven by their versatility and rapid action against a wide range of pests and parasites. The demand for user-friendly and easily mixable solutions continues to drive the adoption of EC, while Water Soluble Granules (SG) and Water Dispersible Granules (WG) are gaining traction for their environmental benefits and reduced chemical residue.
- For instance, Zoetis’ Revolution Plus solution delivers 60 mg of Milbemycin oxime per milliliter, ensuring precise and effective dosing for companion animals.
By Application
Pesticides represent the dominant application segment in the Milbemycin market, accounting for the majority of the market share. The strong growth of this segment is fueled by the rising demand for effective pest management solutions in agriculture and livestock industries. The increasing prevalence of parasitic infestations and the need to improve crop and animal health are key drivers for the extensive use of Milbemycin-based pesticides. Chemical additives and other applications contribute a smaller share, mainly serving specialized or niche market requirements.
- For instance, Elanco Animal Health manufactures Interceptor Plus, a chewable tablet for dogs that contains 2.3 mg of Milbemycin oxime per tablet, offering reliable and consistent parasite control.
Market Overview
Rising Pet Ownership & Preventive Animal Healthcare
The global surge in pet ownership, particularly in emerging economies, galvanizes demand for Milbemycin products. As pet owners increasingly embrace preventive care, veterinary treatments like heartworm prevention and parasitic dewormers become staple routines. This shift boosts consumption of Milbemycin-based formulations, especially in the companion animal segment, which leads the veterinary pharmaceuticals market. Manufacturers are responding by launching combination therapies and user-friendly delivery methods, fueling further adoption and driving sustained market growth.
- For instance, Boehringer Ingelheim’s NexGard Spectra contains 2.5 mg of Milbemycin oxime per chew, with over 18 million doses distributed globally in a year.
Innovation in Formulation & Delivery
Technological advancements in Milbemycin formulations act as a potent market accelerant. Industry players are developing improved deliverables sustained-release formulas, novel carriers, and combination products to enhance efficacy, safety, and compliance. Such innovation reduces treatment frequency and expands spectrum of action while addressing resistance management. These improvements align with end-user needs and regulatory emphasis on high-performance veterinary pharmaceuticals, consolidating market share and enabling manufacturers to differentiate in a competitive landscape.
- For instance, Bayer Animal Health’s Milbemax tablets provide 16 mg of Milbemycin oxime per tablet for large dogs and are approved in more than 60 countries.
Expansion in Emerging Markets & Livestock Sector
Growing disposable incomes and evolving agricultural practices in Asia-Pacific and Latin America present significant growth opportunities for Milbemycin in livestock applications. Farmers increasingly adopt veterinary tools to enhance herd health and productivity. The livestock segment is therefore expanding rapidly, supported by infrastructure investments, rising awareness of zoonotic disease control, and government initiatives. As Milbemycin gains prominence in integrated parasite management strategies, its application in livestock is forecast to significantly contribute to future market expansion.
Key Trends & Opportunities
Combination Products & Strategic Innovations
The trend toward combination therapies-incorporating Milbemycin with other antiparasitics-is gaining momentum. These formulations offer broader-spectrum parasite control, improved efficacy, and reduced dosing complexity. Additionally, manufacturers are exploring organic and eco-friendly Milbemycin variations to meet heightened consumer demand for sustainable, low-residue products. Parallel development of digital distribution models, such as tele-veterinary services and e-commerce, are opening new channels for reaching end-users directly, especially in rural and underserved areas.
- For instance, Zoetis distributed more than 25 million doses of Simparica Trio, a combination tablet containing 12 mg of Milbemycin oxime, in a single year.
Veterinary Infrastructure Growth in Developing Regions
Developing countries are witnessing robust expansion in veterinary infrastructure-new clinics, diagnostic labs, and supply chains-driven by rising pet ownership and recognition of animal health economics. This trend propels higher prescription rates for Milbemycin in both companion and production animals. Strategically, global players can form regional partnerships to localize manufacturing and distribution. This will facilitate affordability, regulatory approval, and brand trust, unlocking significant market potential in untapped demographics.
- For instance, Norbrook Laboratories expanded its manufacturing capacity in Africa by establishing a 6,000 square meter veterinary product facility in Nairobi, supporting wider access to Milbemycin-based therapies.
Key Challenges
Regulatory Complexity & Approval Barriers
Stringent and heterogeneous regulatory frameworks represent a major obstacle for Milbemycin manufacturers. Regulatory bodies such as the EPA in the U.S., EMA in Europe, and counterparts in emerging markets mandate comprehensive testing and compliance requirements, extending time-to-market and inflating costs. Company expansion into new geographies requires navigating diverse and evolving regulations. This slows product rollouts, pressures R&D budgets, and complicates competitive positioning in a dynamic, regulated environment.
Parasitic Resistance & Environmental Concerns
The efficacy of antiparasitics like Milbemycin is threatened by increasing parasite resistance due to prolonged use. Resistance reduces therapeutic utility and necessitates dosage adjustments or combination therapies, increasing R&D and regulatory costs. Environmental concerns also challenge market acceptance; users and authorities seek formulations with minimal ecological impact. To sustain market growth, industry must invest in resistance monitoring, responsible use programs, and green chemistry initiatives.
Supply Chain Volatility & Raw Material Costs
Fluctuations in raw material availability and pricing, exacerbated by global supply chain disruptions, pose a tangible risk to Milbemycin manufacturers. The complexity of producing APIs and delivering finished products to rural or remote veterinary outlets can result in stock-outs or increased costs. Companies need robust sourcing strategies, diversified supplier networks, and agile logistics to ensure stable supply. This is especially critical during disease outbreaks, when demand can spike and margins are slim.
Regional Analysis
North America
North America holds a significant position in the Milbemycin market, capturing the largest market share with a value of USD 317.6 million in 2018 and increasing to USD 429.2 million in 2024. The region is projected to reach USD 710.3 million by 2032, registering a CAGR of 8.0% during the forecast period. North America currently accounts for approximately 34% of the global market share. Strong demand for advanced veterinary pharmaceuticals, a well-developed animal healthcare sector, and increasing pet ownership are key factors driving robust market growth in this region.
Europe
Europe stands as the second-largest regional market, with a market size of USD 249.0 million in 2018, rising to USD 332.6 million in 2024 and projected to reach USD 559.2 million by 2032 at a CAGR of 7.1%. Europe currently holds about 26.5% of the global market share. The region’s growth is supported by stringent animal health regulations, growing awareness of parasite management, and a mature livestock industry. These drivers, coupled with ongoing product innovations, position Europe as a core market for Milbemycin-based products.
Asia Pacific
Asia Pacific is witnessing the fastest growth in the Milbemycin market, with a market value of USD 172.4 million in 2018, expanding to USD 284.9 million in 2024 and anticipated to reach USD 617.9 million by 2032 at a CAGR of 8.8%. This region commands around 22.7% of the global market share. Rapid economic development, increasing investments in animal healthcare, and rising awareness about zoonotic diseases are major growth drivers. The robust expansion of the livestock sector further underpins Asia Pacific’s accelerating market trajectory.
Latin America
Latin America accounts for a smaller but growing share of the Milbemycin market, valued at USD 51.0 million in 2018, increasing to USD 65.3 million in 2024, and forecasted to reach USD 142.1 million by 2032 at a CAGR of 5.8%. With a current market share of about 5.2%, the region is benefiting from rising livestock production, expanding agricultural activities, and gradual improvements in veterinary infrastructure. However, market expansion remains constrained by limited access to advanced pharmaceuticals and regulatory challenges.
Middle East
The Middle East represents a developing segment in the Milbemycin market, with a market size of USD 60.7 million in 2018, progressing to USD 92.9 million in 2024 and expected to reach USD 178.1 million by 2032 at a CAGR of 6.5%. The region currently holds around 6.6% of the global market share. Growth is driven by increased focus on livestock health and government initiatives supporting the animal health sector, though market size remains moderate due to infrastructural limitations.
Africa
Africa contributes a modest share to the global Milbemycin market, valued at USD 29.0 million in 2018, reaching USD 50.2 million in 2024, and projected to slightly decrease to USD 47.4 million by 2032, with a negative growth outlook (CAGR 4.8%). Currently accounting for approximately 2.1% of the global market, Africa’s market is challenged by limited veterinary infrastructure, lower awareness of animal health solutions, and economic constraints, which collectively restrict the pace of market development in the region.
Market Segmentations:
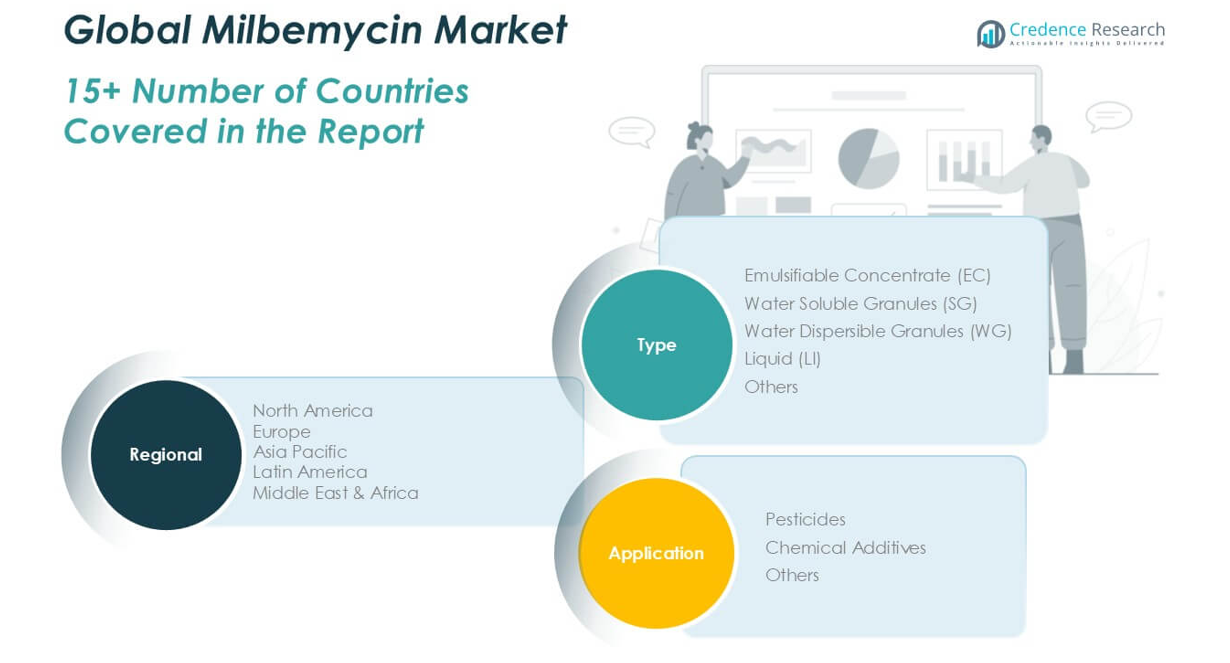
By Type
- Emulsifiable Concentrate (EC)
- Water Soluble Granules (SG)
- Water Dispersible Granules (WG)
- Liquid (LI)
- Others
By Application
- Pesticides
- Chemical Additives
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Milbemycin market is characterized by the presence of several prominent multinational companies and specialized regional players, all striving to enhance their market positions through strategic initiatives and innovation. Leading firms such as Merck & Co. / MSD Animal Health, Elanco Animal Health, Zoetis Inc., Boehringer Ingelheim, and Bayer Animal Health dominate the market, leveraging robust product portfolios, advanced R&D capabilities, and extensive distribution networks. These companies focus on product differentiation, regular portfolio expansion, and the introduction of new formulations to address emerging demands in both companion animal and livestock segments. Global players like Syngenta AG, BASF SE, and DuPont further intensify competition by integrating Milbemycin into broader pest management solutions. Regional manufacturers, including Jiamusi Xingyu and Zhejiang Hisun Pharmaceutical, contribute to market diversity and price competitiveness. Strategic partnerships, acquisitions, and continuous investment in sustainable production practices remain central to maintaining a competitive edge in this evolving landscape.
Key Player Analysis
- Merck & Co. / MSD Animal Health
- Elanco Animal Health
- Zoetis Inc.
- Boehringer Ingelheim
- Bayer Animal Health
- Syngenta AG
- BASF SE
- DuPont
- Norbrook Laboratories
- Jiamusi Xingyu (China)
- SinoHarvest (USA)
- Sino‑Agri United (USA)
- Ginkgo BioWorks
- Zhejiang Hisun Pharmaceutical / Chemica
Recent Developments
- In July 2024, Elanco completed the sale of its aqua business to MSD Animal Health (Merck), which included anti-parasitic treatments relevant to aquatic species. While the announcement highlights products like IMVIXA® (for sea lice), there is no direct reference to milbemycin-based products in this transaction.
Market Concentration & Characteristics
The Milbemycin Market demonstrates moderate to high market concentration, with a few global leaders such as Merck & Co. / MSD Animal Health, Elanco Animal Health, Zoetis Inc., Boehringer Ingelheim, and Bayer Animal Health collectively accounting for a substantial portion of total revenues. It features strong entry barriers due to the complexities of regulatory approvals, substantial investment requirements for research and development, and the technical expertise needed for product formulation. The market favors companies with established distribution networks and broad product portfolios, supporting rapid adoption in both developed and emerging economies. It is characterized by a high degree of innovation, with frequent product enhancements, the introduction of combination therapies, and advanced formulations designed to improve efficacy and safety profiles. Regulatory standards and a focus on sustainable production continue to influence company strategies. Competitive differentiation is largely driven by technological advancements, quality, and the ability to address evolving customer needs across various application segments
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Milbemycin Market will expand with increasing adoption of preventative animal healthcare practices.
- Producers will introduce innovative combination products to broaden parasite control coverage.
- Regulatory agencies will tighten oversight, prompting investments in safety and compliance.
- Emerging regions will drive volume growth through improved veterinary infrastructure and awareness.
- Advances in formulation technologies will enhance delivery and reduce dosing frequency.
- Focus on sustainable and eco-friendly products will shape R&D priorities.
- Digital platforms will streamline distribution and veterinary service delivery.
- Collaboration among animal health firms will accelerate product pipeline development.
- Monitoring of parasite resistance will inform targeted product use and lifecycle management.
- Supply chain optimization will become essential to mitigate raw material disruptions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Preventive Animal Healthcare and Pet Ownership
The increasing global trend of pet ownership, especially in emerging economies, is driving demand for Milbemycin-based products as pet owners prioritize preventive care such as heartworm prevention and deworming. This shift is boosting the consumption of Milbemycin in the companion animal segment.
Expansion of Livestock and Agricultural Sectors
Rising investments in animal healthcare and evolving agricultural practices, particularly in Asia-Pacific and Latin America, are increasing the adoption of Milbemycin for livestock parasite management. This is further supported by government initiatives and growing awareness of zoonotic disease control.
Innovation in Formulation and Combination Therapies
Industry players are developing advanced Milbemycin formulations, including sustained-release and combination products, to enhance efficacy, safety, and compliance. These innovations reduce dosing frequency, broaden spectrum of action, and address resistance management, making Milbemycin products more attractive to end-users.
Regulatory Emphasis on Veterinary Pharmaceutical Quality
Stringent regulatory standards in developed markets are pushing manufacturers to invest in high-quality, safe, and effective Milbemycin products. Compliance with these regulations enhances market credibility and supports the adoption of Milbemycin-based solutions in both established and emerging regions.
Digital Distribution and Veterinary Infrastructure Growth
The rise of tele-veterinary services, e-commerce, and improved veterinary infrastructure in developing regions is expanding access to Milbemycin products. These channels facilitate direct reach to end-users, especially in rural and underserved areas, supporting market penetration and growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Milbemycin Market?
What factors are driving the growth of the Milbemycin Market?
What are some challenges faced by the Milbemycin Market?
Who are the major players in the Milbemycin Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Emulsifiable Concentrate (EC)
- 1.2.2 Water Soluble Granules (SG)
- 1.2.3 Water Dispersible Granules (WG)
- 1.2.4 Liquid (LI)
- 1.2.5 Others
- 1.3 By Animal Type
- 1.3.1 Companion Animals
- 1.3.2 Livestock
- 1.3.3 Aquatic Species
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Pesticides
- 1.4.2 Chemical Additives
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,255.0 million → 2032: USD 2,255.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Milbemycin Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Milbemycin Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Milbemycin Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Milbemycin Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Milbemycin Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Milbemycin Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Milbemycin Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Milbemycin Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,255.0 million → 2032: USD 2,255.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Milbemycin Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Emulsifiable Concentrate (EC)
- 12.3.7.2 Water Soluble Granules (SG)
- 12.3.7.3 Water Dispersible Granules (WG)
- 12.3.7.4 Liquid (LI)
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Animal Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Companion Animals
- 12.4.7.2 Livestock
- 12.4.7.3 Aquatic Species
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pesticides
- 12.5.7.2 Chemical Additives
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Milbemycin End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Milbemycin Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Milbemycin Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Milbemycin Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Merck & Co. / MSD Animal Health
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Elanco Animal Health
- 18.4 Zoetis Inc.
- 18.5 Boehringer Ingelheim
- 18.6 Bayer Animal Health
- 18.7 Syngenta AG
- 18.8 BASF SE
- 18.9 DuPont
- 18.10 Norbrook Laboratories
- 18.11 Zhejiang Hisun Pharmaceutical
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

