
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Multi-Cancer Early Detection (MCED) Market Size 2024 | USD 1,870 million |
| Multi-Cancer Early Detection (MCED) Market, CAGR | 17.2% |
| Multi-Cancer Early Detection (MCED) Market Size 2032 | USD 6,656.75 million |
Market Overview:
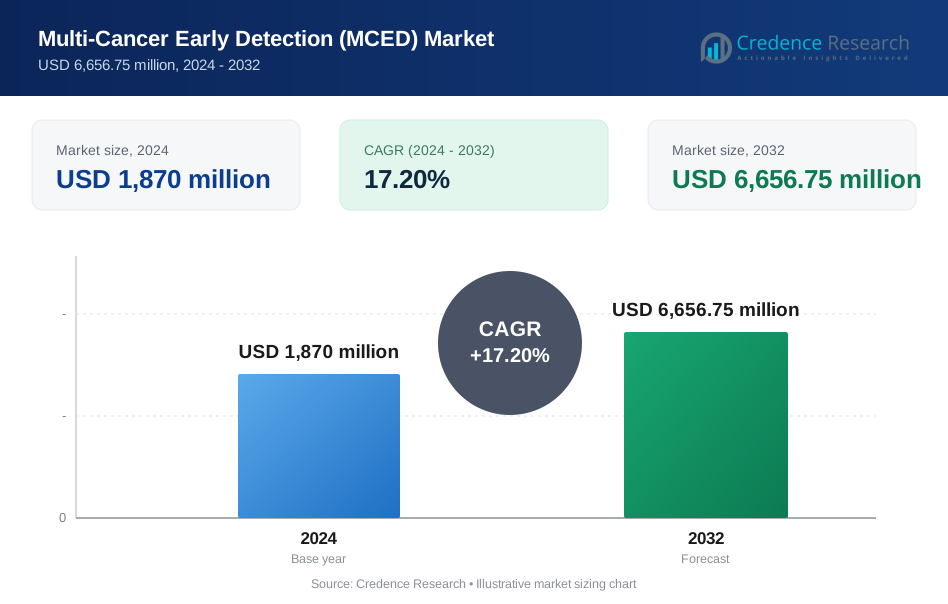
The Multi-Cancer Early Detection (MCED) market is projected to grow from USD 1,870 million in 2024 to USD 6,656.75 million by 2032, with a compound annual growth rate (CAGR) of 17.2%.
The Multi-Cancer Early Detection (MCED) market is driven by increasing cancer prevalence, rising awareness about the importance of early detection, and advancements in diagnostic technologies. The demand for MCED solutions is further propelled by the shift towards precision medicine and personalized healthcare, as well as the growing adoption of non-invasive screening methods. Governments and healthcare organizations are investing in cancer screening programs, aiming to reduce the overall cancer burden through early diagnosis, which improves treatment outcomes and lowers healthcare costs. Additionally, the development of multi-cancer screening tests capable of detecting various cancer types in asymptomatic patients is gaining traction. Trends such as artificial intelligence and machine learning are playing a critical role in enhancing the accuracy and efficiency of MCED technologies. Furthermore, strategic collaborations between biotech companies, research institutions, and healthcare providers are fostering innovation in this rapidly growing market. The adoption of MCED solutions is expected to rise as affordability and accessibility improve over time.
The Multi-Cancer Early Detection (MCED) market demonstrates significant geographical variation, with North America leading in market share, driven by advanced healthcare infrastructure and strong governmental initiatives, holding approximately 40% of the global market in 2024. Europe follows closely with 30%, benefiting from robust early detection programs in countries like Germany and the UK. The Asia-Pacific region, accounting for 20%, is an emerging market with rapid healthcare advancements in China, Japan, and India. The Rest of the World, including Latin America, the Middle East, and Africa, holds the remaining 10%, with gradual growth as healthcare investments rise. Key players like GRAIL, Guardant Health, Thrive Earlier Detection, and Exact Sciences maintain a strong presence across these regions, driving innovation and expansion in early cancer detection technologies.
Market Insights:
- The Multi-Cancer Early Detection (MCED) market is projected to grow from USD 1,870 million in 2024 to USD 6,656.75 million by 2032, with a CAGR of 17.2%.
- Increasing cancer prevalence and the rising awareness of early detection are key drivers of the MCED market, along with advancements in diagnostic technologies.
- The demand for MCED solutions is fueled by a shift towards precision medicine and personalized healthcare, alongside growing adoption of non-invasive screening methods.
- Government initiatives and healthcare investments are boosting the adoption of MCED technologies, with early diagnosis reducing treatment costs and improving outcomes.
- Technologies such as liquid biopsy and next-generation sequencing are driving the development of multi-cancer screening tests that can detect various cancers in asymptomatic patients.
- Artificial intelligence and machine learning are playing a vital role in enhancing the accuracy and efficiency of MCED tests, fostering innovation in the market.
- The market demonstrates geographical variation, with North America leading, followed by Europe, Asia-Pacific, and the Rest of the World, where growth potential is emerging.
Market Drivers:
Increasing Cancer Prevalence and Need for Early Detection:
The growing global cancer burden is a primary driver of the Multi-Cancer Early Detection (MCED) market. As cancer rates continue to rise, the demand for early detection solutions becomes more critical. Early diagnosis significantly improves the chances of successful treatment and survival, reducing the need for more invasive and costly therapies. For instance, tests like GRAIL's Galleri can detect multiple types of cancer at an early stage from a single blood sample, enabling prompt medical intervention. This pressing need for early-stage cancer detection is encouraging healthcare providers and governments to invest in advanced diagnostic technologies, leading to greater adoption of MCED tests.
Technological Advancements in Diagnostics:
Rapid advancements in diagnostic technologies are fueling the growth of the MCED market. Innovations in genomics, molecular biology, and next-generation sequencing (NGS) have paved the way for the development of multi-cancer screening tests that detect multiple types of cancer through a single blood test. These tests offer a less invasive, more efficient, and highly accurate alternative to traditional screening methods. Additionally, the integration of artificial intelligence (AI) and machine learning in diagnostics is enhancing the precision and predictive capabilities of MCED solutions, making them more effective and widely accessible.
Government Initiatives and Healthcare Investments:
Governments and healthcare organizations worldwide are actively supporting initiatives to reduce cancer mortality rates, which is further driving the MCED market. Public health campaigns and government-funded programs are encouraging early cancer screening to lower the economic and social burden of cancer. For instance, the U.S. National Cancer Institute's Cancer Moonshot program is funding research to advance early detection technologies, promoting innovation in MCED tests. These initiatives, along with increased funding for cancer research and screening technologies, are creating a favorable environment for the growth of the MCED market, as they expand access to early detection solutions.
Shift Towards Personalized and Preventive Healthcare:
The rising emphasis on personalized and preventive healthcare is another key factor driving the MCED market. As healthcare systems shift toward more individualized approaches to treatment and prevention, multi-cancer early detection tests are gaining traction for their ability to detect cancers before symptoms arise. This proactive approach aligns with the broader trend of precision medicine, where early intervention can lead to better patient outcomes and lower healthcare costs.
Market Trends:
Adoption of Non-Invasive Screening Methods:
One of the prevailing trends in the Multi-Cancer Early Detection (MCED) market is the growing preference for non-invasive screening techniques. Liquid biopsy, which involves analyzing blood samples to detect cancer-related biomarkers, is gaining traction due to its convenience and minimal risk to patients. For instance, GRAIL's Galleri test utilizes liquid biopsy technology to detect over 50 types of cancer from a single blood sample, offering a patient-friendly alternative to traditional biopsies. This shift away from traditional invasive procedures, such as tissue biopsies, reflects the increasing demand for more patient-friendly screening methods that can identify multiple cancer types with a single test, enhancing early detection efforts.
Integration of Artificial Intelligence and Machine Learning:
Artificial intelligence (AI) and machine learning (ML) are playing a pivotal role in improving the accuracy and efficiency of MCED technologies. These tools enable the analysis of large volumes of genetic and molecular data, helping to identify cancer signals with greater precision. AI-driven algorithms are being used to enhance the sensitivity of detection tests, reducing false positives and negatives, which ultimately leads to better clinical outcomes. This trend is accelerating the development and adoption of more advanced, AI-enhanced MCED solutions.
Expansion of Multi-Cancer Screening Tests:
The MCED market is witnessing an increasing focus on multi-cancer screening tests capable of detecting several cancer types simultaneously. This expansion is driven by the need for cost-effective and comprehensive cancer detection methods. For instance, Exact Sciences has developed multi-cancer screening tools that aim to identify hard-to-detect cancers, improving early-stage diagnosis rates. Companies are developing tests that can screen for various cancers, including those that are often difficult to detect in their early stages. These advancements are making cancer screening more efficient and accessible, which is expected to drive broader adoption in clinical settings.
Collaborations and Strategic Partnerships:
Collaborations between biotech companies, research institutions, and healthcare providers are shaping the MCED market. These partnerships foster innovation and accelerate the commercialization of cutting-edge detection technologies. By pooling resources and expertise, stakeholders are driving the development of new MCED solutions that meet the growing demand for early cancer detection, contributing to the overall growth of the market.
Market Challenges Analysis:
High Cost of Advanced Diagnostic Technologies:
A significant challenge in the Multi-Cancer Early Detection (MCED) market is the high cost associated with advanced diagnostic technologies. While innovations such as next-generation sequencing (NGS) and liquid biopsies have revolutionized early cancer detection by offering more accurate and less invasive solutions, their implementation remains costly. The expenses related to research, development, and the acquisition of complex equipment required for these tests often result in high prices for end users. This makes MCED solutions less accessible, particularly in low- and middle-income countries where healthcare infrastructure and budgets are already constrained. High costs also present challenges for widespread adoption in public health systems, where cost-effectiveness and budgetary constraints are critical considerations. For example two-step MCED screening approach that utilizes OncoSeek for initial screening, followed by SeekInCare for individuals who test positive. Additionally, the cost burden may deter healthcare providers from adopting MCED solutions on a large scale, impacting early cancer detection rates. Although prices may decrease over time as technology advances and economies of scale are realized, the current expense remains a significant barrier to broader implementation and accessibility for many healthcare providers and patients.
Regulatory and Reimbursement Hurdles:
Regulatory and reimbursement challenges further complicate the growth of the MCED market. Gaining regulatory approval for new cancer detection technologies can be a lengthy, complex process, requiring extensive clinical validation and large-scale trials to demonstrate safety, efficacy, and reliability. This process is essential but often delays the time-to-market for cutting-edge MCED solutions. Additionally, variations in regulatory standards across different countries and regions can further slow the global rollout of MCED technologies, adding layers of complexity for companies aiming to expand internationally. Even after regulatory clearance is achieved, securing reimbursement from insurance companies or government healthcare programs remains a significant hurdle. Many MCED tests are still considered experimental or investigational by insurers, leading to limited or inconsistent coverage. Without proper reimbursement mechanisms in place, patients may struggle to afford these early detection tests, limiting their widespread use. Addressing these regulatory and financial barriers will be essential for achieving large-scale adoption and realizing the full potential of MCED technologies across diverse healthcare systems.
Market Opportunities:
The Multi-Cancer Early Detection (MCED) market presents significant growth opportunities due to the increasing emphasis on early diagnosis and preventive healthcare. As cancer remains one of the leading causes of mortality worldwide, there is a growing demand for comprehensive screening methods that can detect multiple cancer types at early stages. The development of innovative MCED solutions, particularly those utilizing liquid biopsy and next-generation sequencing (NGS) technologies, offers a unique opportunity to meet this demand. These non-invasive tests provide the ability to identify cancer biomarkers through a simple blood test, making screening more convenient for patients and expanding access to early detection. With rising awareness and adoption of these advanced diagnostic tools, there is potential for market expansion, especially in developed countries where healthcare systems are more equipped to integrate such technologies.
Furthermore, the growing focus on personalized medicine and precision oncology creates a favorable environment for the MCED market. The integration of AI and machine learning into cancer detection is expected to improve the accuracy and efficiency of these tests, offering healthcare providers more precise diagnostic tools. Additionally, expanding collaborations between biotechnology companies, research institutions, and healthcare organizations can accelerate the development of more affordable MCED solutions, making them accessible to broader populations. Emerging markets, in particular, offer substantial opportunities for growth, as improving healthcare infrastructure and increasing government initiatives aimed at cancer prevention will drive demand for early detection technologies. By capitalizing on these trends and focusing on reducing costs and enhancing accessibility, the MCED market has significant potential to shape the future of cancer screening and contribute to better patient outcomes globally.
Market Segmentation Analysis:
By Type
The Multi-Cancer Early Detection (MCED) market can be segmented by type, primarily into liquid biopsy and gene panel-based tests. Liquid biopsy, which involves the analysis of blood samples to detect cancer-specific biomarkers, is gaining popularity due to its non-invasive nature and efficiency. Gene panel-based tests, leveraging next-generation sequencing (NGS), offer precise, multi-cancer screening capabilities and are particularly favored in advanced healthcare settings. As demand for comprehensive early detection methods increases, both segments are expected to grow, with liquid biopsy witnessing accelerated adoption due to its accessibility.
By End Use
The MCED market is also segmented by end use, including hospitals, diagnostic laboratories, and research institutes. Hospitals and diagnostic laboratories represent the largest end-use segments, driven by the increasing integration of early detection tests in routine clinical practices. Research institutes are a key contributor to the market’s growth, as ongoing research and development in cancer detection technologies propel innovation. Each segment plays a critical role in advancing the adoption of MCED solutions globally.
Segments:
Based on Type:
- Gene Panel
- LDT & Others
- Liquid Biopsy
Based on End-User
- Diagnostic Laboratories
- Hospitals
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds the largest share of the Multi-Cancer Early Detection (MCED) market, accounting for 40% of the global market in 2024. The region’s dominance is driven by advanced healthcare infrastructure, significant government investments in cancer research, and high awareness regarding early cancer screening. The United States, in particular, plays a critical role due to the presence of leading biotechnology companies, cutting-edge research institutions, and strong regulatory support. Initiatives like the Biden-Harris administration’s Cancer Moonshot, which aims to accelerate cancer detection and treatment, further boost the adoption of MCED technologies. Additionally, favorable reimbursement policies and high adoption rates of innovative diagnostic tools contribute to North America's substantial market share. The increasing prevalence of cancer and the growing demand for precision medicine will likely sustain this region’s leadership position in the coming years.
Europe:
Europe holds the second-largest share of the MCED market, capturing 30% of the global market in 2024. The region benefits from strong government initiatives, particularly in countries like Germany, the United Kingdom, and France, where cancer prevention and early detection programs are prioritized. Europe’s well-established healthcare systems are increasingly adopting advanced diagnostic technologies, including multi-cancer screening tests, to address the rising cancer burden. Additionally, collaborative efforts between biotechnology companies and research institutions in the European Union are driving innovation in cancer diagnostics. The European market is further supported by a growing aging population and a high level of public awareness about the importance of early cancer detection. As a result, Europe is expected to witness steady growth in the MCED market over the forecast period.
Asia-Pacific:
The Asia-Pacific region is an emerging market for MCED technologies, accounting for 20% of the global market in 2024. The region's growth is driven by increasing cancer incidence, rising healthcare expenditure, and improving healthcare infrastructure, particularly in countries like China, Japan, and India. Governments in these countries are increasingly focusing on early cancer detection to reduce cancer-related mortality rates, creating a favorable environment for the adoption of MCED solutions. Although the market share is lower compared to North America and Europe, the Asia-Pacific region presents significant growth potential, especially as healthcare providers invest in advanced diagnostic technologies and screening programs. Additionally, the region’s large population base and the rising middle class contribute to the growing demand for accessible and cost-effective cancer screening solutions.
Rest of the World:
The Rest of the World (RoW), including regions like Latin America, the Middle East, and Africa, holds the remaining 10% of the global MCED market share in 2024. These regions are witnessing a gradual increase in the adoption of cancer screening technologies, though market penetration remains lower compared to more developed regions. However, growing healthcare investments and increased government initiatives aimed at cancer prevention are expected to drive demand for MCED solutions in these regions. While infrastructure and affordability challenges persist, ongoing advancements in healthcare systems, along with international collaborations, will likely expand the market's reach across the RoW.
Key Player Analysis:
- Guardant Health
- Thrive Earlier Detection
- GRAIL
- Freenome
- Exact Sciences
- Foundation Medicine
- CellMax Life
- C2i Genomics
- Elypta
- StageZero Life Sciences
- VolitionRX
- Genomic Health
- Burning Rock Biotech
Competitive Analysis:
The Multi-Cancer Early Detection (MCED) market is highly competitive, with several leading players driving innovation and technological advancements. Companies such as GRAIL, Guardant Health, Thrive Earlier Detection, Freenome, and Exact Sciences are at the forefront of developing cutting-edge MCED technologies. These firms focus on leveraging next-generation sequencing (NGS), liquid biopsy, and machine learning to improve the accuracy and accessibility of cancer detection tests. GRAIL’s Galleri test and Guardant Health’s Guardant360 are notable examples of advanced MCED solutions currently available in the market. Additionally, companies like Foundation Medicine and Burning Rock Biotech are expanding their presence by developing precision oncology tools and enhancing early cancer detection capabilities. The competitive landscape is further intensified by emerging players like CellMax Life, C2i Genomics, and Elypta, which are introducing novel approaches to multi-cancer screening. Strategic collaborations, mergers, and acquisitions are common as these players seek to expand their portfolios and solidify their positions in this rapidly growing market.
Recent Developments:
- In February 2024, the NIH launched the Cancer Screening Research Network (CSRN) to assess innovative detection technologies and methods, aligning with the Biden-Harris administration's Cancer Moonshot initiative. To support this, the National Cancer Institute (NCI) funded eight research groups to commence the network.
- In August 2024, Exact Sciences had enrolled its first patient in the MCED Falcon Registry Real-World Evidence study at Baylor Scott & White, Texas's largest non-profit health system. This multi-site study aims to recruit up to 25,000 patients to evaluate the clinical performance, patient and provider experiences, and the psychological impact of Multi-Cancer Early Detection (MCED) testing over five years.
- In October 2024, SeekIn Inc. unveiled a groundbreaking two-step multi-cancer screening strategy at the Early Detection of Cancer Conference in San Francisco. This approach is designed to reduce the financial burden of widespread screening, making MCED tests more affordable and accessible.
Market Concentration & Characteristics:
The Multi-Cancer Early Detection (MCED) market is characterized by a moderate to high level of concentration, with a few key players dominating the industry. Companies such as GRAIL, Guardant Health, Thrive Earlier Detection, and Exact Sciences hold significant market shares due to their advanced technologies and established presence. These players are driving innovation through extensive research and development, focusing on precision diagnostics and multi-cancer screening methods. The market is also marked by ongoing collaborations between biotech firms, research institutions, and healthcare providers to accelerate product development and expand clinical applications. While large corporations lead the market, smaller, emerging companies are introducing disruptive technologies that contribute to increasing competition. The MCED market is dynamic, with a strong emphasis on technological advancements, non-invasive testing, and early cancer detection, aligning with the broader healthcare shift toward personalized medicine and improved patient outcomes.
Report Coverage:
The research report offers an in-depth analysis based on Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for multi-cancer early detection solutions will continue to rise as cancer prevalence increases globally.
- Technological advancements in genomics and liquid biopsy will enhance the accuracy and efficiency of MCED tests.
- Non-invasive screening methods will become more widely adopted due to their convenience and patient-friendly nature.
- Governments and healthcare organizations will invest more in early cancer detection programs to reduce cancer mortality rates.
- The integration of artificial intelligence and machine learning will play a crucial role in improving diagnostic precision.
- Strategic collaborations between biotech companies and research institutions will foster continued innovation in MCED technologies.
- Expansion into emerging markets, particularly in Asia-Pacific, will drive growth as healthcare infrastructure improves.
- Regulatory approvals will increase, facilitating broader global adoption of multi-cancer screening tests.
- Cost reduction efforts will make MCED solutions more accessible and affordable over time.
- The shift toward personalized and preventive healthcare will accelerate the adoption of MCED technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Cancer Prevalence and Need for Early Detection
Rising global cancer rates are intensifying the need for early detection solutions, as early diagnosis significantly improves treatment outcomes and survival rates. This is driving healthcare providers and governments to invest in advanced MCED technologies that can identify cancers at asymptomatic stages.
Technological Advancements in Diagnostics
Innovations in genomics, next-generation sequencing, and liquid biopsy are enabling the development of highly accurate, non-invasive multi-cancer screening tests. These advancements are making MCED solutions more effective and accessible, accelerating their adoption in clinical practice.
Government Initiatives and Healthcare Investments
Governments and healthcare organizations are launching early cancer screening programs and increasing funding for research, which is expanding access to MCED technologies. Initiatives like the U.S. Cancer Moonshot are directly supporting the development and deployment of early detection solutions.
Shift Toward Personalized and Preventive Healthcare
The movement toward precision medicine and preventive care is boosting demand for MCED tests, as these solutions align with the goal of identifying and treating cancers before symptoms arise. This trend is fostering broader integration of MCED technologies into routine healthcare.
Integration of Artificial Intelligence and Machine Learning
AI and machine learning are enhancing the accuracy and efficiency of MCED tests by enabling the analysis of complex genetic and molecular data. This technological integration is reducing false positives/negatives and supporting the development of next-generation screening tools.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Multi-Cancer Early Detection Market?
What factors are driving the growth of the Multi-Cancer Early Detection Market?
What are the key segments within the Multi-Cancer Early Detection Market?
Who are the major players in the Multi-Cancer Early Detection Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Gene Panel
- 1.2.2 LDT & Others
- 1.2.3 Liquid Biopsy
- 1.3 By End-User
- 1.3.1 Diagnostic Laboratories
- 1.3.2 Hospitals
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,870 million → 2032: USD 6,656.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Multi-Cancer Early Detection (MCED) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Multi-Cancer Early Detection (MCED) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Multi-Cancer Early Detection (MCED) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Multi-Cancer Early Detection (MCED) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Multi-Cancer Early Detection (MCED) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Multi-Cancer Early Detection (MCED) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Multi-Cancer Early Detection (MCED) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Multi-Cancer Early Detection (MCED) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,870 million → 2032: USD 6,656.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Multi-Cancer Early Detection (MCED) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gene Panel
- 12.3.7.2 LDT & Others
- 12.3.7.3 Liquid Biopsy
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diagnostic Laboratories
- 12.4.7.2 Hospitals
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Multi-Cancer Early Detection (MCED) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Multi-Cancer Early Detection (MCED) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Multi-Cancer Early Detection (MCED) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Multi-Cancer Early Detection (MCED) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GRAIL
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Guardant Health
- 18.4 Thrive Earlier Detection
- 18.5 Exact Sciences
- 18.6 Freenome
- 18.7 Foundation Medicine
- 18.8 CellMax Life
- 18.9 Burning Rock Biotech
- 18.10 C2i Genomics
- 18.11 Elypta
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
