
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
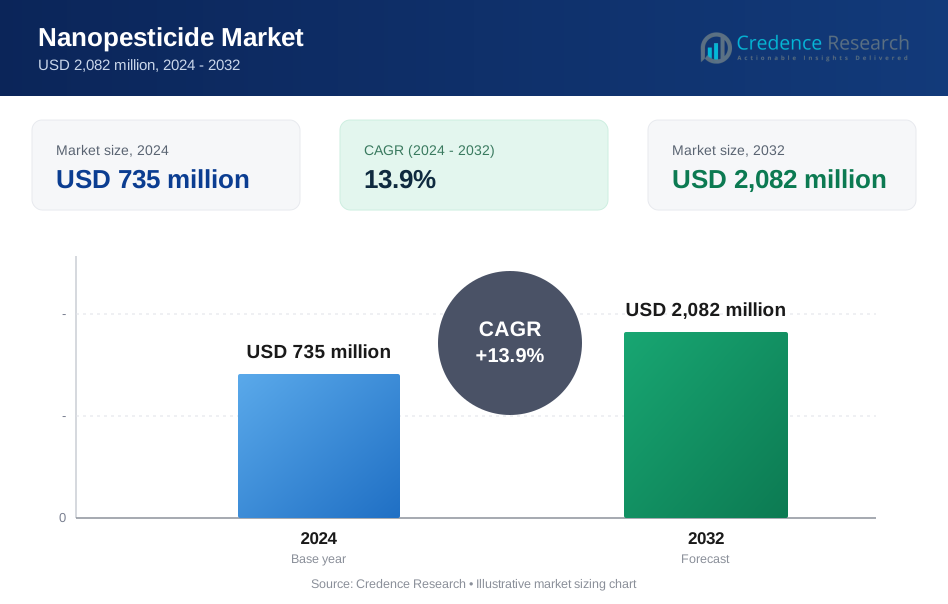
| Nanopesticide Market Size 2024 | USD 735 million |
| Nanopesticide Market, CAGR | 13.9% |
| Nanopesticide Market Size 2032 | USD 2,082 million |
Market Overview:
The Nanopesticide Market is projected to grow from USD 735 million in 2024 to an estimated USD 2,082 million by 2032, with a compound annual growth rate (CAGR) of 13.9% from 2024 to 2032.
Key drivers of the nanopesticide market include increasing demand for sustainable agricultural practices and the rising need for more efficient pest management solutions. Nanopesticides offer several advantages over traditional pesticides, including improved targeting of pests, reduced environmental impact, and enhanced crop protection. These benefits are particularly important as the agricultural industry seeks to address challenges such as pest resistance, soil degradation, and the need for higher crop yields in the face of climate change. Additionally, the growing adoption of precision agriculture, which leverages advanced technologies like drones, sensors, and data analytics, is expected to further propel the demand for nanopesticides. These technologies allow for more precise application of nanoparticles, minimizing waste and ensuring that pesticides are delivered directly to the intended target, thus reducing their impact on non-target species and the environment.
Regionally, North America and Europe are expected to dominate the nanopesticide market due to the presence of key industry players, stringent regulatory frameworks, and growing investments in agricultural research and development. In Asia Pacific, countries like China and India are anticipated to experience significant market growth, driven by the increasing demand for crop protection solutions, the adoption of advanced agricultural technologies, and the region's vast agricultural output. Latin America and the Middle East & Africa are also likely to see growing adoption of nanopesticides as part of their efforts to improve crop yields and sustainability in agriculture.
Market Drivers:
Technological Advancements in Nanotechnology:
Nanotechnology is revolutionizing pest management in agriculture by enabling the development of highly effective and targeted pesticide formulations. Nanopesticides utilize nanoparticles to increase the efficiency and precision of pest control methods. These advancements in nanotechnology provide significant advantages over traditional pesticide formulations by reducing chemical usage and enhancing delivery systems for active ingredients. For instance, the U.S. National Nanotechnology Initiative (NNI) has supported research into nanotechnology applications in agriculture, leading to innovations in nanopesticide formulations. Nanoparticles allow for the controlled release of pesticides, which not only minimizes wastage but also ensures that pesticides are applied precisely where needed. This targeted approach reduces the environmental footprint of pest control and helps to mitigate issues such as pesticide resistance, a growing problem in traditional pest management. The International Food Policy Research Institute (IFPRI) reported that the use of innovative agricultural technologies, such as nanotechnology, could help increase global food production by 70% by 2050. This is particularly crucial as the global population continues to grow and the demand for food intensifies. Nanotechnology in pesticide development is expected to significantly contribute to addressing these challenges.
Regulatory Support and Government Initiatives:
Government regulations play a crucial role in driving the adoption of nanopesticides by encouraging the development of more sustainable and less harmful agricultural practices. As environmental concerns become more prominent, regulatory bodies in various regions are increasingly pushing for the use of safer, more eco-friendly pesticides. In many countries, regulatory frameworks are evolving to support the use of nanotechnology in agricultural applications. The European Commission, through its European Union Framework Program for Research and Innovation, has supported several research initiatives that focus on the safe use of nanomaterials in agricultural products. These initiatives are designed to ensure that nanopesticides meet rigorous safety standards, addressing potential concerns regarding their environmental and health impacts. Furthermore, the European Union's Farm to Fork Strategy, introduced in 2020, emphasizes the need for a more sustainable food system. The strategy outlines objectives such as reducing pesticide use by 50% by 2030, creating an opportunity for nanopesticides to play a critical role in meeting these sustainability goals.
Growing Environmental Awareness and Sustainability:
Environmental sustainability is becoming a top priority for both consumers and businesses alike. There is increasing awareness about the environmental impact of traditional pesticide use, which has led to a shift towards more eco-friendly alternatives, including nanopesticides. Nanopesticides offer numerous environmental benefits, including lower toxicity, reduced environmental contamination, and better targeting of pests. This makes them a more sustainable option for pest control. For example, the United Nations Environment Programme (UNEP) has advocated for the adoption of sustainable agricultural practices to address issues such as pesticide runoff, soil degradation, and biodiversity loss. Nanopesticides, by virtue of their precision and reduced environmental impact, align with these global sustainability goals. The World Health Organization (WHO) has highlighted that excessive use of traditional chemical pesticides is a major contributor to the decline in pollinator populations, underscoring the need for safer alternatives.
Changing Consumer Preferences for Organic and Sustainable Products:
Consumer demand for organic and sustainably produced food is rapidly increasing, driven by concerns about health, environmental impact, and food quality. As consumers become more educated about the negative effects of chemical pesticides, there is a growing preference for food produced with minimal chemical inputs. Nanopesticides offer a potential solution to this problem, as they are more targeted, require smaller quantities, and reduce the need for harmful chemical applications. The Food and Agriculture Organization (FAO) has reported that the global organic food market has grown substantially, with organic food sales increasing by 10% annually. This surge in demand for organic produce is driving the need for alternative pest management solutions, such as nanopesticides, which align with organic farming principles by reducing the use of traditional chemical pesticides. Moreover, global certification bodies such as The International Federation of Organic Agriculture Movements (IFOAM) are encouraging farmers to adopt eco-friendly pest control solutions to maintain organic certification. Nanopesticides, being more sustainable and environmentally friendly, are well-positioned to meet these growing consumer expectations.
Market Trends:
Increasing Adoption of Precision Agriculture Technologies:
The integration of precision agriculture technologies is a significant trend driving the adoption of nanopesticides. Precision agriculture involves using advanced tools such as drones, satellite imaging, sensors, and data analytics to optimize agricultural practices and increase efficiency. Nanopesticides, due to their precision and effectiveness, fit well into the precision farming model by allowing for targeted pesticide applications. This reduces chemical usage and ensures that pesticides are applied only where they are needed, minimizing environmental damage. For instance, the United States Department of Agriculture (USDA) has reported that the adoption of precision agriculture tools has been increasing steadily across the U.S. agricultural sector, with over 75% of farms using some form of precision farming technology. These technologies enable farmers to apply pesticides with higher accuracy, which aligns with the benefits offered by nanopesticides. Moreover, the USDA’s Economic Research Service notes that the use of precision technologies could reduce input costs by up to 10%, further incentivizing the use of more efficient pest management tools, such as nanopesticides.
Rising Focus on Sustainable Agricultural Practices:
There is a growing global trend towards sustainable agricultural practices, driven by the need to balance increased food production with environmental conservation. Governments, international organizations, and businesses are pushing for the reduction of harmful chemicals in farming and encouraging sustainable pest management solutions. Nanopesticides are gaining traction as they offer an environmentally friendly alternative to conventional chemical pesticides, with reduced toxicity to non-target organisms and lower environmental persistence. For example, the European Commission’s Green Deal and its Farm to Fork Strategy aim to reduce pesticide use in Europe by 50% by 2030, fostering the adoption of more sustainable agricultural practices. In support of this, the Food and Agriculture Organization (FAO) has highlighted that adopting sustainable pest control methods like nanopesticides is crucial to ensuring food security while protecting the environment. The FAO estimates that transitioning to sustainable farming systems globally could potentially increase agricultural productivity by 15% to 20%, while also reducing environmental impact, thus reinforcing the need for innovative solutions like nanopesticides. Moreover, the World Bank has emphasized the role of sustainable agricultural technologies in improving food security in developing regions. According to their report, countries in Africa and South Asia could benefit significantly from adopting sustainable practices, including the use of nanotechnology for crop protection, to increase yields while preserving environmental health.
Market Challenge Analysis:
Regulatory Hurdles and Safety Concerns:
One of the significant challenges facing the nanopesticide market is the regulatory uncertainty and safety concerns surrounding the use of nanotechnology in agricultural products. While nanopesticides hold promise for more effective and sustainable pest control, the regulatory frameworks for nanomaterials are still evolving. In many regions, including the United States and the European Union, regulations governing the use of nanotechnology in agriculture are not fully established, which creates a complex approval process for nanopesticide products. For example, the U.S. Environmental Protection Agency (EPA) has approved certain nanopesticide formulations but continues to require extensive safety data to assess their impact on human health and the environment. Regulatory bodies like the European Food Safety Authority (EFSA) have raised concerns about the potential long-term effects of nanoparticles on ecosystems and human health, particularly regarding the accumulation of nanoparticles in soil and water. The lack of standardized testing protocols and the slow pace of regulatory approval are creating significant barriers to widespread adoption. These concerns also extend to the lack of a universally accepted definition of "nanomaterials," which makes it difficult to classify and regulate products consistently.
High Research and Development Costs:
Another major challenge in the nanopesticide market is the high costs associated with research, development, and manufacturing of nanopesticide products. The process of developing effective nanopesticide formulations is complex and resource-intensive, often requiring specialized expertise and cutting-edge technology. This makes it difficult for small and medium-sized enterprises (SMEs) to enter the market, as they lack the financial resources to conduct extensive R&D and navigate regulatory approval processes. For instance, research conducted by the International Food Policy Research Institute (IFPRI) indicates that developing novel nanomaterials for agricultural use can be prohibitively expensive, often requiring multi-million-dollar investments in R&D. In addition, there is a lack of public and private funding specifically earmarked for nanotechnology in agriculture, which results in slower innovation and higher entry barriers for new companies. The cost of producing nanopesticides at scale, combined with the complexities of maintaining product quality and safety standards, adds further financial pressure on manufacturers. Additionally, large companies that dominate the agricultural chemicals market have greater resources to invest in the development of nanopesticide products, which puts smaller firms at a competitive disadvantage.
Market Segmentation Analysis:
By Type
The nanopesticide market is segmented based on the type of nanoparticle used. Common types include nanoemulsions, nanoparticles, and nanostructured materials. Nanoemulsions are widely favored for their stability and ability to deliver active ingredients effectively. Nanoparticles such as silica, carbon-based, and metal oxide nanoparticles are utilized for their ability to target pests with high precision while minimizing environmental impact. Each type has its unique advantages, depending on the specific requirements of pest control, such as the target pest, crop type, and environmental conditions.
By Technology
In terms of technology, the market is divided into chemical synthesis, biological synthesis, and physical methods. Chemical synthesis is the most common approach, involving the use of chemical reactions to create nanoparticles, offering scalability and controlled properties. Biological synthesis uses plant extracts or microorganisms to create nanoparticles, which is seen as an eco-friendly alternative. Physical methods, such as laser ablation and mechanical grinding, are also used to create nanoparticles with high precision and uniformity. Each technology provides different benefits related to cost, sustainability, and application efficiency.
By End-User
The primary end-users of nanopesticides are farmers and agricultural producers, including those in crop farming, horticulture, and forestry. The demand from these sectors is driven by the need for effective pest management solutions that can boost crop yield while minimizing environmental damage. Nanopesticides are also increasingly used in organic farming, where traditional chemical pesticides are limited. Additionally, the market sees growing interest from the landscaping and turf management sectors, where sustainable pest control methods are being adopted to maintain green spaces and public parks.
Segmentation:
Based on Product Type:
- Nanoemulsions
- Nanoparticles
- Nanostructured Materials
- Others
Based on Technology:
- Chemical Synthesis
- Biological Synthesis
- Physical Methods
Based on End-User:
- Crop Farming
- Horticulture
- Forestry
- Organic Farming
- Landscaping & Turf Management
Based on Region:
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- Latin America
- Brazil
- Argentina
- Chile
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Egypt
Regional Analysis:
North America
North America is expected to dominate the global nanopesticide market due to its advanced agricultural practices, strong regulatory frameworks, and significant investment in research and development (R&D). The region's established agricultural industry, particularly in the United States and Canada, is increasingly adopting sustainable and innovative farming solutions, including nanopesticides. In the U.S., large-scale agricultural producers are actively seeking alternatives to conventional pesticides that are more efficient, environmentally friendly, and aligned with evolving regulations. The U.S. Environmental Protection Agency (EPA) has taken a proactive approach to the approval and regulation of nanopesticides, fostering market growth by ensuring their safety and efficacy. Furthermore, the growing consumer demand for organic and sustainably grown produce in North America is driving the adoption of nanopesticides, which are seen as a safer and more sustainable alternative to traditional pesticides. According to estimates from the U.S. Department of Agriculture (USDA), the organic farming market in the U.S. continues to expand rapidly, with organic food sales in 2020 reaching nearly 6% of total food sales.
Europe
Europe is another key region for the growth of the nanopesticide market, driven by stringent environmental regulations and a strong emphasis on sustainable farming practices. The European Union’s Farm to Fork Strategy, which aims to reduce pesticide use by 50% by 2030, presents a significant opportunity for nanopesticides to gain market traction. With increasing concerns about the environmental impact of traditional pesticides, the EU has been actively promoting the use of eco-friendly alternatives, including nanopesticides. Countries like Germany, France, the United Kingdom, and Italy are leading the charge in adopting sustainable agricultural solutions. The EU is also heavily investing in research and development for nanotechnology in agriculture. The European Commission has provided funding for projects that focus on the safe use of nanomaterials in agriculture, helping to accelerate the commercialization of nanopesticides. Moreover, the growing demand for organic and sustainably grown food in Europe is driving farmers to explore alternative pest control methods, further boosting the market for nanopesticides.
Asia Pacific
The Asia Pacific region is poised for significant growth in the nanopesticide market due to the increasing demand for crop protection solutions in countries with large agricultural sectors such as China, India, Japan, and South Korea. Asia Pacific is the largest producer of agricultural commodities globally, with nations like China and India being major contributors to the world's food supply. As these countries face challenges such as pest resistance, soil degradation, and the need to increase agricultural productivity, nanopesticides offer an attractive solution. In countries like China, government initiatives and funding for agricultural innovation are driving the adoption of nanotechnology in pest management. The Chinese Academy of Agricultural Sciences (CAAS) has been involved in several research projects focused on the development and application of nanopesticides. In India, the government is promoting sustainable agriculture practices through its National Mission on Sustainable Agriculture (NMSA), which encourages the use of less harmful chemicals in farming. As a result, nanopesticides are gaining traction as part of the solution to these environmental and agricultural challenges.
Key Player Analysis:
- Andermatt Biocontrol AG
- Marrone Bio Innovations
- Stockton Biotechnologies
- Bayer AG
- Corteva
- Camson Biotechnologies
- BioWorks, Inc.
- Migrow Agro Solution
- Plantix Crop Care
- Annadata Organic
Competitive Analysis:
The nanopesticide market is highly competitive, with both established agrochemical companies and specialized nanotechnology firms vying for market share. Major industry players such as BASF, Syngenta, and DowDuPont dominate the space, leveraging their strong R&D capabilities, vast distribution networks, and deep industry expertise to integrate nanotechnology into their pesticide offerings. These companies are increasingly focusing on sustainable and precision-targeted solutions to meet the growing demand for eco-friendly pest control methods. However, smaller, more agile companies are also making significant inroads by developing innovative nanopesticide formulations and targeting niche applications in organic farming and precision agriculture. AgraQuest (now part of BASF) and Marrone Bio Innovations are examples of companies that have ventured into nanopesticides, focusing on biopesticides and nano-enabled solutions for pest management. Government-funded research initiatives, such as the National Nanotechnology Initiative (NNI) in the U.S. and the European Union’s Horizon 2020 program, are also facilitating innovation, enabling smaller firms to compete alongside larger corporations. Despite the competitive dynamics, the market faces challenges such as high R&D costs, regulatory hurdles, and concerns over the long-term environmental impact of nanoparticles. As a result, firms that can navigate these complexities, align with regulatory standards, and provide sustainable, cost-effective solutions are likely to emerge as leaders. Overall, the market's future will be shaped by a blend of technological innovation, regulatory compliance, and a strong shift toward environmentally conscious agriculture.
Recent Developments:
- In March 2024, Insecticides (India) Limited introduced a new patented insecticide turner, expanding its product portfolio to enhance pest control solutions. This innovation aims to provide more effective and targeted crop protection, supporting the company's commitment to agricultural sustainability and improving farmers' yields.
- In the same month, BASF launched Efficon, a new insecticide designed to meet the growing demand for more efficient pest control solutions. Efficient combines advanced technology and environmental considerations, positioning BASF as a leader in the development of sustainable agricultural products.
- In November 2023, Insecticides (India) Ltd. further strengthened its market presence by launching four new crop protection products. These products are designed to offer farmers a wider range of options for safeguarding their crops against various pests and diseases, ultimately improving productivity and crop quality.
- Also, in November 2023, FMC introduced a new insecticide/fungicide premix product, combining insect control and fungal protection benefits. This product is designed to provide dual-action crop protection, offering growers an efficient solution for managing pest and disease challenges in a single application.
Market Concentration & Characteristics:
The nanopesticide market is characterized by moderate to high concentration, with a few large multinational companies dominating the landscape while numerous smaller players contribute to innovation and niche solutions. Major agrochemical corporations like BASF, Syngenta, and DowDuPont hold a significant share of the market, driven by their extensive resources, robust R&D capabilities, and established distribution channels. These industry giants are increasingly incorporating nanotechnology into their existing pest control portfolios, aiming to capture the growing demand for more efficient, eco-friendly alternatives to traditional pesticides. However, the market is also witnessing the emergence of specialized startups and mid-sized companies that focus on developing cutting-edge nanopesticide formulations, often targeting organic farming or precision agriculture. These smaller companies benefit from greater agility and the ability to respond more rapidly to market demands, but they face challenges related to high R&D costs and regulatory hurdles. Despite the market concentration at the top, competition remains fierce, as companies must balance technological innovation with the need for regulatory compliance and consumer demand for sustainable products. The market's characteristics also include significant investment in research and development, particularly in countries with strong agricultural sectors such as the U.S., EU, and parts of Asia Pacific. As the technology matures and regulatory frameworks evolve, the market is expected to become more competitive, with increasing collaboration between large corporations and smaller tech-focused firms to drive the next wave of growth and innovation in nanopesticides.
Report Coverage:
This report provides a comprehensive analysis of the global nanopesticide market, covering key trends, market dynamics, and growth drivers from 2024 to 2032. It includes an in-depth examination of market segmentation by product type, technology, end-user, and region. The report explores the current landscape of the nanopesticide industry, highlighting major players such as BASF, Syngenta, and DowDuPont, as well as emerging companies innovating in the nanotechnology space. Key drivers of growth, including the demand for sustainable agriculture practices, the rise of precision farming technologies, and increasing regulatory pressures on traditional pesticides, are thoroughly analyzed. The report also assesses regional dynamics, with a particular focus on North America, Europe, and Asia Pacific, which together represent the largest and fastest-growing markets. Additionally, it addresses the challenges facing the industry, such as regulatory hurdles, high R&D costs, and concerns over environmental and safety implications of nanomaterials. Competitive strategies, technological advancements, and future growth opportunities are discussed to provide a holistic view of the market’s potential. This report also includes insights into market concentration, characteristics, and the competitive landscape, helping stakeholders understand the competitive dynamics and market positioning of key players. It concludes with a forward-looking perspective, offering strategic recommendations for industry participants aiming to capitalize on the growth opportunities in the nanopesticide market.
Future Outlook:
- The nanopesticide market will continue to expand as farmers seek more sustainable and efficient pest management solutions.
- Increased adoption of precision agriculture technologies, such as drones and sensors, will drive the demand for nanopesticides, enabling more precise application.
- Governments around the world are likely to strengthen regulations promoting eco-friendly pesticides, boosting the growth of nanopesticides as a safer alternative.
- Ongoing advancements in nanotechnology will enhance the formulation and effectiveness of nanopesticides, improving their performance in pest control.
- Rising consumer demand for organic and sustainably grown produce will encourage farmers to adopt more environmentally friendly pest management strategies, including nanopesticides.
- As pest resistance to traditional pesticides grows, nanopesticides will become an essential tool for managing resistant pest populations.
- The growing global focus on food security and higher agricultural yields will further support the adoption of advanced pest control methods like nanopesticides.
- Investments in agricultural R&D will foster innovation, leading to the development of new nanopesticide formulations tailored to specific crops and pests.
- Regional markets, particularly in Asia Pacific, will experience significant growth due to the increasing need for crop protection in major agricultural economies like China and India.
- Collaboration between agricultural companies and technology providers will accelerate the integration of nanopesticides into modern farming practices, ensuring long-term market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Nanotechnology
Ongoing innovations in nanotechnology are enabling the development of highly targeted and efficient nanopesticide formulations, which improve pest control effectiveness while reducing chemical usage and environmental impact.
Regulatory Support and Government Initiatives
Stricter regulations on traditional pesticides and government-backed programs promoting sustainable agriculture are accelerating the adoption of nanopesticides as safer, eco-friendly alternatives.
Rising Adoption of Precision Agriculture
The integration of precision agriculture tools such as drones, sensors, and data analytics allows for more accurate application of nanopesticides, minimizing waste and maximizing crop protection efficiency.
Growing Environmental Awareness and Sustainability
Increasing concerns about the environmental and health impacts of conventional pesticides are driving demand for nanopesticides, which offer lower toxicity, reduced runoff, and better targeting of pests.
Changing Consumer Preferences for Organic and Sustainable Products
The surge in demand for organic and sustainably produced food is pushing farmers to adopt pest management solutions like nanopesticides that align with organic farming principles and reduce reliance on harmful chemicals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the nanopesticide market?
What are the key drivers behind the growth of the nanopesticide market?
How do nanopesticides benefit agriculture compared to traditional pesticides?
What role does precision agriculture play in the nanopesticide market?
Which regions are expected to lead the nanopesticide market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Crop Farming
- 1.2.2 Horticulture
- 1.2.3 Forestry
- 1.2.4 Organic Farming
- 1.2.5 Landscaping & Turf Management
- 1.3 By Technology
- 1.3.1 Chemical Synthesis
- 1.3.2 Biological Synthesis
- 1.3.3 Physical Methods
- 1.4 By Product Type
- 1.4.1 Nanoemulsions
- 1.4.2 Nanoparticles
- 1.4.3 Nanostructured Materials
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 735 million → 2032: USD 2,082 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Nanopesticide Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Nanopesticide Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Nanopesticide Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Nanopesticide Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Nanopesticide Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Nanopesticide Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Nanopesticide Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Nanopesticide Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 735 million → 2032: USD 2,082 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Nanopesticide Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Crop Farming
- 12.3.7.2 Horticulture
- 12.3.7.3 Forestry
- 12.3.7.4 Organic Farming
- 12.3.7.5 Landscaping & Turf Management
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Chemical Synthesis
- 12.4.7.2 Biological Synthesis
- 12.4.7.3 Physical Methods
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Nanoemulsions
- 12.5.7.2 Nanoparticles
- 12.5.7.3 Nanostructured Materials
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Nanopesticide End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Nanopesticide Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Nanopesticide Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Nanopesticide Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Syngenta
- 18.4 DowDuPont
- 18.5 Bayer AG
- 18.6 Corteva
- 18.7 Marrone Bio Innovations
- 18.8 Andermatt Biocontrol AG
- 18.9 Stockton Biotechnologies
- 18.10 BioWorks, Inc.
- 18.11 Camson Biotechnologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

