
Market Overview
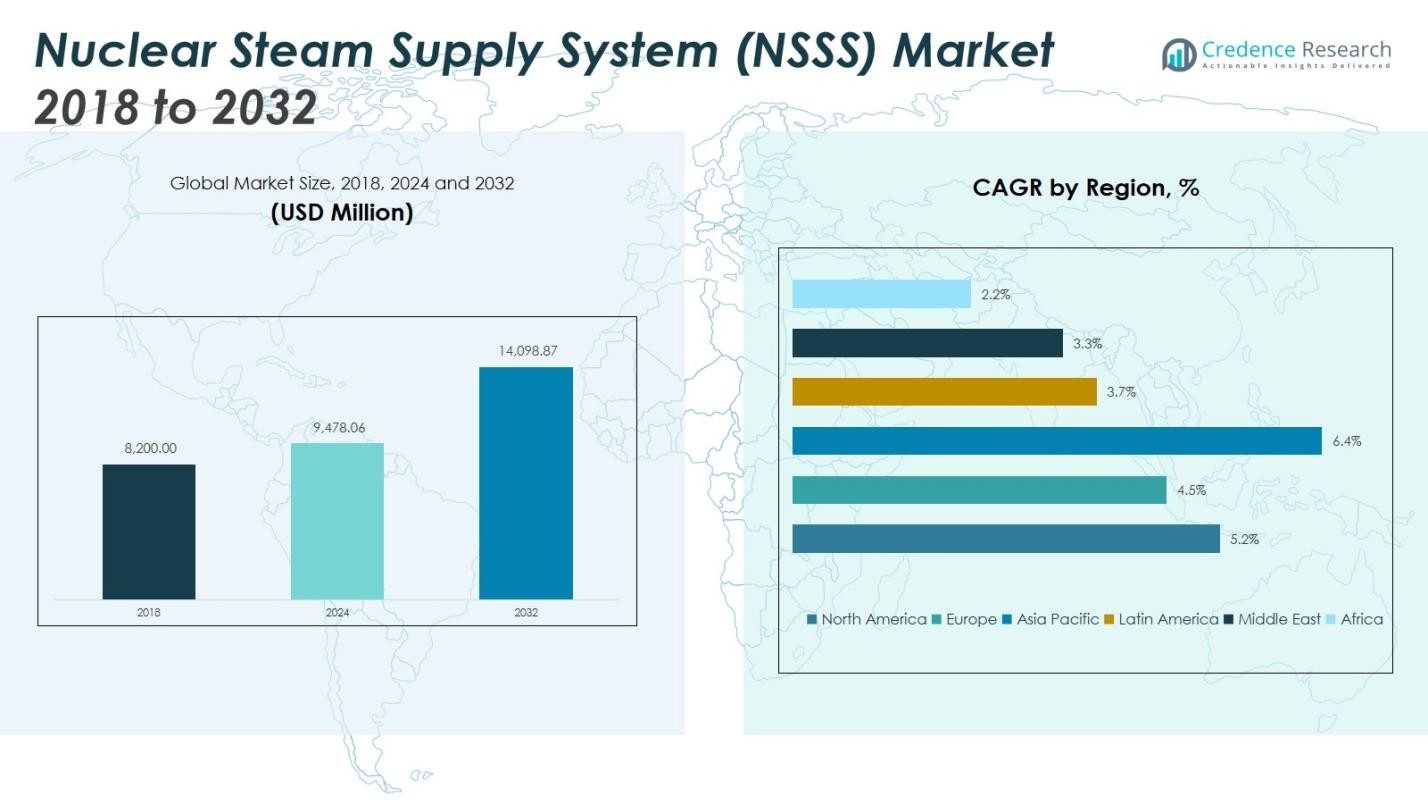
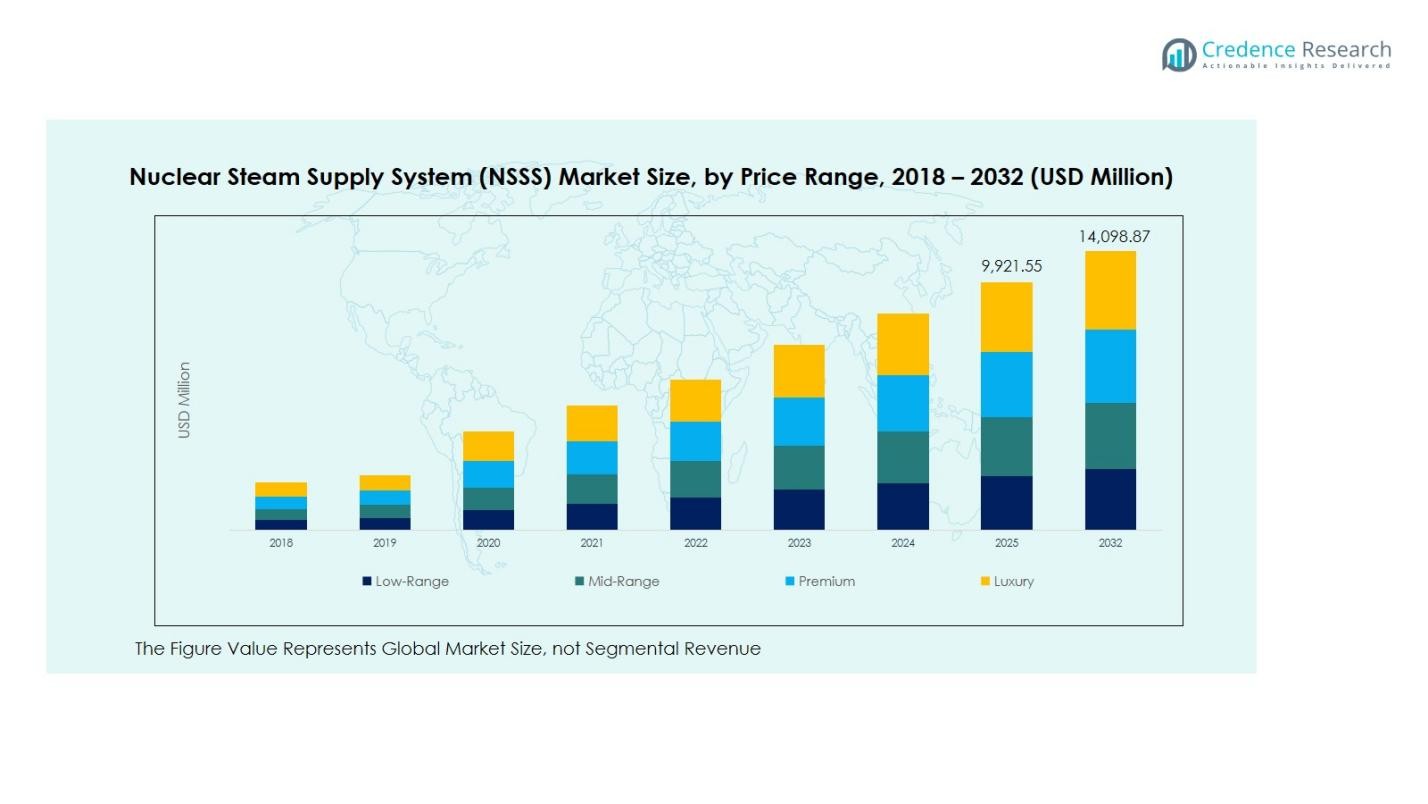
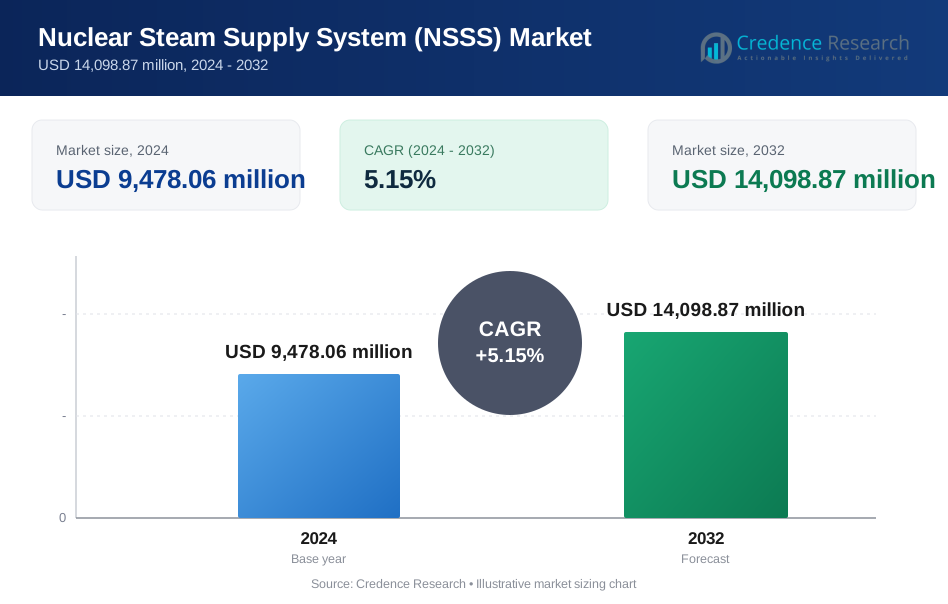
The Nuclear Steam Supply System (NSSS) Market size was valued at USD 8,200.00 Million in 2018, increased to USD 9,478.06 Million in 2024, and is anticipated to reach USD 14,098.87 Billion by 2032, at a CAGR of 5.15% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Nuclear Steam Supply System (NSSS) Market Size 2024 | USD 9,478.06 Million |
| Nuclear Steam Supply System (NSSS) Market, CAGR | 5.15% |
| Nuclear Steam Supply System (NSSS) Market Size 2032 | USD 14,098.87 Million |
The Nuclear Steam Supply System (NSSS) Market is dominated by key players such as Westinghouse Electric Company, General Electric (GE) Hitachi Nuclear Energy, Mitsubishi Heavy Industries, Korea Electric Power Corporation (KEPCO), and Rosatom State Atomic Energy Corporation. These companies lead the market due to their extensive experience, technological expertise, and large-scale manufacturing capabilities. North America holds the largest market share, approximately 28%, driven by investments in nuclear infrastructure and plant life extensions. Europe follows with a 26% market share, influenced by nuclear energy's role in the region's sustainability goals. Asia Pacific is the fastest-growing region, accounting for 25% of the market, driven by rapid nuclear energy developments in China and India. These regions, alongside emerging markets, are fueling the demand for advanced NSSS systems as part of the global shift toward cleaner and more reliable energy sources.
 Market Insights
- The Nuclear Steam Supply System (NSSS) Market was valued at USD 9,478.06 million in 2024 and is projected to reach USD 14,098.87 million by 2032, growing at a CAGR of 5.15%.
- Increasing global demand for clean and reliable energy is a major driver for the market, with nuclear energy gaining prominence as a stable, low-carbon power source.
- Technological advancements such as the deployment of small modular reactors (SMRs) and improvements in reactor safety systems are key trends boosting the market.
- High capital and operational costs, along with regulatory and safety concerns, remain significant restraints, limiting faster growth in some regions.
- North America holds the largest share of the market at 28%, followed by Europe at 26%, while Asia Pacific is growing rapidly, accounting for 25% of the market, driven by expanding nuclear energy investments in China and India.
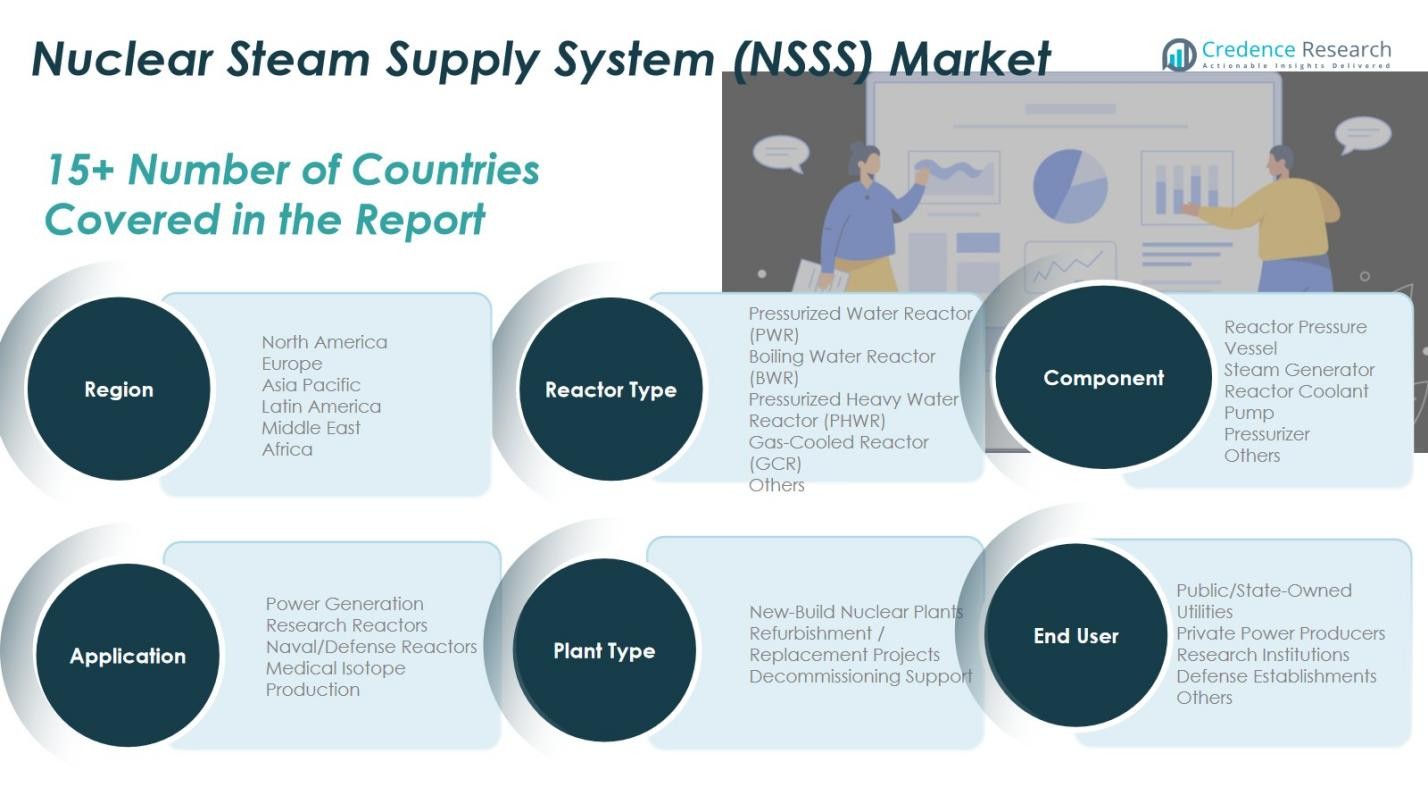
Market Segmentation Analysis:
By Reactor Type
The Pressurized Water Reactor (PWR) segment dominates the NSSS market, holding a significant share of 60%. PWRs are the most widely deployed reactor type globally, favored for their safety features and operational maturity. The growth of this segment is driven by the rising global demand for reliable, clean energy and ongoing life-extension programs for existing PWR plants. Other reactor types like Boiling Water Reactor (BWR) and Pressurized Heavy Water Reactor (PHWR) follow, with smaller shares due to regional preferences and specific fuel capabilities. Gas-Cooled Reactors (GCR) and Others hold niche market shares, driven by experimental and advanced nuclear technology projects.
- For instance, for PHWRs, L&T Heavy Engineering provides critical services such as life extension through coolant channel replacement and in-service inspections, supporting long-term operation of these reactors.
By Application
The Power Generation segment is the dominant application for NSSS systems, accounting for more than 85% of the market share. This is largely due to the critical role nuclear power plays in providing clean and reliable electricity across the globe. The demand for low-carbon power generation drives the expansion of nuclear power plants. Research Reactors, Naval/Defense Reactors, and Medical Isotope Production hold smaller shares, with research and defense reactors primarily serving niche markets such as scientific research, military applications, and isotope production for medical uses.
- For instance, nuclear power plants generate nearly 10% of the global electricity and contribute about a quarter of all low-carbon electricity, underscoring their significance in low-carbon power generation efforts.
By End-User
Public/State-Owned Utilities dominate the NSSS market with an overwhelming share of around 85%. This segment is driven by the ownership of large-scale nuclear power plants by state or government entities, which are the main operators of nuclear facilities worldwide. Private Power Producers represent a growing but smaller share (5-10%), as more private sector investments in nuclear energy emerge. Research Institutions and Defense Establishments each account for a minor share, focusing on specialized reactor designs and systems for academic, military, and security purposes.
Key Growth Drivers
Increasing Demand for Clean and Reliable Energy
The growing global emphasis on reducing carbon emissions is a primary driver for the Nuclear Steam Supply System (NSSS) market. As nations strive to meet sustainability targets, nuclear energy is gaining prominence as a stable and low-carbon source of power. This is particularly relevant in regions with rising electricity demand and limited alternative clean energy options. The urgency to transition away from fossil fuels and the need for reliable, baseload power further support the expansion of nuclear energy, driving substantial demand for NSSS systems.
- For instance, GE Steam Power signed a contract with Bharat Heavy Electricals Limited (BHEL) to supply three nuclear steam turbines for NPCIL's domestic nuclear program, contributing to 8.4 GW of CO2-free electricity enough to power over 14 million homes.
Deployment of Advanced Nuclear Technologies
The deployment of advanced and small modular reactors (SMRs) is accelerating the growth of the NSSS market. SMRs offer improved safety, lower upfront costs, and the flexibility to be deployed in smaller or remote locations, expanding the market potential. As these technologies mature and gain regulatory approval, they open up new avenues for nuclear energy adoption, particularly in countries with a growing energy demand. This trend is boosting investments in NSSS, as these reactors require innovative and more efficient steam supply systems for optimal operation.
- For instance, NuScale Power Corporation’s NuScale Power Module generates 77 megawatts per unit and can be combined into plants producing up to 924 MWe, allowing scalable and factory-fabricated solutions that simplify deployment.
Nuclear Plant Life Extension and Refurbishment
A significant driver of the NSSS market is the ongoing refurbishment and life-extension programs for aging nuclear power plants. Many reactors worldwide, particularly in North America and Europe, are reaching the end of their operational life and are undergoing modernization. These upgrades often involve replacing or upgrading critical components, such as the NSSS, to improve efficiency and extend plant life. As a result, there is increasing demand for NSSS systems to support the longevity of existing nuclear fleets, maintaining market stability and expansion.
 Key Trends & Opportunities
Integration of Hybrid Energy Systems
The integration of nuclear power with renewable energy sources, such as wind and solar, is becoming an emerging trend in the NSSS market. Hybrid energy systems, combining nuclear with renewables, offer enhanced grid stability and efficiency, addressing the intermittent nature of renewable power. This integration creates new opportunities for NSSS suppliers to develop systems that can seamlessly work with these hybrid setups. As governments continue to invest in renewable energy infrastructure, the demand for hybrid solutions incorporating NSSS will likely increase, providing a significant market opportunity.
- For instance, the U.S. National Renewable Energy Laboratory (NREL) and Idaho National Laboratory demonstrated a hybrid power plant combining a nuclear reactor, solar arrays, lithium-ion batteries, and hydrogen electrolyzers that seamlessly adjusted to fluctuations in solar power, enhancing grid reliability.
Rising Investment in Nuclear Safety and Technology Innovation
With an increasing focus on nuclear safety, there is growing investment in the development of advanced NSSS systems that offer improved safety features, such as passive safety systems and automated emergency response mechanisms. Technological innovation is another significant opportunity, with ongoing research into advanced materials, reactor designs, and cooling technologies. These innovations aim to make nuclear power more efficient, safer, and more economically viable, thus driving demand for next-generation NSSS solutions. Companies investing in these innovations will benefit from growing demand across developed and emerging markets.
- For instance, Westinghouse Electric has deployed its AP1000 reactor design with fully passive safety systems, capable of cooling the core for 72 hours without operator intervention or external power, and these have been operational at Sanmen and Haiyang plants in China since 2018.
Key Challenges
High Capital and Operational Costs
One of the major challenges facing the NSSS market is the high capital and operational costs associated with nuclear power plants. Building and maintaining nuclear facilities is a significant financial burden, with high upfront investments in reactor construction, licensing, and infrastructure. The operational costs, including safety and regulatory compliance, add further strain. This financial barrier makes nuclear energy less attractive compared to other energy sources like natural gas and renewables, limiting the pace at which new plants are constructed and affecting NSSS demand in some regions.
Regulatory and Safety Concerns
Regulatory hurdles and safety concerns remain one of the key challenges for the NSSS market. Nuclear energy is heavily regulated, and navigating the complex licensing and approval processes can be time-consuming and costly. Public perception of nuclear safety, especially in the wake of past incidents like Fukushima, continues to pose challenges for the industry. As governments and regulatory bodies impose stricter safety standards and compliance requirements, this may increase costs and delays, affecting market growth and hindering the expansion of NSSS deployments.
 Regional Analysis
North America
North America holds a significant market share of 28% in the Nuclear Steam Supply System (NSSS) market. The market size was USD 2,935.60 million in 2018, with projections to reach USD 3,351.39 million by 2024 and USD 4,978.34 million by 2032, growing at a CAGR of 5.2%. The region's growth is largely driven by robust investments in nuclear energy infrastructure, including the life extension of existing plants and new nuclear projects, as part of the clean energy transition in the United States and Canada. As such, the demand for NSSS systems is expected to remain strong throughout the forecast period.
Europe
Europe commands a market share of 26% of the global NSSS market. The market was valued at USD 2,469.84 million in 2018 and is expected to grow to USD 2,757.86 million by 2024, reaching USD 3,904.72 million by 2032, with a CAGR of 4.5%. Nuclear power's role in the region's energy mix remains critical, with significant investments in both the refurbishment of aging plants and the development of new nuclear reactors. This continued reliance on nuclear energy for baseload power and sustainability goals will fuel demand for NSSS systems in Europe.
Asia Pacific
Asia Pacific is the fastest-growing region in the NSSS market, with a projected market share of 25% by 2024. The market size was USD 2,089.36 million in 2018, expected to reach USD 2,517.81 million by 2024, and USD 4,118.29 million by 2032, growing at a robust CAGR of 6.4%. China, India, and Japan are leading the charge in nuclear energy development, particularly in China, where large-scale nuclear projects are expanding rapidly. This strong regional growth is fueled by increasing energy demand, industrialization, and the need for clean energy sources.
Latin America
Latin America holds a smaller share of the NSSS market, contributing 4% of the global market share. The market size in 2018 was USD 344.40 million, projected to increase to USD 392.30 million by 2024, and USD 519.83 million by 2032, with a CAGR of 3.7%. Nuclear energy is still in its early stages in many Latin American countries, but growing interest in diversifying energy sources is pushing forward nuclear power projects, especially in Brazil and Argentina. As these nations expand their nuclear infrastructure, the NSSS market in Latin America is expected to see steady growth.
Middle East
The Middle East holds a smaller market share of 3% in the global NSSS market. Valued at USD 229.60 million in 2018, the market is projected to grow to USD 242.58 million in 2024, reaching USD 311.66 million by 2032, at a CAGR of 3.3%. Nuclear energy adoption is increasing in the region, particularly in countries like the UAE and Saudi Arabia, as part of their energy diversification strategies. Despite its smaller share, the market for NSSS systems in the Middle East is set to grow steadily as these countries continue to invest in nuclear infrastructure.
Africa
Africa accounts for the smallest market share of 2% in the global NSSS market. The market was valued at USD 131.20 million in 2018 and is expected to grow to USD 216.14 million by 2024, reaching USD 266.04 million by 2032, with a CAGR of 2.2%. South Africa remains the leader in nuclear energy generation in the region, but other African nations are starting to explore nuclear power to address energy security challenges. As these countries invest in nuclear infrastructure, demand for NSSS systems will gradually rise, contributing to modest market growth in the coming years.
Market Segmentations:
By Reactor Type:
- Pressurized Water Reactor (PWR)
- Boiling Water Reactor (BWR)
- Pressurized Heavy Water Reactor (PHWR)
- Gas-Cooled Reactor (GCR)
- Others
By Application:
- Power Generation
- Research Reactors
- Naval/Defense Reactors
- Medical Isotope Production
By End-user:
- Public/State-Owned Utilities
- Private Power Producers
- Research Institutions
- Defense Establishments
- Others
By Component:
- Reactor Pressure Vessel
- Steam Generator
- Reactor Coolant Pump
- Pressurizer
- Others
By Plant Type:
- New-Build Nuclear Plants
- Refurbishment / Replacement Projects
- Decommissioning Support
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive analysis in the Nuclear Steam Supply System (NSSS) market reveals a dynamic and evolving landscape, with key players such as Westinghouse Electric Company, General Electric (GE) Hitachi Nuclear Energy, Mitsubishi Heavy Industries, Korea Electric Power Corporation (KEPCO), and Rosatom State Atomic Energy Corporation leading the charge. These companies dominate the market due to their extensive experience, strong technological expertise, and large-scale manufacturing capabilities. Additionally, these players are at the forefront of innovations in nuclear reactor designs, safety features, and energy efficiency improvements, contributing to the growth of the NSSS market. The market is characterized by a mix of established industry giants and emerging players, especially in regions such as Asia Pacific, where new entrants are gaining traction. Strategic partnerships, mergers, and acquisitions are common among key players to strengthen their position in the market, expand their geographic reach, and enhance product offerings. As the demand for nuclear energy grows, competition is expected to intensify, with a focus on reducing costs, improving reactor performance, and ensuring regulatory compliance.
Key Player Analysis
- Westinghouse Electric Company
- General Electric (GE) Hitachi Nuclear Energy
- Mitsubishi Heavy Industries
- Korea Electric Power Corporation (KEPCO)
- China National Nuclear Corporation (CNNC)
- Rosatom State Atomic Energy Corporation
- Doosan Heavy Industries & Construction
- Babcock & Wilcox Enterprises
- Toshiba Energy Systems & Solutions
Recent Developments
- In October 2025, the U.S. Government, Brookfield Asset Management and Cameco Corporation formed a strategic partnership with Westinghouse to deliver new nuclear reactors using its NSSS technology.
- In March 2025, Westinghouse Electric Company signed MoUs with six Canadian suppliers (in Saskatchewan) to support its new build NSSS and AP1000 reactor projects.
- In February 2025, Siemens Energy and Rolls‑Royce SMR signed an exclusive partnership agreement in which Siemens Energy will be the global turbine systems partner (steam turbines, generators and auxiliary systems) for Rolls‑Royce’s small modular reactors (SMRs).
Report Coverage
The research report offers an in-depth analysis based on Reactor Type, Application, Component, Plant Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The NSSS market is expected to witness steady growth driven by increasing global demand for clean and reliable energy.
- Technological advancements in nuclear reactor designs, including small modular reactors (SMRs), will play a pivotal role in shaping market dynamics.
- Investment in nuclear energy infrastructure, especially in Asia Pacific and North America, is anticipated to accelerate in the coming years.
- The shift towards nuclear energy as a sustainable alternative to fossil fuels will support long-term market expansion.
- Regulatory frameworks will continue to evolve, ensuring higher safety standards, which could drive demand for advanced NSSS systems.
- The rise in nuclear power plant life extension and refurbishment projects will contribute significantly to NSSS market growth.
- The growing interest in hybrid energy systems combining nuclear and renewable energy sources will open new opportunities in the market.
- As new nuclear plants are commissioned, the demand for advanced NSSS components, such as steam generators and reactor pressure vessels, will increase.
- Strategic collaborations and partnerships between nuclear energy companies and governments will enhance market development and regional reach.
- The market will face challenges related to high capital costs and regulatory complexities, which may impact the pace of growth in certain regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Clean and Reliable Energy
As countries seek to reduce carbon emissions and transition away from fossil fuels, nuclear energy is gaining prominence as a stable, low-carbon power source. This shift is driving substantial demand for advanced Nuclear Steam Supply Systems to support new and existing nuclear power plants.
Deployment of Advanced Nuclear Technologies
The adoption of small modular reactors (SMRs) and improvements in reactor safety systems are expanding the market. These technologies offer enhanced safety, lower upfront costs, and flexibility, making nuclear energy more accessible and boosting investments in NSSS.
Nuclear Plant Life Extension and Refurbishment
Aging nuclear fleets, especially in North America and Europe, are undergoing modernization and life-extension programs. These initiatives require replacement or upgrading of critical NSSS components, supporting ongoing market growth.
Integration of Hybrid Energy Systems
The trend toward combining nuclear with renewable energy sources to create hybrid systems is increasing demand for NSSS solutions that can operate flexibly alongside intermittent renewables, enhancing grid stability and efficiency.
Rising Investment in Nuclear Safety and Technology Innovation
Growing regulatory focus on safety and ongoing innovation in reactor designs and materials are driving the development and adoption of next-generation NSSS systems, making nuclear power safer and more economically viable.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Nuclear Steam Supply System (NSSS) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Nuclear Steam Supply System (NSSS) Market projected to grow between 2025 and 2032?
Which Nuclear Steam Supply System (NSSS) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Nuclear Steam Supply System (NSSS) Market?
Who are the leading companies in the Nuclear Steam Supply System (NSSS) Market?
Which region commanded the largest share of the Nuclear Steam Supply System (NSSS) Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Public/State-Owned Utilities
- 1.2.2 Private Power Producers
- 1.2.3 Research Institutions
- 1.2.4 Defense Establishments
- 1.2.5 Others
- 1.3 By Component
- 1.3.1 Reactor Pressure Vessel
- 1.3.2 Steam Generator
- 1.3.3 Reactor Coolant Pump
- 1.3.4 Pressurizer
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Power Generation
- 1.4.2 Research Reactors
- 1.4.3 Naval/Defense Reactors
- 1.4.4 Medical Isotope Production
- 1.5 By Reactor Type
- 1.5.1 Pressurized Water Reactor (PWR)
- 1.5.2 Boiling Water Reactor (BWR)
- 1.5.3 Pressurized Heavy Water Reactor (PHWR)
- 1.5.4 Gas-Cooled Reactor (GCR)
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,478.06 million → 2032: USD 14,098.87 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Nuclear Steam Supply System (NSSS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Nuclear Steam Supply System (NSSS) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Nuclear Steam Supply System (NSSS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Nuclear Steam Supply System (NSSS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Nuclear Steam Supply System (NSSS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Nuclear Steam Supply System (NSSS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Nuclear Steam Supply System (NSSS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Nuclear Steam Supply System (NSSS) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,478.06 million → 2032: USD 14,098.87 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Nuclear Steam Supply System (NSSS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Public/State-Owned Utilities
- 12.3.7.2 Private Power Producers
- 12.3.7.3 Research Institutions
- 12.3.7.4 Defense Establishments
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Reactor Pressure Vessel
- 12.4.7.2 Steam Generator
- 12.4.7.3 Reactor Coolant Pump
- 12.4.7.4 Pressurizer
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Power Generation
- 12.5.7.2 Research Reactors
- 12.5.7.3 Naval/Defense Reactors
- 12.5.7.4 Medical Isotope Production
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Reactor Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pressurized Water Reactor (PWR)
- 12.6.7.2 Boiling Water Reactor (BWR)
- 12.6.7.3 Pressurized Heavy Water Reactor (PHWR)
- 12.6.7.4 Gas-Cooled Reactor (GCR)
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Nuclear Steam Supply System (NSSS) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Nuclear Steam Supply System (NSSS) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Nuclear Steam Supply System (NSSS) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Nuclear Steam Supply System (NSSS) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Westinghouse Electric Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 General Electric (GE) Hitachi Nuclear Energy
- 18.4 Mitsubishi Heavy Industries
- 18.5 Korea Electric Power Corporation (KEPCO)
- 18.6 Rosatom State Atomic Energy Corporation
- 18.7 China National Nuclear Corporation (CNNC)
- 18.8 Doosan Heavy Industries & Construction
- 18.9 Babcock & Wilcox Enterprises
- 18.10 Toshiba Energy Systems & Solutions
- 18.11 Siemens Energy
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

