
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Orthokeratology Lenses Market Size 2024 | USD 857.8 Million |
| Orthokeratology Lenses Market, CAGR | 15.82% |
| Orthokeratology Lenses Market Size 2032 | USD 2,777.5 Million |
Market Overview
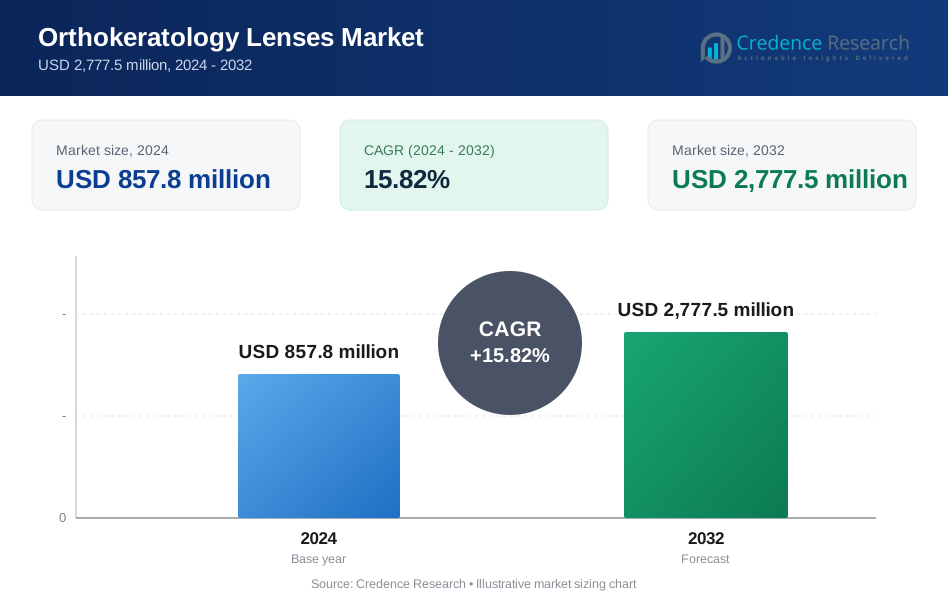
The Orthokeratology Lenses Market is projected to grow from USD 857.8 million in 2024 to USD 2,777.5 million by 2032, at a compound annual growth rate (CAGR) of 15.82%.
The Orthokeratology Lenses market is driven by the rising prevalence of myopia and the increasing awareness of non-surgical vision correction options. Additionally, advancements in lens technology enhance comfort and effectiveness, attracting more users. The growing adoption of digital devices contributes to higher rates of refractive errors, further fueling demand. Key trends include a shift towards personalized lens designs and increased investment in research and development by manufacturers to innovate product offerings. Moreover, supportive government initiatives promoting eye care awareness are expected to bolster market growth in the coming years, creating a favorable environment for industry expansion.
The geographical analysis of the Orthokeratology Lenses market reveals significant growth across regions such as North America and Asia-Pacific. North America holds a substantial market share due to advanced healthcare infrastructure and increasing awareness of myopia control solutions. In contrast, the Asia-Pacific region is rapidly expanding, driven by rising myopia rates among children and greater accessibility to eye care services. Key players in this market include Bausch & Lomb Inc., Johnson & Johnson Vision Care, Inc., CooperVision, and Euclid Systems Corp., all of which are actively investing in innovative products to capture a larger share of the growing demand for orthokeratology lenses.
Market Drivers
Rising Prevalence of Refractive Errors
The Orthokeratology Lenses market is significantly driven by the rising prevalence of refractive errors, particularly myopia and astigmatism. The increasing incidence of nearsightedness, especially among children, highlights the urgent need for effective vision correction options. For instance, the World Health Organization reports that globally, at least 2.2 billion people have a near or distance vision impairment, with refractive errors being a leading cause. Moreover, orthokeratology’s capability to effectively correct astigmatism further expands its potential market, making it a valuable solution for a wider demographic of patients seeking non-invasive treatments.
Advancements in Lens Technology
Recent advancements in lens technology have also played a crucial role in propelling the orthokeratology market. The development of more biocompatible and comfortable materials has enhanced patient experience, reducing discomfort associated with long-term wear. For instance, advancements in diamond lathes, next-generation topographers, and new higher-Dk fluorosilicone acrylate materials have set the stage for rapid development in orthokeratology. Additionally, customized designs that offer precise correction and better fit lead to increased patient satisfaction, making orthokeratology a preferred choice for many individuals looking for effective vision correction solutions.
Benefits Over Traditional Vision Correction
Orthokeratology presents distinct advantages over traditional vision correction methods, such as glasses or permanent procedures like LASIK. This reversible alternative allows patients to enjoy temporary vision correction without the commitment of surgical options. Furthermore, studies indicate that orthokeratology can slow the progression of myopia in children, providing a proactive approach to managing refractive errors. For instance, research suggests that orthokeratology can reduce the rate of myopic progression by approximately 45-50% compared to traditional single-vision corrective lenses. Many patients also find orthokeratology more convenient than daily contact lenses or glasses, contributing to its growing popularity.
Increased Awareness and Acceptance
Increasing awareness and acceptance of orthokeratology significantly drive market growth. Education and marketing efforts aimed at both patients and eye care professionals are fostering greater understanding and adoption of this innovative treatment. For instance, extensive research efforts and lens design advancements have led to a resurgence in the popularity of orthokeratology. Additionally, celebrity endorsements advocating for orthokeratology can influence public opinion and encourage more individuals to explore this effective vision correction option. As awareness continues to rise, the market is expected to experience sustained expansion.
Market Trends
Increasing Adoption and Market Accessibility
The Orthokeratology Lenses market is witnessing increasing adoption driven by growing awareness among the population about the benefits of this innovative vision correction method. For instance, a survey conducted among more than 500 U.S. eye care professionals revealed that 56% of respondents actively fitting orthokeratology lenses anticipate market growth within the next 12 months. As more individuals learn about how orthokeratology can effectively manage refractive errors and provide temporary vision correction without surgical intervention, adoption rates are steadily rising. Additionally, the expanded availability of orthokeratology treatments across various regions is contributing significantly to market growth. Improved access to these lenses, coupled with educational initiatives targeting both patients and eye care professionals, fosters a greater understanding of the technology. This heightened awareness creates a positive feedback loop, encouraging even more individuals to consider orthokeratology as a viable option for addressing their vision needs. Furthermore, the efforts to improve accessibility in developing regions, especially in countries with large populations and rising disposable incomes, position orthokeratology as an increasingly attractive choice in the global market.
Technological Advancements and Focus on Myopia Control
Technological advancements are pivotal in shaping the future of the orthokeratology market, particularly with the emergence of smart lenses that incorporate integrated technology, such as sensors or therapeutic capabilities. These innovations not only enhance the user experience but also hold significant potential for future growth in the industry. Customization plays a key role as well, with tailored lenses offering precise correction and improved fit, leading to heightened patient satisfaction. In conjunction with these advancements, there is a growing focus on myopia control, particularly among younger patients. Orthokeratology is increasingly recognized for its ability to slow the progression of myopia in children, addressing a critical public health concern. Ongoing research into the long-term benefits of myopia control using orthokeratology further solidifies its position in the market, as parents and eye care professionals alike seek effective solutions for managing refractive errors in the younger population. As both technological innovations and a focus on myopia control continue to evolve, they are expected to drive demand and bolster the overall growth of the orthokeratology market.
Market Challenges Analysis
Initial Costs and Treatment Commitment
One of the primary challenges facing the Orthokeratology Lenses market is the initial cost associated with these specialized lenses. Compared to traditional vision correction methods, such as glasses or contact lenses, orthokeratology can require a higher investment, which may act as a barrier for some patients, particularly those with limited budgets. For instance, a study analyzing 623 cases of contact lens-related keratitis in the U.S. from 2015-2019 found that orthokeratology lens use was associated with the highest risk and worst visual outcomes compared to other types of contact lenses. This financial consideration can deter potential users from exploring orthokeratology, despite its long-term benefits and effectiveness. Additionally, orthokeratology necessitates a time commitment, as achieving desired results requires consistent wear of the lenses over a specified period. Adherence to this treatment regimen can be challenging for some patients, leading to frustration and potentially compromising the effectiveness of the therapy. As a result, both the financial and time commitments may limit the market's growth and adoption among certain demographics.
Complications and Regulatory Challenges
Potential complications associated with orthokeratology lenses present another significant challenge. Although rare, issues such as corneal edema can occur, particularly among patients who overwear their lenses or have pre-existing eye conditions. Other complications, including discomfort, dryness, and allergic reactions, may also arise, contributing to patient hesitancy and affecting overall satisfaction with the treatment. Furthermore, regulatory hurdles complicate the landscape for orthokeratology. Obtaining regulatory approval for these lenses can be both time-consuming and costly, which poses a barrier to market entry for manufacturers. Additionally, the varying regulatory requirements across different countries can further complicate the approval process, limiting the availability of orthokeratology treatments globally. This lack of standardization in regulations can hinder the expansion of the market, making it essential for manufacturers to navigate complex approval processes while ensuring compliance with diverse standards. Overall, the combination of potential complications and regulatory challenges creates a multifaceted landscape that may impede the growth and widespread adoption of orthokeratology lenses in the competitive vision correction market.
Market Segmentation Analysis:
By Type:
The Orthokeratology Lenses market is primarily segmented by type into Overnight Ortho-K Lenses and Daytime Ortho-K Lenses. Overnight Ortho-K Lenses are designed for overnight wear, allowing patients to enjoy clear vision throughout the day without the need for corrective eyewear. This segment is gaining traction among individuals seeking a non-invasive solution for refractive errors, particularly myopia and astigmatism. In contrast, Daytime Ortho-K Lenses are intended for use during waking hours, appealing to patients who prefer flexibility in their lens-wearing schedule. The demand for these lenses is fueled by an increasing awareness of the benefits of orthokeratology and advancements in lens technology, which enhance comfort and effectiveness. As both types of lenses cater to different user preferences, the market is expected to expand in response to diverse patient needs and lifestyle choices.
By Age Group:
The age group segmentation of the Orthokeratology Lenses market includes children and adults, each with unique drivers and preferences. Children represent a significant segment, as the rising prevalence of myopia in younger populations prompts parents to seek effective and non-surgical corrective solutions. Orthokeratology is particularly appealing to this demographic due to its ability to slow the progression of myopia, making it a proactive choice for parents concerned about their children's eye health. Conversely, the adult segment also shows considerable growth potential, with many individuals seeking alternatives to traditional vision correction methods, such as glasses and contact lenses. Adults appreciate the convenience and flexibility that orthokeratology offers, particularly for those with active lifestyles. As awareness of orthokeratology continues to increase and the benefits for both children and adults become more widely recognized, the market is poised for significant growth, driven by the unique needs and preferences of these two age groups.
Segments:
Based on Type
- Overnight Ortho-K Lens
- Daytime Ortho-K Lens
Based on Age Group
- Children
- Adults
Based on Application
- Myopia
- Astigmatism
- Others
By End-user
- Optometrist Offices
- Hospitals & Ophthalmology Clinics
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant market share in the Orthokeratology Lenses industry, accounting for approximately 35% of the global market. The strong demand in this region can be attributed to a high prevalence of myopia and a growing awareness of orthokeratology as a viable vision correction option. Furthermore, the presence of advanced healthcare infrastructure and a robust network of eye care professionals facilitates the adoption of innovative eye care solutions. The increasing focus on myopia control among children, coupled with educational initiatives from health organizations, has further propelled market growth in North America. Major players in the market are investing in marketing campaigns to raise awareness about the benefits of orthokeratology, contributing to its acceptance among patients and eye care providers alike.
Asia-Pacific
In contrast, the Asia-Pacific region is witnessing rapid growth in the Orthokeratology Lenses market, currently capturing around 30% of the global market share. This growth can be attributed to the rising incidence of myopia, particularly in densely populated countries such as China and India, where lifestyle factors and increased screen time among children are contributing to higher rates of refractive errors. The growing disposable income in emerging markets within the region also plays a crucial role in the increasing demand for advanced vision correction solutions. Additionally, the expansion of eye care clinics and the availability of specialized optometrists are enhancing access to orthokeratology treatments. As awareness of the long-term benefits of myopia control increases, the Asia-Pacific region is expected to experience significant market expansion, making it a key player in the global Orthokeratology Lenses landscape.
Key Player Analysis
- Brighten Optix, Co.
- MiracLens L.L.C.
- CooperVision
- TruForm Optics, Inc.
- Johnson & Johnson Vision Care, Inc.
- GP Specialists
- Euclid Systems Corp.
- Art Optical Contact Lens, Inc.
- Bausch & Lomb Inc.
- Alpha Corporation (Menicon Group)
Competitive Analysis
The competitive landscape of the Orthokeratology Lenses market is characterized by several leading players, including Bausch & Lomb Inc., Johnson & Johnson Vision Care, Inc., CooperVision, Euclid Systems Corp., and Alpha Corporation (Menicon Group). These companies are focused on innovation, enhancing product offerings through advancements in lens technology and materials to improve patient comfort and satisfaction. Additionally, they invest heavily in marketing and education initiatives to raise awareness about the benefits of orthokeratology, particularly among parents of children with myopia. Strategic partnerships and collaborations with eye care professionals are also prevalent, facilitating broader distribution and accessibility of their products. With increasing competition from emerging players and alternative vision correction methods, the established companies must continuously adapt their strategies to maintain their market position and meet the evolving needs of consumers. This dynamic environment fosters innovation and drives growth within the orthokeratology lens market.
Recent Developments
- In July 2024, Brighten Optix has made significant strides in the industry, earning accolades for its cutting-edge technology and patient-centric approach. Notable achievements include the development of high-precision lenses that cater to a wide range of refractive errors.
- In January 2023, CooperVision released a study indicating that orthokeratology (ortho-k) is the preferred method of myopia management in physically active children and adults.
- In September 2023, Art Optical introduced the MOONLENS in KATTCloud by KATT Design Group, a novel platform for ultimate practice efficiency.
Market Concentration & Characteristics
The market concentration for Orthokeratology Lenses is characterized by a mix of established players and emerging companies, resulting in a moderately competitive landscape. Major corporations, such as Bausch & Lomb Inc., Johnson & Johnson Vision Care, Inc., and CooperVision, dominate the market due to their strong brand recognition, extensive distribution networks, and significant investment in research and development. These players focus on innovation, improving lens design, and enhancing patient comfort, thereby strengthening their market positions. Additionally, the market exhibits characteristics such as increasing collaboration with eye care professionals and educational initiatives aimed at raising awareness about orthokeratology. Emerging companies are also entering the market, bringing new technologies and designs, which fosters healthy competition and drives overall market growth. As awareness of myopia and refractive errors continues to rise, the market is likely to see increased investment and innovation, further shaping its competitive dynamics and characteristics.
Report Coverage
The research report offers an in-depth analysis based on Type, Age Group, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for Orthokeratology Lenses is expected to increase as awareness of myopia control continues to grow among parents and eye care professionals.
- Advancements in lens technology, including smart lenses with integrated features, will enhance patient experience and comfort.
- The market will likely see a rise in customized lens designs tailored to individual patient needs, improving treatment effectiveness.
- Emerging markets in Asia-Pacific and Latin America will present significant growth opportunities due to rising disposable incomes and access to eye care services.
- Collaborations between key players and healthcare providers will expand distribution channels and improve accessibility to orthokeratology treatments.
- Increased focus on research and clinical studies will provide more long-term data on the efficacy and safety of orthokeratology, building trust among consumers.
- Regulatory changes may streamline approval processes, allowing for quicker market entry of new products.
- The trend towards non-surgical vision correction methods will continue to boost interest in orthokeratology as a viable alternative to LASIK.
- Growing digital marketing efforts will enhance patient education, leading to higher adoption rates of orthokeratology lenses.
- Overall, the Orthokeratology Lenses market is poised for substantial growth, driven by technological innovations and increasing awareness of eye health.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Orthokeratology Lenses market?
What factors are driving the growth of the Orthokeratology Lenses market?
What are the key segments within the Orthokeratology Lenses market?
What are some challenges faced by the Orthokeratology Lenses market?
Who are the major players in the Orthokeratology Lenses market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 857.8 million → 2032: USD 2,777.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Orthokeratology Lenses Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Orthokeratology Lenses Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Orthokeratology Lenses Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Orthokeratology Lenses Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Orthokeratology Lenses Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Orthokeratology Lenses Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Orthokeratology Lenses Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Orthokeratology Lenses Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 857.8 million → 2032: USD 2,777.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Orthokeratology Lenses Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Orthokeratology Lenses Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Orthokeratology Lenses Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Orthokeratology Lenses Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
