
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Pediatric Clinical Trials Market Size 2024 | USD 17,929.10 Million |
| Pediatric Clinical Trials Market, CAGR | 6.1% |
| Pediatric Clinical Trials Market Size 2032 | USD 28,361.3 Million |
Market Overview
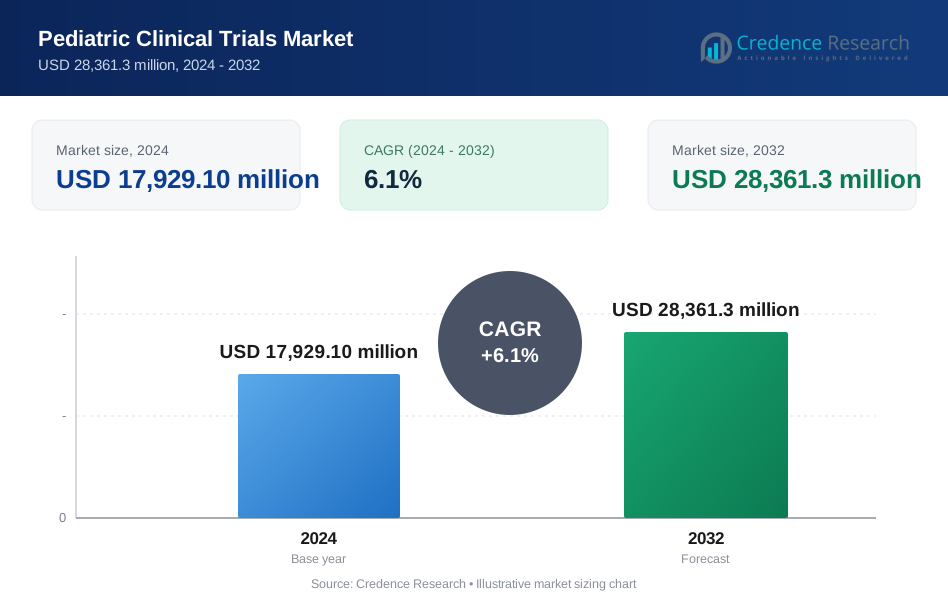
The Pediatric Clinical Trials Market is expected to grow from USD 17,929.10 million in 2024 to USD 28,361.3 million by 2032, at a compound annual growth rate (CAGR) of 6.1%.
The Pediatric Clinical Trials Market is driven by the increasing prevalence of pediatric diseases, the rising demand for tailored treatments, and advancements in pediatric healthcare. Enhanced regulatory frameworks and a growing focus on personalized medicine for children are further fueling market growth. Additionally, the need for accurate safety and efficacy data for pediatric populations is encouraging investments in clinical trials specific to children. Increasing collaborations between pharmaceutical companies and research organizations are also contributing to the market's expansion. Furthermore, technological innovations, including digital platforms and data analytics, are improving trial efficiency and patient recruitment. The growing emphasis on improving child health outcomes and the rising number of pediatric clinical studies worldwide are driving demand for better-targeted therapies. These factors, coupled with rising healthcare budgets and government support, are creating a favorable environment for market growth, positioning pediatric clinical trials as an essential area for future development in the global healthcare landscape.
The Pediatric Clinical Trials Market is experiencing notable growth across all regions, with North America holding the largest market share in 2024, driven by strong healthcare infrastructure and regulatory support. Europe follows closely, with significant contributions from the UK, Germany, and France, thanks to government initiatives and a focus on pediatric-specific research. The Asia-Pacific region is rapidly expanding, particularly in China and India, due to increasing healthcare investments and a growing demand for pediatric treatments. Latin America and the Middle East & Africa are also seeing gradual growth, with emerging markets like Brazil and Saudi Arabia becoming key players. Leading companies such as CSL Behring, Sanofi, Takeda Pharmaceutical Company Limited, Orchard Therapeutics, and BioCryst Pharmaceuticals are actively operating across these regions, driving innovations and expanding their clinical trial initiatives to cater to pediatric populations.
Market Insights
- The Pediatric Clinical Trials Market is projected to grow from USD 17,929.10 million in 2024 to USD 28,361.3 million by 2032, at a CAGR of 6.1%.
- Increasing prevalence of pediatric diseases, including respiratory disorders and childhood cancers, is driving the demand for tailored treatments and clinical trials.
- Advancements in pediatric healthcare, such as telemedicine and wearable devices, are enhancing trial efficiency and patient recruitment.
- Regulatory support, including initiatives like the Pediatric Research Equity Act (PREA), is encouraging more pediatric clinical trials.
- Rising focus on personalized medicine, integrating treatments tailored to children’s genetic makeup, is boosting market growth.
- Increasing collaborations between pharmaceutical companies and research organizations are contributing to market expansion.
- Technological innovations, including digital platforms and data analytics, are improving trial operations and patient monitoring.
Market Drivers
Increasing Prevalence of Pediatric Diseases
The rising incidence of pediatric diseases, including respiratory disorders, genetic conditions, and childhood cancers, is a primary driver of the Pediatric Clinical Trials Market. For instance, companies like Pfizer and GlaxoSmithKline are focusing on developing specialized drugs and vaccines for children, thereby driving the need for more pediatric clinical trials. As the number of children affected by chronic and acute diseases increases, there is a growing demand for effective therapies and treatments.
Focus on Personalized Medicine
Personalized medicine is gaining significant traction in pediatric healthcare, which is another key factor influencing the growth of pediatric clinical trials. With an increasing emphasis on tailoring treatments to the individual needs of children based on their genetic makeup, personalized therapies are being integrated into pediatric healthcare strategies. For instance, Novartis and Roche are promoting the development of more clinical trials aimed at identifying the most effective treatment options for specific pediatric populations, accelerating the overall growth of the market.
Advancements in Pediatric Healthcare
Advancements in pediatric healthcare and technology are playing a pivotal role in the expansion of the pediatric clinical trials market. Innovations such as telemedicine, wearable devices, and artificial intelligence are enhancing the ability to monitor and track pediatric patients during trials. For instance, companies like Medtronic and Philips are integrating telemedicine and wearable devices to improve the efficiency of clinical trials, making it easier to recruit participants, collect data, and ensure patient safety. The integration of these technologies is enabling faster and more accurate assessments, contributing to the market’s growth.
Government Initiatives and Regulatory Support
Government initiatives and regulatory frameworks supporting pediatric research are crucial drivers of the Pediatric Clinical Trials Market. Policymakers across the globe are recognizing the need for more pediatric-specific research and are providing incentives such as funding and regulatory ease to stimulate pediatric drug development. For instance, the Pediatric Research Equity Act (PREA) in the U.S. mandates that new drugs be tested in children, while similar regulations in other countries are encouraging clinical trials focused on pediatric populations. This regulatory support is crucial in advancing pediatric clinical research and contributing to market growth.
Market Trends
Growth of Pediatric Oncology Trials
One of the significant current trends in the Pediatric Clinical Trials Market is the growing focus on pediatric oncology. With an increase in childhood cancer rates and the need for more effective treatments, pediatric oncology trials are becoming a central area of research. For instance, pharmaceutical companies like Novartis and Bristol-Myers Squibb are increasingly prioritizing cancer treatments designed specifically for children, due to the distinct physiological characteristics and response to therapies in pediatric populations. This trend is expected to continue, leading to more clinical trials targeting childhood cancers such as leukemia, brain tumors, and lymphoma.
Integration of Digital Technologies in Clinical Trials
The integration of digital technologies in pediatric clinical trials is transforming how these studies are conducted. Tools like electronic health records (EHRs), mobile health applications, and wearable devices are being used to streamline data collection, improve patient monitoring, and increase participant engagement. For instance, companies like Medtronic and Philips are using electronic health records (EHRs), mobile health applications, and wearable devices to streamline data collection, improve patient monitoring, and increase participant engagement. These technologies enhance the ability to conduct remote trials, making it easier to recruit patients, especially in geographically diverse regions. Digital tools also facilitate real-time data analysis, which accelerates decision-making and improves trial outcomes, contributing to market growth.
Emphasis on Rare Pediatric Diseases
Another notable trend is the growing emphasis on rare pediatric diseases, which are often neglected in clinical research. To address this gap, pharmaceutical companies are increasingly developing therapies for rare conditions such as pediatric autoimmune diseases, rare genetic disorders, and metabolic disorders. For instance, companies like Sanofi and Pfizer are developing therapies for rare conditions such as pediatric autoimmune diseases, rare genetic disorders, and metabolic disorders. Regulatory incentives, such as orphan drug status and fast-track approval processes, are encouraging investments in the development of treatments for these rare diseases. As a result, there is a rise in clinical trials focused on providing better therapeutic options for children suffering from conditions with limited treatment options.
Expansion of Collaborative Research Models
Collaborative research models are becoming more prevalent in pediatric clinical trials, with academic institutions, government agencies, and pharmaceutical companies working together to enhance the scope and impact of trials. For instance, collaborations between academic institutions and pharmaceutical companies like Johnson & Johnson and GlaxoSmithKline enable the pooling of resources, expertise, and patient networks, allowing for faster and more comprehensive studies. The trend of partnership-based research is helping to overcome challenges like limited patient populations, improving trial efficiency, and driving advancements in pediatric healthcare.
Market Challenges Analysis
Recruitment and Retention of Pediatric Participants
One of the primary challenges in the Pediatric Clinical Trials Market is the recruitment and retention of pediatric participants. Due to the sensitive nature of involving children in clinical research, obtaining informed consent from parents or guardians presents a significant hurdle. Additionally, children’s medical conditions often vary greatly, making it challenging to find suitable candidates who meet specific trial criteria. Further complicating recruitment efforts is the limited number of pediatric patients for certain rare diseases, which can lead to longer recruitment periods and difficulties in achieving statistical significance. Retaining participants throughout the course of a trial is also a challenge, as children may experience side effects, become disinterested, or face other personal barriers that result in early withdrawal. Addressing these issues requires innovative strategies to improve engagement and retention, such as offering more flexible trial designs, clearer communication with families, providing better support systems, and offering incentives to ensure participant commitment.
Ethical and Regulatory Challenges
The pediatric clinical trials landscape is also significantly impacted by ethical and regulatory challenges. Conducting clinical trials with children involves stringent ethical considerations to ensure their safety and well-being, as children are considered a vulnerable population. Regulatory agencies, such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), require extensive review and adherence to strict guidelines to protect pediatric participants. The complexities of obtaining parental consent, ensuring appropriate trial protocols, and managing the ethical responsibility of conducting studies with minors present ongoing challenges for pharmaceutical companies and researchers. Moreover, in many countries, regulatory frameworks for pediatric trials are still evolving, and variations in global regulations add an additional layer of complexity for companies conducting multi-national studies. This complex regulatory environment can delay trial timelines and increase operational costs, making it a considerable challenge for organizations involved in pediatric clinical trials.
Market Opportunities
The Pediatric Clinical Trials Market presents significant opportunities driven by the increasing demand for tailored treatments and therapies specific to children. As the prevalence of pediatric diseases continues to rise, including childhood cancers, genetic disorders, and respiratory illnesses, there is a growing need for specialized clinical trials focused on developing effective treatments for younger populations. Advancements in pediatric healthcare, such as the integration of personalized medicine, are creating additional opportunities for the market, allowing for more precise and targeted therapies. The ongoing development of vaccines and biologics for pediatric use, alongside increasing awareness of the unique health needs of children, is driving investment in pediatric clinical trials. With the rise in demand for pediatric-specific treatments, pharmaceutical companies and research institutions are recognizing the importance of developing drugs and therapies that account for the unique physiology of children, creating a substantial growth opportunity for clinical trial providers.
Furthermore, the increasing collaboration between pharmaceutical companies, academic institutions, and government agencies is providing additional opportunities in the market. These partnerships enable resource sharing, enhance trial efficiency, and improve patient recruitment, particularly for rare pediatric diseases where patient populations are limited. Regulatory support, including government incentives such as funding for pediatric research and fast-track approval processes, is also creating a favorable environment for clinical trials. The rise in orphan drug development for rare pediatric diseases and the shift toward digital solutions like remote monitoring and telemedicine are further bolstering market opportunities. As a result, the Pediatric Clinical Trials Market is poised for significant growth, driven by a combination of regulatory support, technological advancements, and an increased focus on meeting the healthcare needs of pediatric populations worldwide.
Market Segmentation Analysis:
By Phase The Pediatric Clinical Trials Market can be segmented by phase, including Phase 1, Phase 2, Phase 3, and Phase 4 trials. Phase 3 trials currently dominate the market due to the increasing demand for large-scale studies to test the efficacy and safety of new treatments in pediatric populations. Phase 1 and 2 trials, although smaller in scale, continue to show steady growth as they focus on initial safety and dosing evaluations.
By Study Design
The market is also segmented by study design, including interventional and observational trials. Interventional trials, where the researchers actively administer treatments, dominate the market, driven by the increasing need for new therapies. Observational studies, while smaller in comparison, are gaining prominence as they provide valuable insights into real-world outcomes and help shape pediatric treatment guidelines.
By Therapeutic Area
In terms of therapeutic areas, the Pediatric Clinical Trials Market is segmented into oncology, infectious diseases, respiratory diseases, neurological disorders, and others. Pediatric oncology trials lead the market due to the rising incidence of childhood cancers and the need for novel, effective treatments. Respiratory diseases and infectious diseases are also significant areas due to the prevalence of conditions like asthma and pneumonia in children.
Segments:
Based on Phase
- Phase I
- Phase II
- Phase III
- Phase IV
Based on Study Design
- Treatment Studies
- Observational Studies
Based on Therapeutic Area
- Respiratory Diseases
- Cardiovascular Diseases
- Neuropsychiatric Conditions
- Oncology
- Diabetes
- Others (Neuropsychiatric Conditions, etc.)
Based on the Geography:
- North America
- S.
- Canada
- Mexico
- Europe
- Germany
- France
- K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
In 2024, North America is expected to hold the largest market share of the Pediatric Clinical Trials Market, accounting for 40%. The region's dominance can be attributed to advanced healthcare infrastructure, strong government support, and the presence of major pharmaceutical companies and research institutions. The U.S. is a key player, with regulatory frameworks such as the Pediatric Research Equity Act (PREA) that encourage pediatric-specific research and ensure the development of therapies for children. Additionally, increasing investments in rare disease research, pediatric oncology, and personalized medicine are fueling market growth. North America’s market is further boosted by technological advancements, including the integration of digital tools in clinical trials, which enhance trial efficiency and patient monitoring.
Europe
Europe is expected to account for 30% of the market share in 2024, making it the second-largest region in the pediatric clinical trials space. The European Medicines Agency (EMA) has implemented several initiatives to support pediatric research, such as the Pediatric Regulation, which mandates the testing of new medicines in children. As a result, there is an increasing focus on pediatric clinical trials for oncology, infectious diseases, and genetic disorders. Countries like the UK, Germany, and France are leading the way in pediatric trials due to strong healthcare systems, supportive regulatory environments, and a collaborative approach involving public-private partnerships. The region’s growing emphasis on rare pediatric diseases and advancements in gene therapy contribute to market growth.
Asia-Pacific
The Asia-Pacific (APAC) region is projected to experience significant growth in the Pediatric Clinical Trials Market, with an estimated market share of 20% in 2024. The region’s expansion is driven by a large and growing pediatric population, increasing healthcare investments, and an improving regulatory environment. Emerging economies such as China and India are witnessing a rise in clinical trials, fueled by a greater demand for pediatric treatments and therapies. The rapid adoption of digital health technologies, increasing government focus on healthcare infrastructure, and the presence of contract research organizations (CROs) are also driving market growth in APAC. However, challenges related to patient recruitment and varying regulatory standards across countries continue to pose barriers.
Latin America
Latin America is expected to account for a smaller portion of the Pediatric Clinical Trials Market in 2024, with a market share of 5%. The region is witnessing gradual growth in pediatric clinical trials, driven by improving healthcare infrastructure and increasing investments from global pharmaceutical companies. Countries like Brazil and Mexico are becoming significant hubs for clinical research, particularly in pediatric vaccines, infectious diseases, and respiratory conditions. The rising awareness of the importance of pediatric-specific therapies is encouraging the growth of clinical trials in Latin America, though challenges like varying regulatory environments and limited patient recruitment remain.
Middle East & Africa
The Middle East & Africa (MEA) region is projected to contribute 5% of the Pediatric Clinical Trials Market in 2024. While this region holds a smaller share, it is experiencing growth in pediatric clinical research due to increasing investments in healthcare and infrastructure development. The Middle East, particularly countries like the UAE and Saudi Arabia, is focusing on pediatric oncology, rare diseases, and vaccines. Despite this progress, the market in MEA faces challenges related to limited access to healthcare resources, varying regulatory standards across countries, and regional disparities in clinical trial expertise. However, ongoing efforts to improve healthcare systems and attract international research partnerships are expected to drive future growth in the region.
Key Player Analysis
- Takeda Pharmaceutical Company Limited
- Orchard Therapeutics plc.
- BioCryst Pharmaceuticals, Inc.
- Adverum Biotechnologies, Inc.
- KalVista Pharmaceuticals
- Ionis Pharmaceuticals, Inc.
- CENTOGENE N.V.
- Pharming Group N.V.
- CSL Behring
- Arrowhead Pharmaceuticals, Inc.
Competitive Analysis
The Pediatric Clinical Trials Market is highly competitive, with leading players such as CSL Behring, Sanofi, Takeda Pharmaceutical Company Limited, Orchard Therapeutics plc., Pharming Group N.V., BioCryst Pharmaceuticals, Inc., Ionis Pharmaceuticals, Inc., Attune Pharmaceuticals, Arrowhead Pharmaceuticals, Inc., Adverum Biotechnologies, Inc., and KalVista Pharmaceuticals actively shaping the market landscape. These companies are investing significantly in innovative therapies and expanding their clinical trial portfolios to address the growing demand for pediatric-specific treatments. The competition is driven by factors such as the need for specialized treatments for rare pediatric diseases, advancements in personalized medicine, and increasing government support for pediatric research. Companies are focusing on improving trial designs, patient recruitment, and retention strategies while also leveraging digital technologies to enhance trial efficiency. For instance, Pharming Group N.V. and BioCryst Pharmaceuticals, Inc. are leveraging digital technologies to enhance trial efficiency. Collaborative research partnerships and regulatory support are key strategies enabling these organizations to maintain a competitive edge in the evolving pediatric clinical trials space.
Recent Developments
- In July 2024, Labcorp entered into a collaboration agreement with Naples Comprehensive Healthcare (NCH) in Southwest Florida. This collaboration aims to combine key capabilities, expertise, and technologies from both organizations to enhance access to laboratory services and advance the delivery of high-quality care.
- In March 2024, Pfizer Inc. announced that the European Commission (EC) granted marketing authorization for its 20-valent pneumococcal conjugate vaccine, PREVENAR 20®. This vaccine is approved for active immunization to prevent invasive diseases, pneumonia, and acute otitis media caused by Streptococcus pneumoniae in infants, children, and adolescents aged 6 weeks to under 18 years.
- In December 2023, Pfizer Inc. and Valneva SE announced the completion of participant recruitment for the Phase 3 trial of the Lyme disease vaccine candidate, VLA15. Building on positive results from earlier Phase 1 and 2 trials, this study includes both adult and pediatric participants and aims to confirm the efficacy, safety, lot consistency, and immunogenicity of VLA15.
- In September 2023, the National Minority Quality Forum (NMQF), an independent non-profit organization dedicated to research and education, and Thermo Fisher Scientific Inc., a global leader in the science service industry, announced their collaboration to expand clinical research to historically underserved patient populations through the NMQF's Alliance for Representative Clinical Trials (ARC).
Market Concentration & Characteristics
The Pediatric Clinical Trials Market exhibits moderate to high concentration, with key players such as CSL Behring, Sanofi, Takeda Pharmaceutical Company Limited, and BioCryst Pharmaceuticals driving significant market share. While large pharmaceutical companies dominate the space, smaller biotechnology firms and specialized research organizations also contribute by focusing on niche pediatric diseases and advanced therapies. These companies often collaborate with academic institutions, government agencies, and contract research organizations (CROs) to expand their research capabilities and reach diverse patient populations. The market is characterized by a high degree of innovation, with a strong emphasis on developing personalized treatments tailored specifically for pediatric populations. The increasing adoption of digital technologies, such as telemedicine and data analytics, is reshaping clinical trial designs, improving patient engagement, and reducing trial costs. As regulatory frameworks continue to evolve, the market is expected to witness more partnerships and an increased focus on rare and genetic pediatric diseases.
Report Coverage
The research report offers an in-depth analysis based on Phase, Study Design, Therapeutic Area and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Pediatric Clinical Trials Market is expected to experience steady growth, driven by the increasing need for pediatric-specific therapies.
- Advancements in personalized medicine will continue to shape the development of tailored treatments for children.
- Technological innovations, such as telemedicine and wearable devices, will enhance trial efficiency and patient engagement.
- Increasing government support and regulatory frameworks will boost investments in pediatric clinical research.
- The growing prevalence of pediatric diseases, including rare conditions, will accelerate the demand for clinical trials focused on children.
- Collaborations between pharmaceutical companies, research organizations, and governments will increase to address unmet pediatric healthcare needs.
- The rise of digital platforms and data analytics will improve recruitment, monitoring, and data collection during clinical trials.
- Pediatric clinical trials will expand in emerging markets, particularly in regions like Asia-Pacific and Latin America.
- Efforts to address recruitment and retention challenges in pediatric trials will result in more efficient patient enrollment strategies.
- Ethical considerations will continue to play a significant role in shaping the design and conduct of pediatric clinical trials.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Pediatric Diseases
The rising incidence of pediatric diseases such as respiratory disorders, genetic conditions, and childhood cancers is driving the need for more clinical trials to develop effective and safe therapies for children.
Advancements in Pediatric Healthcare and Technology
Innovations like telemedicine, wearable devices, and digital health platforms are improving the efficiency of pediatric clinical trials by enhancing patient monitoring, data collection, and recruitment processes.
Regulatory Support and Government Initiatives
Policies such as the Pediatric Research Equity Act (PREA) in the U.S. and similar regulations in Europe mandate and incentivize pediatric-specific research, encouraging pharmaceutical companies to invest in clinical trials for children.
Focus on Personalized Medicine
The growing emphasis on tailoring treatments to children's genetic profiles is increasing the demand for pediatric clinical trials that can validate the safety and efficacy of personalized therapies.
Expansion of Collaborative Research Models
Increasing partnerships between pharmaceutical companies, academic institutions, and government agencies are pooling resources and expertise, enabling more comprehensive and efficient pediatric clinical studies, especially for rare diseases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Pediatric Clinical Trials Market?
What factors are driving the growth of the Pediatric Clinical Trials Market?
What are the key segments within the Pediatric Clinical Trials Market?
What are some challenges faced by the Pediatric Clinical Trials Market?
Who are the major players in the Pediatric Clinical Trials Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Phase
- 1.2.1 Phase I
- 1.2.2 Phase II
- 1.2.3 Phase III
- 1.2.4 Phase IV
- 1.3 By Study Design
- 1.3.1 Treatment Studies
- 1.3.2 Observational Studies
- 1.4 By Therapeutic Area
- 1.4.1 Respiratory Diseases
- 1.4.2 Cardiovascular Diseases
- 1.4.3 Neuropsychiatric Conditions
- 1.4.4 Oncology
- 1.4.5 Diabetes
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,929.10 million → 2032: USD 28,361.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pediatric Clinical Trials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pediatric Clinical Trials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pediatric Clinical Trials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pediatric Clinical Trials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pediatric Clinical Trials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pediatric Clinical Trials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pediatric Clinical Trials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pediatric Clinical Trials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,929.10 million → 2032: USD 28,361.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pediatric Clinical Trials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Phase - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Phase I
- 12.3.7.2 Phase II
- 12.3.7.3 Phase III
- 12.3.7.4 Phase IV
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Study Design - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Treatment Studies
- 12.4.7.2 Observational Studies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Therapeutic Area - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Respiratory Diseases
- 12.5.7.2 Cardiovascular Diseases
- 12.5.7.3 Neuropsychiatric Conditions
- 12.5.7.4 Oncology
- 12.5.7.5 Diabetes
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pediatric Clinical Trials Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Pediatric Clinical Trials Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Pediatric Clinical Trials Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Takeda Pharmaceutical Company Limited
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Orchard Therapeutics plc.
- 17.4 BioCryst Pharmaceuticals, Inc.
- 17.5 CSL Behring
- 17.6 Sanofi
- 17.7 Pharming Group N.V.
- 17.8 Ionis Pharmaceuticals, Inc.
- 17.9 Adverum Biotechnologies, Inc.
- 17.10 Arrowhead Pharmaceuticals, Inc.
- 17.11 KalVista Pharmaceuticals
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

