
Market Overview:
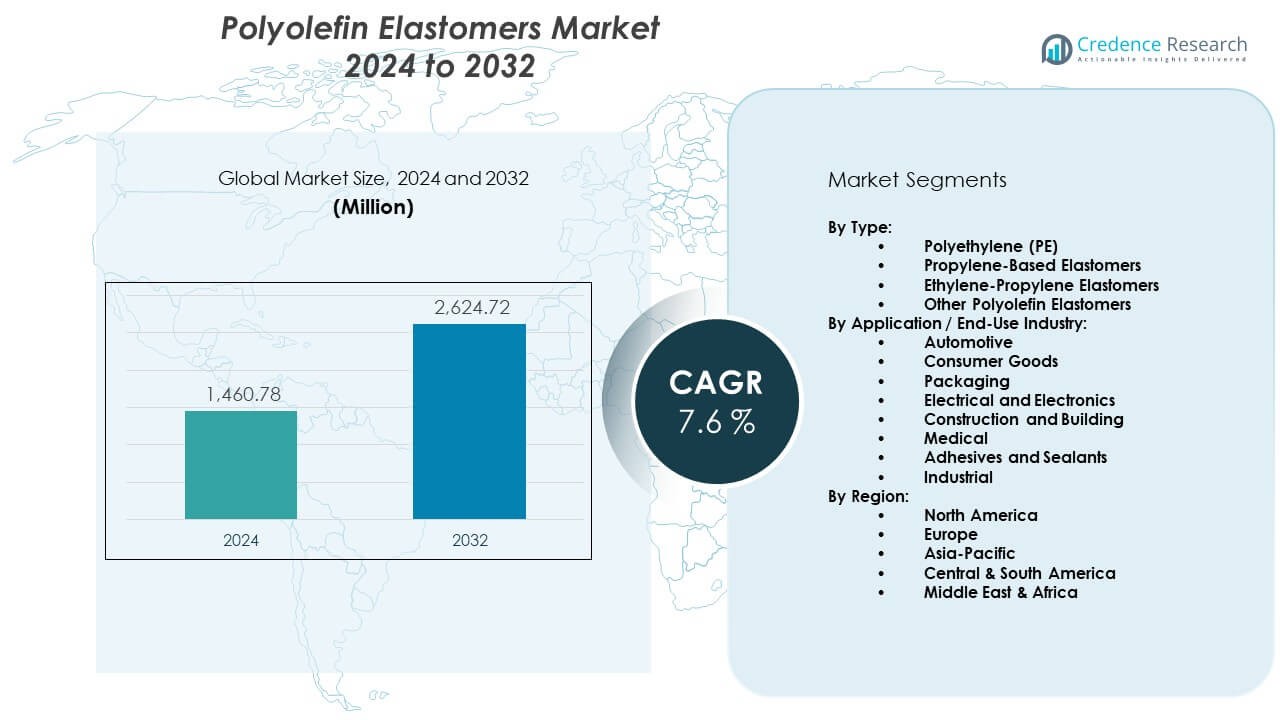
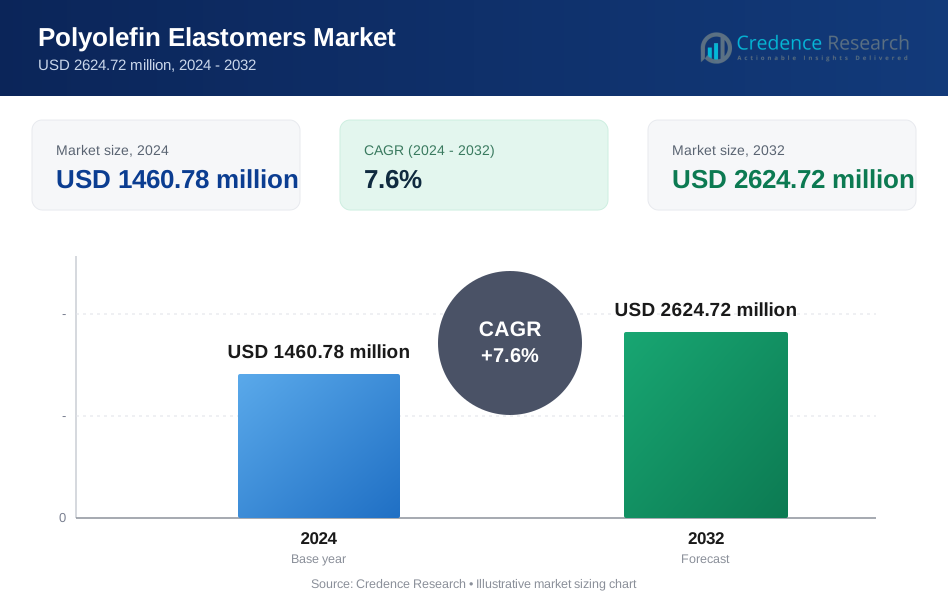
The Polyolefin Elastomers Market is projected to grow from USD 1460.78 million in 2024 to an estimated USD 2624.72 million by 2032, with a compound annual growth rate (CAGR) of 7.6% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polyolefin Elastomers Market Size 2024 | USD 1460.78 Million |
| Polyolefin Elastomers Market, CAGR | 7.6% |
| Polyolefin Elastomers Market Size 2032 | USD 2624.72 Million |
Rising interest in lightweight materials drives stronger uptake across transportation and electronics. Producers develop elastomers with better impact strength to support durable components. Packaging companies shift toward flexible film structures that improve product protection. The Polyolefin Elastomers Market gains momentum as brand owners seek sustainable materials with better recyclability. Consumer goods makers use advanced elastomers to enhance stretch, softness, and safety. Industrial buyers adopt these materials to streamline molding processes and reduce production waste.
North America leads due to strong demand from automotive and packaging industries supported by advanced manufacturing capabilities. Europe follows with steady consumption driven by strict sustainability goals and strong polymer innovation. Asia Pacific emerges as the fastest-growing region due to expanding automotive production and rapid growth in flexible packaging. China, India, and Southeast Asia push wider adoption through rising industrial output and higher use of modern polymer blends. Latin America and the Middle East show gradual expansion driven by infrastructure upgrades and a growing consumer base.
Market Insights:
- The Polyolefin Elastomers Market is projected to grow from USD 1460.78 million in 2024 to USD 2624.72 million by 2032, recording a 6% CAGR, driven by rising use in automotive parts, packaging films, and consumer goods.
- North America (38%), Asia-Pacific (30%), and Europe (27%) hold the largest shares due to strong automotive demand, advanced polymer processing, and strict sustainability-driven adoption.
- Asia-Pacific, at 30% share, stands as the fastest-growing region supported by expanding automotive production, rapid industrialization, and strong growth in flexible packaging.
- Packaging accounts for the largest segment share at 34%, driven by demand for flexible films, clarity, and durable protective layers across industries.
- Automotive holds around 27% share, supported by lightweight material needs, improved part durability, and growing electric vehicle production.
 Market Drivers:
Rising Use of Lightweight Polymers in Automotive and Transportation
Demand grows as automakers replace heavier materials with flexible elastomer grades that support weight reduction. Manufacturers focus on impact-resistant compounds to improve part longevity. Engineers use these polymers to upgrade bumper systems, seals, and trims. The shift toward electric vehicles pushes wider adoption of soft-touch components. Suppliers expand portfolios to meet strict safety and durability needs. The Polyolefin Elastomers Market gains steady traction through rising production volumes. It helps brands improve fuel efficiency targets. The trend strengthens global interest in lightweight design.
- For instance, ExxonMobil reports that its Vistamaxx™ performance polymers improve impact resistance in automotive interiors by up to 20%, enabling lighter assemblies.
Growing Demand for Flexible Packaging Structures Across Industries
Packaging converters increase use of elastomers to improve seal strength and film clarity. Food brands adopt flexible materials to extend product shelf life. Healthcare firms rely on soft films to support sterile packaging needs. Producers upgrade film blends for better tear resistance. It supports consistent performance in demanding logistics cycles. The Polyolefin Elastomers Market grows through rapid expansion in e-commerce shipments. Brand owners look for safer and more appealing packaging formats. Sustainability goals push wider use of recyclable polymer blends.
- For instance, ExxonMobil’s Exceed™ XP films demonstrate puncture resistance exceeding 5 J, which enhances durability for packaged goods. Food brands adopt flexible materials to extend product shelf life.
Strong Shift Toward Sustainable and Recyclable Material Formulations
Manufacturers redesign elastomer grades to reduce environmental footprints. Research teams explore cleaner catalyst systems to support greener production. Packaging firms invest in recyclable structures to meet regulatory needs. It encourages companies to trial mono-material solutions for easier recovery. The Polyolefin Elastomers Market benefits from stronger commitments to circular models. Automotive suppliers test bio-based blends for interior and exterior components. Industrial buyers evaluate low-emission grades to meet compliance norms. Global sustainability frameworks accelerate polymer innovation.
Expanding Role of High-Performance Elastomers in Consumer Goods
Producers develop soft-touch materials to improve comfort and product aesthetics. Consumer brands adopt elastomers to enhance grip and durability. Toy manufacturers use safer grades for flexible parts. Sports equipment firms include advanced compounds to improve performance. It supports stronger demand for customized product features. The Polyolefin Elastomers Market gains value through rising lifestyle-oriented consumption. Electronics brands use elastomers for ergonomic casings. Growth rises as buyers seek products with better tactile feel.
Market Trends:
Innovation in Catalyst Technology to Improve Material Precision and Performance
Producers invest in metallocene catalyst systems to deliver better control over polymer structure. It helps improve softness, elasticity, and clarity for advanced applications. The Polyolefin Elastomers Market observes rising demand for grades with tighter molecular distribution. Packaging converters benefit from improved mechanical balance. Automotive suppliers use precision grades for enhanced molding consistency. Consumer goods manufacturers gain better design flexibility. Research teams test catalysts that reduce defects during production. Innovation accelerates adoption across multiple industries.
- For instance, Mitsui Chemicals’ Tafmer™ metallocene elastomers achieve melt flow rates down to 5 g/10 min, enabling high precision in film and molding applications.
Shift Toward High-Temperature and High-Strength Elastomer Grades
Industrial buyers seek materials that withstand tougher mechanical loads. Producers respond with elastomers designed for elevated thermal conditions. It expands usage across heavy-duty segments. The Polyolefin Elastomers Market gains traction as buyers search for long-lasting materials. Engineers adopt stronger grades to improve end-product stability. Automotive firms test these polymers in demanding environments. Packaging converters use heat-resistant blends for retort applications. Strong performance needs drive continuous material upgrades.
- For instance, LG Chem’s POE grades for industrial parts withstand temperatures near 120°C without losing elasticity.
Rising Integration of Elastomers in Advanced Film and Lamination Technologies
Film manufacturers use elastomer-enhanced structures for better flexibility. It supports higher resistance to puncture during transport cycles. The Polyolefin Elastomers Market grows through expanding multilayer film adoption. Packaging brands invest in smoother sealing surfaces. Healthcare firms test elastomer blends for sensitive medical films. Electronics producers use advanced laminates to protect components. E-commerce growth accelerates need for durable packaging films. Demand rises across logistics and retail supply chains.
Growth in Specialty Applications Driven by Custom Material Engineering
Producers create tailor-made elastomer grades for niche segments. It helps brands adopt unique material functions across products. The Polyolefin Elastomers Market benefits from greater customization requests. Footwear firms use engineered blends for improved cushioning. Cable manufacturers adopt elastomers for flexible jacketing. Medical suppliers test soft-touch materials for safer devices. Industrial designers push demand for differentiated polymer properties. Specialty applications unlock new revenue pathways.
Market Challenges Analysis:
High Production Costs and Limitations in Feedstock Availability
Manufacturers face strong pressure due to volatile raw material supply. Feedstock shortages disrupt production cycles across regions. It raises cost burdens for converters and compounders. The Polyolefin Elastomers Market experiences challenges when supply chains tighten. Producers struggle to balance pricing with customer expectations. Import-dependent regions report higher exposure to global disruptions. Industrial buyers delay procurement when price gaps widen. Competition stiffens as firms seek low-cost alternatives.
Technical Constraints in High-Precision Processing and Product Standardization
Elastomers require strict processing controls to maintain uniform quality. It creates operational difficulty for smaller manufacturers. The Polyolefin Elastomers Market encounters hurdles when precision molding demands rise. Variability in performance limits adoption in safety-critical applications. Converters invest in advanced machinery to improve consistency. Product standardization remains uneven across global markets. Engineers face difficulty ensuring identical results across batches. Technical challenges push firms to upgrade equipment frequently.
Market Opportunities:
Rapid Expansion of Sustainable Alternatives Across Packaging and Consumer Goods
Brands shift toward recyclable materials to meet environmental goals. Producers develop cleaner polymer grades to support regulatory needs. It encourages adoption across flexible packaging and personal care products. The Polyolefin Elastomers Market benefits from rising demand for eco-friendly solutions. Converters explore mono-material designs for easier recovery. Consumer brands promote greener products to enhance market appeal. Growth opportunities rise within regions focusing on circular economies. New formulations help reduce environmental impact.
Growing Adoption of Elastomers in High-Value Industrial and Medical Applications
Medical device makers seek soft-touch materials for improved comfort. Industrial suppliers test elastomers for better vibration control. It supports wider use in tools and safety gear. The Polyolefin Elastomers Market expands through emerging application clusters. Electronics producers include elastomers in ergonomic housings. Robotics designers use flexible polymers for sensitive movement parts. Demand grows as buyers look for advanced performance features. Broader industrial needs open space for long-term innovation.
Market Segmentation Analysis:
By Type
Polyethylene (PE) leads the segment due to strong demand for flexible films, soft-touch components, and high-clarity packaging structures. Propylene-based elastomers follow with wider use in automotive interiors, bumpers, and sealing systems that require improved impact strength. Ethylene-propylene elastomers gain traction for weather-resistant and durable outdoor applications. Other polyolefin elastomers support niche needs where custom performance or specialized processing is required. The Polyolefin Elastomers Market benefits from strong compatibility across molding, extrusion, and blending operations. It supports manufacturers seeking versatile materials with balanced mechanical properties. Type diversification strengthens product innovation across industries.
- For instance, SABIC’s PE-based elastomers achieve dart drop impact strength above 1,500 g, supporting premium packaging uses.
By Application / End-Use Industry
Automotive holds significant share due to rising adoption in trims, gaskets, and lightweight components. Consumer goods rely on elastomers for soft-touch grips, wear resistance, and improved ergonomics. Packaging emerges as a major user due to strong demand for flexible films, sealants, and protective layers. Electrical and electronics firms use elastomers for insulation, cushioning, and component safety. Construction and building applications grow through greater use in roofing membranes and sealants. Medical uses expand due to interest in safer, non-latex alternatives. Adhesives and sealants benefit from improved bonding strength and durability. Industrial users adopt elastomers to support vibration control and reliable mechanical performance.
- For instance, Dow’s ENGAGE™ materials are used in auto weatherseals with compression set improvements of up to 25%. Consumer goods rely on elastomers for soft-touch grips, wear resistance, and better ergonomics.
Segmentation:
By Type:
- Polyethylene (PE)
- Propylene-Based Elastomers
- Ethylene-Propylene Elastomers
- Other Polyolefin Elastomers
By Application / End-Use Industry:
- Automotive
- Consumer Goods
- Packaging
- Electrical and Electronics
- Construction and Building
- Medical
- Adhesives and Sealants
- Industrial
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Polyolefin Elastomers Market, accounting for around 38% due to strong adoption in automotive, packaging, and consumer goods. Demand rises as manufacturers invest in advanced polymer processing and lightweight design. The region benefits from a mature industrial base supported by strong R&D capabilities. It gains steady traction through wider use in high-performance films and molded parts. Automotive suppliers depend on elastomers to improve durability and safety. Packaging companies increase use of flexible structures to meet sustainability goals. The market maintains a stable growth path supported by strong technology development.
Europe
Europe secures about 27% share driven by strict environmental standards and rising demand for recyclable materials. Producers adopt elastomers to comply with evolving circular economy regulations. The Polyolefin Elastomers Market grows through stronger interest in eco-friendly packaging formats. It gains support from automotive manufacturers that prioritize lightweight and low-emission parts. Consumer goods brands rely on high-quality elastomers to improve comfort and product life. Medical and healthcare applications expand with growing need for safer and latex-free materials. Regional innovation centers push steady improvements in polymer performance.
Asia-Pacific
Asia-Pacific captures nearly 30% share and remains the fastest-growing region due to expanding manufacturing capacity and rising consumption across key industries. China, India, and Southeast Asia drive higher demand for automotive parts, construction materials, and flexible packaging. It benefits from rapid industrialization and increasing investments in processing technologies. The Polyolefin Elastomers Market gains strong momentum as regional producers scale polymer production. Electronics manufacturers use elastomers for insulation and shock absorption. Packaging converters boost usage to serve large FMCG and e-commerce sectors. Growth accelerates with improving infrastructure and rising disposable income across developing economies.
Key Player Analysis:
- DowDuPont (US)
- The Dow Chemical Company (US)
- Exxon Mobil Corporation (US)
- Mitsui Chemicals, Inc. (Japan)
- LG Chem (South Korea)
- Mitsubishi Chemical Holding Corporation (Japan)
- Polmann India Ltd (India)
- SABIC (Saudi Arabia)
- LyondellBasell Industries Holdings BV (Netherlands)
- RTP Company (US)
- PolyOne Corporation (US)
Competitive Analysis:
The Polyolefin Elastomers Market features strong competition driven by product quality, processing efficiency, and global supply capabilities. Leading companies invest in advanced catalyst technologies to deliver consistent material performance across industries. Producers expand portfolios to meet rising demand for flexible packaging, automotive components, and consumer goods. It benefits from continuous improvements in mechanical strength, clarity, and recyclability. Key players focus on strategic partnerships to secure feedstock stability and extend regional presence. Innovation centers support development of specialized grades for high-value applications. Competition intensifies as new entrants target niche performance segments. Established firms strengthen distribution networks to maintain leadership positions.
Recent Developments:
- In September 2025, Mitsui Chemicals, Idemitsu Kosan, and Sumitomo Chemical entered into a Memorandum of Understanding (MOU) for integrating Sumitomo Chemical's polypropylene (PP) and linear low-density polyethylene (LLDPE) businesses in Japan into Prime Polymer Co., Ltd., the joint venture between Mitsui (65% stake) and Idemitsu (35% stake). Following the integration scheduled for April 2026, the shareholding structure will change to Mitsui 52%, Idemitsu 28%, and Sumitomo 20%, with an ambitious goal to generate integration synergies exceeding 8 billion yen through facility consolidation, product line optimization, and productivity improvements, while enhancing capabilities to develop high-performance and environmentally conscious polyolefin products for a sustainable green chemical business.
- In July 2025, ENEOS Corporation and Mitsubishi Chemical Corporation completed their chemical recycling facility for plastic-to-oil conversion business at MCC's Ibaraki Plant in Kamisu City, Ibaraki Prefecture, marking a significant step forward in advanced plastic recycling technology and demonstrating the companies' commitment to developing innovative circular economy solutions in specialty materials production.
- In October 2024, ExxonMobil Corporation announced the launch of its Signature Polymers brand, a transformative strategic initiative that unified all polyolefin products under a single portfolio brand as part of a comprehensive repositioning strategy to enhance customer partnership and service. The new brand architecture includes streamlined product naming and portfolio organization, new "PolyView" events to facilitate industry dialogue and market insights sharing, and the introduction of a Signature Polymers Academy focused on delivering training and workshops for customers across key markets, demonstrating ExxonMobil's commitment to becoming the industry's most valued global partner through improved service and collaboration.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Application/End-Use Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for elastomers will rise with increased adoption in flexible packaging.
- Automotive firms will use more lightweight polymer blends for trims and sealing parts.
- Processing innovation will support higher-quality film and molding performance.
- Material recyclability will become a central focus for producers and converters.
- Medical device makers will expand use of soft-touch and latex-free elastomers.
- Electronics firms will rely on advanced grades for insulation and shock protection.
- New catalyst systems will improve material precision for high-value applications.
- Infrastructure growth in Asia-Pacific will drive regional consumption.
- Global suppliers will expand facilities to secure long-term feedstock stability.
- Specialty elastomers will gain traction for emerging industrial and consumer uses.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Use of Lightweight Polymers in Automotive and Transportation
Automakers are increasingly replacing heavier materials with polyolefin elastomers to achieve weight reduction, improve fuel efficiency, and meet stricter emissions standards. The shift toward electric vehicles and the need for impact-resistant, durable parts further accelerate adoption in this sector.
Growing Demand for Flexible Packaging Structures Across Industries
Packaging converters and brand owners are adopting polyolefin elastomers for their superior seal strength, clarity, and puncture resistance, which enhance product protection and shelf life. The rapid expansion of e-commerce and the push for recyclable packaging materials are further driving market growth.
Strong Shift Toward Sustainable and Recyclable Material Formulations
Manufacturers are developing polyolefin elastomers with improved recyclability and lower environmental footprints to comply with evolving regulations and meet consumer demand for sustainable products. This trend is especially pronounced in packaging and automotive applications.
Innovation in Catalyst Technology to Improve Material Precision and Performance
Advancements in catalyst systems, such as metallocene catalysts, enable the production of elastomers with better softness, elasticity, and clarity. These innovations support the development of high-performance materials for demanding applications in packaging, automotive, and consumer goods.
Expanding Role of High-Performance Elastomers in Consumer Goods and Medical Devices
Consumer brands and medical device manufacturers are increasingly using advanced polyolefin elastomers to enhance product comfort, safety, and aesthetics. The demand for soft-touch, latex-free, and ergonomic materials is driving broader adoption in these sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Polyolefin Elastomers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polyolefin Elastomers Market projected to grow between 2025 and 2032?
Which Polyolefin Elastomers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polyolefin Elastomers Market?
Who are the leading companies in the Polyolefin Elastomers Market?
Which region commanded the largest share of the Polyolefin Elastomers Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Polyethylene (PE)
- 1.2.2 Propylene-Based Elastomers
- 1.2.3 Ethylene-Propylene Elastomers
- 1.2.4 Other Polyolefin Elastomers
- 1.3 By Application / End-Use Industry
- 1.3.1 Automotive
- 1.3.2 Consumer Goods
- 1.3.3 Packaging
- 1.3.4 Electrical and Electronics
- 1.3.5 Construction and Building
- 1.3.6 Medical
- 1.3.7 Adhesives and Sealants
- 1.3.8 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1460.78 million → 2032: USD 2624.72 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polyolefin Elastomers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polyolefin Elastomers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polyolefin Elastomers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polyolefin Elastomers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polyolefin Elastomers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polyolefin Elastomers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polyolefin Elastomers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polyolefin Elastomers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1460.78 million → 2032: USD 2624.72 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polyolefin Elastomers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Polyethylene (PE)
- 12.3.7.2 Propylene-Based Elastomers
- 12.3.7.3 Ethylene-Propylene Elastomers
- 12.3.7.4 Other Polyolefin Elastomers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application / End-Use Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Consumer Goods
- 12.4.7.3 Packaging
- 12.4.7.4 Electrical and Electronics
- 12.4.7.5 Construction and Building
- 12.4.7.6 Medical
- 12.4.7.7 Adhesives and Sealants
- 12.4.7.8 Industrial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polyolefin Elastomers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polyolefin Elastomers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polyolefin Elastomers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polyolefin Elastomers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DowDuPont
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 The Dow Chemical Company
- 18.4 Exxon Mobil Corporation
- 18.5 Mitsui Chemicals, Inc.
- 18.6 LG Chem
- 18.7 Mitsubishi Chemical Holding Corporation
- 18.8 Polmann India Ltd
- 18.9 SABIC
- 18.10 LyondellBasell Industries Holdings BV
- 18.11 RTP Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

