
Market Overview:
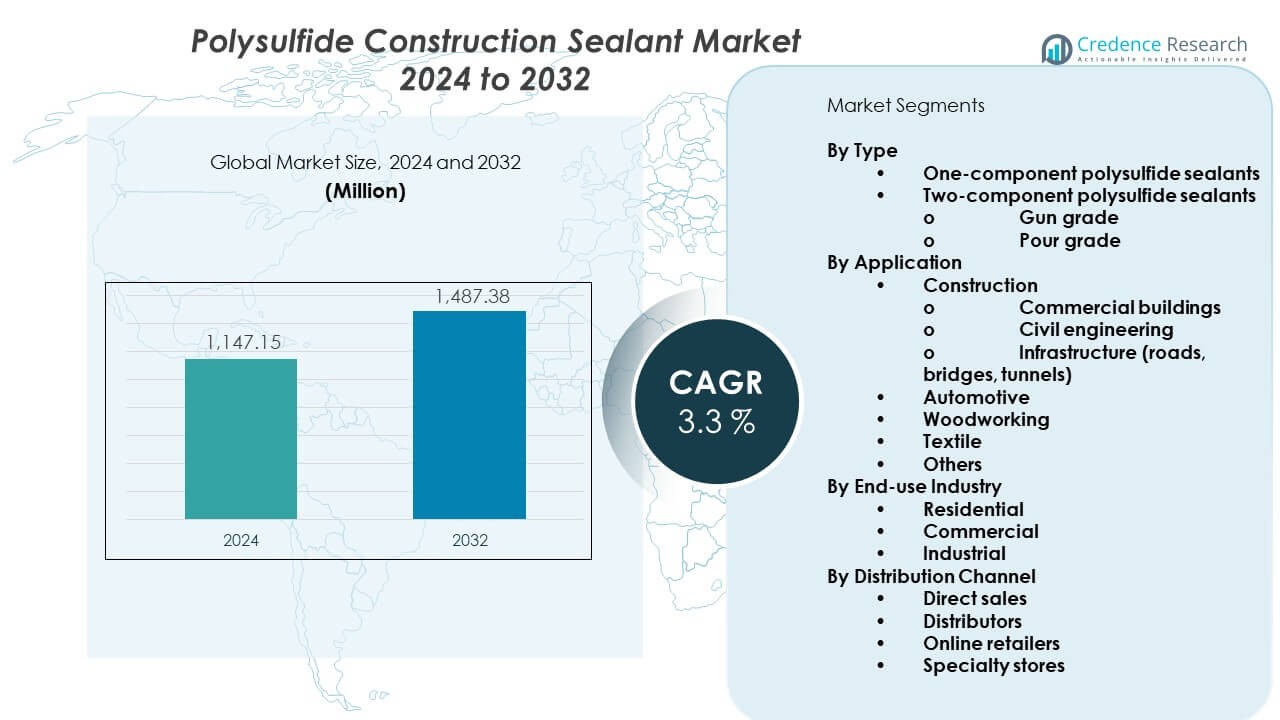
The Polysulfide Construction Sealant Market is projected to grow from USD 1,147.15 million in 2024 to an estimated USD 1,487.38 million by 2032, with a CAGR of 3.3% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polysulfide Construction Sealant Market Size 2024 | USD 1,147.15 Million |
| Polysulfide Construction Sealant Market, CAGR | 3.3% |
| Polysulfide Construction Sealant Market Size 2032 | USD 1,487.38 Million |
Demand grows as builders need durable sealing solutions for joints exposed to movement, chemicals, and weather stress. Adoption rises in large infrastructure upgrades where long-term elasticity supports safer structures. Manufacturers promote high-performance grades used in façades, runways, and water-retaining systems. Strict construction standards increase the shift toward materials that resist cracking and moisture. Repair teams also prefer these sealants due to strong bonding and long service life in harsh zones.
North America leads due to widespread commercial renovation and strong compliance with sealing standards. Europe follows based on strict building codes and ongoing infrastructure renewal. Asia Pacific emerges as a fast-growing region supported by urban expansion across India, China, and Southeast Asia. The Middle East shows rising adoption driven by large construction projects in high-temperature climates. Latin America develops steadily with increasing investment in transport and residential upgrades.
Market Insights:
- The market overview shows the Polysulfide construction sealant market valued at USD 1,147.15 million in 2024, projected to reach USD 1,487.38 million by 2032, and growing at a CAGR of 3.3%.
- North America leads with approximately ~38% share due to extensive infrastructure and high sealing standards; Europe follows with ~28% driven by stringent regulations and renovation of older buildings; Asia-Pacific holds about ~22% aided by rapid urbanisation and industrial expansion.
- Asia-Pacific is the fastest-growing region, with a ~22% share driven by large-scale infrastructure projects, rising residential construction, and increasing industrial applications.
- By type, one-component sealants command around ~55% of the market thanks to ease of use, while two-component (gun-grade and pour-grade combined) hold about ~45% because of superior performance in demanding joints.
- In application, the construction segment (commercial buildings, civil engineering, infrastructure) comprises roughly ~65% of demand due to large joint sealing requirements, while automotive, woodworking, textile and other uses represent about ~35%.
Market Drivers:
Strong Demand for Long-Life Joint Protection in Infrastructure and Commercial Buildings
The Polysulfide construction sealant market advances due to rising demand for durable joint sealing across heavy structures. Builders specify these sealants for bridges, runways, façades, and tanks that require long-term elasticity. Engineers prefer formulations that maintain bond strength under heat, moisture, and chemical exposure. Demand expands with renovation cycles in commercial towers and transport hubs. It supports safer designs that reduce structural stress around movement-prone joints. Construction teams apply these sealants to protect expansion zones across large surfaces. Buyers choose high-performance grades that handle pressure changes in extreme climates. Strong lifespan advantages reinforce interest across public and private projects.
- For instance, Sika joint sealing systems for highways and runways are widely used on concrete pavements and plaza decks and meet ASTM C920 and ASTM D5893 requirements, with approvals from many U.S. Departments of Transportation.
Growing Need for High Chemical Resistance in Industrial and Utility Projects
Industrial operators adopt polysulfide sealants to secure storage zones, wastewater systems, and processing areas. The material offers stable performance when exposed to fuels, solvents, and aggressive compounds. Demand rises in chemical plants where joint failure creates safety risks. It supports regulated facilities that enforce strict sealing standards for containment. Utility agencies rely on these compounds to protect pipelines and reservoirs. Manufacturing sites choose them to maintain operational continuity in corrosive work zones. Strong adhesion helps reduce maintenance downtime across large layouts. Rising compliance pressure strengthens material preference across multiple industries.
- For instance, Fosroc reports that its joint sealant solutions have been used for over 60 years on iconic buildings such as the Royal Grandstand at Ascot Racecourse and the Holy Mosque in Madinah, while its water-industry systems protect reservoirs and treatment works from chemical attack, joint leaks, cracks, and corrosion.
Expansion of Modern Construction Practices Requiring Elastic and Movement-Tolerant Materials
Modern architecture favors flexible materials that adapt to thermal shifts and structural motion. Polysulfide sealants meet these requirements through consistent elasticity. Engineers specify them for curtain walls, modular units, and composite panels. It supports design approaches that integrate high glass content and lightweight framing. Demand rises as builders target leak-free joints in challenging geometric layouts. Contractors value easy tooling and predictable curing in large builds. Adoption grows with the shift toward precision sealing in prefabricated systems. Their mechanical stability boosts confidence across advanced construction workflows.
Rising Focus on Water-Retaining and Weather-Exposed Structures Needing Strong Moisture Barriers
Water-retaining structures depend on reliable sealing to prevent leakage and material fatigue. Polysulfide sealants maintain stability in submerged or damp conditions. Municipal agencies use them for dams, reservoirs, and treatment plants. It supports long-term moisture control in outdoor infrastructure. Builders apply these compounds to façades that encounter heavy wind load and rainfall. Strong UV and ozone tolerance preserve performance in open environments. Operators prefer them for reducing repair cycles in weather-exposed assets. Growing climate variability encourages broader use across sensitive construction categories.
Market Trends:
Shift Toward Advanced Formulations with Improved Environmental and Worker Safety Profiles
Producers introduce low-VOC formulations that meet updated emission norms. The Polysulfide construction sealant market adapts to stricter safety criteria across major regions. Manufacturers redesign blends to reduce odors and improve application comfort. It supports contractors who work in sealed or sensitive environments. Buyers prefer options that simplify compliance during large building upgrades. R&D teams develop cleaner chemistries without compromising durability. Adoption grows across sectors focused on green-building certification. The trend aligns with rising demand for sustainable construction materials.
- For instance, SikaSeal-106 Construction carries GEV-Emicode EC1PLUS, LEED v4 EQc2 low-emitting materials, and RTS M1 classifications, while Sikaflex Construction Sealant reports a VOC content of 37 g/L, supporting low-emission building and indoor air quality goals documented in Sika’s guidance on low-VOC adhesives and sealants.
Integration of Automated and Precision-Controlled Application Methods Across Worksites
Construction teams shift to automated dispensing systems that improve sealing accuracy. Advanced equipment applies uniform beads across large joint distances. The Polysulfide construction sealant market benefits from faster installation cycles supported by machine-assisted workflows. It supports reduced waste and more consistent adhesion. Robotics improve performance in difficult-to-reach joints. Skilled labor shortages accelerate interest in semi-automated tools. Adoption grows in high-volume commercial and industrial settings. Precise output enhances long-term structural reliability.
- For instance, a bus manufacturer partnering with Pioneer Industrial Systems deployed a robotic urethane dispensing cell that improved quality and consistency, increased throughput, and helped relieve labor shortages, showing how automated sealant application boosts productivity in high-volume settings.
Growing Use of Sealants in Smart Infrastructure and High-Performance Building Designs
Modern projects feature embedded sensors and technical components requiring controlled sealing zones. Builders incorporate polysulfide compounds into smart façades and utility hubs. The Polysulfide construction sealant market aligns with trends in connected and energy-efficient infrastructure. It supports airtight envelopes that reduce losses in climate-controlled spaces. Architects choose flexible sealants to accommodate dynamic building systems. Interest rises in mixed-use skyscrapers with complex joint structures. Designers value high bonding stability across varied materials. This trend expands use across premium construction segments.
Rising Adoption in Marine, Aviation, and Specialty Engineering Projects
Specialty sectors use polysulfide sealants for demanding environments involving vibration, salt exposure, and heavy load. Marine teams rely on them for hull joints and storage zones. Aviation crews apply them to fuel systems and pressure-sensitive areas. The Polysulfide construction sealant market gains traction in technical upgrades across transport sectors. It supports safety-critical repairs where bond failure carries high risk. Demand rises with fleet renewal projects in ports and airports. Specialty contractors value consistent adhesion in multi-material assemblies. Growth continues across industries with extreme exposure demands.
Market Challenges Analysis:
Stringent Regulatory Scrutiny and Rising Compliance Costs Across Manufacturing and Application Stages
Producers face complex regulatory requirements governing VOC emissions, worker safety, and chemical management. Compliance raises operational costs across production lines. The Polysulfide construction sealant market must adjust to frequent updates in material standards. It manages certification needs for infrastructure and industrial approvals. Buyers evaluate documentation more carefully before product selection. Regional variations in rules complicate international supply planning. Contractors require training to maintain safe application practices. These factors create pressure on companies operating in cost-sensitive project ecosystems.
Growing Competition from Alternative Sealant Technologies Offering Faster Cures and Easier Handling
Alternative chemistries such as silicone, polyurethane, and hybrid sealants gain traction in several projects. These options offer faster cure rates and simpler application steps. It challenges polysulfide manufacturers to maintain competitiveness in mainstream construction. Buyers often compare maintenance profiles and labor requirements before choosing a material. Some alternatives provide stronger aesthetic finishes for visible joints. Market penetration increases in segments where extreme chemical resistance is not required. Distributors introduce wider product lines that shift preference patterns. Competitive pressure pushes producers to enhance performance features.
Market Opportunities:
Expansion Potential in Harsh-Environment Structures Requiring Extreme Chemical, Water, and Weather Resistance
Builders of reservoirs, chemical zones, and coastal assets seek high-grade sealing solutions. The Polysulfide construction sealant market can expand through specialized grades designed for severe exposure. It supports uptime gains across industrial and utility networks. Demand increases in regions investing in water security and resilient infrastructure. Contractors adopt advanced sealants to reduce repair frequency in climate-heavy zones. Strong moisture control creates opportunities in both public and private construction. Buyers look for materials that deliver predictable long-term stability. Growth strengthens across sectors where safety margins remain critical.
Rising Scope in Modular, Prefabricated, and High-Precision Construction Models
Modern building methods rely on clean, consistent, and movement-tolerant sealing. The Polysulfide construction sealant market aligns with precision requirements in modular units. It supports rapid installation workflows across large housing and commercial programs. Prefabrication increases demand for uniform bonding solutions across varied surfaces. Design firms integrate flexible sealants to address expansion gaps in hybrid structures. Adoption rises as developers scale factory-built construction lines. Global prefabrication growth creates new opportunities for adaptable sealing products. This trend widens long-term demand across diverse applications.
Market Segmentation Analysis:
By Type
One-component and two-component polysulfide sealants drive usage across varied project needs. The Polysulfide construction sealant market gains strength from two-component grades that support heavy structural joints in civil and industrial settings. Gun grade formats suit precision work, while pour grade products handle large expansion joints. It supports diverse installation conditions across commercial and infrastructure projects.
- For instance, Fosroc supplies a wide range of two-component sealant systems for engineering projects and highlights long-term performance in major civil construction, while Sika’s pour-grade polysulphide products are specified for expansion joints where large movement is anticipated in concrete construction and between diverse materials.
By Application
Construction dominates due to extensive use in commercial buildings, civil structures, and transport infrastructure. Contractors depend on these sealants to protect road and bridge joints from moisture and chemical attack. Automotive applications grow with the need for fuel-resistant bonding. Woodworking, textile, and other sectors adopt these materials for stability and long-term elasticity. It maintains performance across demanding operational environments.
- For instance, Sika reports that its joint sealing systems for roads and highways are widely used in formed and saw-cut joints on concrete highways, runways, plaza decks, and driveways, meeting highway regulations and providing UV- and weather-resistant performance, while Fosroc solutions protect water-industry reservoirs and channels from chemical attack and joint leaks.
By End-use Industry
Commercial and industrial sectors lead adoption due to high structural load and safety requirements. Residential demand grows with rising renovation and waterproofing activities. Industrial facilities use these sealants to secure tanks, pipelines, and containment areas. It delivers consistent sealing performance across variable temperature and pressure conditions.
By Distribution Channel
Direct sales dominate large-scale procurement for infrastructure and commercial projects. Distributors support widespread availability for mid-sized contractors. Online retailers expand reach among small buyers needing fast access to specialized grades. Specialty stores maintain demand from technical users who prefer expert-guided product selection. It supports flexible sourcing across diverse customer segments.
Segmentation:
By Type
- One-component polysulfide sealants
- Two-component polysulfide sealants
- Gun grade
- Pour grade
By Application
- Construction
- Commercial buildings
- Civil engineering
- Infrastructure (roads, bridges, tunnels)
- Automotive
- Woodworking
- Textile
- Others
By End-use Industry
- Residential
- Commercial
- Industrial
By Distribution Channel
- Direct sales
- Distributors
- Online retailers
- Specialty stores
By Region / Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a leading share of the Polysulfide construction sealant market, supported by strong infrastructure renewal programs. The region maintains high adoption across commercial buildings and transport networks with strict sealing standards. It benefits from advanced construction practices that require long-life joint protection. Demand increases in airports, bridges, and public facilities due to heavy structural stress. Suppliers operate well-established distribution networks across the United States and Canada. Market growth remains stable due to frequent maintenance cycles and rising waterproofing needs.
Europe
Europe secures a significant market share driven by strict regulatory norms and widespread use of high-performance sealing materials. The region invests heavily in heritage restoration, commercial renovation, and industrial upgrades. The Polysulfide construction sealant market supports projects targeting thermal movement control and moisture protection. Contractors prefer long-lasting formulations for façades, tunnels, and water-retaining structures. Demand expands with rising emphasis on energy-efficient buildings across Germany, the UK, and France. Strong compliance requirements sustain long-term consumption across public and private construction zones.
Asia-Pacific, Latin America, and Middle East & Africa
Asia-Pacific represents the fastest-growing share due to rapid urbanization, large-scale infrastructure programs, and industrial expansion. Demand rises across China, India, and Southeast Asia where high humidity and temperature shifts require elastic sealing materials. The Polysulfide construction sealant market gains traction through increasing construction of bridges, highways, and commercial complexes. Latin America holds a developing share supported by growing investment in residential and light commercial projects. The Middle East & Africa expand steadily with demand from industrial hubs and climate-exposed structures. Rising mega-projects in Gulf countries strengthen long-term adoption.
Key Player Analysis:
- Pecora Corporation
- Euclid Chemical
- Coastal Construction Products
- NEDEX GROUP
- AkzoNobel
- Fosroc Inc.
- Sika AG
- Henkel AG & Co. KGaA
- B. Fuller
- Trelleborg AB
Competitive Analysis:
The Polysulfide construction sealant market shows strong competition driven by performance upgrades, wider distribution reach, and targeted expansion across infrastructure and industrial segments. Leading companies focus on durable formulations that support long-life sealing in demanding environments. It benefits from suppliers that invest in high-adhesion compounds for bridges, tunnels, and commercial façades. Major brands strengthen market presence through supply chain alignment and contractor-focused product support. New entrants face pressure from established companies with long-standing regulatory compliance and technical certifications. Strategic pricing, product reliability, and wide application coverage influence competitive positioning. Vendors continue to expand across North America, Europe, and Asia-Pacific through technical partnerships and distribution agreements.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Application, By End-use Industry, and By Distribution Channel segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise for high-flexibility sealants used in bridges, runways, and civil structures.
- Adoption will strengthen across commercial façades due to higher movement-tolerance needs.
- Industrial operators will expand use in chemical and water-retaining facilities requiring strong resistance.
- Product innovation will focus on low-VOC and safer formulations aligned with compliance norms.
- Distribution networks will widen through hybrid models combining direct sales and digital channels.
- Contractors will prefer formulations that deliver predictable curing and long-term durability.
- Infrastructure upgrades in Asia-Pacific will reinforce regional growth momentum.
- Repair and maintenance cycles will support steady consumption across aging structures.
- Marine and specialty projects will adopt more high-adhesion polysulfide solutions.
- R&D teams will invest in advanced bonding chemistries to support next-generation construction methods.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Strong Demand for Long-Life Joint Protection in Infrastructure and Commercial Buildings
Polysulfide sealants are increasingly specified for bridges, runways, façades, and tanks due to their long-term elasticity and ability to maintain bond strength under heat, moisture, and chemical exposure, supporting safer and more durable structures.
Growing Need for High Chemical Resistance in Industrial and Utility Projects
Industrial operators and utility agencies adopt polysulfide sealants for their stable performance against fuels, solvents, and aggressive compounds, reducing maintenance downtime and ensuring safety in regulated environments such as chemical plants and water treatment facilities.
Expansion of Modern Construction Practices Requiring Elastic and Movement-Tolerant Materials
Modern architecture and prefabricated construction methods require sealants that adapt to thermal shifts and structural motion; polysulfide sealants provide the necessary flexibility and mechanical stability for these advanced building designs.
Rising Focus on Water-Retaining and Weather-Exposed Structures Needing Strong Moisture Barriers
Municipal agencies and builders use polysulfide sealants in dams, reservoirs, and façades exposed to harsh weather, leveraging their UV, ozone, and moisture resistance to prevent leaks and extend service life in challenging environments.
Shift Toward Advanced, Low-VOC Formulations for Environmental and Worker Safety
Stricter emission norms and green-building certifications are driving demand for low-VOC polysulfide sealants, prompting manufacturers to innovate with safer, environmentally friendly products that meet evolving regulatory and sustainability standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Polysulfide construction sealant market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polysulfide construction sealant market projected to grow between 2024 and 2032?
Which segment held the largest share in the Polysulfide construction sealant market in 2024?
What are the primary factors fueling the growth of the Polysulfide construction sealant market?
Who are the leading companies in the Polysulfide construction sealant market?
Which region commanded the largest share of the Polysulfide construction sealant market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 One-component polysulfide sealants
- 1.2.2 Two-component polysulfide sealants (Gun grade)
- 1.2.3 Two-component polysulfide sealants (Pour grade)
- 1.3 By Application
- 1.3.1 Construction (Commercial buildings, Civil engineering, Infrastructure)
- 1.3.2 Automotive
- 1.3.3 Woodworking
- 1.3.4 Textile
- 1.3.5 Others
- 1.4 By End-use Industry
- 1.4.1 Residential
- 1.4.2 Commercial
- 1.4.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,147.15 million → 2032: USD 1,487.38 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polysulfide Construction Sealant Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polysulfide Construction Sealant Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polysulfide Construction Sealant Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polysulfide Construction Sealant Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polysulfide Construction Sealant Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polysulfide Construction Sealant Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polysulfide Construction Sealant Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polysulfide Construction Sealant Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,147.15 million → 2032: USD 1,487.38 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polysulfide Construction Sealant Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 One-component polysulfide sealants
- 12.3.7.2 Two-component polysulfide sealants (Gun grade)
- 12.3.7.3 Two-component polysulfide sealants (Pour grade)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Construction (Commercial buildings, Civil engineering, Infrastructure)
- 12.4.7.2 Automotive
- 12.4.7.3 Woodworking
- 12.4.7.4 Textile
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial
- 12.5.7.3 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polysulfide Construction Sealant End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polysulfide Construction Sealant Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polysulfide Construction Sealant Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polysulfide Construction Sealant Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pecora Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Euclid Chemical
- 18.4 Coastal Construction Products
- 18.5 NEDEX GROUP
- 18.6 AkzoNobel
- 18.7 Fosroc Inc.
- 18.8 Sika AG
- 18.9 Henkel AG & Co. KGaA
- 18.10 H.B. Fuller
- 18.11 Trelleborg AB
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

