
Heat-killed strains move from Japan into global brands
The global postbiotic supplements market was valued at USD 198.6 million in 2025 and is projected to increase from USD 220.8 million in 2026 to USD 574.1 million by 2035, registering a CAGR of 11.20% during 2026–2035. Demand comes from adults who want immune and digestive support in a tablet, capsule or chew that needs no refrigeration, and from brands that can add inactivated bacteria to formats where live strains would die. Asia Pacific held the largest regional share, 48.0% in 2025, and is also the fastest-growing region at 11.6% a year, because Japanese makers have sold heat-killed lactic acid bacteria tablets for years. North America follows with 28.0%, built on yeast fermentates and pasteurized strains sold under dietary supplement rules. The main commercial change is that probiotic strain owners now launch inactivated versions of their own strains, while the main restraint is that the European Union still accepts no gut or immune claim for these ingredients.
Which products count as a postbiotic supplement?
The market counts finished dietary supplements in which the active ingredient is a preparation of inanimate microorganisms or their components, such as heat-killed lactic acid bacteria, pasteurized Akkermansia, yeast fermentates and butyrate blends, valued at the price the brand owner receives. Brands buy the ingredient from strain owners on supply contracts, then sell capsules, tablets, powders and chews through drugstores, online stores and practitioners.
Postbiotic drinks, yogurts, fortified foods, cosmetics, pet products and feed additives are excluded, although several strain owners sell the same ingredient into those uses. Combination products that pair live probiotics with a postbiotic are counted when the postbiotic is named on the label as an active ingredient.
Postbiotic Supplements Market Insights
- The market is projected to rise from USD 198.6 million in 2025 to USD 574.1 million by 2035 at 11.20% a year, with chewable formats and weight management claims adding the most new value.
- Asia Pacific held 48.0% of 2025 value and grows fastest at 11.6% a year, as Japanese heat-killed lactic acid bacteria brands expand abroad.
- Immune Support led applications with 41.0% of 2025 value, because the largest postbiotic brands were built on immune clinical trials.
- Kirin's iMUSE supplement sales rose about 30% in 2025 and overseas LC-Plasma ingredient shipments about 50%, according to the company.
- Probi launched Rham271h, its first postbiotic, at Vitafoods Europe in May 2026, joining Kerry and dsm-firmenich in selling inactivated strains.
Immune tablets lead while chews and weight claims grow
Why do capsules and tablets hold most postbiotic value?
Based on form, the market is categorized into capsules and tablets, powder and granules, and soft-gel and chews. Capsules and Tablets led with 54.0% of 2025 value because the main clinical doses fit one small unit, such as the 500-milligram EpiCor capsule and Kirin iMUSE tablets sold in 30-day packs. Soft-gel and Chews grow fastest at 12.6% a year, as inactivated strains survive heat and moisture, and Concordix said in September 2026 that it would show chewable postbiotic concepts using Kerry and dsm-firmenich strains at SupplySide Global. Brands moving into chews gain shelf space in children and beauty ranges, while powder sticks stay strongest in Japan.
Why does immune support lead postbiotic applications?
Based on application, the market is categorized into immune support, gut and digestive health, metabolic and weight management, and skin, mood and others. Immune Support led with 41.0% of 2025 value because the two largest postbiotic brands, Kirin LC-Plasma and Cargill EpiCor, were built on immune trials, and Cargill lists seven human immune studies for EpiCor. Metabolic and Weight Management grows fastest at 13.1% a year, as a 2026 Nature Medicine trial in 90 adults found that those taking pasteurized Akkermansia regained 1.2 kilograms over a 24-week maintenance phase, against 3.2 kilograms on placebo. Brands with human metabolic data can charge the highest daily prices.
How do buyers reach postbiotic products across channels?
Based on distribution channel, the market is categorized into drug stores and pharmacies, online retail, health and beauty stores, and supermarkets and hypermarkets. Drug Stores and Pharmacies led with 35.0% of 2025 value because Japanese chains carry the largest brands, and Tsuruha lists three 30-day packs of Kirin iMUSE immune care tablets at JPY 7,798. Online Retail grows fastest at 12.6% a year, as Kirin and Blackmores launched an LC-Plasma powder on Blackmores Taiwan e-commerce in March 2025 and U.S. Akkermansia capsules sell mainly through online and practitioner stores. Online sellers gain repeat subscriptions, while supermarkets carry few postbiotic lines.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Form | Capsules and Tablets | 54.0% | Soft-gel and Chews | 12.6% |
| By Application | Immune Support | 41.0% | Metabolic and Weight Management | 13.1% |
| By Distribution Channel | Drug Stores and Pharmacies | 35.0% | Online Retail | 12.6% |
Akkermansia costs over four times a yeast fermentate daily
Brands price postbiotic products per daily serving, and the spread follows the clinical evidence and the cost of growing the strain. A yeast fermentate such as EpiCor works out to about USD 0.45 a day at list price, while pasteurized Akkermansia, an anaerobic organism that is hard to grow at scale, costs about USD 2.05 a day. Japanese heat-killed lactic acid bacteria tablets sit between them at about JPY 87 a day. Price moves with fermentation yields, licensing fees paid to strain owners and the strength of approved claims, so brands with exclusive human data keep the widest margins, while blends that add a small postbiotic dose compete on price.
| Offer or segment | Typical price or fee | Basis |
|---|---|---|
| Pasteurized Akkermansia capsules, 30 x 150 mg | USD 61.43 per bottle | Vitacost list price, November 2026 |
| EpiCor yeast fermentate capsules, 60 x 500 mg | USD 27.19 per bottle | Swanson list price, November 2026 |
| Kirin iMUSE immune care tablets, three 30-day packs | JPY 7,798 per set | Tsuruha online list price, November 2026 |
| Prebiotic, probiotic and butyrate postbiotic capsules, 60 count | USD 44.95 per bottle | MaryRuth's list price, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Stability, Japanese immune brands and new trials lift use
Shelf stability lets brands use formats closed to live strains
Inactivated bacteria do not need to stay alive in the bottle, so brands can put them into tablets, gummies and drinks that would kill most live probiotics. The International Scientific Association for Probiotics and Prebiotics, writing in Nature Reviews Gastroenterology & Hepatology, defined a postbiotic in May 2021 as a preparation of inanimate microorganisms and their components that confers a health benefit on the host. Cargill states a three-year shelf life for EpiCor postbiotic and cites more than 15 published studies behind it. Morinaga Milk said in September 2025 that its heat-killed MCC1848 strain is already used in more than 100 Japanese products, including candies and vinegar drinks, which widens demand beyond capsules. Contract makers lacking cold storage gain most, because they can run postbiotic lines on standard tablet and gummy equipment.
Japanese immune brands are scaling heat-killed bacteria
Japanese companies built the largest consumer base for postbiotic products by selling heat-killed lactic acid bacteria as everyday immune care, and that base is now growing abroad. Kirin reported that sales of its iMUSE supplement series rose about 30% in 2025 and FANCL Meneki Support about 20%, while its LC-Plasma strain is now sold by 12 partner companies in 24 functional food products. Kirin and Blackmores also developed an LC-Plasma powder together, showing that the strain now travels beyond Japanese brands. Brand owners in Asia that license proven Japanese strains gain a faster route to market than those funding new trials.
Metabolic trials give postbiotics a new claim base
Weight and glucose support is becoming the second claim base for postbiotic products, because inactivated strains now carry regulatory approvals and controlled trial data in this area. Commission Implementing Regulation (EU) 2022/168 authorized pasteurised Akkermansia muciniphila as a novel food in February 2022, for food supplements used by adults at up to 34 billion cells a day. ADM says its heat-treated HT-BPL1 strain showed results similar to the live BPL1 strain, which reduced waist circumference in 2 clinical studies, and in August 2021 it launched HT-BPL1 in Nourished 3D-printed gummies in the U.K. The 2026 Nature Medicine result noted in the segment section adds human weight maintenance data and supports adoption. Strain owners holding metabolic data gain pricing power over immune-only rivals.
Older adults form the largest buying group
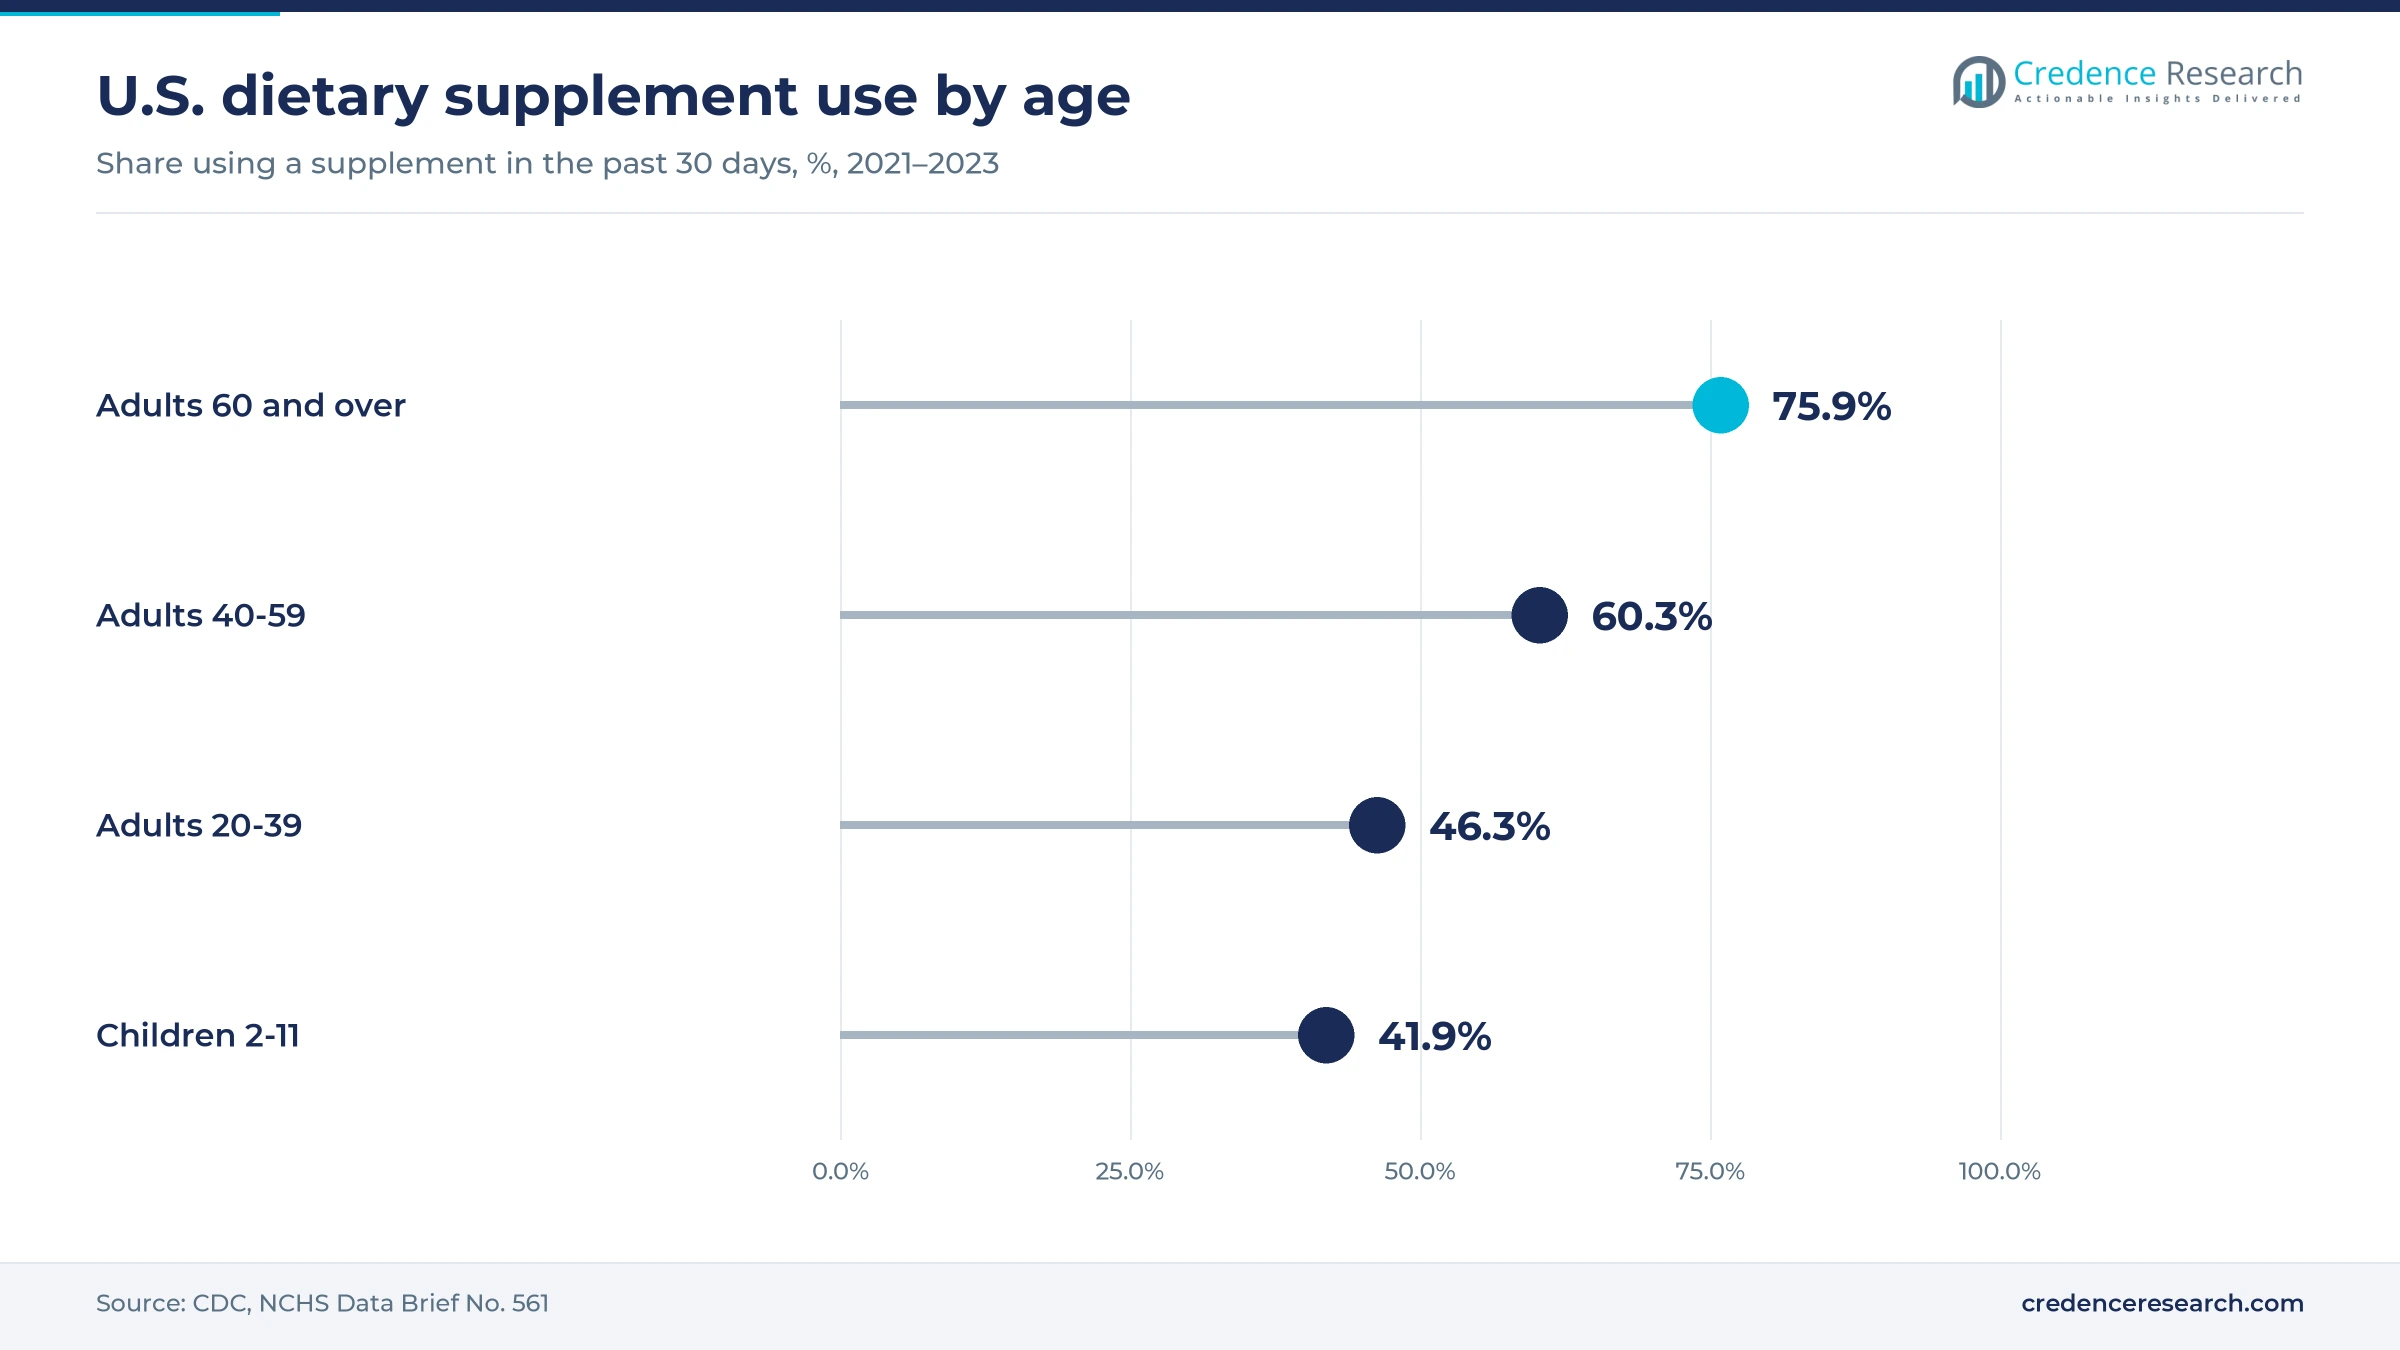
Supplement use rises sharply with age, and postbiotic suppliers are aiming at older buyers with muscle, immune and mobility claims. The CDC reported in May 2026 that 75.9% of U.S. adults aged 60 and over used a dietary supplement in 2021–2023, against 46.3% of adults aged 20 to 39. Women used supplements more than men, at 66.1% against 53.9%. dsm-firmenich said in February 2026 that two human trials of its Humiome Post LB strain in adults aged 55 and over were under way. Brands selling to older adults gain a large, repeat-buying group, provided they can cite human data for the claim.
Strain owners launch inactivated twins of probiotics
Probiotic strain owners are launching inactivated twins
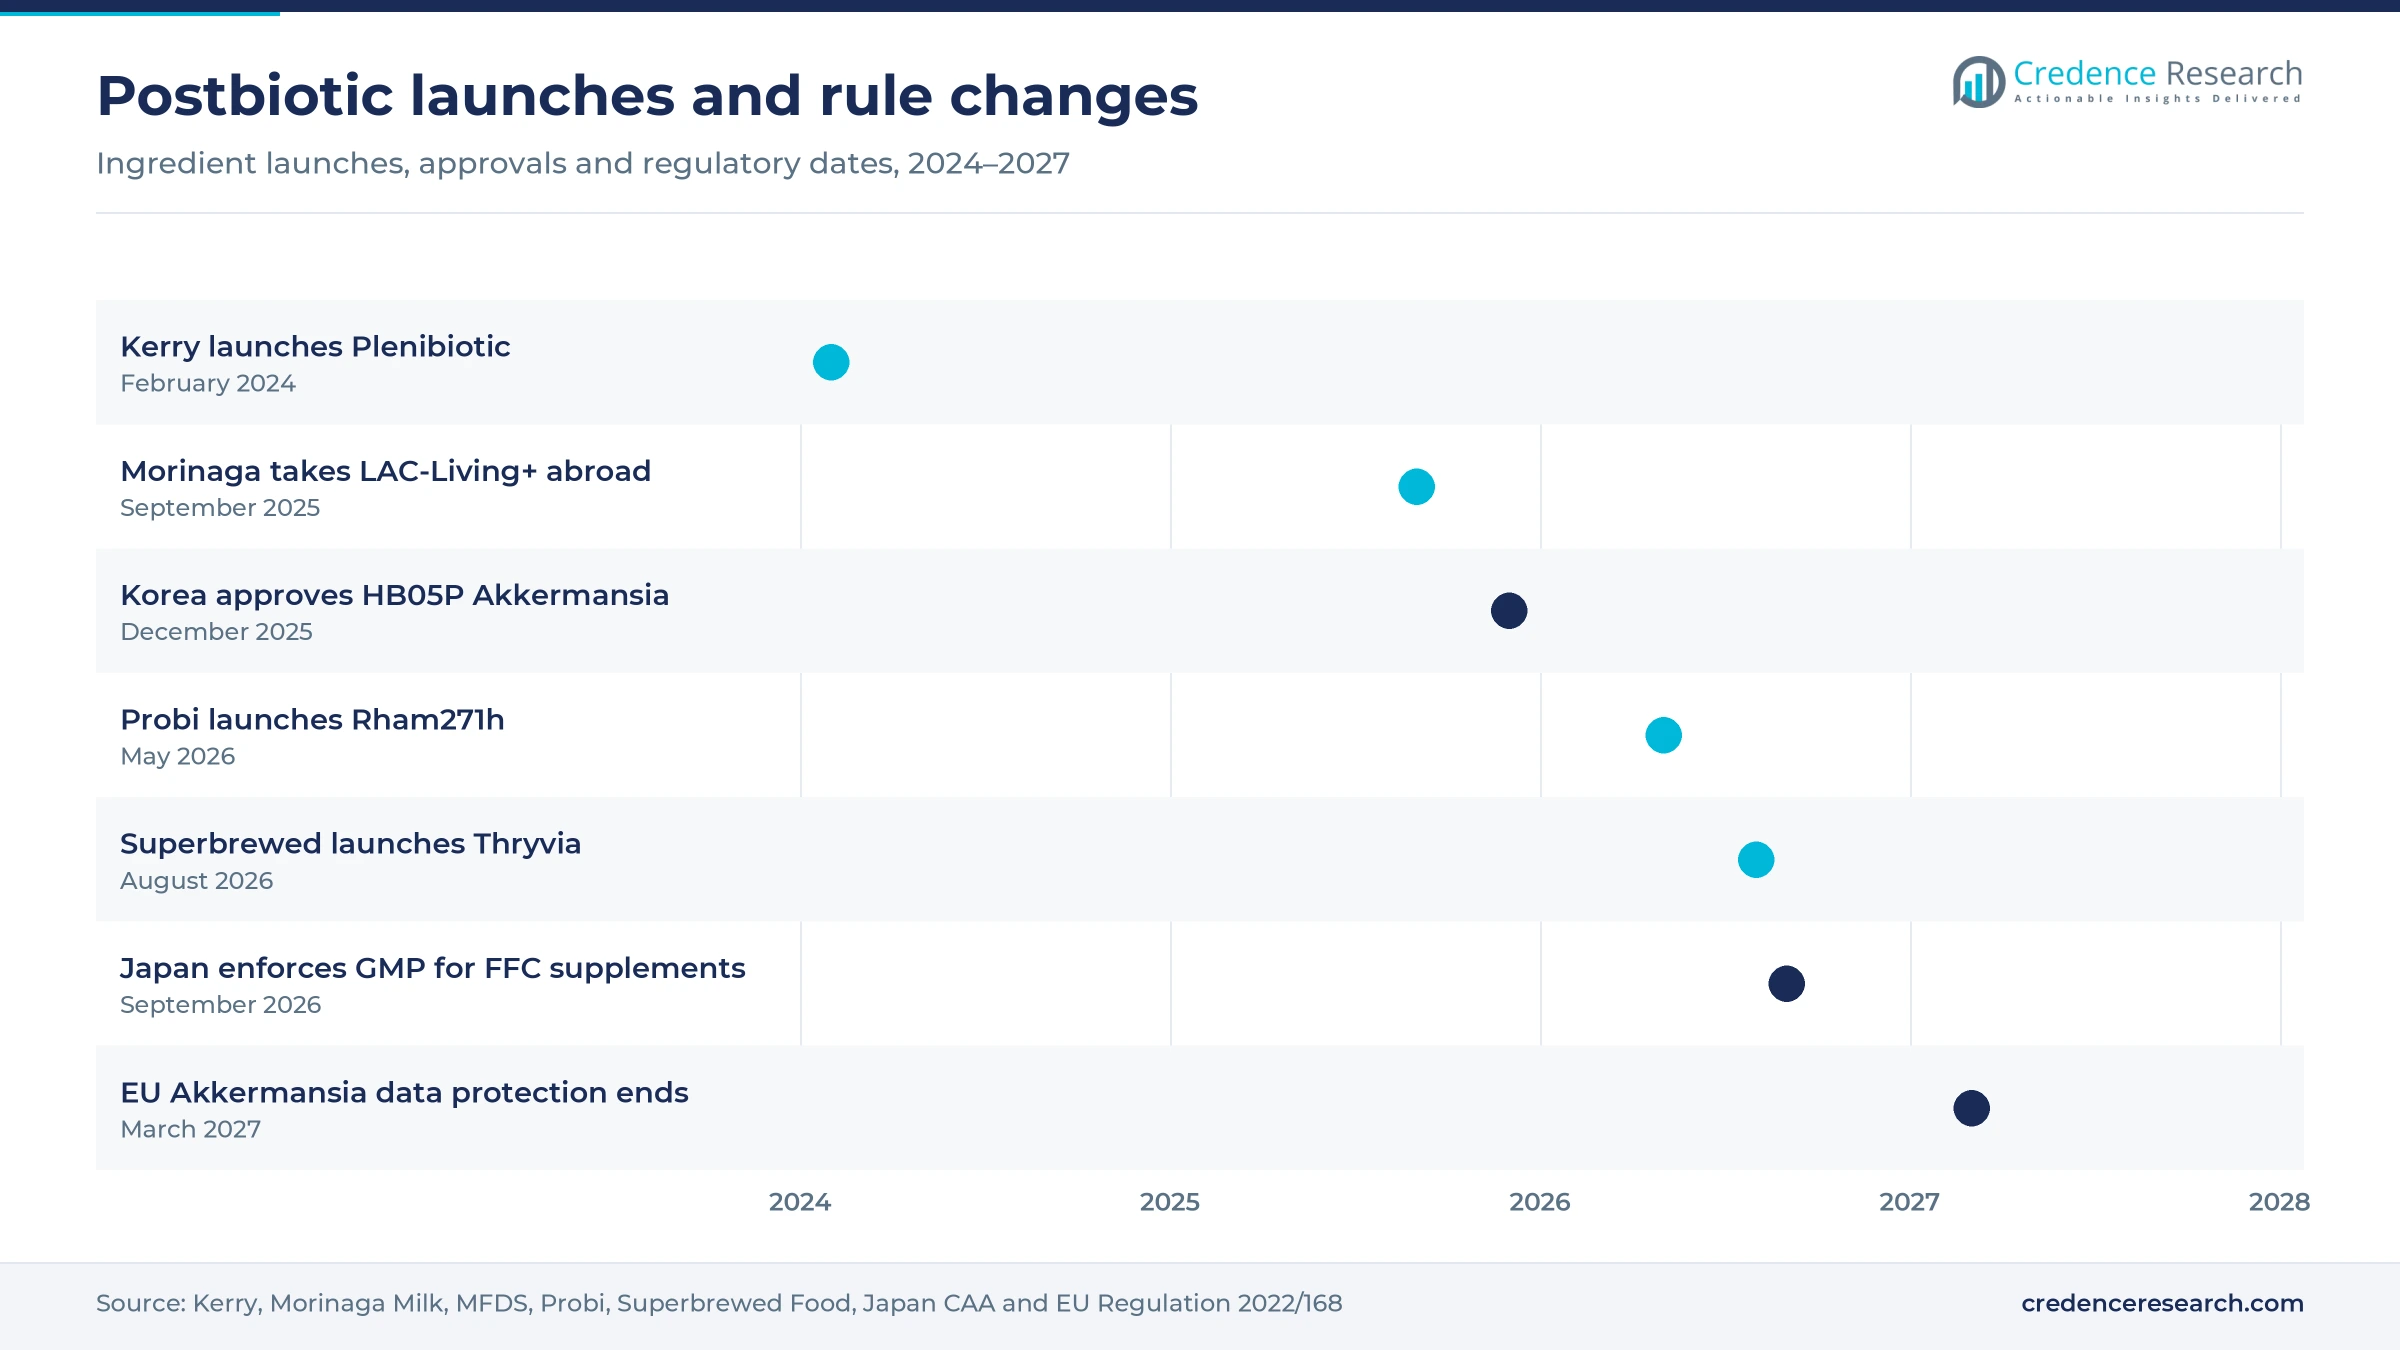
Probiotic suppliers are shifting toward inactivated versions of their own clinically studied strains to address brand demand for heat-stable formats, creating openings for postbiotic lines across tablets, gummies and drinks. Probi announced on May 5, 2026, that it had launched Rham271h, its first postbiotic, at Vitafoods Europe, based on its Lacticaseibacillus rhamnosus 271 strain. Kerry launched Plenibiotic, its first postbiotic ingredient, made from Lactobacillus casei 327, in February 2024 for gut and skin health in humans and pets. dsm-firmenich sells Humiome Post LB, a heat-treated blend of L. delbrueckii and L. fermentum. Strain owners reuse existing safety and strain data, which cuts development time, while newcomers without a strain library find it harder to compete.
Mood and cognition claims are emerging beside immune care
Ingredient suppliers are shifting postbiotic positioning toward mood and cognition to address buyers who already take immune products, creating openings in stress and sleep ranges. Morinaga Milk launched LAC-Living+, a heat-killed Lactobacillus helveticus MCC1848 ingredient, for international markets in September 2025, starting in Asia Pacific. Two 4-week placebo-controlled trials at 5 billion heat-killed cells a day, one in Brain Sciences with 46 nursing students and one in Beneficial Microbes with 58 participants, reported better positive emotion scores, although negative emotion scores did not change. The dsm-firmenich trials in older adults also assess cognition, with results expected in the second half of 2026. Evidence remains small and short, so brands that make mood claims carry more regulatory risk than immune brands do.
A second pasteurized Akkermansia supply is an opening
Brands that want pasteurized Akkermansia but cannot license the first supplier are an underserved customer group, and a second source is now forming. HealthBiome says it holds FDA new dietary ingredient acknowledgments for its HB05P pasteurized Akkermansia, the first received in December 2024. Korea's Ministry of Food and Drug Safety approved HB05P as a functional ingredient, No. 2025-71, on Dec. 24, 2025, with a claim that it may help maintain muscle strength affected by aging. HealthBiome plans capsule launches in Korea and the U.S. in 2026 and B2B supply deals. In the EU, Regulation 2022/168 keeps data protection for the first authorized supplier until March 1, 2027, which opens that market to other applicants.
Children's gummies are an opening for immune postbiotics
Parents buying immune products for school-age children are an underserved group, because postbiotic chews avoid live cultures and fit gummy formats. A Cargill-funded trial in Pediatric Research gave 256 Canadian children aged 4 to 12 a daily 500-milligram EpiCor gummy through the 2022–2023 cold season, and children on placebo were 1.7 times more likely to use medication. The CDC found that 41.9% of U.S. children aged 2 to 11 used a supplement in 2021–2023. MaryRuth's already sells an organic kids multivitamin gummy with two postbiotic strains. Brands with pediatric data can enter functional jellies and gummies ranges, although child claims face tighter review.
Claim rules, GMP costs and thin evidence slow growth
European claim rules block gut and immune wording
The EU treats the word probiotic as a health claim, and FoodNavigator reported in January 2025 that EFSA has substantiated no specific probiotic health claim. Postbiotic brands therefore cannot state gut or immune benefits on EU labels unless an authorized vitamin or mineral claim sits on the product. About 10 member states have national guidance allowing the term, which splits the market by country. European brands and importers are most exposed, because they must market through science content rather than labels.
Japanese GMP rules raise costs for small brands
Japan made Good Manufacturing Practice mandatory for tablet, capsule and powder products sold under Foods with Function Claims, with enforcement from Sept. 1, 2026. The rule followed the Kobayashi red yeast rice case, which had reached 1,614 medical cases and five deaths by May 2024. The rule adds plant audits and adverse event reporting, which raise fixed costs for every supplement line. Small Japanese brands without certified plants are most exposed, while contract manufacturing firms gain orders.
Thin human evidence weakens newer ingredients
Many postbiotic ingredients reach shelves with safety files but little human efficacy data, which limits what brands can claim and buyers can trust. Superbrewed Food launched Thryvia, a heat-killed Clostridium tyrobutyricum ingredient, in August 2026, backed by an FDA GRAS letter of February 2024 that covers use as a protein source. Its human study measured perceived digestive comfort over four weeks, without a disclosed sample size. Brands using such ingredients are exposed if regulators or retailers ask for clinical support.
No common dose unit makes products hard to compare
Postbiotic labels state doses in different units, so buyers cannot compare products, and this slows retailer listing. Probi sets a minimum effective dose of 10 billion TFU for Rham271h, The Akkermansia Company labels 30 billion TFU per capsule, and Morinaga uses 5 billion heat-killed cells a day. No regulator has adopted a standard count for inactivated cells, and Credence Research found no official testing method for them. Smaller brands buying unbranded material are most exposed to quality disputes.
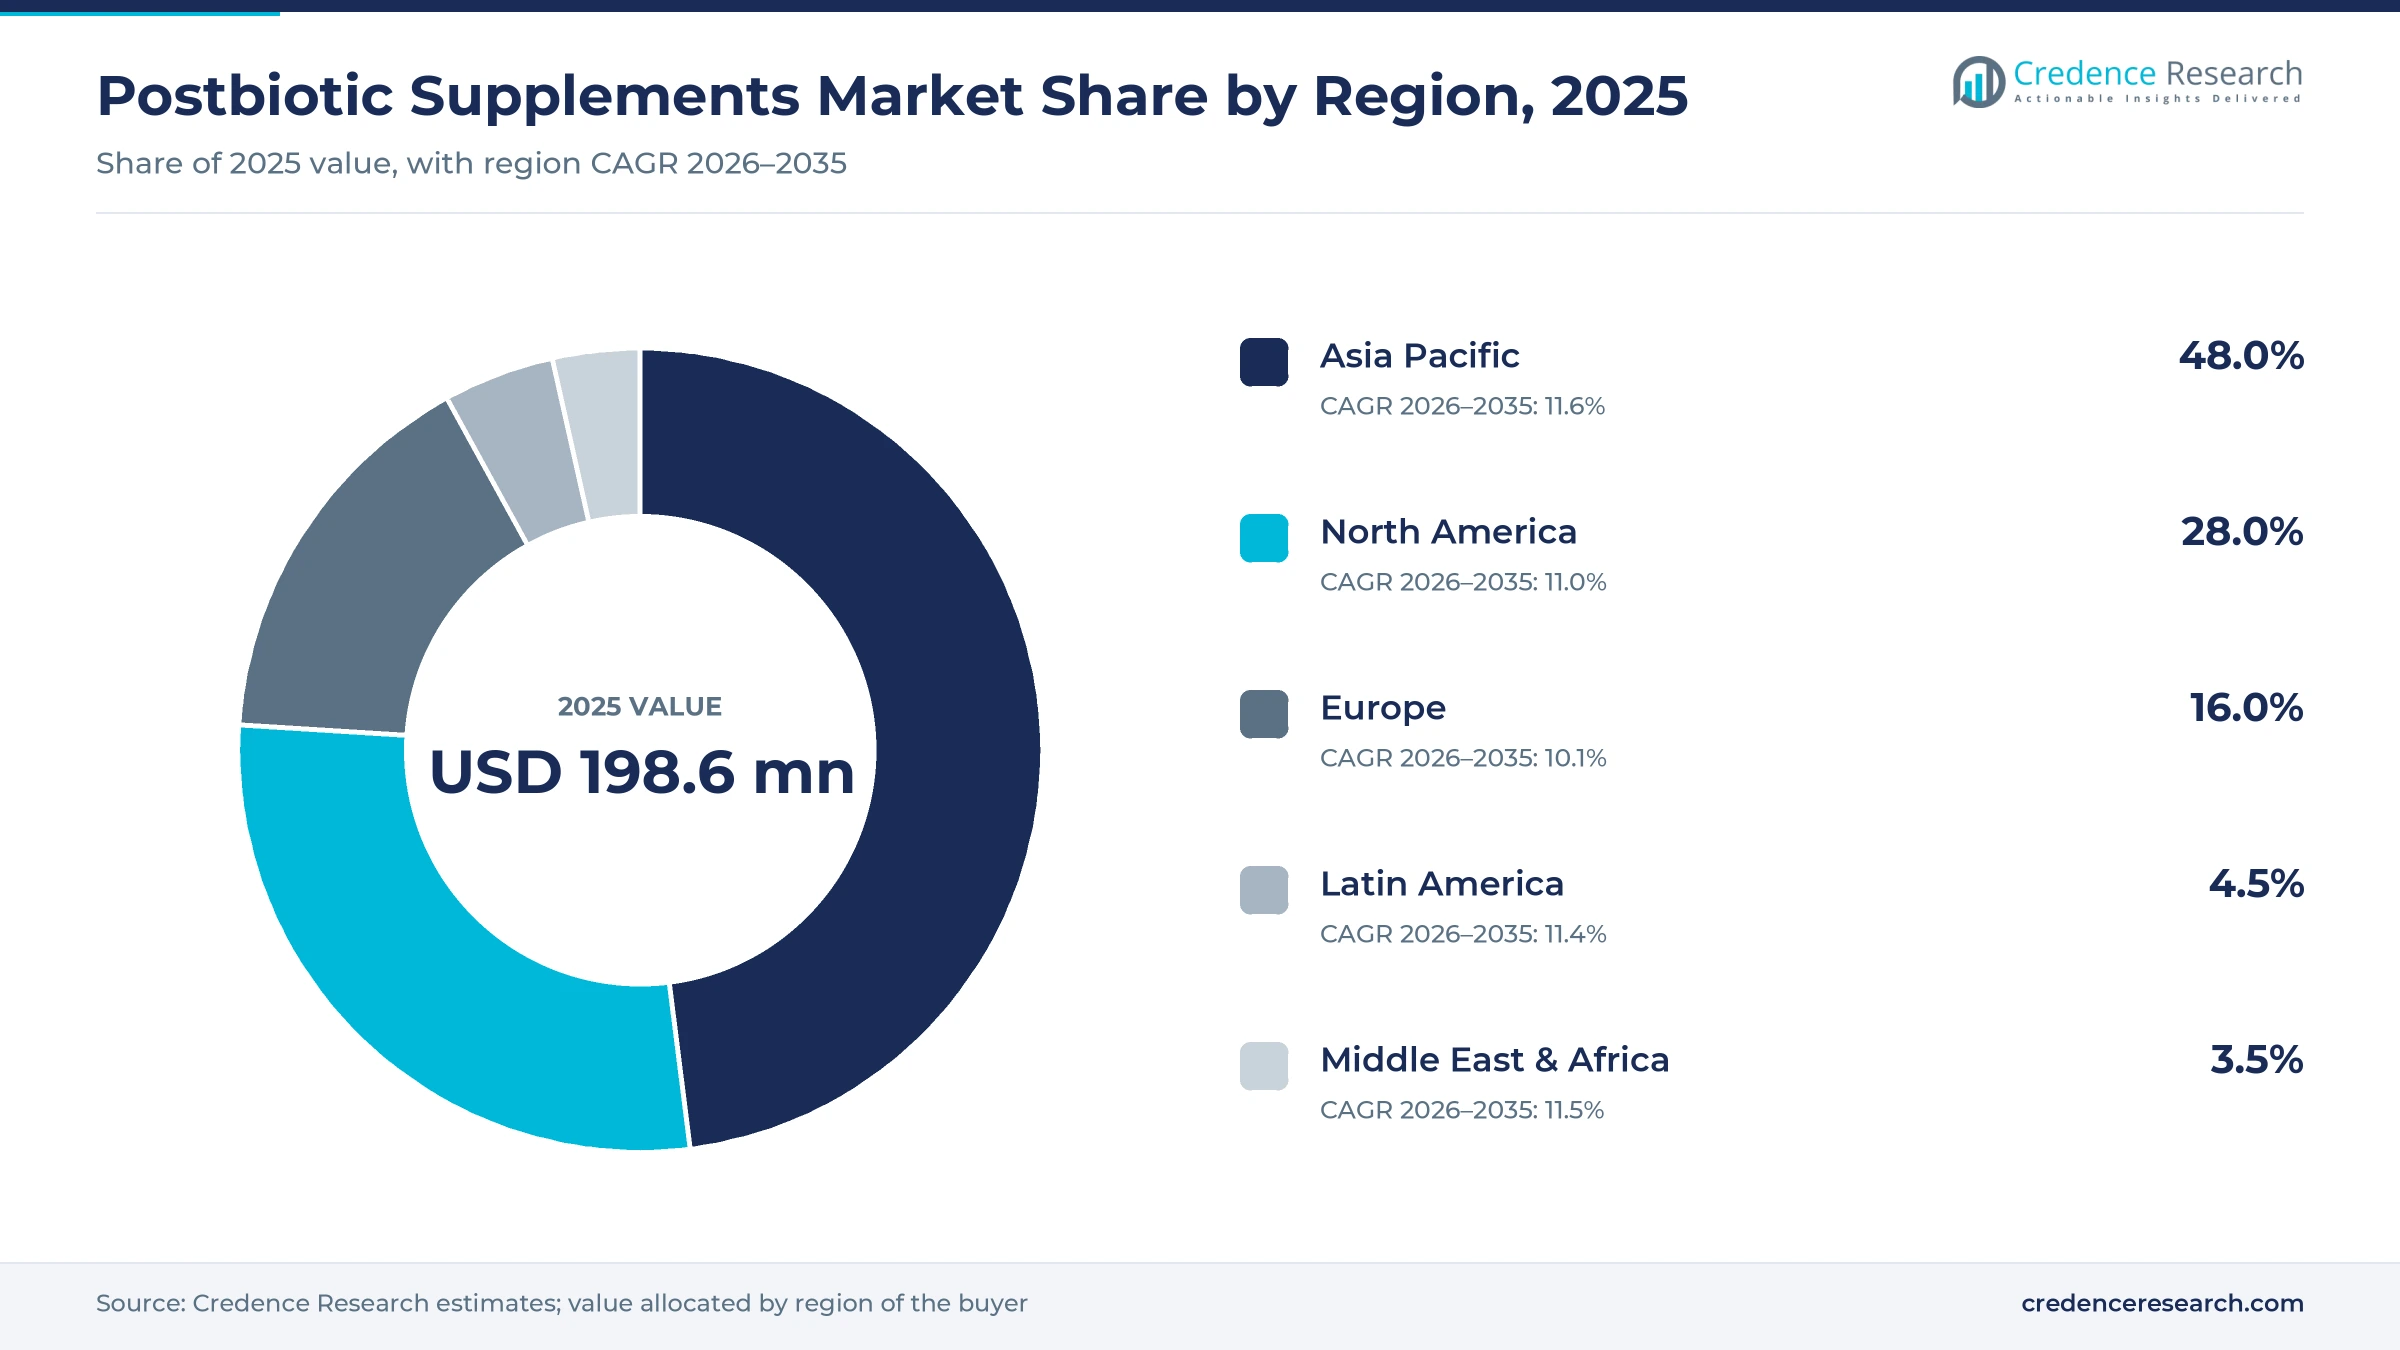
Asia Pacific leads on Japanese heat-killed bacteria
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Asia Pacific | 95.3 | 48.0% | 11.6% |
| North America | 55.6 | 28.0% | 11.0% |
| Europe | 31.8 | 16.0% | 10.1% |
| Latin America | 8.9 | 4.5% | 11.4% |
| Middle East & Africa | 7.0 | 3.5% | 11.5% |
Asia Pacific leads on Japanese heat-killed bacteria
Asia Pacific held 48.0% of 2025 postbiotic supplements value and grows fastest at 11.6% a year. This lead exists because Japan has the longest history of heat-killed lactic acid bacteria tablets and Kirin and Morinaga now export their strains. Japanese drugstores carry immune tablets beside vitamins, and Korea opened a functional ingredient route with the HB05P approval. Credence Research puts Japan at about 75% of regional value. The September 2026 GMP rule will remove some small Japanese brands, which favors large brand owners.
North America grows on yeast fermentates and Akkermansia
North America held 28.0% of 2025 postbiotic supplements value and grows at 11.0% a year. The U.S. leads the region, because dietary supplement rules let brands launch new postbiotics after a GRAS letter or a new dietary ingredient notification. Cargill makes EpiCor in the U.S., and The Akkermansia Company sells pasteurized Akkermansia capsules through online and practitioner channels. High supplement use among adults over 60 supports immune and muscle claims. Credence Research puts the U.S. at about 88% of regional value.
Europe is held back by claim rules
Europe held 16.0% of 2025 postbiotic supplements value and grows at 10.1% a year, the slowest regional rate. Growth lags because brands cannot print gut or immune claims for these ingredients. The region still hosts major strain owners, including Kerry in Ireland, Probi in Sweden and dsm-firmenich, which sell postbiotic ingredients worldwide. Pasteurized Akkermansia is the only postbiotic with an EU novel food authorization for supplements, and wider supply after March 2027 is the main upside for European brands.
Latin America buys imported brands
Latin America held 4.5% of 2025 postbiotic supplements value and grows at 11.4% a year. Demand is concentrated in Brazil and Mexico through imported U.S. and Japanese brands and local brands buying ingredients from global suppliers. Credence Research found no regional postbiotic strain producer and no public sales data, so this estimate rests on import prices and the regional share of supplement sales. That remains an evidence gap for any buyer sizing the region. Online marketplaces are the main route for new brands entering Brazil and Mexico.
Middle East and Africa remains a small import market
Middle East & Africa held 3.5% of 2025 postbiotic supplements value and grows at 11.5% a year. Demand comes from imported immune and gut products sold in Gulf pharmacies and South African health stores. Credence Research found no local postbiotic production and no public sales data, so the estimate rests on imports of finished goods. Brands with halal certificates, such as EpiCor, which Cargill lists as Certified Halal, are better placed to win Gulf pharmacy listings.
Launches and approvals marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In February 2024, Kerry launched Plenibiotic, its first postbiotic ingredient, made from Lactobacillus casei 327 for gut and skin health. | Commercial launch; the ingredient is offered to supplement, food and pet brands. |
| In September 2025, Morinaga Milk launched LAC-Living+, a heat-killed Lactobacillus helveticus MCC1848 ingredient, for international markets. | Commercial launch with an initial Asia Pacific focus; the strain is already sold in Japan. |
| In December 2025, Korea's Ministry of Food and Drug Safety approved HealthBiome's HB05P pasteurized Akkermansia as a functional ingredient. | Regulatory approval; capsule launches in Korea and the U.S. are planned for 2026. |
| In May 2026, Probi launched Rham271h, the postbiotic version of its Rham271 strain, at Vitafoods Europe. | Commercial launch for supplement, food and beverage brands. |
| In August 2026, Superbrewed Food launched Thryvia, a heat-killed Clostridium tyrobutyricum ingredient, for digestive and immune products. | Commercial launch; further human studies are described as ongoing. |
Inactivation method and dose units decide quality
- Heat inactivation kills lactic acid bacteria while keeping cell wall parts that immune cells recognize, and it suits tablet and gummy lines.
- Pasteurization of anaerobic strains is used for Akkermansia, which is hard to keep alive outside the gut, and it gives a stable powder for capsules.
- Yeast fermentation produces whole fermentates such as EpiCor, which contain metabolites, cell wall fragments and proteins in one dried ingredient.
- Cell counting by TFU replaces colony counts for dead cells, but methods differ between suppliers, which complicates label comparison.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Ingredient owners compete on clinical files and claims
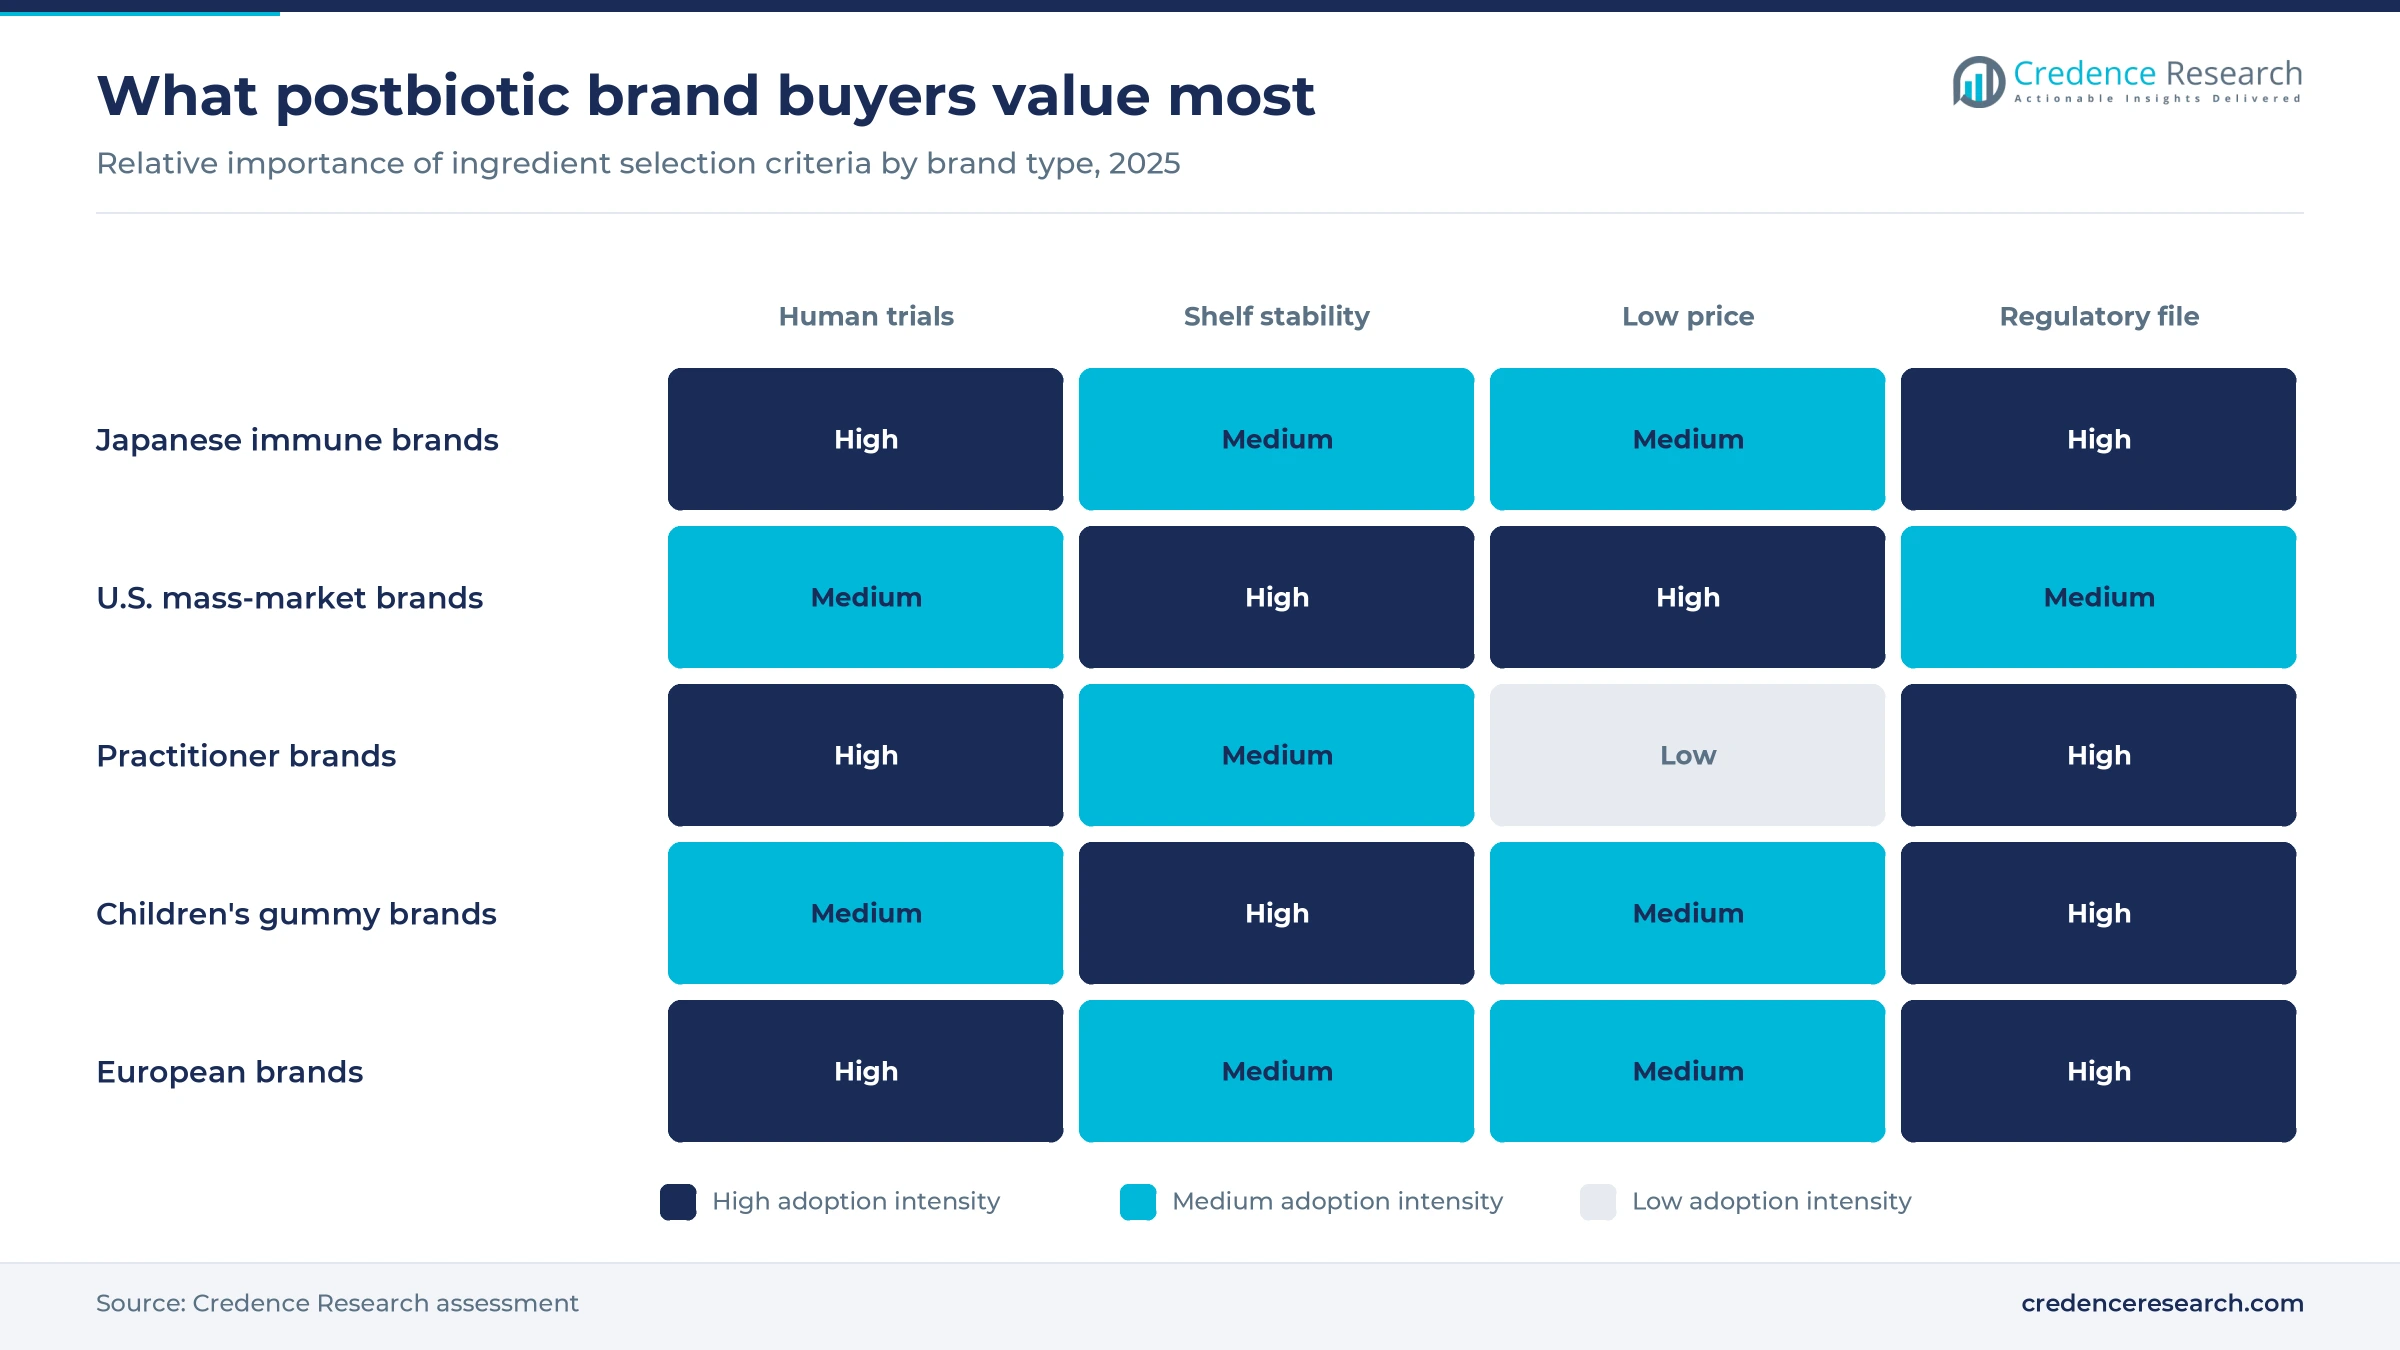
Competition splits between strain owners that sell branded ingredients and brands that build products around them. Kirin and Morinaga lead in Japan with heat-killed lactic acid bacteria, and Kirin also sells finished iMUSE products. Cargill supplies EpiCor to many U.S. brands, while ADM, Kerry, dsm-firmenich and Probi license inactivated strains from their probiotic libraries. The Akkermansia Company and HealthBiome compete in pasteurized Akkermansia, the highest-priced niche. Superbrewed Food is a new entrant with a heat-killed anaerobic strain. Finished brands such as MaryRuth's and Dr. Emil Nutrition combine postbiotics with prebiotics and probiotics in multi-ingredient formulas. Suppliers win through human trial data, regulatory files and stability, because brands need claims they can defend. Buyers should weigh exclusivity and claim support as heavily as ingredient price.
Strain owners with human trials hold the margin
Supply sits with a small group of strain owners, including Kirin, Cargill, ADM, Kerry, dsm-firmenich, Morinaga and Probi, which hold the clinical files and patents, and many brand owners that buy their ingredients. Entry barriers are high for strain owners because human trials and regulatory files take years, but low for brands that license a branded ingredient. Margins sit mostly with brands that hold exclusive human data and with strain owners that charge licensing fees, while unbranded blends compete on price.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Kirin Holdings Company, Limited | Strain owner and brand | LC-Plasma heat-killed Lactococcus lactis in iMUSE tablets and partner products |
| Cargill, Incorporated | Ingredient supplier | EpiCor yeast fermentate postbiotic sold to supplement brands |
| ADM | Ingredient supplier | HT-BPL1 heat-treated Bifidobacterium lactis for metabolic health products |
| Kerry Group plc | Ingredient supplier | Plenibiotic Lactobacillus casei 327 postbiotic for gut and skin health |
| dsm-firmenich | Ingredient supplier | Humiome Post LB heat-treated lactobacilli blend for digestive and healthy aging uses |
| Morinaga Milk Industry Co., Ltd. | Strain owner | LAC-Living+ heat-killed Lactobacillus helveticus MCC1848 for mood support |
| The Akkermansia Company | Specialist | Pasteurized Akkermansia muciniphila MucT capsules for weight and glucose support |
| Probi AB (Symrise) | Ingredient supplier | Rham271h inactivated Lacticaseibacillus rhamnosus 271 launched in 2026 |
| HealthBiome | Specialist | HB05P pasteurized Akkermansia with Korean muscle claim and U.S. NDI files |
| Superbrewed Food, Inc. | Specialist | Thryvia heat-killed Clostridium tyrobutyricum for digestive and immune products |
| MaryRuth's Organics | Brand owner | Kids multivitamin gummies with postbiotic strains and butyrate gut capsules |
| Dr. Emil Nutrition | Brand owner | Total Gut Complex capsules combining prebiotic, probiotic and postbiotic ingredients |
Clinical files matter more than live counts
Credence Research's view is that the postbiotic supplements market will be decided by clinical files rather than by cell counts, because inactivated strains cannot rely on the live-culture message that sold probiotics. Immune Support keeps 41.0% of 2025 value on Japanese and U.S. immune trials, but weight and muscle claims will add the most new value if human data hold. Strain owners with exclusive data and regulatory files will keep the best margins. Brands selling small postbiotic doses inside blends face price pressure and should expect closer questions from retailers.
Estimates rest on company disclosures and prices
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate was rebuilt from a bottom-up check of company sales disclosures, retail prices and supplement use statistics, which gave a much larger 2025 value, while the earlier growth rate was kept. Regional shares, segment splits and the Japanese supplement share are Credence Research estimates. Sources include regulator documents, company releases, health statistics and peer-reviewed trial reports; no interviews or surveys are claimed.
Metabolic and chewable formats carry growth to 2035
Metabolic and Weight Management should grow at 13.1% a year to 2035, the fastest application rate in postbiotic supplements. The market should reach USD 574.1 million by 2035, with immune products still the largest application and Asia Pacific the largest region. Growth through 2027 depends on human trial results for weight and muscle claims, the end of EU data protection for pasteurized Akkermansia and the effect of Japanese GMP rules. These projections are modeled estimates and would shift with regulatory decisions and trial outcomes.
Metabolic trial data and claim rules set the upside
The range depends mainly on how fast metabolic claims gain human evidence and on whether regulators in Europe and Japan ease or tighten claim and manufacturing rules. Strong weight maintenance data and new Akkermansia suppliers would lift prices and volumes, while a safety scare or weak trial results would push brands back toward cheaper live probiotics.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 9.2% | USD 487.6 million | Weak metabolic trial results and tighter claim rules push brands back to live probiotics |
| Base | 11.20% | USD 574.1 million | Steady immune demand, gradual metabolic adoption and more strain owners entering |
| Upside | 12.9% | USD 658.1 million | Positive weight maintenance trials and new Akkermansia suppliers widen adoption in the U.S. and Asia |
Frequently Asked Questions
How big is the postbiotic supplements market?
What is the size of the postbiotic food supplements market?
Who are the leading postbiotic suppliers and manufacturers?
Which postbiotic manufacturing companies launched new ingredients recently?
Why are postbiotic ingredients used in functional foods and chews?
Are shelf-stable postbiotic products more expensive than probiotics?
How large is the postbiotic market in Germany, France and Italy?
Which region leads the postbiotic supplements market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Capsules and Tablets
- 1.2.2 Powder and Granules
- 1.2.3 Soft-gel and Chews
- 1.3 By Application
- 1.3.1 Immune Support
- 1.3.2 Gut and Digestive Health
- 1.3.3 Metabolic and Weight Management
- 1.3.4 Skin, Mood and Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 198.6 million → 2035: USD 574.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Postbiotic Supplements Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Postbiotic Supplements Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Postbiotic Supplements Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Postbiotic Supplements Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Postbiotic Supplements Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Postbiotic Supplements Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Postbiotic Supplements Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Postbiotic Supplements Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 198.6 million → 2035: USD 574.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Postbiotic Supplements Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Capsules and Tablets
- 12.3.7.2 Powder and Granules
- 12.3.7.3 Soft-gel and Chews
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Immune Support
- 12.4.7.2 Gut and Digestive Health
- 12.4.7.3 Metabolic and Weight Management
- 12.4.7.4 Skin, Mood and Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Postbiotic Supplements End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Postbiotic Supplements Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Postbiotic Supplements Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Postbiotic Supplements Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kirin Holdings Company, Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cargill, Incorporated
- 18.4 ADM
- 18.5 Kerry Group plc
- 18.6 dsm-firmenich
- 18.7 Morinaga Milk Industry Co., Ltd.
- 18.8 The Akkermansia Company
- 18.9 Probi AB (Symrise)
- 18.10 HealthBiome
- 18.11 Superbrewed Food, Inc.
- 18.12 MaryRuth's Organics
- 18.13 Dr. Emil Nutrition
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

