
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Rodent Control Pesticides Market Size 2024 | USD 6050 Million |
| Rodent Control Pesticides Market, CAGR | 6.3% |
| Rodent Control Pesticides Market Size 2032 | USD 9863.28 Million |
Market Overview:
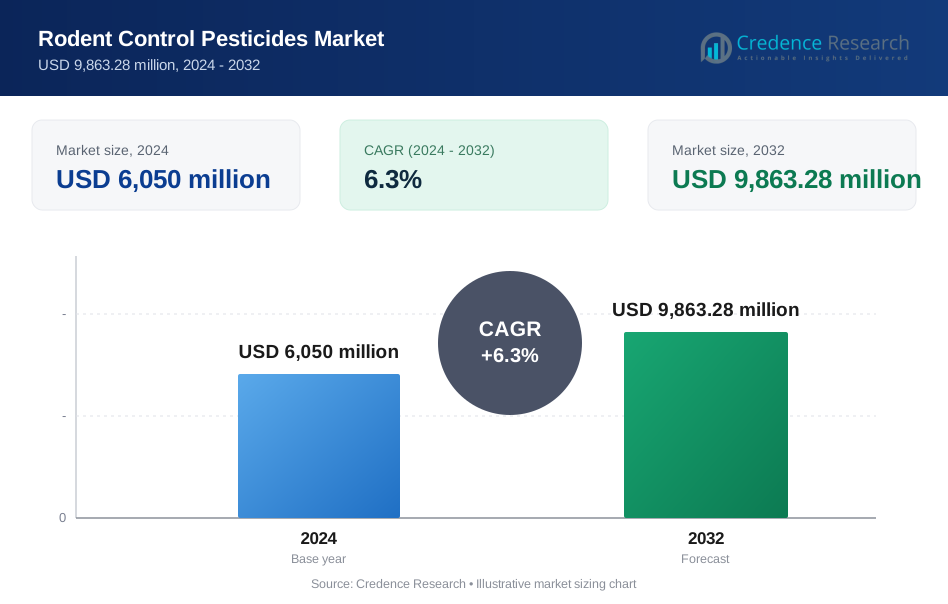
The Rodent Control Pesticides Market size was valued at USD 6050 million in 2024 and is anticipated to reach USD 9863.28 million by 2032, at a CAGR of 6.3% during the forecast period (2024-2032).
Market growth is primarily driven by rising rodent infestations due to urban expansion and climate change, which create favorable breeding conditions. The growing emphasis on food safety regulations and hygiene standards across industries such as food processing, hospitality, and healthcare is increasing the demand for rodent control solutions. Additionally, advancements in pesticide formulations, including eco-friendly and bio-based rodenticides, are supporting market expansion. Government initiatives promoting pest control measures and strict regulations against the use of harmful pesticides are further influencing the development of safer and more sustainable solutions. The rising adoption of automation and sensor-based rodent control systems is improving efficiency and reducing dependency on traditional chemical-based methods. Furthermore, increasing awareness among consumers regarding health risks associated with rodent infestations is driving demand for DIY pest control solutions.
Regionally, North America dominates the rodent control pesticides market, driven by stringent regulatory frameworks and high adoption rates across commercial and residential sectors. The Asia-Pacific region is expected to witness the highest growth rate, supported by rapid urbanization, increasing awareness of pest-related health risks, and expanding agricultural activities. Europe maintains a strong market position with a focus on sustainable and eco-friendly pest control solutions. Meanwhile, Latin America and the Middle East & Africa are experiencing moderate growth due to improving infrastructure and increasing investments in pest management solutions. The presence of global rodent control service providers in these regions is accelerating market development. Additionally, government initiatives promoting public health awareness and pest control programs are playing a crucial role in shaping regional market dynamics.
Market Insights:
- The market was valued at USD 6,050 million in 2024 and is projected to reach USD 9,863.28 million by 2032, growing at a CAGR of 6.3%.
- Rising rodent infestations due to urban expansion and climate change are key drivers increasing demand for rodenticides across residential, commercial, and agricultural sectors.
- The growing emphasis on food safety regulations in industries such as food processing, hospitality, and healthcare is fueling market growth.
- Advancements in pesticide formulations, including eco-friendly and bio-based rodenticides, are reshaping the industry amid increasing regulatory restrictions on toxic chemicals.
- The adoption of automation and sensor-based pest control systems is improving efficiency and reducing reliance on traditional chemical-based rodenticides.
- North America leads the market with a 35% share, while Asia-Pacific is expected to witness the highest growth, driven by rapid urbanization and expanding agricultural activities.
- Increasing consumer awareness about rodent-related health risks is boosting demand for DIY rodent control solutions and professional pest management services.
Market Drivers:
Rising Rodent Infestations Due to Urbanization and Climate Change:
The increasing prevalence of rodent infestations, driven by rapid urbanization and climate change, is a key factor fueling the demand for rodent control pesticides. Expanding urban areas create ideal conditions for rodents by providing abundant food sources and shelter, leading to higher infestation rates in residential, commercial, and industrial spaces. For instance, the National Pest Management Association reports that rodent-related service calls have significantly increased in major metropolitan areas across the United States. Climate change is also influencing rodent behavior and reproduction cycles, causing them to thrive in new environments and increasing their resistance to conventional control methods. This trend has heightened the need for effective rodenticides that can combat infestations in evolving climatic conditions.
Stringent Food Safety and Hygiene Regulations:
Governments and regulatory bodies worldwide are enforcing strict food safety and hygiene standards, increasing the demand for efficient rodent control solutions. Industries such as food processing, hospitality, and healthcare are particularly impacted by these regulations, as compliance is essential to prevent contamination and ensure public health. For instance, the Food and Drug Administration (FDA) has implemented the Food Safety Modernization Act, which mandates comprehensive pest control measures in food facilities. Non-compliance with hygiene standards can result in financial penalties, reputational damage, and operational disruptions, prompting businesses to adopt proactive rodent control measures. This regulatory landscape is accelerating the development and adoption of innovative pesticides, including eco-friendly and non-toxic rodenticides, to meet compliance requirements.
Advancements in Pesticide Formulations and Technologies:
Continuous advancements in pesticide formulations are enhancing the effectiveness of rodent control products while minimizing environmental and human health risks. The introduction of bio-based rodenticides, slow-acting anticoagulants, and bait station solutions is improving control strategies and increasing adoption across various sectors. For instance, the Environmental Protection Agency (EPA) has approved several new rodenticide formulations that offer improved efficacy and reduced secondary poisoning risks. Additionally, the integration of smart pest management technologies, such as sensor-based monitoring and automated baiting systems, is optimizing control efforts and reducing chemical dependency. These innovations are driving market growth by offering safer, more efficient, and sustainable rodent control solutions.
Increasing Awareness and Adoption of Integrated Pest Management (IPM):
The rising awareness of the negative impacts of traditional pesticides has led to a growing preference for integrated pest management (IPM) strategies. IPM focuses on a combination of chemical, biological, and mechanical control methods, promoting sustainable and long-term pest management solutions. Governments and environmental organizations are actively advocating for IPM practices, encouraging businesses and households to adopt safer alternatives. For instance, the United States Department of Agriculture (USDA) has established the National Institute of Food and Agriculture's Crop Protection and Pest Management Program to promote IPM adoption. As a result, demand for eco-friendly rodenticides, biological controls, and professional pest management services is increasing, further driving market expansion.
Market Trends:
Growing Demand for Eco-Friendly and Bio-Based Rodenticides:
The shift toward sustainable pest control solutions is driving the adoption of eco-friendly and bio-based rodenticides. Increasing regulatory restrictions on toxic chemical-based pesticides have encouraged the development of alternatives that minimize environmental and health risks. Manufacturers are focusing on plant-based active ingredients, microbial pesticides, and anticoagulant-free formulations to enhance safety and effectiveness. For instance, Nature-Cide, a product by Med-X, Inc., has introduced Rat & Mouse Repellent Pouches infused with botanical essential oils that effectively repel rats and mice indoors or outdoors. The growing preference for non-toxic and biodegradable rodenticides is reshaping market dynamics, particularly in regions with stringent environmental regulations.
Adoption of Smart Pest Control Technologies:
The integration of advanced technologies in rodent control solutions is gaining traction, with sensor-based monitoring systems and automated bait stations improving efficiency. Smart pest control solutions utilize data analytics and real-time tracking to detect infestations and optimize pesticide usage. For instance, EMnify's customers in pest control are digitizing their industry by providing smart traps and infestation monitoring systems, allowing technicians to view trap locations and activity remotely. Businesses and commercial establishments are increasingly investing in these technologies to enhance cost-effectiveness and regulatory compliance. The rise of the Internet of Things (IoT) and artificial intelligence (AI) in pest management is further driving innovation in the market.
Rising Popularity of Integrated Pest Management (IPM):
The growing emphasis on sustainable pest control practices is increasing the adoption of Integrated Pest Management (IPM) strategies. IPM combines chemical, biological, and mechanical control methods to minimize pesticide use while maintaining effectiveness. For instance, the Department of Agriculture, Cooperation & Farmers Welfare in India promotes the IPM approach through 31 Central IPM centers in 28 States and One UT, focusing on pest monitoring, bio-control agent production, and farmer training. Governments and industry associations are actively promoting IPM programs, influencing market players to develop solutions that align with regulatory and environmental standards. The demand for professional pest management services that incorporate IPM strategies is expanding across commercial and industrial sectors.
Expansion of Rodent Control Services in Emerging Markets:
Emerging economies are witnessing increased investments in pest control infrastructure due to rising urbanization and growing awareness of pest-related health risks. Expanding food processing industries, improved hygiene regulations, and the presence of multinational pest control service providers are driving market growth in these regions. For instance, in the Bahamas, a pilot case study involving multidisciplinary teams and community engagement successfully developed and implemented a standardized national surveillance protocol for rodent control in disadvantaged urban areas. Companies are leveraging opportunities in Asia-Pacific, Latin America, and the Middle East & Africa by introducing cost-effective and region-specific rodent control solutions. The increasing availability of professional rodent control services is supporting market expansion in developing regions.
Market Challenges Analysis:
Regulatory Restrictions and Environmental Concerns:
Stringent regulations on the use of chemical rodenticides present a significant challenge for market growth. Governments and regulatory bodies worldwide are imposing strict guidelines to limit the use of toxic pesticides due to their adverse effects on non-target species, human health, and the environment. Bans on certain active ingredients and restrictions on anticoagulant rodenticides are prompting manufacturers to reformulate products, increasing research and development costs. Additionally, the demand for eco-friendly alternatives poses challenges in maintaining the same level of efficacy as traditional chemical-based solutions. Compliance with evolving regulatory frameworks requires continuous adaptation, affecting product availability and market expansion. The lengthy approval process for new pesticide formulations further slows market penetration and increases costs for manufacturers. Moreover, frequent policy changes and regional variations in pesticide regulations create complexities for global market players, requiring tailored solutions for different markets.
Increasing Rodent Resistance and Limited Consumer Awareness:
The rising resistance of rodents to conventional pesticides is reducing the effectiveness of commonly used rodenticides, necessitating the development of new formulations. Frequent exposure to anticoagulant-based rodenticides has led to genetic mutations in rodent populations, making them less susceptible to chemical treatments. This challenge forces manufacturers to invest in innovative solutions, increasing costs and time-to-market for new products. Furthermore, limited consumer awareness regarding proper rodent control practices and the safe application of pesticides continues to hinder market growth. In many regions, a lack of education on preventive measures and the benefits of integrated pest management (IPM) results in ineffective pest control strategies. Expanding awareness campaigns and training programs for both consumers and pest control professionals will be essential to addressing this challenge and ensuring the optimal use of rodent control solutions. The growing prevalence of DIY pest control solutions, often without proper knowledge, can lead to ineffective rodent management and increased infestations. Additionally, the lack of access to professional pest control services in rural and underdeveloped regions further limits market expansion, necessitating greater outreach and education initiatives.
Market Opportunities:
The rodent control pesticides market presents significant growth opportunities driven by increasing demand for eco-friendly and bio-based rodenticides. With rising environmental concerns and stringent regulations on chemical-based pesticides, manufacturers are investing in the development of safer, biodegradable alternatives. Innovations in non-toxic bait formulations, botanical extracts, and microbial pesticides are gaining traction, catering to both regulatory compliance and consumer preferences for sustainable solutions. Additionally, the growing adoption of integrated pest management (IPM) strategies across industries such as agriculture, food processing, and commercial facilities is creating new market avenues. Companies that develop rodenticides compatible with IPM practices, offering long-term and environmentally responsible solutions, are poised for substantial growth.
Technological advancements in rodent control solutions, including smart monitoring systems and automated bait stations, provide lucrative opportunities for market players. The integration of IoT and AI-driven pest management tools enhances efficiency by enabling real-time tracking and targeted pesticide application. Increasing investments in digital pest control solutions, particularly in urban and industrial settings, are further expanding market potential. Emerging markets, particularly in Asia-Pacific, Latin America, and the Middle East & Africa, also offer untapped opportunities due to rising urbanization, improving hygiene standards, and expanding food supply chains. Government initiatives promoting pest control awareness and disease prevention in these regions further drive market demand. As consumer awareness regarding health risks associated with rodent infestations grows, the demand for professional rodent control services is also increasing, presenting additional revenue streams for companies offering comprehensive pest management solutions.
Market Segmentation Analysis:
By Type
The rodent control pesticides market is segmented into anticoagulants and non-anticoagulants. Anticoagulant rodenticides, including first-generation and second-generation compounds, dominate the market due to their high effectiveness in controlling rodent populations. These products disrupt blood clotting mechanisms, leading to gradual rodent elimination. However, increasing resistance among rodent species and regulatory restrictions on toxic chemicals are driving demand for non-anticoagulant alternatives. Non-anticoagulant rodenticides, such as bromethalin and cholecalciferol-based formulations, are gaining traction due to their rapid action and lower environmental impact. The shift toward eco-friendly rodenticides is expected to reshape the market dynamics in the coming years.
By End-Use
Based on end-use, the market is categorized into residential, commercial, industrial, and agricultural sectors. The commercial segment holds a significant share, driven by stringent hygiene regulations in food processing, hospitality, and healthcare industries. Industrial facilities and warehouses also require effective rodent control to prevent contamination and infrastructure damage. The agricultural sector remains a key consumer of rodenticides, as rodents pose serious threats to crop yield and storage facilities. Additionally, the residential segment is witnessing increased adoption of rodent control solutions, fueled by rising consumer awareness of health risks associated with rodent infestations. The growing demand for professional pest management services across all end-use sectors further supports market expansion.
Segmentations:
By Type:
- Non-anticoagulant
- Anticoagulant
By End-Use:
- Pest Control
- Household
- Agriculture
- Warehouse
- Urban Centers
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a market share of 35%, making it the dominant region in the rodent control pesticides market. The strong presence of pest control service providers, stringent food safety regulations, and increasing urban rodent infestations drive demand for rodenticides across the region. The commercial sector, particularly food processing, hospitality, and healthcare industries, contributes significantly to market growth due to strict hygiene standards. The residential segment is also expanding as consumer awareness regarding rodent-related health risks increases. Additionally, regulatory agencies such as the Environmental Protection Agency (EPA) are promoting safer rodent control solutions, leading to the growing adoption of eco-friendly and bio-based rodenticides. Advancements in smart pest management technologies, including IoT-enabled monitoring systems, are further supporting market expansion. The rising frequency of rodent-borne disease outbreaks in urban centers is accelerating the demand for effective pest control solutions.
Asia-Pacific
Asia-Pacific accounts for a market share of 30% and is expected to witness the highest growth rate over the forecast period. Rapid urbanization, expanding food production industries, and increasing awareness of pest-related health hazards are key factors driving demand for rodent control pesticides. The agricultural sector remains a major consumer of rodenticides, as rodents cause significant crop losses in China, India, and Indonesia. Government initiatives promoting pest control practices and stricter hygiene regulations in commercial establishments are fueling market growth. The rise of integrated pest management (IPM) strategies is increasing demand for non-toxic and sustainable solutions. The presence of multinational pest control companies in emerging markets is also contributing to market expansion. Additionally, the rising affordability and availability of rodenticides in developing economies are encouraging wider adoption across multiple sectors. Investments in smart pest control solutions, such as automated bait stations, are further transforming market trends.
Europe
Europe holds a market share of 20%, driven by stringent environmental regulations and a growing preference for sustainable pest control solutions. The European Union’s restrictions on chemical rodenticides have accelerated the adoption of eco-friendly alternatives. The commercial sector remains a key contributor to market growth, with strict compliance requirements in food, beverage, pharmaceutical, and healthcare industries. The residential segment is also expanding as awareness of rodent-related diseases rises. Government-supported pest management programs and advancements in biological rodenticides are shaping market trends. The adoption of automated pest control solutions, including sensor-based baiting systems, is enhancing market efficiency. The growing emphasis on urban sanitation and rodent prevention programs is strengthening market expansion in key European cities.
Key Player Analysis:
- BASF SE
- Bayer AG
- Syngenta AG
- JT Eaton & Co. Inc.
- UPL Limited
- Rollins, Inc.
- Liphatech, Inc.
- Ecolab, Inc.
- Rentokil Initial PLC
- Neogen Corporation
- Anticimex
- Senetech, Inc.
Competitive Analysis:
The rodent control pesticides market is highly competitive, with key players focusing on product innovation, regulatory compliance, and market expansion. Leading companies are investing in research and development to introduce eco-friendly, bio-based, and non-toxic rodenticides that align with evolving regulatory standards. For instance, the United States Department of Agriculture (USDA) conducted a survey revealing that a significant number of agricultural operations are adopting integrated pest management practices, including the use of eco-friendly rodenticides. Advancements in smart pest control technologies, such as automated bait stations and IoT-enabled monitoring systems, are further shaping competition. Strategic mergers, acquisitions, and partnerships are strengthening market positions, enabling companies to expand their geographic presence and enhance product portfolios. Established players dominate North America and Europe due to stringent regulations, while emerging markets in Asia-Pacific offer significant growth opportunities. The growing demand for integrated pest management (IPM) solutions is driving innovation among market participants. As environmental concerns rise, companies that develop sustainable and highly effective rodenticides will gain a competitive edge, positioning themselves for long-term growth in the evolving pest control industry.
Recent Developments:
- In February 2025, Ecolab reported strong performance in its Pest Elimination segment, with organic sales increasing Q4 2024. The company announced plans to accelerate the rollout of its digital pest intelligence program.
- In June 2023, UPL and Radicle Growth launched "The Radicle Natural Plant Protection Challenge," investing $1.75 million in early-stage companies developing natural and biological solutions for crop protection, which could potentially include rodent control technologies.
- In March 2023, UPL participated in the Earth Summit in Doha to create a 'food security' program, which may indirectly impact rodent control strategies in agricultural settings.
- In May 2023, Liphatech introduced TakeDown II mini blocks containing bromethalin, an acute rodenticide designed for fast results against anticoagulant-resistant rodent populations, especially in commercial settings.
Market Concentration & Characteristics:
The rodent control pesticides market is moderately concentrated, with a mix of global and regional players competing through product innovation, regulatory compliance, and strategic expansion. Large multinational companies dominate developed regions such as North America and Europe due to strict environmental regulations and advanced pest management infrastructure. In contrast, emerging markets in Asia-Pacific and Latin America are witnessing increased competition from local manufacturers offering cost-effective rodenticides. The market is characterized by continuous advancements in eco-friendly and bio-based formulations, driven by rising environmental concerns and regulatory restrictions on toxic chemicals. The growing adoption of integrated pest management (IPM) solutions is reshaping the industry, prompting companies to develop non-toxic, targeted, and automated rodent control products. Technological innovations, including sensor-based monitoring and automated bait stations, are further influencing market dynamics. Companies that prioritize sustainability, efficacy, and compliance with evolving regulations are likely to strengthen their market presence and gain a competitive advantage.
Report Coverage:
The research report offers an in-depth analysis based on Type, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for eco-friendly and bio-based rodenticides will increase due to stringent regulations on chemical-based pesticides and rising environmental concerns.
- Advancements in smart pest control solutions, such as IoT-enabled monitoring systems and automated bait stations, will drive efficiency and precision in rodent management.
- The adoption of integrated pest management (IPM) strategies will expand, encouraging the development of sustainable and non-toxic rodent control solutions.
- Emerging markets, particularly in Asia-Pacific and Latin America, will witness rapid growth due to urbanization, expanding food production industries, and increasing hygiene awareness.
- Regulatory restrictions on anticoagulant-based rodenticides will prompt manufacturers to invest in alternative formulations with improved safety and efficacy.
- The agricultural sector will continue to be a major consumer of rodenticides, with increasing efforts to prevent crop losses caused by rodent infestations.
- Growth in the commercial sector, including food processing, hospitality, and healthcare industries, will accelerate the adoption of advanced rodent control solutions.
- Increasing rodent resistance to conventional pesticides will drive innovation in chemical compositions and delivery mechanisms for more effective control.
- Consumer awareness regarding rodent-borne diseases will fuel demand for both professional pest control services and DIY rodent control products.
- The industry will experience consolidation through mergers, acquisitions, and partnerships as companies seek to expand their market presence and enhance product portfolios.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the rodent control pesticides market?
What are the key factors driving market growth?
Which region dominates the rodent control pesticides market?
How is technology impacting the rodent control pesticides market?
Which industries are driving demand for rodent control pesticides?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Rodent Control Pesticides Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Rodent Control Pesticides Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,050 million → 2032: USD 9,863.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Rodent Control Pesticides Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Rodent Control Pesticides Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Rodent Control Pesticides Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Rodent Control Pesticides Market Drivers
- 3.3 Rodent Control Pesticides Market Restraints & Challenges
- 3.4 Rodent Control Pesticides Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Rodent Control Pesticides Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Rodent Control Pesticides Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Rodent Control Pesticides category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Rodent Control Pesticides Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Rodent Control Pesticides Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Rodent Control Pesticides market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Rodent Control Pesticides Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Rodent Control Pesticides Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Rodent Control Pesticides Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Rodent Control Pesticides (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Rodent Control Pesticides Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Rodent Control Pesticides Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Rodent Control Pesticides Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Rodent Control Pesticides Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Rodent Control Pesticides Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Rodent Control Pesticides Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Rodent Control Pesticides Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Rodent Control Pesticides Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Rodent Control Pesticides Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
