
Fire fleet renewal and telemetry reshape SCBA buying
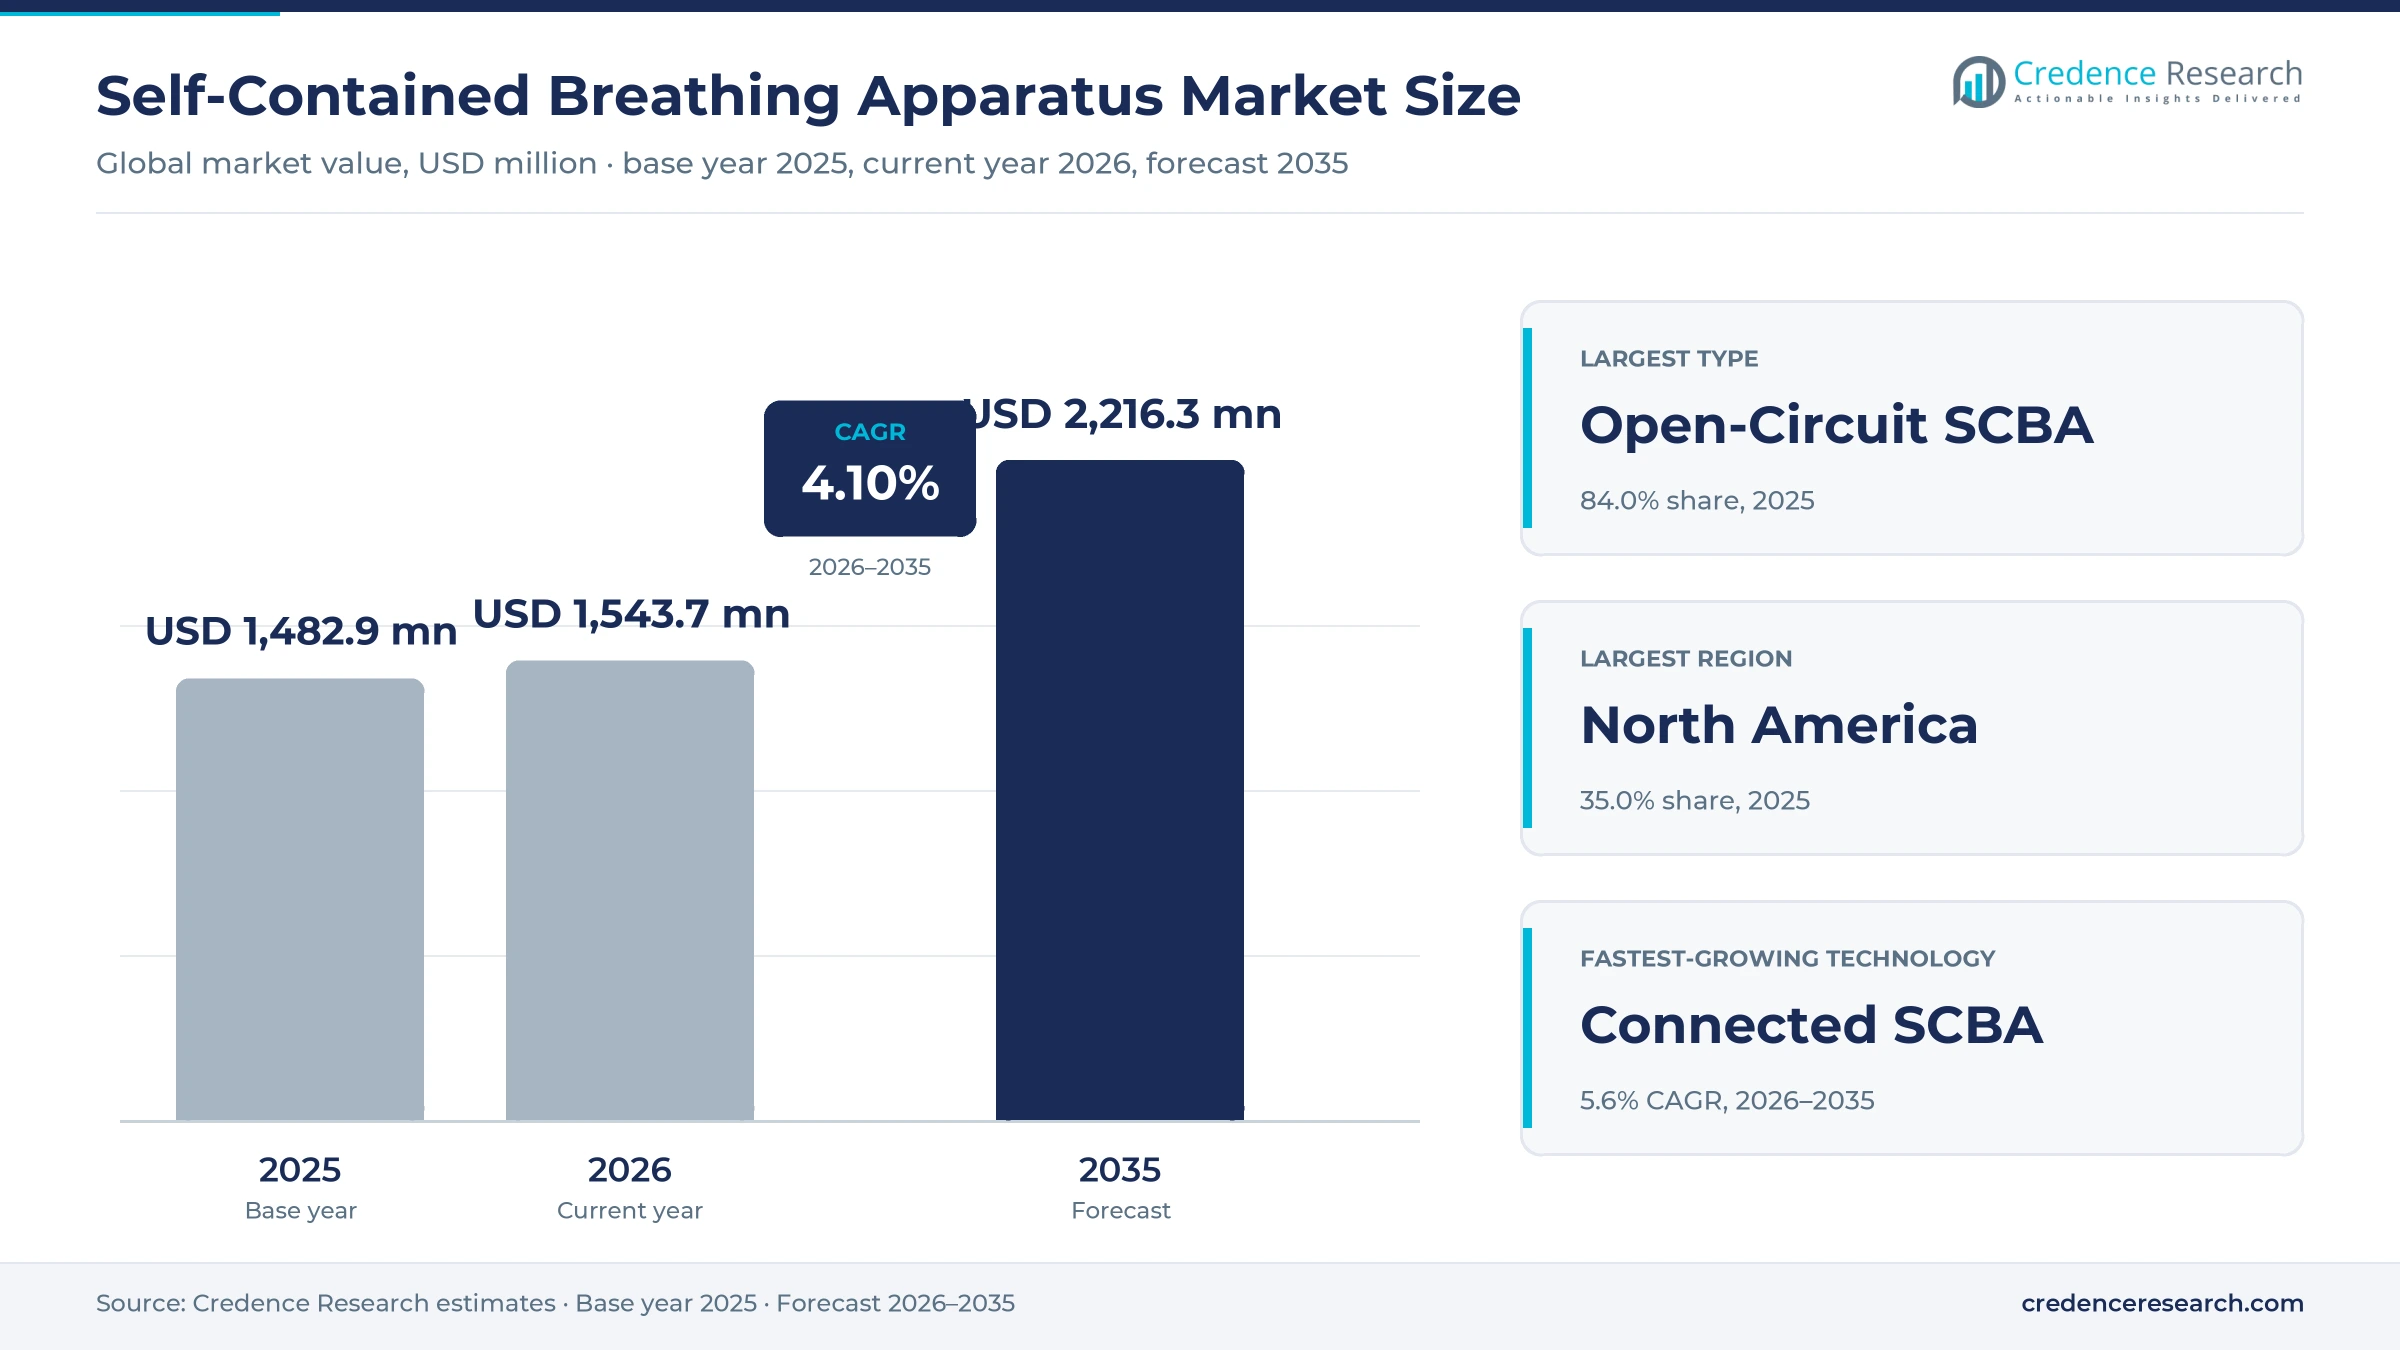
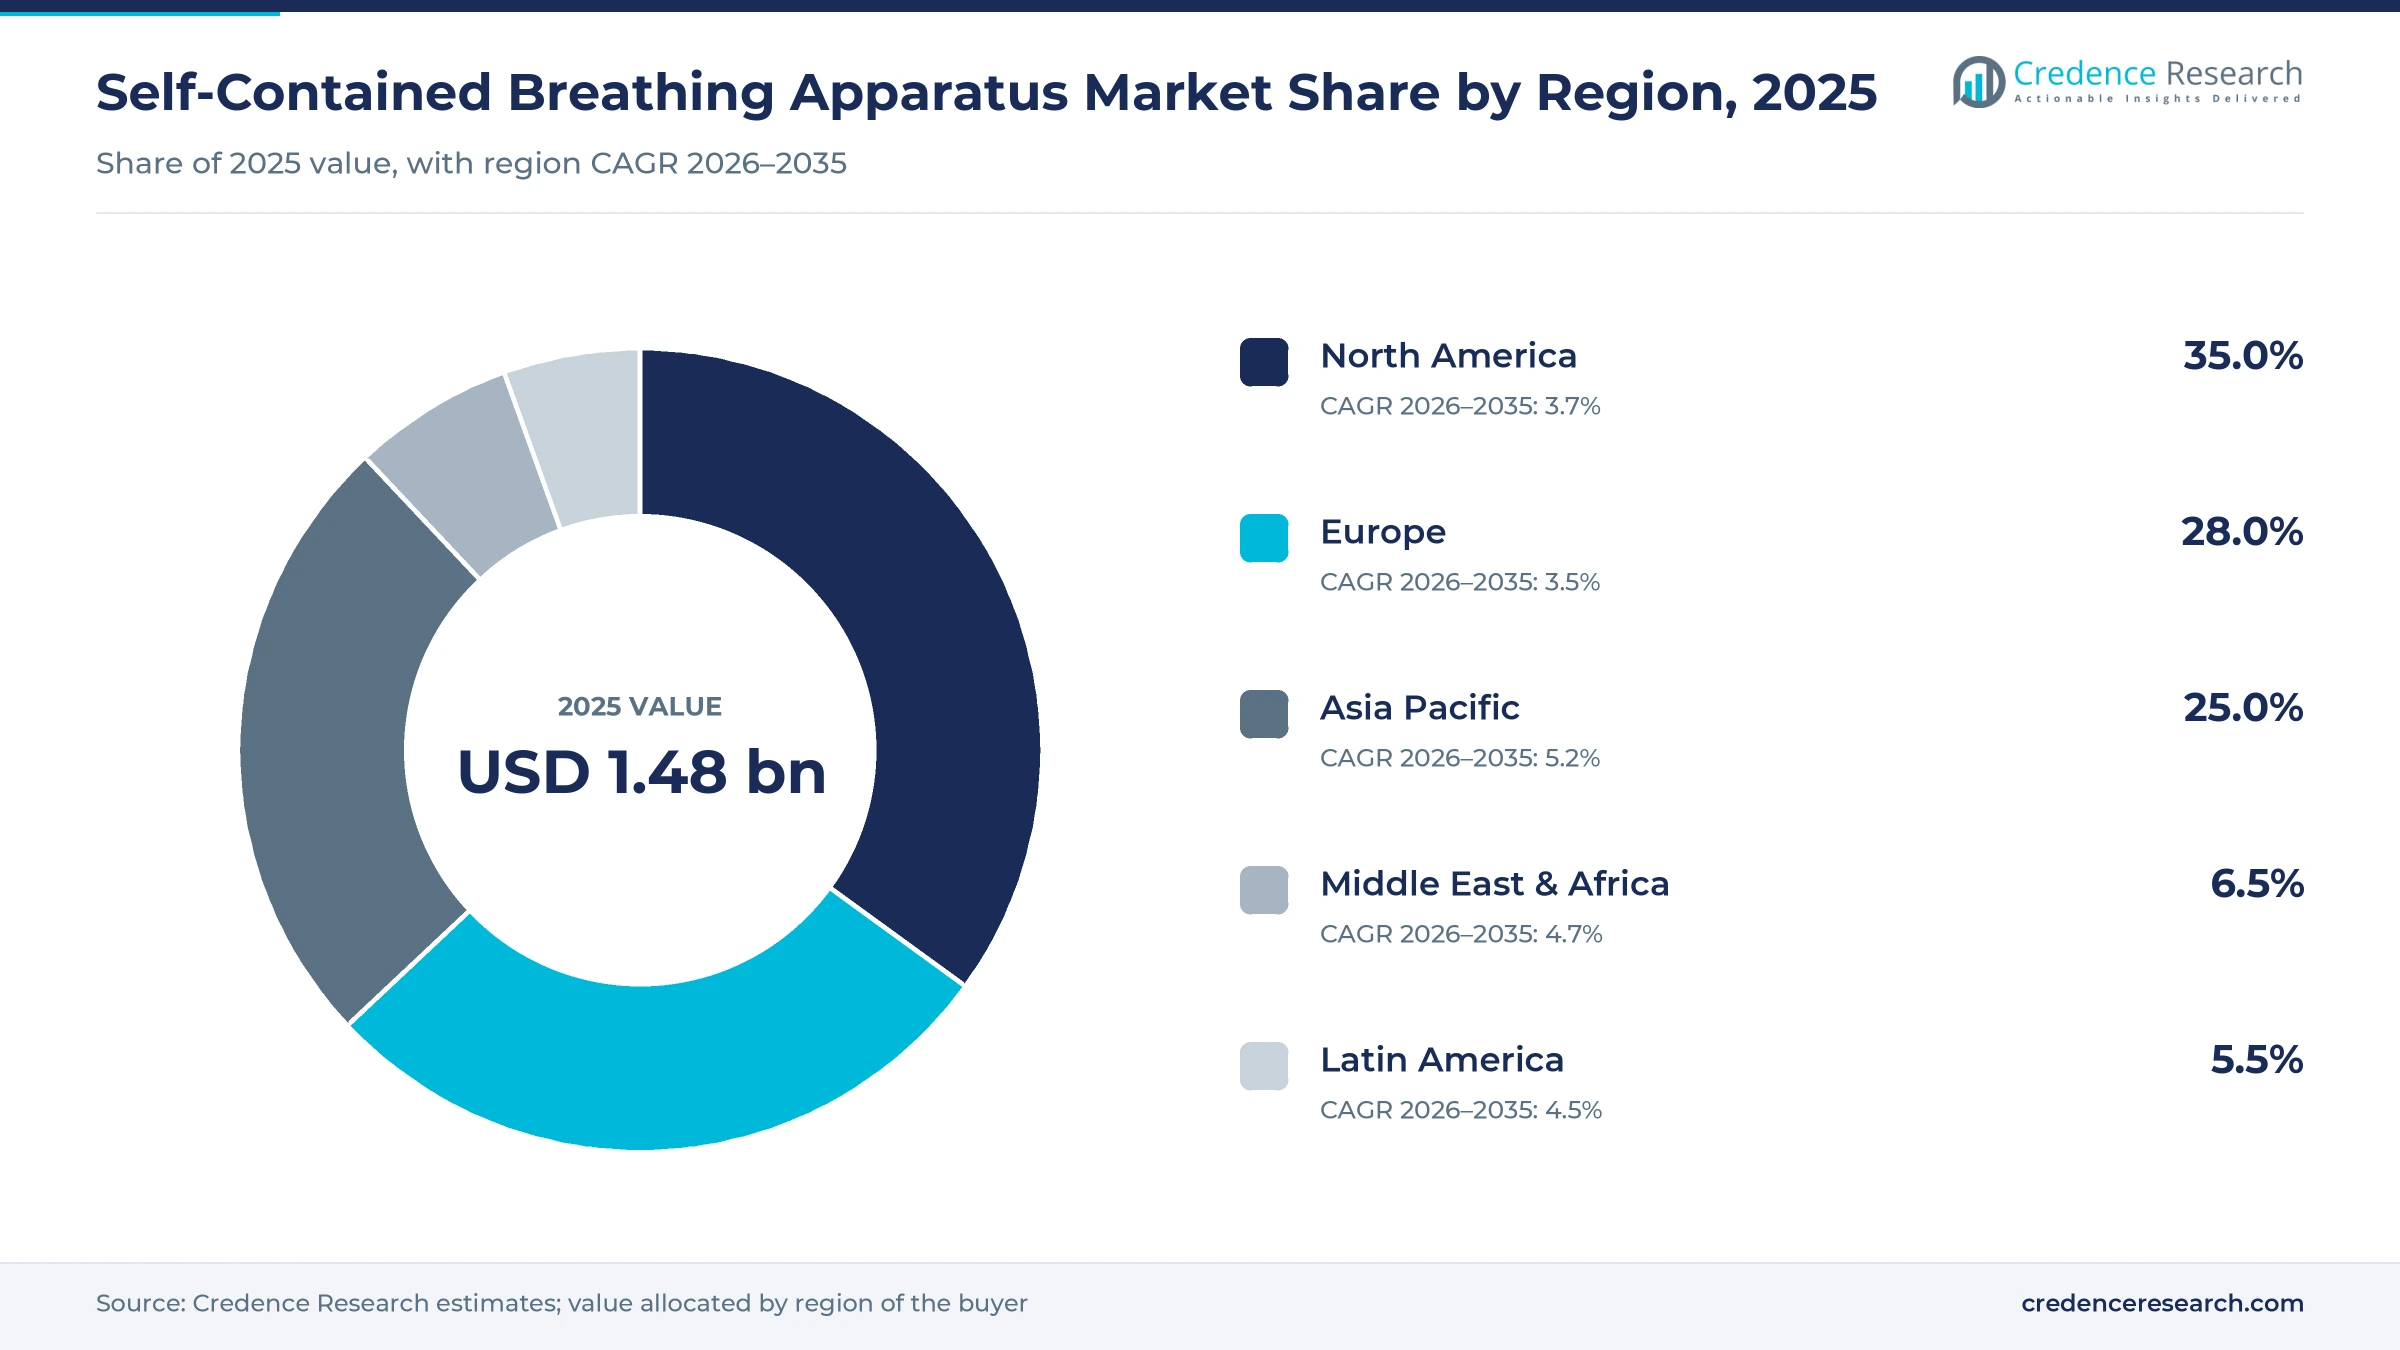
The global self-contained breathing apparatus market was valued at USD 1.48 billion in 2025 and is projected to increase from USD 1.54 billion in 2026 to USD 2.22 billion by 2035, registering a CAGR of 4.10% during 2026–2035. Demand comes from municipal and industrial fire brigades replacing packs at the end of their service life, and from oil and gas, chemical, mining and marine operators whose crews enter atmospheres that are immediately dangerous to life. North America held the largest regional share, 35.0% in 2025, because U.S. departments buy to NFPA and NIOSH rules and draw on federal grant money. Asia Pacific is the fastest-growing region at 5.2% a year, as India, China and Japan expand and re-equip professional fire services. The consolidation of the SCBA standard into the 2025 edition of NFPA 1970 has reset product certification in the largest market. Rising pack prices and tight municipal budgets still stretch replacement cycles for smaller departments.
Why do fire brigades buy breathing sets in fleet-wide cycles?
The estimate counts complete open-circuit and closed-circuit sets with backplates, regulators, facepieces and cylinders, plus integrated telemetry modules and the maintenance contracts that original equipment makers sell with them. Most volume comes from public fire services that standardize on one maker so that cylinders, masks and training are interchangeable across every engine company.
Escape hoods, air-purifying respirators and airline respirators without an independent air supply sit outside the scope. Because a department rarely mixes brands, a single award decides a decade of facepiece, cylinder and service sales, which makes tender wins far more valuable than individual unit margins suggest.
Self-Contained Breathing Apparatus Market Insights
- The market is valued at USD 1.48 billion in 2025 and is projected to reach USD 2.22 billion by 2035, growing at a 4.10% CAGR as fire services replace packs certified to older editions.
- North America led with 35.0% of 2025 value, because more than one million U.S. firefighters work under NFPA and NIOSH certification rules.
- Open-Circuit SCBA sets held 84.0% of 2025 value, since every structural firefighting standard is written around positive-pressure open-circuit air.
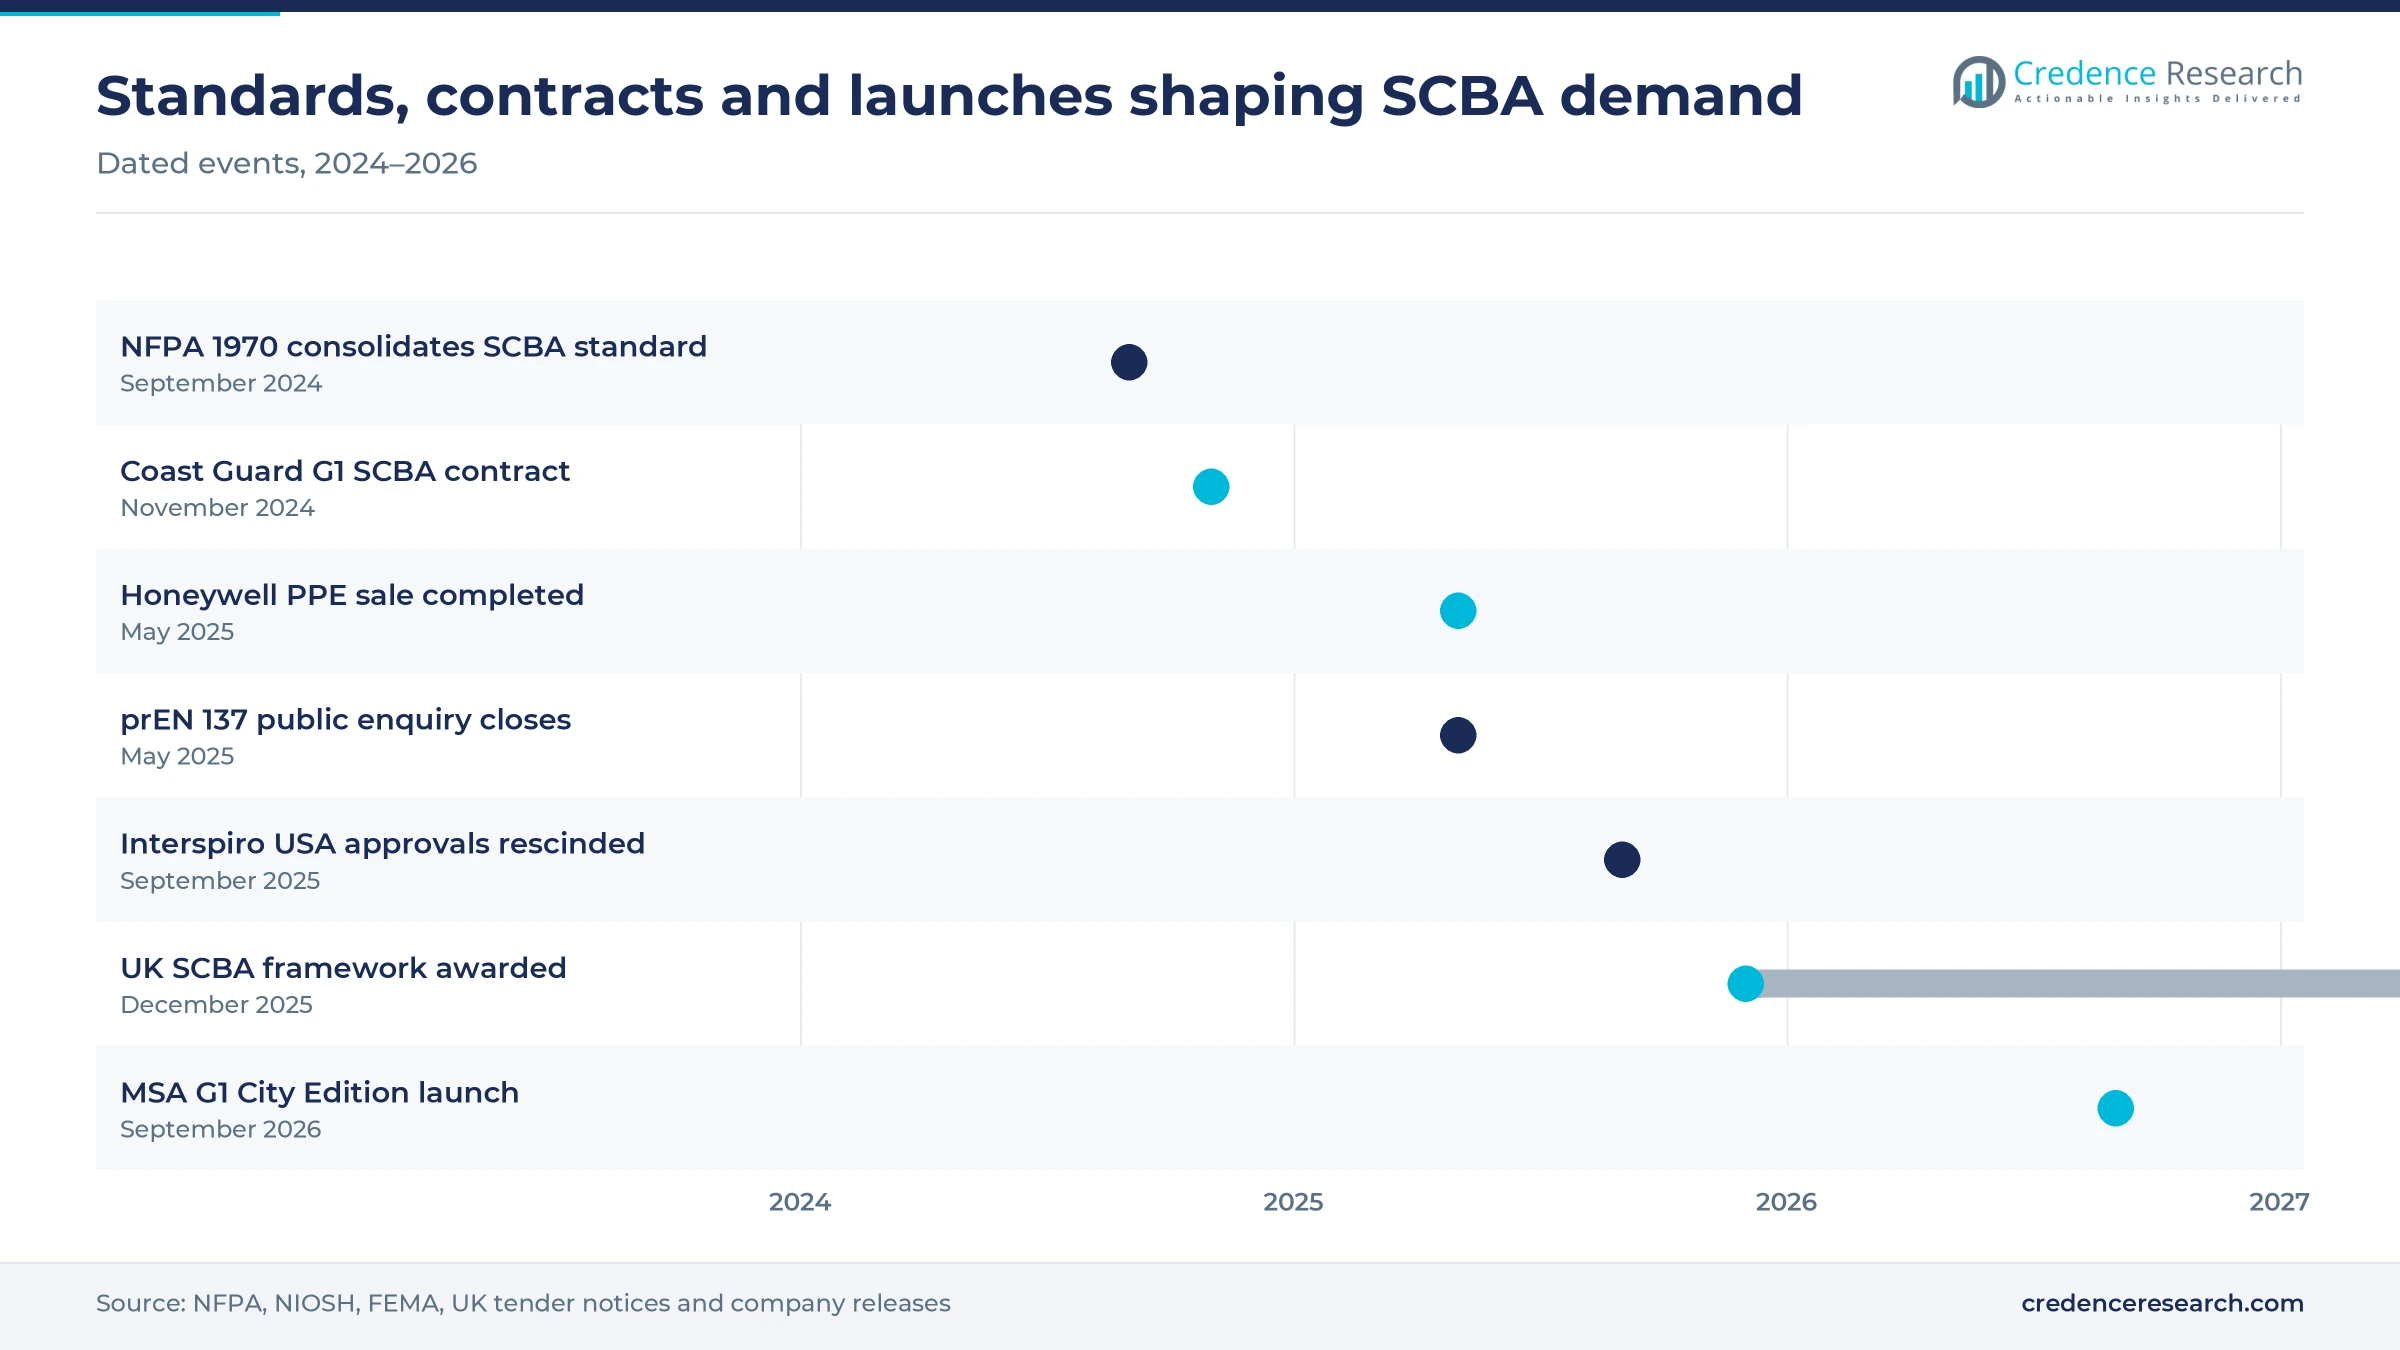
- In December 2025, U.K. fire authorities awarded a GBP 36 million SCBA framework lot to Dräger, Interspiro and MSA running from March 2026 to February 2030.
- In September 2025, Interspiro USA voluntarily rescinded 16 NIOSH approvals for older SCBA lines, which ends their legal sale and use in the United States.
Open-circuit packs and fire services hold most value
Why do open-circuit sets dominate value and volume?
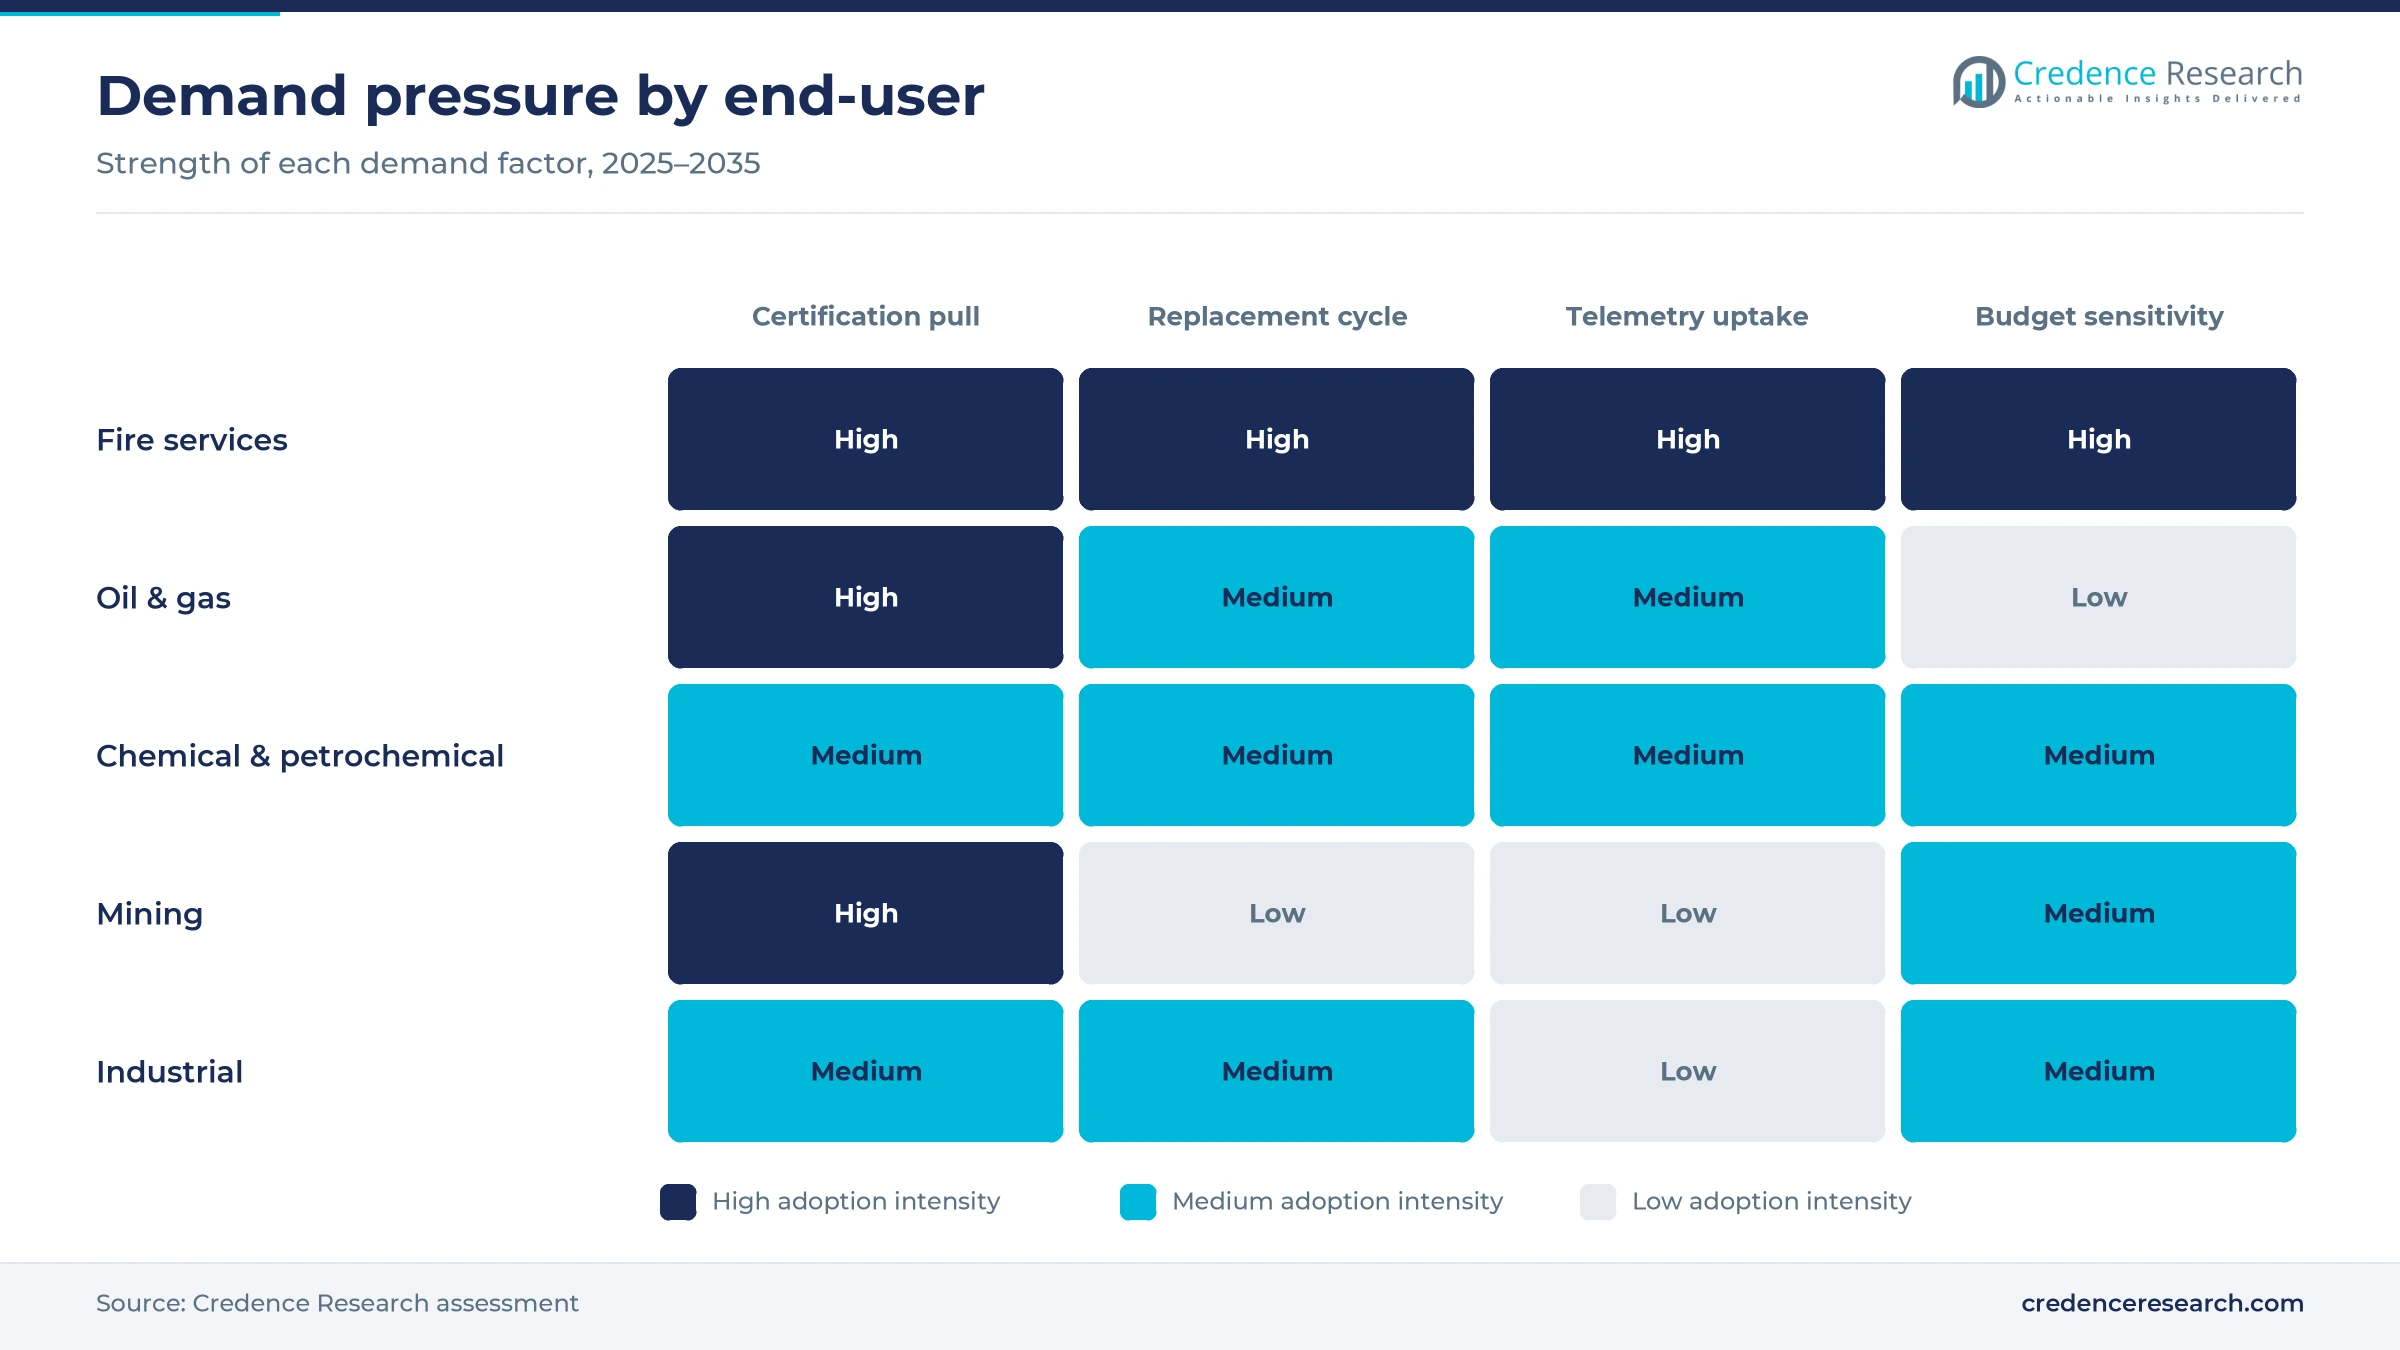
Based on type, the market is categorized into open-circuit SCBA and closed-circuit SCBA. Open-Circuit SCBA sets led with 84.0% of 2025 value because structural firefighting relies on compressed-air packs, and the City of Fresno alone approved 398 packs, 790 bottles and 499 masks for USD 4.41 million in June 2023. Open-Circuit SCBA sets also grow fastest at 4.2% a year as recertified fire fleets renew, with cylinders expiring from mid-2026 at departments such as Grand Forks. Closed-circuit rebreathers stay a niche because the Mine Safety and Health Administration requires only 12 apparatus with at least four hours of capacity at each mine rescue station.
Why do conventional packs lead while connected sets gain?
Based on technology, the market is categorized into conventional SCBA and connected SCBA. Conventional SCBA packs led with 64.0% of 2025 value because most installed fleets predate telemetry, and the Grand Forks Fire Department in North Dakota still ran units built to the 2007 edition of NFPA 1981 in January 2026. Connected SCBA packs grow fastest at 5.6% a year as command staff want live air data, and the Orange County Fire Authority chose G1 sets in April 2025 that send cylinder pressure, battery and alarm data to FireGrid software.
Why do fire services lead and keep growing fastest?
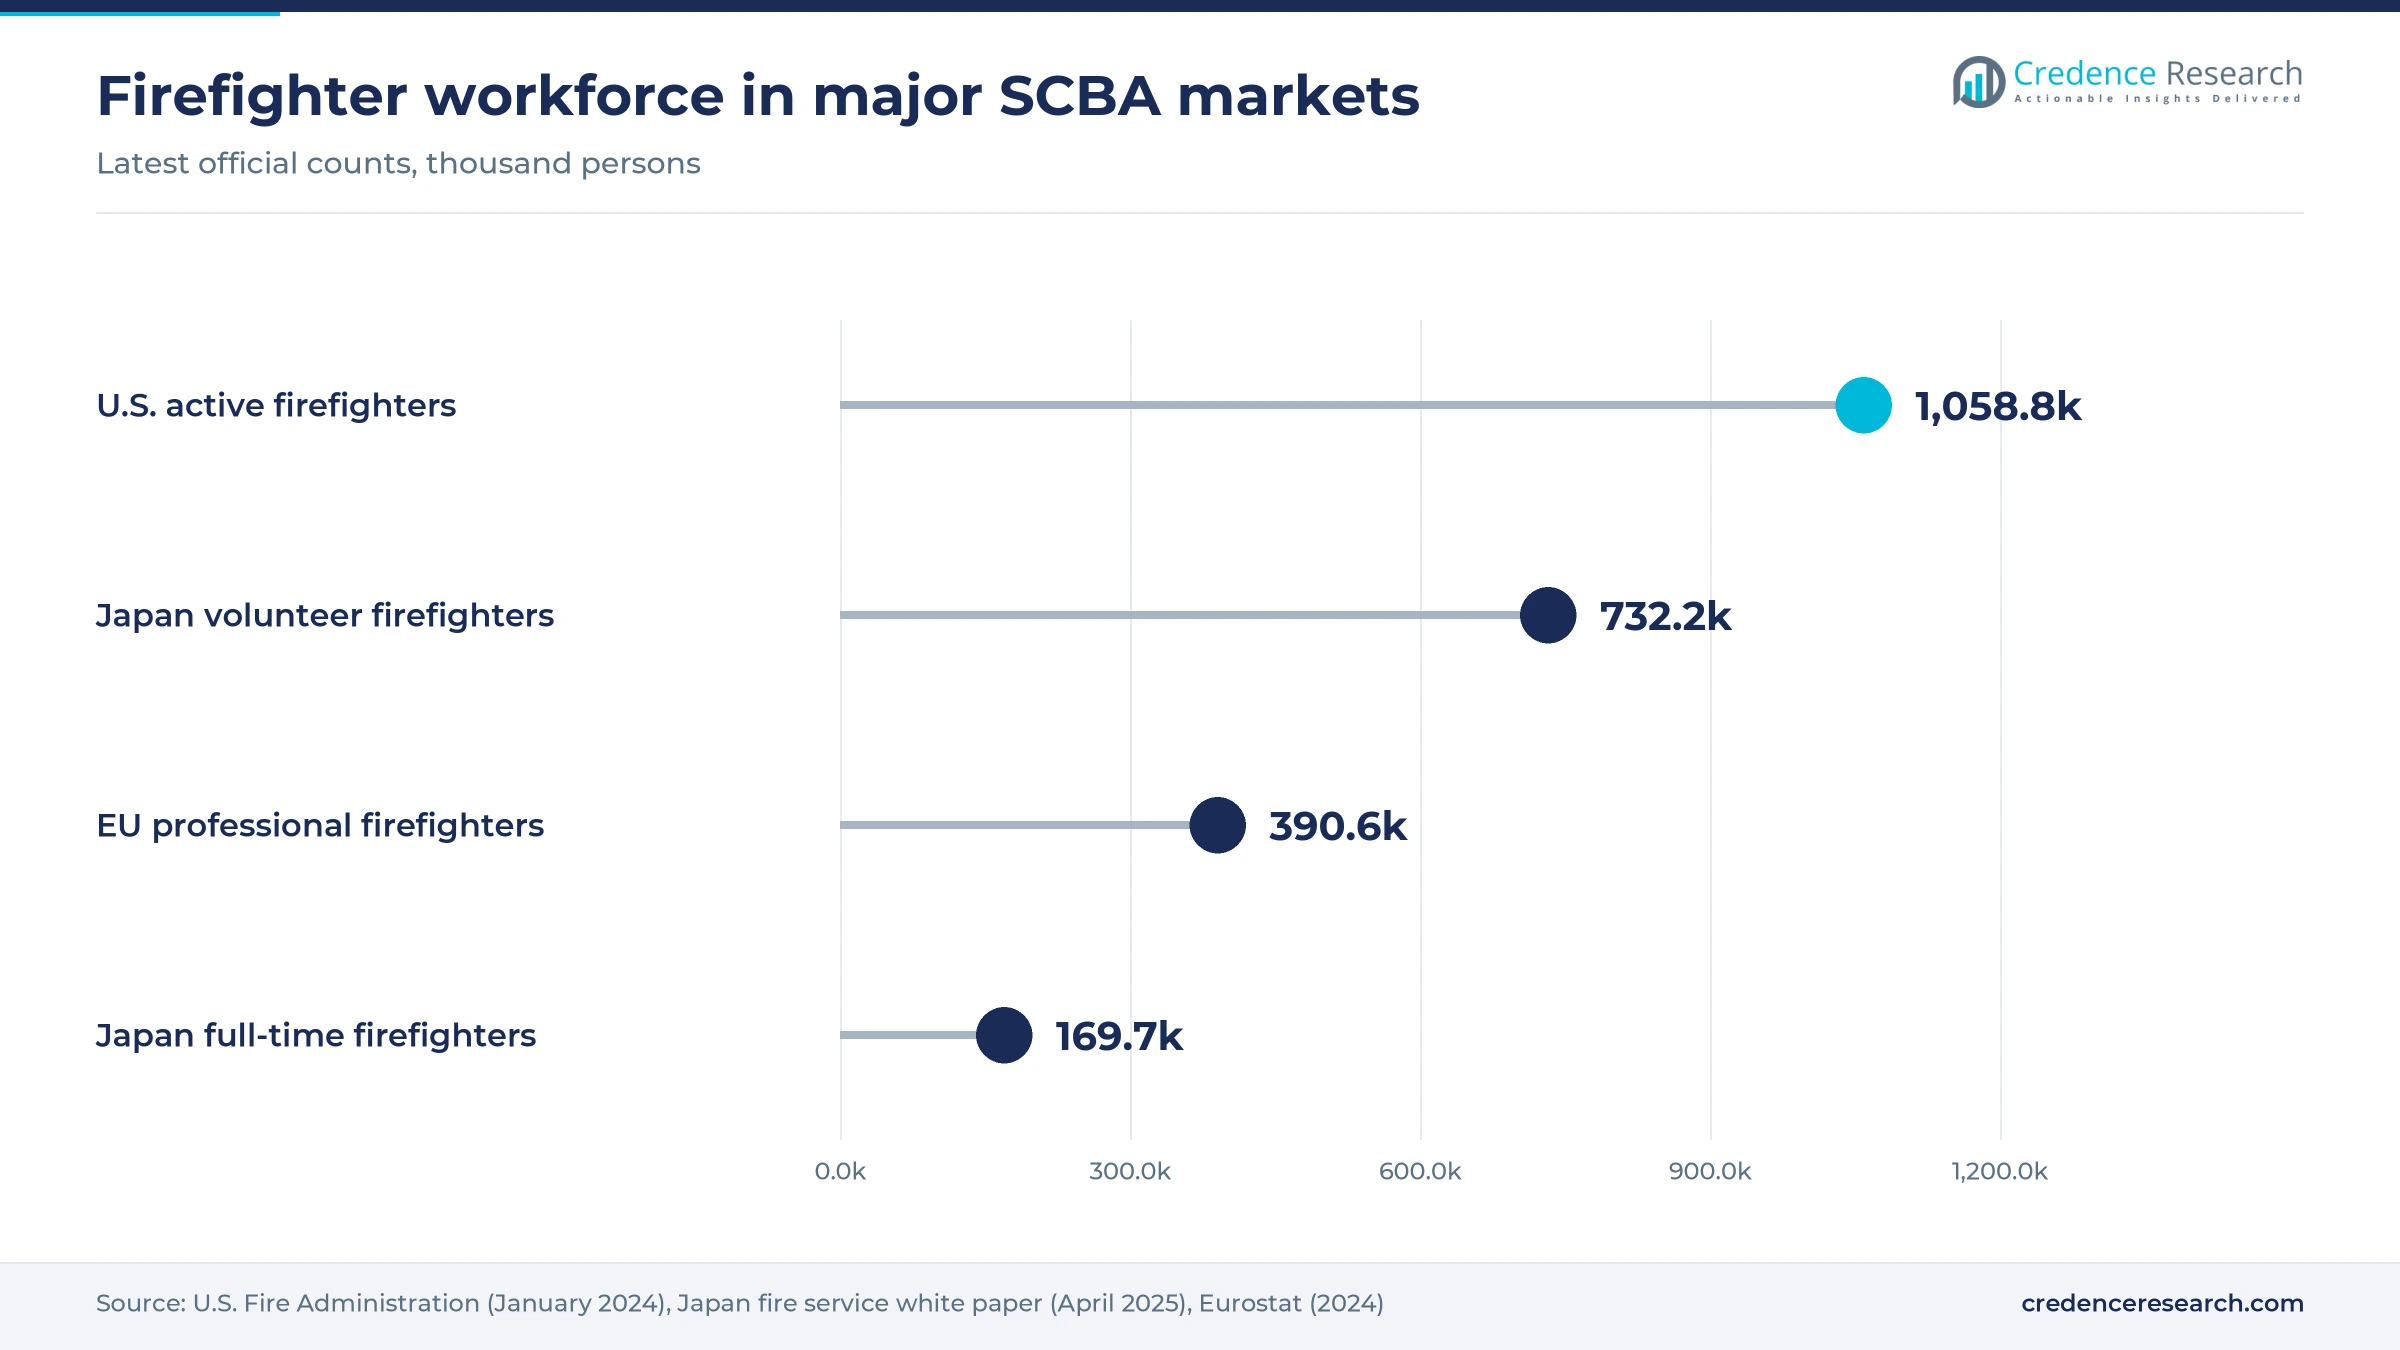
Based on end-user, the market is categorized into fire services, oil & gas, chemical & petrochemical, mining and industrial users. Fire Services led with 54.0% of 2025 value because the U.S. Fire Administration counted 27,166 registered departments and 1,058,800 active firefighters in January 2024, each crew needing certified packs. Fire Services also grow fastest at 4.3% a year as staffing rises, with Eurostat reporting 390,600 professional firefighters in the European Union in 2024, up from 362,400 a year earlier.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Open-Circuit SCBA | 84.0% | Open-Circuit SCBA | 4.2% |
| By Technology | Conventional SCBA | 64.0% | Connected SCBA | 5.6% |
| By End-user | Fire Services | 54.0% | Fire Services | 4.3% |
Packs list at USD 4,800–8,000 before cylinders and masks
Fire services buy SCBA as a system priced per pack, with cylinders, facepieces, voice and radio interfaces and telemetry quoted as separate lines, so a fully equipped position costs far more than the backplate price. Cylinder duration, pressure rating, hazmat configuration and connectivity move the price, and the National Volunteer Fire Council says SCBA costs rose about 32% between 2019 and early 2025. Makers recover margin through proprietary masks, cylinders and certified service, which is why departments compare lifetime cost rather than the pack price.
| Item or contract | Typical price or fee | Basis |
|---|---|---|
| 3M Scott Air-Pak X3 Pro, 5,500 psi, hazmat configuration | USD 8,025 per pack | Gwinnett County, Georgia award, November 2025 |
| 3M Scott Air-Pak X3-21 Pro, 5,500 psi | USD 4,810 per pack | Gwinnett County, Georgia award, November 2025 |
| Carbon fiber cylinder, 60 and 75 minutes, 5,500 psi | USD 1,585 and USD 1,750 each | Gwinnett County, Georgia award, November 2025 |
| Facepiece, AV3000HT medium | USD 325 each | Gwinnett County, Georgia award, November 2025 |
| Grant-funded fire service pack incl. cylinders and accessories | About USD 10,800 per unit | Credence Research estimate from a USD 1.3 million AFG award for 120 units, October 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
New NFPA rules, grants and fleet contracts lift orders
NFPA 1970 resets certification for U.S. fire fleets
The new NFPA 1970 standard is pulling U.S. replacement orders forward, because fleets certified to older SCBA editions grow harder to support. NFPA merged four standards, including the SCBA and PASS standards NFPA 1981 and NFPA 1982, into the 2025 edition of NFPA 1970, as FireRescue1 reported in September 2024. 3M Scott Fire & Safety said in February 2026 that its Air-Pak X3 Pro and Air-Pak XD packs were certified to the new edition. The Grand Forks Fire Department approved about USD 702,000 for replacement, USD 453,843 of it grant money, in January 2026, citing units two revision cycles behind and cylinders expiring from mid-2026, against a 15-year maximum service life cited by Pasadena, California, in May 2026. Makers with certified packs already shipping hold the edge in this renewal.
Federal grants keep smaller departments buying
Federal grants decide when many smaller U.S. departments can replace their packs, because few local budgets can fund a full fleet at once. FEMA lists a USD 324 million appropriation for the fiscal 2024 Assistance to Firefighters Grant program, with USD 291.6 million available for awards. The National Volunteer Fire Council says applications that year totaled USD 3.9 billion, more than 13 times the money on offer. In October 2025, Midland, Saginaw and Bay City in Michigan shared more than USD 1.3 million in grant money for 120 new SCBA units. Grant timing therefore shapes quarterly order patterns for every supplier serving volunteer and small career departments.
Large agencies lock in multiyear SCBA programs
Large agencies are converting SCBA replacement into multiyear supply programs, which gives suppliers visible volume for a decade. MSA Safety won a USD 33 million, 10-year U.S. Coast Guard contract in November 2024 for G1 packs across the surface fleet, with initial orders of USD 22 million. The Orange County Fire Authority in California followed with a USD 10 million G1 award in April 2025. A U.S. Department of Homeland Security report from May 2024 noted that the Fire Department of the City of New York had about 10,000 SCBAs nearing end of life. Such awards tie cylinders, masks and service to one maker for the length of the program.
Gulf oil, gas and petrochemical sites expand industrial demand
Industrial users in the Gulf add a second demand base, because oil, gas and petrochemical sites must equip their own fire and rescue teams. An Aramco supplier workshop held in January 2025 sized the Saudi respirator market, SCBA included, at about USD 38 million in 2025, and the wider Gulf Cooperation Council at about USD 63 million. The same slides separated 60-minute carbon-cylinder firefighter sets from 30-minute aluminum-cylinder industrial sets. Aramco also cited mandatory local procurement quotas for public and private firefighting needs. Suppliers that assemble or service packs in the kingdom therefore gain an edge in tenders tied to new plants and refinery expansions.
Connected packs, cleaner designs and pooled tenders
Connected packs shift accountability to the incident commander
Fire services are shifting toward packs that report air and location data in real time, because accountability on a large fireground still depends on radio calls. MSA launched the G1 City Edition in September 2026 with a beacon that lets LUNAR handheld devices locate a downed firefighter, and a cylinder retention band more than 10% lighter than the standard G1. Tyne and Wear Fire and Rescue Service in England equipped crews with 220 Dräger PSS AirBoss Connect sets linked to the FireGround accountability system. Connected SCBA packs grow at 5.6% a year in the Credence Research split, as buyers write telemetry into tender specifications. Suppliers with their own software platforms gain recurring licence and upgrade revenue that pure hardware makers cannot match.
Cleaner, lighter designs answer contamination concerns
Makers are shifting toward packs that strip down without tools, because departments now treat soot on harnesses as a health exposure rather than a cosmetic issue. Dräger said in February 2026 that its PSS AirBoss, now certified to NFPA 1970, uses tool-less disassembly for faster cleaning and a floating waist belt that keeps weight on the hips. MSA unveiled the G1 SCBA XR in April 2025 with removable straps, lumbar pad and fill pouches, opening orders in May 2025. The G1 XR stays backward compatible with earlier G1 packs, which protects existing fleets. Buyers gain shorter decontamination cycles, while makers sell replacement soft goods throughout the life of each pack.
Pooled European frameworks open multiyear supply slots
Pooled frameworks create an opening for suppliers that can serve dozens of brigades from a single award. Devon & Somerset Fire & Rescue Authority, working with the National Fire Chiefs Council, awarded a GBP 36 million SCBA lot in December 2025 to Dräger, Interspiro and MSA. The framework runs from March 2026 to February 2030 and can extend to February 2032. In Europe, the draft prEN 137:2025, which closed public enquiry in May 2025, will supersede EN 137:2006 and adds optional cylinder interchangeability requirements. Makers admitted to such frameworks can win brigade switches without a full tender, while excluded makers lose access for up to six years.
Indian and Asian fire service build-outs need first-time fleets
Fire service modernization in South Asia and East Asia offers an underserved opening, because many stations are still being built or re-equipped for the first time. India launched an INR 5,000 crore scheme for fire service modernization in July 2023, according to Business Standard, and a committee chaired by Home Minister Amit Shah approved more than INR 1,604 crore for five states in March 2025, as All India Radio reported. Japan counted 720 fire headquarters and 169,730 full-time firefighters on April 1, 2025. Suppliers offering EN or national certification at lower price points stand to win this first-equipment demand.
Price inflation, approval churn and radio gaps
Pack inflation outruns municipal budgets
Rising prices are stretching replacement cycles, which exposes small and volunteer departments the most. The National Volunteer Fire Council says, citing an NFPA needs assessment, that more than half of U.S. departments cannot equip all personnel with SCBA, a gap the price rise noted above keeps widening. Congress cut the grant program by 10% in fiscal 2024. Departments facing that gap run packs to the end of their service life or buy fewer spare cylinders, which slows unit volume for every supplier.
Approval withdrawals strand older fleets
Certification churn can strand fleets overnight, which hits departments running discontinued models hardest. NIOSH recorded that Interspiro USA voluntarily rescinded 16 approvals effective Sept. 15, 2025, covering Spiromatic, Spirolite and Spirotek lines that may no longer be manufactured, sold or used. Owners of those packs must replace or convert them within budget years they did not plan. The episode raises the perceived risk of smaller brands and pushes buyers toward makers with long support records.
Radio links and mask seals still fail in the field
Field reliability gaps limit how far buyers trust connected packs, especially in high-rise and underground work. The Department of Homeland Security reported in May 2024 that wireless systems may need added repeaters in high-rise and subterranean settings and that NFPA rules do not address recovery after a lost connection. Firefighters in the same tests reported mask seal failures under sweat and exertion. Buyers in dense cities carry the most exposure until makers prove network resilience in live incidents.
Ownership changes unsettle support for some brands
Portfolio sales create support uncertainty for buyers of smaller SCBA lines, because a fleet depends on spare parts and certified service for well over a decade. Honeywell completed the USD 1.325 billion sale of its personal protective equipment business to Protective Industrial Products in May 2025, and Honeywell SCBA product pages now redirect to the new owner. Industrial customers using those packs face questions on parts and training continuity. Rival makers can target such accounts with conversion offers during the transition.
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 0.52 | 35.0% | 3.6% |
| Europe | 0.42 | 28.0% | 3.5% |
| Asia Pacific | 0.37 | 25.0% | 5.2% |
| Middle East & Africa | 0.10 | 6.5% | 4.7% |
| Latin America | 0.08 | 5.5% | 4.5% |
North America leads on certified fleet renewal
North America held 35.0% of 2025 value and grows at 3.6% a year, because U.S. departments must buy NIOSH-approved packs that meet NFPA rules and usually replace whole fleets at once. Contract sizes show the scale, with Fresno, Orange County and the Coast Guard each committing millions to single brands. The grant program noted above smooths demand for smaller departments, whose order sizes follow the number of crews riding their fire engines. The United States accounts for most of the regional value in Credence Research estimates, with Canada buying largely the same NFPA-certified products.
Europe buys through frameworks and service contracts
Europe held 28.0% of 2025 value and grows at 3.5% a year, the slowest pace, because most brigades already run modern EN 137 packs and renew on long cycles. Service revenue matters as much as hardware, and Cumbria Commissioner Fire and Rescue Authority signed a GBP 97,594 Total Care maintenance contract with Dräger in November 2025. The pending revision of EN 137 may trigger specification updates across national fleets and in later tenders.
Asia Pacific grows fastest on fire service expansion
Asia Pacific held 25.0% of 2025 value and is the fastest-growing region at 5.2% a year, as governments expand professional fire services and industrial safety rules tighten. Japan relies on 732,223 volunteer firefighters alongside its career crews. The Indian state fire service projects noted above add first-time fleets. Domestic makers such as Nanjing Zhengze Technology and Shigematsu compete with Western brands on price and local certification.
Middle East & Africa follows oil, gas and civil defense
Middle East & Africa held 6.5% of 2025 value and grows at 4.7% a year on refinery, petrochemical and civil defense demand. Oil and gas operators such as Aramco and ADNOC usually specify NFPA-certified equipment, which MSA supplies through partners alongside portable gas detectors. Civil defense forces tend to prefer CEN-certified packs, according to an MSA interview published in January 2022. MSA has run a Dubai office since the early 1980s, and Saudi localization quotas favor suppliers that assemble or service equipment in the kingdom.
Latin America depends on oil, mining and city brigades
Latin America held 5.5% of 2025 value and grows at 4.5% a year, with demand concentrated in offshore oil, copper and gold mining, and large city fire departments in Brazil, Mexico and Chile. Public data on regional SCBA procurement are thin, so this split is a Credence Research estimate with a wider error band than other regions. Without a public tender series, the estimate leans on industrial activity and fire service size rather than award data.
Coast Guard, NFCC and AirBoss deals mark 2024–2026
| Development | Status and market relevance |
|---|---|
| In November 2024, MSA Safety won a USD 33 million, 10-year U.S. Coast Guard contract for G1 SCBA, with initial orders of USD 22 million. | Contract award with orders placed; it secures surface-fleet volume and cylinder and service sales for a decade. |
| In May 2025, Honeywell completed the USD 1.325 billion sale of its personal protective equipment business to Protective Industrial Products. | Completed transaction; Honeywell-branded SCBA lines now sit with a new owner focused on safety equipment. |
| In December 2025, Devon & Somerset Fire & Rescue Authority awarded the SCBA lot of a U.K. fire service framework to Dräger, Interspiro and MSA. | Award decision, with the framework running from March 2026 to February 2030; it fixes the shortlist for U.K. brigade purchases. |
| In February 2026, Dräger opened U.S. ordering for the PSS AirBoss certified to NFPA 1970 through its network of authorized sales partners. | Commercial launch; it lets Dräger contest U.S. fleet tenders with a pack certified to the new edition. |
| In September 2026, MSA Safety launched the G1 City Edition SCBA with built-in LUNAR beacon search and NFPA 1970 certification. | Product launch with no shipping date or price disclosed; it extends the G1 installed base toward urban departments. |
Pressure regulators, composite cylinders and telemetry
- Positive-pressure regulators keep the facepiece above ambient pressure, so any leak pushes air out rather than letting smoke in, which is why structural firefighting standards require them.
- Carbon composite cylinders use a carbon fiber composite wrap to hold air at 4,500 or 5,500 psi at a fraction of the weight of steel, although their limited service life forces regular replacement purchases.
- Closed-circuit rebreathers scrub carbon dioxide and add oxygen to exhaled gas, giving mine rescue teams four hours or more of breathing time.
- Telemetry and end-of-service-time alarms send cylinder pressure, battery and alarm data to incident commanders and warn wearers when remaining air reaches the set point.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Three Western makers dominate certified fire tenders
Competition centers on fleet awards rather than unit sales, because a fire service that adopts one maker standardizes masks, cylinders, training and repair benches around it for a decade or more. MSA Safety has used the G1 platform and its LUNAR and FireGrid software to win large U.S. awards, including the Coast Guard and Orange County. 3M Scott Fire & Safety defends a deep installed base of Air-Pak packs, now recertified to NFPA 1970. Dräger leads in much of Europe and is pushing the AirBoss into the United States through a national dealer network. Interspiro and Avon Protection compete on design and specialist missions, while Shigematsu, Spasciani and Chinese makers such as Nanjing Zhengze serve national and price-led tenders. Service capability and parts availability often decide close evaluations between certified self-contained breathing apparatus bids.
How concentrated is the supply side?
Three makers, MSA Safety, 3M Scott Fire & Safety and Dräger, win most certified fire service tenders in North America and Europe, because NIOSH approval, NFPA or EN certification and a dealer service network take years and heavy testing to build. A second tier of Interspiro, Avon Protection, Spasciani and Shigematsu holds strong niche or national positions, while Chinese producers compete on price in Asia and export markets. Margins sit mostly in proprietary facepieces, cylinders, telemetry and certified service, since a brigade that standardizes on one brand rarely switches before the next fleet renewal.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| MSA Safety Incorporated | Full-line supplier | G1 and M1 SCBA with LUNAR and FireGrid telemetry for fire and industry |
| 3M Company (3M Scott Fire & Safety) | Full-line supplier | Air-Pak X3 Pro and XD SCBA, cylinders and facepieces |
| Drägerwerk AG & Co. KGaA | Full-line supplier | PSS AirBoss open-circuit SCBA and BG ProAir closed-circuit rebreathers |
| Interspiro AB | Specialist | S9 Incurve SCBA for fire services and marine users |
| Avon Technologies plc (Avon Protection) | Specialist | ST54 tactical SCBA and supplied-air systems for defense and police |
| Protective Industrial Products, Inc. (Honeywell SCBA line) | Full-line PPE supplier | Honeywell-branded Titan and Aeris SCBA for industry and fire |
| Shigematsu Works Co., Ltd. | National specialist | SCBA and supplied-air respirators for Japanese fire and industry |
| Spasciani S.p.A. | Specialist | Firefighting and industrial SCBA and escape breathing devices |
| Nanjing Zhengze Technology Co., Ltd. | Local manufacturer | Carbon-cylinder SCBA for Chinese and export fire services |
Installed-base lock-in decides who wins renewals
Credence Research's view is that the installed base, not new technology alone, decides who grows in self-contained breathing apparatus, where fire services hold 54.0% of 2025 demand. Each fleet award ties cylinders, masks, service and training to one maker for a decade, so the 2025 to 2030 NFPA 1970 renewal wave in the United States will largely set supplier positions until the next cycle. Connected packs raise the value of each position, although buyers will pay for telemetry only where network reliability is proven. Outside the West, first-time fleets in India and other Asian markets reward makers that pair credible certification with lower prices and local service.
Earlier estimate rolled forward and tested on fleets
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The earlier Credence Research estimate was rolled forward one year at its own growth rate and then tested against fire service headcounts, grant budgets, published contract values and tender prices. Market values come from the Credence Research model, and regional and segment splits are Credence Research estimates. Sources used include NIOSH notices, FEMA and U.S. Fire Administration data, Eurostat, Japan's fire service white paper, public tender and award notices, company releases and trade press. No interviews or surveys were conducted for this edition of the self-contained breathing apparatus study.
Replacement cycles and Asian fire services carry growth
Through 2035, self-contained breathing apparatus spending should rise at 4.10% a year as U.S. departments retire packs certified to older editions and as European brigades move through framework renewals. Asia Pacific will add the most new positions, led by Indian state fire service projects and the re-equipment of Chinese and Japanese crews. Connected packs should move from premium option to tender requirement in large cities once wireless reliability improves. Price inflation and grant budgets remain the main swing factors, and makers that keep parts and service available across long fleet lives will hold their accounts.
Grant budgets and Asian tenders set the range of outcomes
The outcome to 2035 depends mostly on how quickly U.S. departments fund NFPA 1970 renewals and how far Asian fire services move from first equipment to regular replacement. Steady grant money and on-time Indian state projects would hold the base case. Prolonged municipal budget pressure would stretch replacement cycles toward the full service life, while faster adoption of connected packs would raise the average selling price per position.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 2.9% | USD 2.00 billion | Grant cuts and tight city budgets stretch U.S. and European fleet renewals to full service life |
| Base | 4.10% | USD 2.22 billion | U.S. fleets renew steadily to NFPA 1970 while Asian fire services keep expanding |
| Upside | 5.1% | USD 2.42 billion | Telemetry becomes standard in tenders and Indian and Chinese brigades re-equip on schedule |
Frequently Asked Questions
How big is the self-contained breathing apparatus market?
What is driving SCBA demand in the United States?
Which region leads the self-contained breathing apparatus market?
Which region grows fastest?
How much does an SCBA pack cost?
What is the difference between open-circuit and closed-circuit SCBA?
Who are the leading SCBA manufacturers?
What are the main challenges for SCBA buyers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Open-Circuit SCBA
- 1.2.2 Closed-Circuit SCBA
- 1.3 By Technology
- 1.3.1 Conventional SCBA
- 1.3.2 Connected SCBA
- 1.4 By End-user
- 1.4.1 Fire Services
- 1.4.2 Oil & Gas
- 1.4.3 Chemical & Petrochemical
- 1.4.4 Mining
- 1.4.5 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.48 billion → 2035: USD 2.22 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Self-Contained Breathing Apparatus Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Self-Contained Breathing Apparatus Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Self-Contained Breathing Apparatus Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Self-Contained Breathing Apparatus Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Self-Contained Breathing Apparatus Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Self-Contained Breathing Apparatus Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Self-Contained Breathing Apparatus Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Self-Contained Breathing Apparatus Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.48 billion → 2035: USD 2.22 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Self-Contained Breathing Apparatus Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Open-Circuit SCBA
- 12.3.7.2 Closed-Circuit SCBA
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional SCBA
- 12.4.7.2 Connected SCBA
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-user - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fire Services
- 12.5.7.2 Oil & Gas
- 12.5.7.3 Chemical & Petrochemical
- 12.5.7.4 Mining
- 12.5.7.5 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Self-Contained Breathing Apparatus End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Self-Contained Breathing Apparatus Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Self-Contained Breathing Apparatus Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Self-Contained Breathing Apparatus Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 MSA Safety Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 3M Company (3M Scott Fire & Safety)
- 18.4 Drägerwerk AG & Co. KGaA
- 18.5 Interspiro AB
- 18.6 Avon Technologies plc (Avon Protection)
- 18.7 Protective Industrial Products, Inc. (Honeywell SCBA line)
- 18.8 Shigematsu Works Co., Ltd.
- 18.9 Spasciani S.p.A.
- 18.10 Nanjing Zhengze Technology Co., Ltd.
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

