
Market Overview
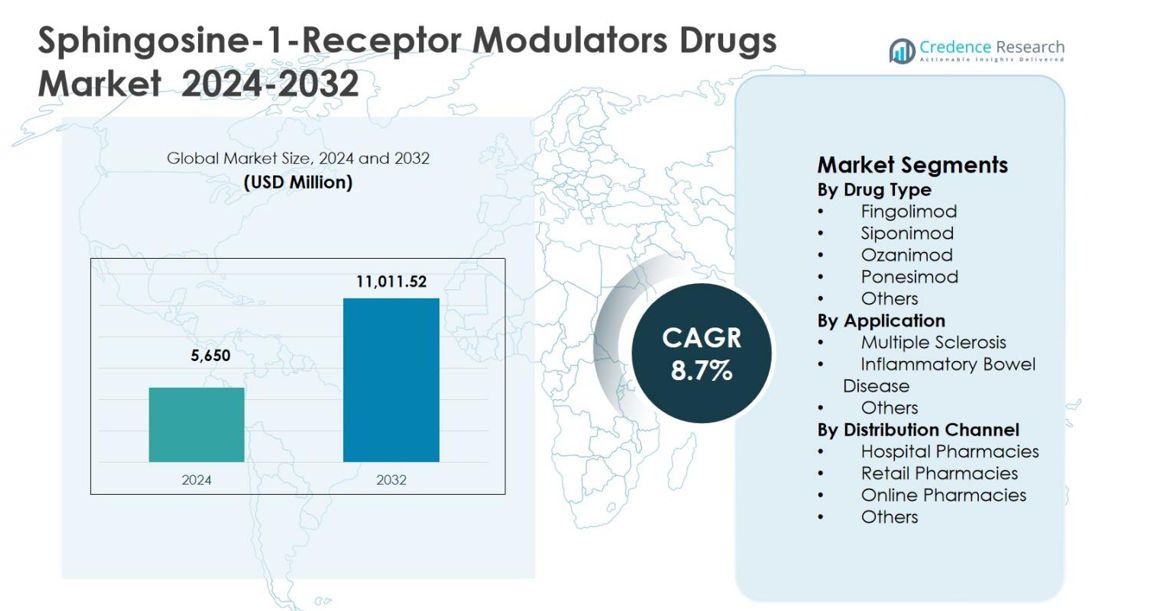
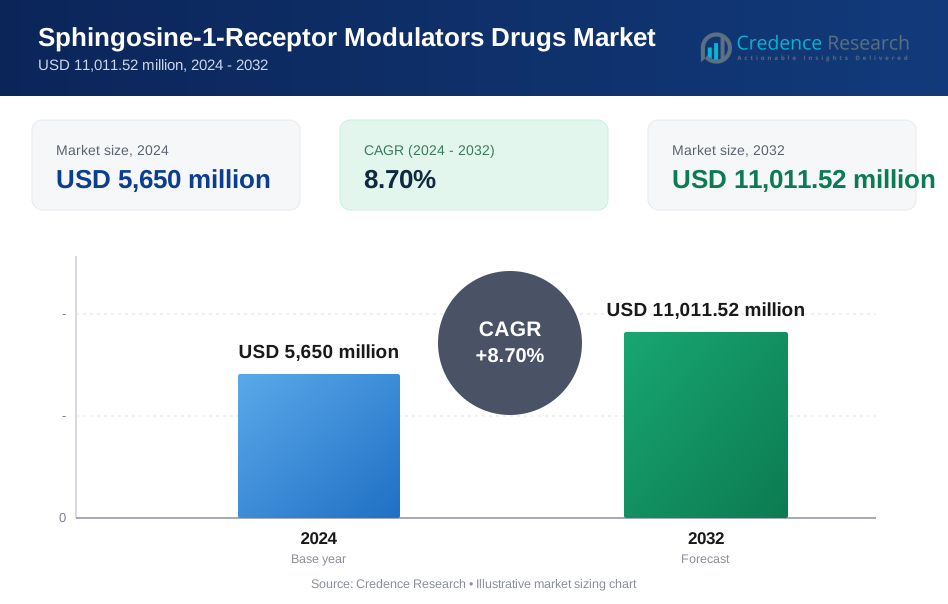
Sphingosine-1-Receptor Modulators Drugs Market size was valued at USD 5,650 million in 2024 and is anticipated to reach USD 11,011.52 million by 2032, growing at a CAGR of 8.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sphingosine-1-Receptor Modulators Drugs Market Size 2024 | USD 5,650 million |
| Sphingosine-1-Receptor Modulators Drugs Market, CAGR | 8.7% |
| Sphingosine-1-Receptor Modulators Drugs Market Size 2032 | USD 11,011.52 million |
Sphingosine-1-Receptor Modulators Drugs Market is driven by strong participation from leading pharmaceutical companies such as Novartis AG, Bristol-Myers Squibb Company, Merck & Co., Inc., Sanofi S.A., Pfizer Inc., Biogen Inc., Roche Holding AG, Eli Lilly and Company, and Teva Pharmaceutical Industries Ltd., which focus on product innovation, lifecycle management, and expanding therapeutic indications. These players invest heavily in research to enhance receptor selectivity and safety profiles while strengthening global distribution networks. Regionally, North America leads the Sphingosine-1-Receptor Modulators Drugs Market with a 41.8% market share, supported by high multiple sclerosis prevalence, advanced neurological care, and favorable reimbursement frameworks, followed by Europe with a 29.6% share, driven by structured healthcare systems and strong adoption of oral immunomodulatory therapies.
Market Insights
- Sphingosine-1-Receptor Modulators Drugs Market was valued at USD 5,650 million in 2024 and is projected to reach USD 11,011.52 million by 2032, growing at a CAGR of 8.7% during the forecast period, supported by rising adoption of oral immunomodulatory therapies.
- Market growth is driven by increasing prevalence of multiple sclerosis and other autoimmune disorders, with the Multiple Sclerosis segment holding a dominant 72.4% share in 2024 due to strong clinical efficacy and long-term disease management benefits.
- Product innovation and lifecycle strategies shape market dynamics, where Fingolimod leads the drug type segment with a 41.6% share in 2024, supported by early market entry, broad approvals, and established physician familiarity.
- Market expansion faces restraints from high treatment costs, safety monitoring requirements, and access limitations in price-sensitive regions, influencing reimbursement decisions and therapy initiation rates.
- Regionally, North America led with a 41.8% share in 2024, followed by Europe at 29.6%, Asia Pacific at 17.2%, Latin America at 6.3%, and Middle East & Africa at 5.1%, reflecting disparities in healthcare access and adoption levels.
Market Segmentation Analysis:
By Drug Type:
The Sphingosine-1-Receptor Modulators Drugs Market, by drug type, is led by Fingolimod, which accounted for 41.6% market share in 2024 due to its early market entry, strong clinical efficacy, and broad regulatory approvals for relapsing forms of multiple sclerosis. Fingolimod benefits from extensive physician familiarity and long-term safety data, supporting sustained prescriptions despite newer entrants. Siponimod and Ozanimod are gaining traction driven by improved receptor selectivity and favorable safety profiles, while Ponesimod adoption is supported by once-daily dosing. Ongoing lifecycle management and expanded indications continue to reinforce segment growth.
- For instance, Novartis' Gilenya (fingolimod) received FDA approval in 2018 for children and adolescents aged 10-17 with relapsing MS, showing an 82% reduction in annualized relapse rate versus interferon beta-1a over up to two years in the Phase III PARADIGMS trial.
By Application:
By application, Multiple Sclerosis dominated the Sphingosine-1-Receptor Modulators Drugs Market with a 72.4% share in 2024, driven by the high prevalence of relapsing-remitting multiple sclerosis and the established role of S1P receptor modulators in disease modification. Strong clinical evidence demonstrating relapse reduction and delayed disability progression supports widespread clinical adoption. Inflammatory Bowel Disease represents an emerging growth area, supported by ongoing clinical trials and regulatory progress for selective S1P modulators. The expanding therapeutic pipeline and rising diagnosis rates continue to strengthen application-level demand.
- For instance, Bristol Myers Squibb's ozanimod (Zeposia), approved for ulcerative colitis, demonstrated efficacy in phase III True North trials by reducing inflammatory markers like faecal calprotectin during induction and maintenance.
By Distribution Channel:
Based on distribution channel, Hospital Pharmacies held the dominant position with a 46.9% market share in 2024, supported by specialist-led prescribing, controlled initiation protocols, and monitoring requirements associated with S1P receptor modulators. Hospitals remain central to treatment initiation for multiple sclerosis patients, particularly during therapy switching and dose titration. Retail Pharmacies benefit from stable refill demand for chronic therapy, while Online Pharmacies are expanding due to improved patient access and digital prescription platforms. Reimbursement integration and specialty drug handling capabilities continue to favor hospital-led distribution.
Key Growth Driver
Rising Prevalence of Autoimmune Disorders
The Sphingosine-1-Receptor Modulators Drugs Market is significantly driven by the increasing global prevalence of autoimmune disorders, particularly multiple sclerosis. Growing diagnostic rates, improved disease awareness, and earlier treatment initiation are expanding the eligible patient pool. S1P receptor modulators offer targeted immune modulation, reduced relapse rates, and convenient oral administration, making them preferred options over injectable therapies. The chronic nature of autoimmune diseases ensures long-term therapy demand, while expanding indications beyond multiple sclerosis further strengthen sustained market growth across developed and emerging healthcare systems.
- For instance, Ozanimod from Bristol Myers Squibb sustained relapse-free rates of 69% at 60 months in the DAYBREAK extension study for relapsing multiple sclerosis. Continuous treatment from parent trials showed the lowest annualized relapse rates among participant groups.
Advancements in Drug Selectivity and Safety Profiles
Continuous advancements in receptor selectivity are accelerating adoption in the Sphingosine-1-Receptor Modulators Drugs Market. New-generation molecules such as siponimod and ozanimod demonstrate improved safety, reduced cardiovascular risks, and better tolerability compared to first-generation therapies. These enhancements expand physician confidence and patient adherence, supporting higher prescription volumes. Improved benefit-risk profiles also facilitate broader regulatory approvals and label expansions. Ongoing research efforts focused on minimizing adverse effects while maintaining efficacy continue to reinforce long-term market expansion.
- For instance, Siponimod selectively binds S1P1 and S1P5 receptors with low affinity for S1P3, mitigating cardiovascular effects observed in less selective modulators. Dose titration eliminates short-term vagomimetic cardiac impacts, with 12-month follow-up showing stabilized baroreflex sensitivity and normal autonomic responses in secondary progressive MS patients.
Expanding Regulatory Approvals and Reimbursement Coverage
Favorable regulatory approvals and expanding reimbursement frameworks are strengthening growth in the Sphingosine-1-Receptor Modulators Drugs Market. Regulatory agencies increasingly support innovative oral immunomodulators with proven clinical benefits. Inclusion of S1P receptor modulators in national treatment guidelines and insurance formularies improves patient access. Reimbursement support reduces treatment cost burdens, encouraging therapy initiation and continuation. These factors collectively accelerate market penetration, particularly in regions with structured healthcare systems and strong payer coverage.
Key Trend & Opportunity
Pipeline Expansion into New Therapeutic Indications
The Sphingosine-1-Receptor Modulators Drugs Market is witnessing strong opportunities from pipeline expansion into additional autoimmune and inflammatory conditions. Clinical development targeting inflammatory bowel disease, lupus, and dermatological disorders is broadening the therapeutic scope of S1P modulators. Positive trial outcomes create opportunities for label expansion and portfolio diversification. This trend enables manufacturers to maximize asset value while addressing unmet clinical needs. Expansion beyond multiple sclerosis positions the market for sustained revenue growth over the forecast period.
- For instance, Idorsia's cenerimod, a selective S1P1 receptor modulator, showed in a phase 2 CARE trial a statistically significant reduction in modified SLEDAI-2K scores at month 6 versus placebo (LS mean difference -1.19), alongside reduced circulating antibody-secreting cells.
Shift Toward Personalized and Oral Therapies
A growing preference for personalized and oral therapies is shaping opportunities in the Sphingosine-1-Receptor Modulators Drugs Market. Oral administration improves patient compliance and quality of life compared to injectable biologics. Advances in biomarker-driven treatment selection support tailored therapy choices, improving outcomes. Healthcare providers increasingly favor convenient dosing regimens combined with strong efficacy. This trend enhances patient retention and supports broader adoption across both established and emerging healthcare markets.
- For instance, Bristol Myers Squibb's Zeposia (ozanimod) reduces plasma neurofilament light chain (pNfL) levels by 20-27% at 12-24 months in relapsing MS trials, outperforming interferon beta-1a at 13-16%. This biomarker decline correlates with fewer lesions and better cognitive scores on tests like SDMT.
Key Challenge
Safety Concerns and Long-Term Risk Management
Safety concerns remain a key challenge in the Sphingosine-1-Receptor Modulators Drugs Market, particularly related to cardiovascular effects, infection risk, and long-term immune modulation. Mandatory monitoring requirements during treatment initiation increase clinical complexity and limit use in certain patient populations. Adverse event management influences prescribing decisions and may delay therapy adoption. Addressing long-term safety through post-marketing surveillance and real-world evidence remains critical for sustained market confidence.
High Treatment Costs and Access Limitations
High therapy costs present a significant challenge in the Sphingosine-1-Receptor Modulators Drugs Market, especially in price-sensitive regions. Patent protection and specialty drug pricing restrict affordability and limit widespread access. Inadequate reimbursement coverage in developing markets further constrains adoption. Cost pressures from healthcare payers also intensify price negotiations and formulary restrictions. Overcoming these barriers will require pricing strategies, patient assistance programs, and broader healthcare policy support to ensure equitable access.
Regional Analysis
North AmericaThe Sphingosine-1-Receptor Modulators Drugs Market in North America accounted for 41.8% market share in 2024, driven by high multiple sclerosis prevalence, advanced diagnostic infrastructure, and early adoption of novel immunomodulatory therapies. Strong presence of leading pharmaceutical manufacturers and robust clinical research activity support sustained innovation. Favorable reimbursement frameworks and inclusion of S1P receptor modulators in treatment guidelines improve patient access. High physician awareness, strong patient adherence to oral therapies, and ongoing label expansions continue to reinforce market dominance across the United States and Canada.
Europe
Europe held a 29.6% market share in 2024 in the Sphingosine-1-Receptor Modulators Drugs Market, supported by rising autoimmune disease incidence and well-established public healthcare systems. Regulatory approvals from the European Medicines Agency and strong adoption of second-generation S1P modulators drive regional growth. Countries such as Germany, France, and the United Kingdom lead demand due to specialist availability and structured reimbursement mechanisms. Increasing focus on cost-effective oral therapies and growing clinical trial activity across Western Europe further strengthen regional market performance.
Asia Pacific
The Asia Pacific region captured a 17.2% market share in 2024 in the Sphingosine-1-Receptor Modulators Drugs Market, supported by improving healthcare access and rising awareness of multiple sclerosis. Expanding diagnostic capabilities and increasing investments in specialty pharmaceuticals contribute to adoption growth. Japan and Australia show strong uptake due to advanced neurological care, while China and India present long-term growth opportunities driven by expanding patient populations. Government initiatives to improve access to innovative therapies and growing private healthcare expenditure support sustained regional expansion.
Latin America
Latin America accounted for a 6.3% market share in 2024 in the Sphingosine-1-Receptor Modulators Drugs Market, driven by gradual improvements in neurological care infrastructure. Brazil and Mexico dominate regional demand due to higher diagnosis rates and better access to specialty medications. Expanding private healthcare facilities and improving reimbursement coverage support market penetration. However, access limitations and cost sensitivity continue to influence prescribing patterns. Increasing awareness programs and regulatory alignment with global standards are expected to enhance regional growth prospects.
Middle East & Africa
The Middle East & Africa region represented a 5.1% market share in 2024 in the Sphingosine-1-Receptor Modulators Drugs Market, supported by growing investments in advanced healthcare services. Gulf Cooperation Council countries lead adoption due to higher healthcare spending and improved access to specialty drugs. Increasing physician training and expansion of tertiary care hospitals contribute to demand growth. In Africa, limited access and diagnostic gaps restrict uptake, although gradual healthcare infrastructure development and international partnerships support long-term market potential.
Market Segmentations:
By Drug Type
- Fingolimod
- Siponimod
- Ozanimod
- Ponesimod
- Others
By Application
- Multiple Sclerosis
- Inflammatory Bowel Disease
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Sphingosine-1-Receptor Modulators Drugs Market is characterized by the presence of key players including Novartis AG, Bristol-Myers Squibb Company, Merck & Co., Inc., Sanofi S.A., Pfizer Inc., Biogen Inc., Roche Holding AG, Eli Lilly and Company, and Teva Pharmaceutical Industries Ltd. The market is shaped by strong product portfolios, ongoing lifecycle management strategies, and continuous investment in research and development to enhance receptor selectivity and safety profiles. Leading companies focus on expanding approved indications, strengthening clinical evidence, and optimizing dosing regimens to sustain market positioning. Strategic collaborations, licensing agreements, and late-stage pipeline development support portfolio diversification and long-term revenue stability. Patent protection remains a key competitive factor, while emerging generic competition influences pricing strategies. Companies also emphasize geographic expansion, physician engagement, and real-world evidence generation to reinforce clinical adoption and maintain leadership across major healthcare markets.
Key Player Analysis
- Eli Lilly and Company
- Teva Pharmaceutical Industries Ltd.
- Roche Holding AG
- Bristol-Myers Squibb Company
- Sanofi S.A.
- Biogen Inc.
- Pfizer Inc.
- Celgene Corporation
- Novartis AG
- Merck & Co., Inc.
Recent Developments
- In February 2025, Nxera Pharma assigned the Japan and APAC (ex-China) rights to the investigational S1P₁ receptor modulator cenerimod to Viatris, giving Viatris exclusive global rights to develop and commercialize cenerimod, an oral S1P modulator being investigated for autoimmune diseases.
- In March 2024, Pfizer received approval from the UK Medicines and Healthcare products Regulatory Agency (MHRA) for Velsipity (etrasimod) in ulcerative colitis, expanding its regulatory footprint for this S1P receptor modulator in Europe.
- In December 2023, Vanda Pharmaceuticals announced that it acquired the U.S. and Canadian rights to PONVORY (ponesimod), a selective S1P1 receptor modulator for relapsing forms of multiple sclerosis, from Actelion Pharmaceuticals Ltd., a Johnson & Johnson company, in a transaction valued at 100 million dollars.
Report Coverage
The research report offers an in-depth analysis based on Drug Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Sphingosine-1-Receptor Modulators Drugs Market will continue expanding due to sustained demand for oral immunomodulatory therapies in autoimmune diseases.
- Advancements in receptor selectivity will improve safety profiles and support broader clinical adoption.
- Label expansions into additional inflammatory and neurological indications will strengthen long-term market growth.
- Increased real-world evidence generation will enhance physician confidence and prescribing consistency.
- Growing preference for oral therapies will improve patient adherence and treatment outcomes.
- Pipeline diversification will reduce reliance on single-indication revenue streams for manufacturers.
- Strategic collaborations will accelerate innovation and optimize late-stage drug development.
- Emerging markets will witness gradual adoption supported by improving diagnostic infrastructure.
- Pricing pressure from payers will drive value-based contracting and access-focused strategies.
- Ongoing post-marketing surveillance will play a critical role in sustaining long-term market trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Autoimmune Disorders
The increasing global incidence of autoimmune diseases, particularly multiple sclerosis, is expanding the eligible patient pool for S1P receptor modulators. Improved diagnosis and earlier treatment initiation are driving sustained demand for these targeted oral therapies.
Advancements in Drug Selectivity and Safety Profiles
Ongoing innovation in receptor selectivity has led to the development of next-generation S1P modulators with improved safety and tolerability. These advancements reduce cardiovascular risks and adverse effects, increasing physician confidence and patient adherence.
Expanding Regulatory Approvals and Reimbursement Coverage
Broader regulatory approvals and inclusion in national treatment guidelines are improving patient access to S1P receptor modulators. Enhanced reimbursement frameworks in key markets reduce cost barriers and support higher therapy initiation rates.
Pipeline Expansion into New Therapeutic Indications
Active clinical development targeting additional autoimmune and inflammatory conditions, such as inflammatory bowel disease and lupus, is broadening the market scope. Successful label expansions diversify revenue streams and address unmet clinical needs.
Shift Toward Personalized and Oral Therapies
The preference for oral administration and biomarker-driven treatment selection is increasing adoption of S1P modulators. These trends improve patient compliance, quality of life, and support broader uptake across both developed and emerging healthcare systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Sphingosine-1-Receptor Modulators Drugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Sphingosine-1-Receptor Modulators Drugs Market projected to grow between 2024 and 2032?
What factors are steering the growth of the Sphingosine-1-Receptor Modulator Drug Market?
What therapeutic applications do Sphingosine-1-Receptor Modulator Drug have?
How is innovation and research contributing to the Sphingosine-1-Receptor Modulator Drug Market?
What challenges and opportunities does the Sphingosine-1-Receptor Modulator Drug Market face?
Who are the leading companies in the Sphingosine-1-Receptor Modulators Drugs Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Type
- 1.2.1 Fingolimod
- 1.2.2 Siponimod
- 1.2.3 Ozanimod
- 1.2.4 Ponesimod
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Multiple Sclerosis
- 1.3.2 Inflammatory Bowel Disease
- 1.3.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,650 million → 2032: USD 11,011.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sphingosine-1-Receptor Modulators Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sphingosine-1-Receptor Modulators Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sphingosine-1-Receptor Modulators Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sphingosine-1-Receptor Modulators Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sphingosine-1-Receptor Modulators Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sphingosine-1-Receptor Modulators Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sphingosine-1-Receptor Modulators Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sphingosine-1-Receptor Modulators Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,650 million → 2032: USD 11,011.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sphingosine-1-Receptor Modulators Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fingolimod
- 12.3.7.2 Siponimod
- 12.3.7.3 Ozanimod
- 12.3.7.4 Ponesimod
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Multiple Sclerosis
- 12.4.7.2 Inflammatory Bowel Disease
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sphingosine-1-Receptor Modulators Drugs End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sphingosine-1-Receptor Modulators Drugs Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sphingosine-1-Receptor Modulators Drugs Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sphingosine-1-Receptor Modulators Drugs Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Novartis AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bristol-Myers Squibb Company
- 18.4 Merck & Co., Inc.
- 18.5 Sanofi S.A.
- 18.6 Pfizer Inc.
- 18.7 Biogen Inc.
- 18.8 Roche Holding AG
- 18.9 Eli Lilly and Company
- 18.10 Teva Pharmaceutical Industries Ltd.
- 18.11 Celgene Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

