
Market Overview:
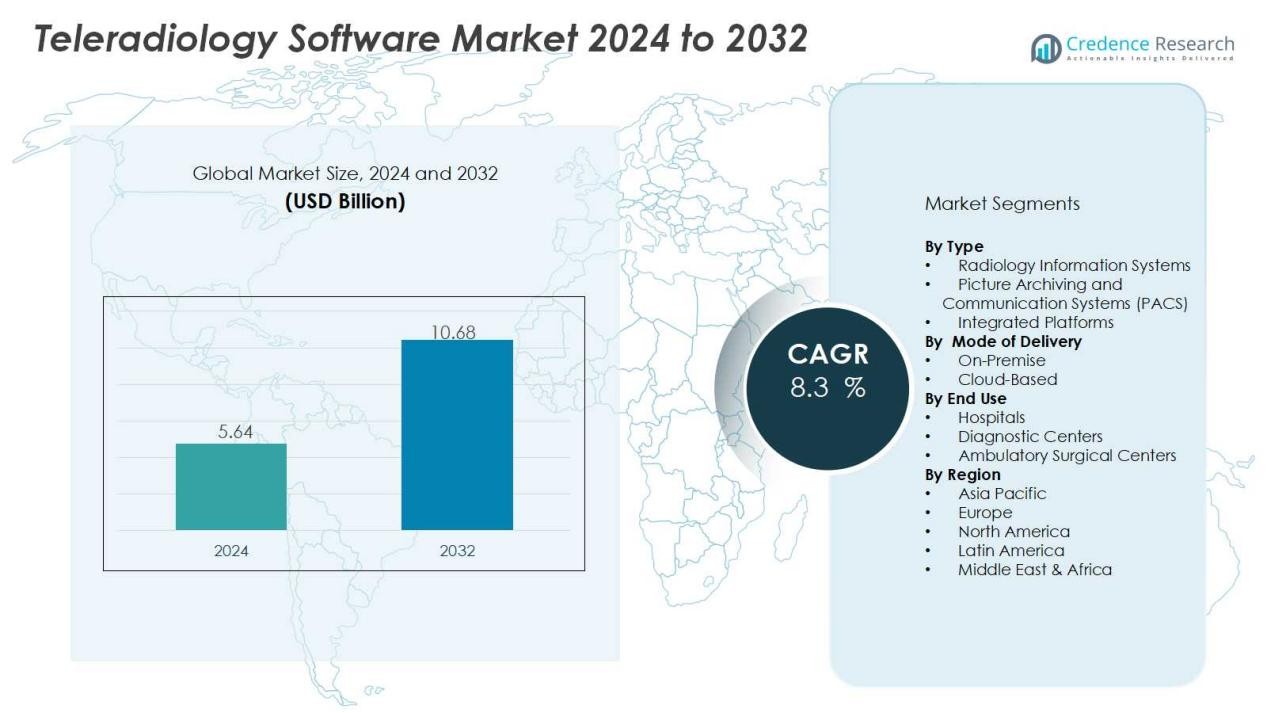
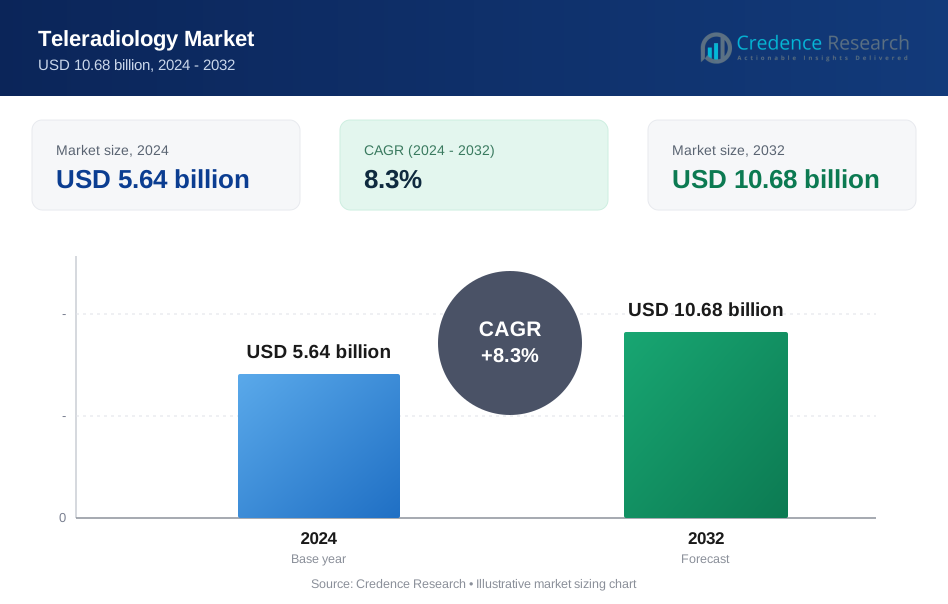
The teleradiology software market size was valued at USD 5.64 billion in 2024 and is anticipated to reach USD 10.68 billion by 2032, at a CAGR of 8.3 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Teleradiology Software Market Size 2024 | USD 5.64 Billion |
| Teleradiology Software Market, CAGR | 8.3 % |
| Teleradiology Software Market Size 2032 | USD 10.68 Billion |
Key drivers shaping the market include the growing shortage of skilled radiologists and the rising burden of chronic diseases that require imaging. Hospitals and clinics are investing in advanced software to improve turnaround time, reduce errors, and enable secure data sharing. Integration of artificial intelligence for image analysis, combined with rising adoption of PACS and RIS systems, also accelerates market expansion. Strong government support for telehealth and cost-effective care delivery further boosts adoption.
Regionally, North America dominates due to its advanced healthcare infrastructure, high adoption of digital health solutions, and favorable reimbursement policies. Europe follows closely, driven by strict healthcare standards and cross-border teleradiology services. Asia-Pacific is anticipated to be the fastest-growing region, led by India, China, and Southeast Asia, where growing healthcare investments, rapid digital transformation, and shortage of radiology professionals fuel demand. Latin America and the Middle East & Africa are also showing steady progress with gradual telehealth adoption.
Market Insights:
- The teleradiology software market was valued at USD 5.64 billion in 2024 and is projected to reach USD 10.68 billion by 2032 at a CAGR of 8.3%.
- Rising demand for remote radiology services is driving adoption as healthcare systems face increasing patient volumes and limited radiology staff.
- Integration of artificial intelligence and advanced imaging tools enhances diagnostic accuracy, speeds up reporting, and supports complex case management.
- The global shortage of skilled radiologists, coupled with growing imaging volumes, highlights the need for software that ensures timely and accurate reporting.
- Government support for telehealth infrastructure and investments in cloud platforms, cybersecurity, and data standardization accelerate adoption worldwide.
- Challenges include data security concerns, high implementation costs, and interoperability issues, which hinder smooth deployment across diverse healthcare systems.
- North America led with a 42% share in 2024, Europe followed with 28%, while Asia-Pacific held 19% and emerged as the fastest-growing region driven by healthcare investments and digital transformation.
Market Drivers:
Growing Demand for Remote Radiology Services Across Healthcare Systems:
The teleradiology software market is supported by rising demand for remote imaging services. Healthcare systems face increasing patient volumes and limited radiology staff, making remote reporting essential. Hospitals, clinics, and diagnostic centers use software to reduce delays and ensure faster diagnoses. It enables radiologists to collaborate across geographies, improving access to expert interpretation. This trend strongly aligns with healthcare’s shift toward efficiency and wider service reach.
- For Instance, vRad, a prominent U.S. teleradiology provider, interprets millions of patient studies each year for more than 2,100 facilities across the U.S..
Integration of Artificial Intelligence and Advanced Imaging Tools:
The adoption of artificial intelligence in teleradiology software is driving efficiency. AI tools support image recognition, automate reporting, and help reduce diagnostic errors. It enhances radiologists’ productivity by analyzing large imaging datasets quickly and accurately. Advanced imaging tools also support complex case management, such as oncology or cardiology, requiring precise interpretations. The software’s integration with PACS and RIS further strengthens workflow optimization.
- For instance, Siemens Healthineers and Intel achieved a 5.5× speedup in quantifying heart function on cardiac MRI scans using AI-powered image analysis.
Shortage of Skilled Radiologists and Growing Imaging Volumes:
Global healthcare systems face a critical shortage of trained radiologists, while demand for imaging continues to rise. The teleradiology software market benefits from this imbalance, as it helps bridge the gap through remote expertise. It ensures round-the-clock reporting services, even in regions with limited specialists. Growing use of MRI, CT, and PET scans for chronic disease management adds further pressure on radiology services. Software solutions support faster turnaround, helping healthcare providers maintain quality care.
Government Support and Expansion of Telehealth Infrastructure:
Governments worldwide are supporting telehealth adoption through policies and funding. The teleradiology software market gains from initiatives that encourage digital healthcare infrastructure development. It benefits from growing investments in cloud platforms, cybersecurity, and data standardization. Regulations promoting interoperability and secure patient data handling drive wider acceptance. Expanding telehealth networks in emerging economies create strong opportunities for adoption in underserved regions.
Market Trends:
Rising Adoption of AI-Powered and Cloud-Based Imaging Solutions:
The teleradiology software market is experiencing rapid adoption of AI-powered and cloud-based platforms. Healthcare providers are leveraging artificial intelligence to enhance accuracy, reduce diagnostic errors, and accelerate reporting workflows. It enables radiologists to manage growing imaging volumes with greater efficiency, especially in complex cases. Cloud-based deployment models are gaining popularity for their scalability, cost-effectiveness, and ability to support multi-location healthcare networks. Hospitals and diagnostic centers prefer cloud systems that allow secure access to imaging data across devices. Integration of AI with PACS and RIS further improves operational workflows and decision-making. This trend is transforming radiology services into more collaborative and data-driven systems.
- For instance, Global Diagnostics Australia implemented Aidoc’s AI solution to prioritize urgent cases in teleradiology, reducing critical case turnaround times across vast remote areas, supporting 24/7 patient care with AI-driven prioritization of intracranial hemorrhage and pulmonary embolism cases.
Expansion of Cross-Border Services and Telehealth Integration:
The teleradiology software market is also shaped by the expansion of cross-border services and integration with telehealth platforms. Growing collaborations between radiology providers across regions ensure round-the-clock reporting coverage. It allows healthcare systems in underserved regions to access specialist expertise without delays. Telehealth integration strengthens patient-centric care by enabling seamless communication between radiologists, physicians, and patients. Healthcare organizations are increasingly focusing on interoperability to ensure smooth data exchange across systems. Rising investments in digital health infrastructure support wider adoption of such integrated platforms. This trend highlights the market’s move toward global connectivity and comprehensive care delivery.
- For Instance, Dicom Systems' Unifier platform implements advanced DICOM Modality Worklist and application-level load balancing, serving over 600 healthcare sites globally to enable seamless cross-border image sharing and telehealth connectivity.
Market Challenges Analysis:
Data Security Concerns and Compliance with Regulations;
The teleradiology software market faces challenges related to data security and regulatory compliance. Patient information is highly sensitive, requiring strict adherence to standards such as HIPAA and GDPR. It is difficult for healthcare providers to balance fast data sharing with robust security protocols. Cybersecurity threats, including ransomware and data breaches, create risks that slow adoption in some regions. Differences in regulatory frameworks across countries complicate cross-border teleradiology services. Smaller healthcare institutions often lack resources to implement advanced compliance measures. This challenge remains a significant barrier to seamless global adoption.
High Implementation Costs and Interoperability Limitations:
The adoption of advanced teleradiology solutions is restricted by high implementation and maintenance costs. Many hospitals, particularly in developing regions, face budget constraints that limit investment. It becomes harder for smaller diagnostic centers to deploy comprehensive systems with AI and cloud integration. Interoperability also creates issues, as legacy systems may not integrate smoothly with modern platforms. Poor connectivity in rural areas further hinders consistent performance of remote radiology services. Lack of skilled IT staff in healthcare facilities increases reliance on vendors for ongoing support. These challenges highlight the need for cost-effective, interoperable, and scalable solutions to ensure widespread adoption.
Market Opportunities:
Expanding Role of Artificial Intelligence and Advanced Analytics:
The teleradiology software market has significant opportunities with the integration of artificial intelligence and advanced analytics. AI-powered tools can automate image analysis, prioritize urgent cases, and support faster decision-making. It enables healthcare providers to improve diagnostic accuracy while reducing workload pressure on radiologists. Predictive analytics and machine learning algorithms further enhance treatment planning and patient outcomes. Vendors that offer AI-driven solutions with seamless PACS and RIS integration can secure strong competitive advantages. Growing confidence in AI applications across healthcare creates long-term growth opportunities for market players.
Rising Adoption in Emerging Economies and Rural Healthcare:
The teleradiology software market also benefits from expanding adoption in emerging economies and underserved regions. Many countries face radiologist shortages, and remote software platforms provide access to specialized expertise. It allows rural and semi-urban healthcare centers to deliver advanced imaging services without heavy infrastructure investments. Governments and private investors are funding telehealth expansion to improve care delivery in these regions. Lower-cost cloud-based solutions are particularly attractive for small and mid-sized hospitals. Partnerships between global vendors and local healthcare providers will strengthen adoption and market penetration. This shift creates vast opportunities for scalable and accessible teleradiology software solutions.
Market Segmentation Analysis:
By Type:
The teleradiology software market by type is segmented into radiology information systems, picture archiving and communication systems, and integrated platforms. Integrated solutions are gaining preference due to their ability to streamline workflows and enhance collaboration. It supports seamless image storage, retrieval, and sharing across multiple healthcare facilities. Radiology information systems hold steady adoption for patient data management, while PACS remains vital for imaging storage and distribution. The demand for advanced, interoperable platforms continues to strengthen adoption across healthcare systems.
- For instance, PostDICOM’s PACS servers use advanced data compression and redundant storage techniques to manage high-volume images efficiently, supporting immediate access even during peak loads.
By Mode of Delivery:
The market by mode of delivery is divided into on-premise and cloud-based solutions. Cloud deployment is growing rapidly due to its scalability, cost efficiency, and secure remote access. It allows healthcare providers to manage large imaging volumes across different locations without heavy infrastructure costs. On-premise models still serve institutions with strict regulatory requirements or legacy system integration needs. However, the shift toward cloud platforms remains dominant, driven by rising telehealth adoption and cross-border services.
- For instance, Sectra’s on-premise PACS and VNA solutions are installed at over 2,000 healthcare sites worldwide as of June 2023, delivering sub-second image retrieval and local data governance for high-security environments.
By End Use:
The teleradiology software market by end use includes hospitals, diagnostic centers, and ambulatory surgical centers. Hospitals represent the largest share, supported by high imaging volumes and multi-specialty care requirements. It enables radiologists to deliver timely reporting and improved patient outcomes. Diagnostic centers are expanding adoption to meet demand for specialized imaging services with limited staff. Ambulatory surgical centers are integrating software to support outpatient care and streamline imaging-based procedures. Growing adoption across these end users highlights the market’s role in modern healthcare delivery.
Segmentations:
By Type:
- Radiology Information Systems
- Picture Archiving and Communication Systems (PACS)
- Integrated Platforms
By Mode of Delivery:
- On-Premise
- Cloud-Based
By End Use:
- Hospitals
- Diagnostic Centers
- Ambulatory Surgical Centers
By Region:
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Analysis:
North America:
North America held a 42% market share in 2024, supported by advanced healthcare systems and strong IT integration. The region’s dominance is driven by early adoption of digital health platforms and favorable reimbursement models. The teleradiology software market in the U.S. is strengthened by widespread use of cloud-based solutions and AI integration. It benefits from continuous investments in cybersecurity and compliance frameworks that support secure imaging workflows. Canada also contributes to growth with rising telehealth adoption and government-backed digital initiatives. Strong presence of leading vendors ensures availability of advanced platforms across hospitals and diagnostic centers. The region remains a benchmark for technological innovation and regulatory compliance.
Europe:
Europe accounted for a 28% market share in 2024, driven by cross-border teleradiology services and strict healthcare standards. Countries such as Germany, the U.K., and France are adopting advanced solutions to address increasing imaging demand. The teleradiology software market in Europe benefits from policies promoting interoperability and standardized data exchange. It is also supported by EU regulations that ensure patient data protection and drive wider adoption. Healthcare providers in the region are focusing on AI-driven platforms to reduce reporting delays and improve outcomes. The growing need for radiology collaboration across borders strengthens market expansion. High investment levels in digital health infrastructure position Europe as a leading growth hub.
Asia-Pacific:
Asia-Pacific held a 19% market share in 2024 and is projected to expand rapidly through 2032. The region’s growth is fueled by rising healthcare investments, shortage of skilled radiologists, and growing demand for telehealth. The teleradiology software market in Asia-Pacific benefits from large patient volumes and expanding diagnostic imaging centers. It is driven by China and India, where government initiatives support digital transformation in healthcare. Southeast Asian countries are adopting cloud-based solutions to strengthen diagnostic access in rural and underserved areas. Growing collaborations between local providers and international vendors expand adoption further. Asia-Pacific’s rapid digitalization ensures its position as the fastest-growing market segment.
Key Player Analysis:
- Carestream Health
- GE Healthcare
- Comarch SA
- Telerad Tech
- Perfect Imaging Solution's, LLC
- OpenRad
- RamSoft, Inc.
- Radical Imaging LLC
- Koninklijke Philips N.V.
- Pediatrix Medical Group
Competitive Analysis:
The teleradiology software market is highly competitive with both global and regional players driving innovation. Key companies include Carestream Health, GE Healthcare, Comarch SA, Telerad Tech, Perfect Imaging Solution's, LLC, OpenRad, and RamSoft, Inc. It is shaped by strong demand for cloud-based solutions, AI integration, and secure imaging platforms. Companies focus on interoperability with PACS and RIS to streamline workflows and improve efficiency. Strategic moves such as partnerships with hospitals, product launches, and geographic expansion strengthen their market presence. Leading vendors emphasize cybersecurity, scalability, and data compliance to gain trust among healthcare providers. Continuous innovation and differentiation remain critical for sustaining leadership in this evolving landscape.
Recent Developments:
- In July 2025, Carestream Health secured a partnership with Vietnam South East Asia Joint Stock Company (VISTACOM), a leading medical equipment distributor in Vietnam, to expand its medical imaging reach in the region.
- In March 2025, GE Healthcare finalized the acquisition of Nihon Medi-Physics, a leading radiopharmaceutical company in Japan, to expand its radiopharmaceutical business.
Report Coverage:
The research report offers an in-depth analysis based on Type, Mode of Delivery, End Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Growing reliance on AI-driven teleradiology platforms will enhance diagnostic accuracy and efficiency.
- Cloud-based deployment will continue to dominate due to scalability, cost-effectiveness, and secure remote access.
- Expansion of telehealth ecosystems will integrate teleradiology software with broader digital healthcare platforms.
- Rising demand for cross-border radiology services will drive global collaboration and data sharing.
- Vendors will invest in advanced cybersecurity frameworks to address rising concerns over patient data safety.
- Healthcare providers in emerging economies will adopt cost-effective solutions to overcome radiologist shortages.
- Interoperability with PACS, RIS, and EHR systems will remain a key priority for hospitals and clinics.
- Government-backed digital health initiatives will accelerate adoption in both developed and developing regions.
- Vendors will focus on customizable solutions to meet the needs of small and mid-sized hospitals.
- Growing emphasis on patient-centric care will encourage platforms that enable seamless communication across healthcare teams.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Teleradiology Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Teleradiology Software Market projected to grow between 2024 and 2032?
Which Teleradiology Software Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Teleradiology Software Market?
Who are the leading companies in the Teleradiology Software Market?
Which region commanded the largest share of the Teleradiology Software Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Teleradiology Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Teleradiology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5.64 billion → 2032: USD 10.68 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Teleradiology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Teleradiology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Teleradiology Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Teleradiology Market Drivers
- 3.3 Teleradiology Market Restraints & Challenges
- 3.4 Teleradiology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Teleradiology Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Teleradiology Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Teleradiology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Teleradiology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Teleradiology Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Teleradiology market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Teleradiology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Teleradiology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Teleradiology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Teleradiology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Teleradiology Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Teleradiology Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Teleradiology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Teleradiology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Teleradiology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Teleradiology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Teleradiology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Teleradiology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Teleradiology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
