
Market Overview
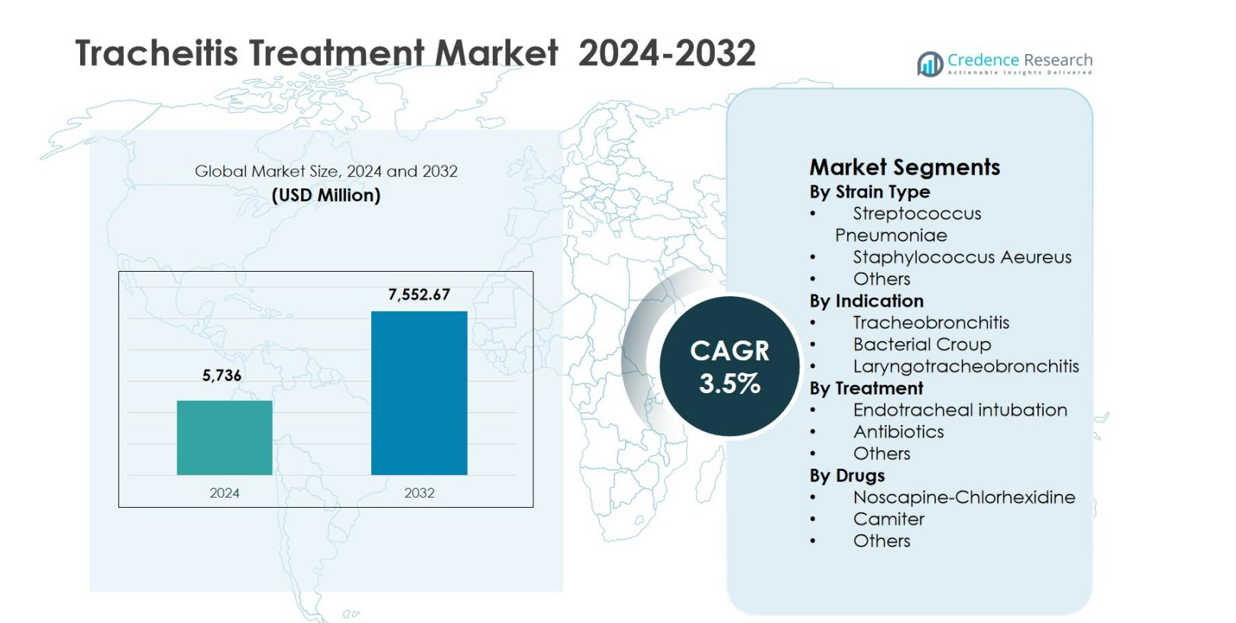
Tracheitis Treatment Market size was valued USD 5,736 million in 2024 and is anticipated to reach USD 7,552.67 million by 2032, at a CAGR of 3.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Tracheitis Treatment Market Size 2024 | USD 5,736 million |
| Tracheitis Treatment Market, CAGR | 3.5% |
| Tracheitis Treatment Market Size 2032 | SD 7,552.67 million |
Tracheitis Treatment Market is characterized by the presence of established pharmaceutical companies such as Novartis AG, GSK plc, AstraZeneca, Abbott, Teva Pharmaceutical Industries Ltd., Cipla Inc., Mylan N.V., Vertex Pharmaceuticals Incorporated, SAVAL Pharmaceuticals, and Genom Biotech Pvt. Ltd., which focus on antibiotic therapies and hospital-based respiratory treatments. These players emphasize broad product availability, pediatric formulations, and strong distribution networks to support consistent treatment demand. Regionally, North America led the Tracheitis Treatment Market with a 38.6% share in 2024, supported by advanced healthcare infrastructure and high awareness of respiratory disorders. Europe followed with a 27.4% share, driven by standardized treatment protocols, while Asia Pacific accounted for 22.1%, reflecting expanding healthcare access and rising respiratory infection prevalence.
Market Insights
- Tracheitis Treatment Market was valued at USD 5,736 million in 2024 and is projected to reach USD 7,552.67 million by 2032, growing at a CAGR of 3.5% during the forecast period.
- Market growth is supported by rising respiratory infections among pediatric and adult populations, with antibiotics holding the dominant treatment segment share of 52.6% in 2024 due to first-line clinical usage and standardized prescribing practices.
- Ongoing trends include increased focus on pediatric respiratory care, early diagnosis, and evidence-based treatment pathways, while leading players such as Novartis AG, GSK plc, AstraZeneca, Abbott, Cipla Inc., and Teva Pharmaceutical Industries Ltd. strengthen product availability and hospital penetration.
- Market restraints include antibiotic resistance risks and delayed diagnosis, which increase treatment complexity and emphasize the need for antimicrobial stewardship and improved diagnostic accuracy.
- Regionally, North America dominated with a 38.6% share in 2024, followed by Europe at 27.4% and Asia Pacific at 22.1%, driven by healthcare infrastructure strength, treatment accessibility, and rising disease awareness.
Market Segmentation Analysis:
By Strain Type:
The Tracheitis Treatment Market by strain type is led by Streptococcus Pneumoniae, which accounted for 44.2% market share in 2024, driven by its high prevalence in bacterial tracheitis cases and strong association with respiratory tract infections in pediatric and geriatric populations. The segment benefits from established diagnostic protocols and well-defined antibiotic treatment pathways, supporting consistent treatment demand. Staphylococcus Aeureus follows due to its role in severe and hospital-acquired infections, while Others contribute a smaller share owing to lower incidence rates. Rising respiratory infection burden and improved microbial identification techniques continue to support segment growth.
By Indication:
Based on indication, Laryngotracheobronchitis dominated the Tracheitis Treatment Market with a 46.8% share in 2024, supported by its higher clinical occurrence, especially among children, and frequent requirement for medical intervention. The segment’s growth is driven by increasing pediatric respiratory infections, seasonal viral outbreaks, and prompt hospital admissions for airway management. Tracheobronchitis holds a notable share due to recurrent adult cases linked to chronic respiratory conditions, while Bacterial Croup contributes steadily, supported by improved diagnosis and early-stage treatment adoption in emergency care settings.
- For instance, dexamethasone at 0.6 mg/kg as a single oral or intramuscular dose reduces hospitalization needs in children with croup, with most cases resolving within 3-4 days under outpatient care.
By Treatment:
In the treatment segment, Antibiotics emerged as the dominant sub-segment, capturing 52.6% of the market share in 2024, driven by their first-line use in bacterial tracheitis management and widespread clinical acceptance. The segment benefits from broad-spectrum antibiotic availability, rapid treatment initiation, and standardized prescribing practices. Endotracheal intubation holds a significant share due to its critical role in severe airway obstruction cases, particularly in intensive care units, while Others maintain moderate demand through adjunct therapies and supportive respiratory interventions.
- For instance, Aristo Pharmaceuticals' Monocef (ceftriaxone) pairs with vancomycin in initial therapy targeting Staphylococcus aureus and Streptococcus pneumoniae, following gram-positive cocci identification in tracheal cultures during acute obstruction management.
Key Growth Drivers
Rising Incidence of Respiratory Infections
The Tracheitis Treatment Market is strongly driven by the increasing incidence of respiratory infections among pediatric and adult populations. Factors such as worsening air pollution, higher exposure to allergens, and frequent seasonal viral outbreaks elevate the risk of secondary bacterial infections, including tracheitis. Children remain particularly susceptible due to immature immune systems, resulting in higher hospitalization rates. This growing patient pool directly increases demand for antibiotics, airway support procedures, and hospital-based care, supporting sustained growth of tracheitis treatment solutions across global healthcare systems.
- For instance, Phoenix Children's Hospital reports use initial IV vancomycin and ceftriaxone empirically for bacterial tracheitis to cover S. aureus (including MRSA) and streptococci, with ceftaroline as a monotherapy alternative, combined with airway control via intubation if needed for critically ill children.
Advancements in Diagnostic and Clinical Management
Ongoing advancements in diagnostic technologies and clinical management practices significantly support the Tracheitis Treatment Market. Rapid pathogen identification, improved imaging techniques, and enhanced clinical monitoring enable early detection and accurate assessment of disease severity. These advancements facilitate timely antibiotic administration and appropriate airway interventions, reducing complications and length of hospital stays. The adoption of standardized treatment guidelines and improved emergency response capabilities further strengthen treatment outcomes and reinforce consistent demand for effective tracheitis management approaches.
- For instance, quality improvement at Boston Children's Hospital limited repeat tracheal aspirate cultures to over 72-hour intervals, reducing culture rates from 10.70 to 7.10 per 100 endotracheal tube/tracheostomy days while maintaining appropriate sampling.
Expansion of Healthcare Infrastructure in Emerging Economies
The expansion of healthcare infrastructure in emerging economies is a key growth driver for the Tracheitis Treatment Market. Increased investments in hospitals, pediatric intensive care units, and emergency respiratory services improve access to timely diagnosis and treatment. Growing healthcare awareness, expanding insurance coverage, and better availability of essential medications enhance treatment uptake. As healthcare delivery systems continue to strengthen in developing regions, demand for tracheitis treatment therapies remains stable and geographically widespread.
Key Trends & Opportunities
Growing Focus on Pediatric Respiratory Care
A major trend shaping the Tracheitis Treatment Market is the increasing focus on pediatric respiratory care. Healthcare providers emphasize early diagnosis and specialized airway management for children, who represent a significant portion of tracheitis cases. This trend encourages the development of pediatric-specific antibiotic formulations, optimized dosing strategies, and less invasive airway management techniques. Improved training of pediatric specialists and refined clinical protocols further enhance treatment effectiveness and create long-term growth opportunities.
- For instance, Merck Manuals recommend initial IV vancomycin combined with ceftriaxone for pediatric bacterial tracheitis to cover S. aureus including MRSA and streptococcal species empirically.
Integration of Evidence-Based Treatment Protocols
The integration of evidence-based treatment protocols is creating new opportunities within the Tracheitis Treatment Market. Hospitals are increasingly implementing standardized clinical pathways that promote early intervention, appropriate antibiotic use, and timely airway management. These protocols improve patient outcomes, reduce treatment variability, and optimize healthcare resource utilization. This trend supports steady demand for validated therapeutic options and fosters collaboration between healthcare providers and pharmaceutical companies.
- For instance, Boston Children's Hospital standardized tracheal aspirate sampling criteria and empiric antibiotic therapy (cefepime and vancomycin for 3 days) for mechanically ventilated children with acute tracheitis.
Key Challenges
Risk of Antibiotic Resistance
Antibiotic resistance presents a significant challenge for the Tracheitis Treatment Market by reducing treatment effectiveness and complicating clinical management. Frequent use of broad-spectrum antibiotics increases the risk of resistant bacterial strains, leading to prolonged treatment durations and higher healthcare costs. This challenge necessitates strict antibiotic stewardship programs and careful treatment selection, placing additional pressure on healthcare systems and limiting therapeutic flexibility.
Limited Awareness and Delayed Diagnosis
Limited disease awareness and delayed diagnosis remain critical challenges in the Tracheitis Treatment Market, especially in low-resource settings. Early symptoms often resemble common respiratory infections, resulting in misdiagnosis or postponed medical intervention. Delayed treatment increases the likelihood of airway obstruction and intensive care requirements, raising clinical risk and cost burden. Addressing this challenge requires improved clinician training, public awareness efforts, and broader access to diagnostic capabilities.
Regional Analysis
North America
North America led the Tracheitis Treatment Market with a 38.6% market share in 2024, supported by advanced healthcare infrastructure, high awareness of respiratory disorders, and strong access to hospital-based emergency care. The region benefits from early diagnosis, widespread availability of antibiotics, and well-established clinical guidelines for airway management. High pediatric hospital admission rates for respiratory infections and strong reimbursement coverage further drive treatment adoption. The presence of major pharmaceutical companies and continuous investments in respiratory care research strengthen market stability across the United States and Canada.
Europe
Europe accounted for a 27.4% market share in 2024 in the Tracheitis Treatment Market, driven by robust public healthcare systems and strong focus on pediatric and emergency respiratory care. Countries such as Germany, the U.K., and France benefit from standardized treatment protocols and high hospital accessibility. Increasing incidence of seasonal respiratory infections and growing geriatric populations contribute to sustained demand. Government-supported healthcare funding and emphasis on evidence-based antibiotic use further support consistent adoption of tracheitis treatment therapies across the region.
Asia Pacific
Asia Pacific captured a 22.1% market share in 2024, reflecting rising healthcare investments and a growing burden of respiratory infections. High pediatric population density, increasing urban air pollution, and improving access to hospital care drive market expansion. Countries such as China, India, and Japan are strengthening healthcare infrastructure, enhancing diagnostic capabilities, and expanding antibiotic availability. Growing health awareness and increasing government focus on infectious disease management continue to support demand for tracheitis treatment solutions across both urban and semi-urban areas.
Latin America
Latin America held a 7.3% market share in 2024 in the Tracheitis Treatment Market, supported by gradual improvements in healthcare access and expanding hospital networks. Brazil and Mexico contribute significantly due to rising respiratory infection cases and improving emergency care services. Increased public healthcare spending, better availability of essential antibiotics, and growing awareness of pediatric respiratory conditions are supporting treatment adoption. However, disparities in healthcare access between urban and rural regions continue to influence overall market penetration.
Middle East & Africa
The Middle East & Africa region accounted for a 4.6% market share in 2024, driven by expanding healthcare infrastructure in Gulf countries and improving access to hospital care. Rising incidence of respiratory infections, increasing pediatric healthcare initiatives, and gradual adoption of standardized treatment protocols support market growth. Countries such as Saudi Arabia and the UAE are investing in advanced hospital facilities, while parts of Africa benefit from international healthcare programs. Limited awareness and access remain constraints, but steady improvements continue to support market development.
Market Segmentations:
By Strain Type
- Streptococcus Pneumoniae
- Staphylococcus Aeureus
- Others
By Indication
- Tracheobronchitis
- Bacterial Croup
- Laryngotracheobronchitis
By Treatment
- Endotracheal intubation
- Antibiotics
- Others
By Drugs
- Noscapine-Chlorhexidine
- Camiter
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Tracheitis Treatment Market highlights the presence of established pharmaceutical manufacturers including Novartis AG, GSK plc, AstraZeneca, Abbott, Teva Pharmaceutical Industries Ltd., Cipla Inc., Mylan N.V., Vertex Pharmaceuticals Incorporated, SAVAL Pharmaceuticals, and Genom Biotech Pvt. Ltd. These companies focus on broad-spectrum antibiotics, pediatric formulations, and hospital-based respiratory therapies to address varying disease severity. Market participants prioritize portfolio expansion through formulation improvements, regulatory approvals, and regional distribution strengthening. Strong emphasis on hospital partnerships and emergency care penetration supports consistent product demand. Companies are also investing in antimicrobial stewardship, clinical research, and post-marketing surveillance to improve treatment outcomes and safety profiles. Geographic expansion across emerging markets, supported by affordable generic offerings, remains a key strategic focus. Overall, competition is shaped by product availability, pricing efficiency, clinical reliability, and the ability to meet standardized treatment guidelines across diverse healthcare settings.
Key Player Analysis
- AstraZeneca (U.K.)
- Cipla Inc. (India)
- Teva Pharmaceutical Industries Ltd. (Israel)
- SAVAL Pharmaceuticals (U.S.)
- Novartis AG (Switzerland)
- Genom Biotech Pvt. Ltd. (India)
- Mylan N.V. (U.S.)
- GSK plc (U.K.)
- Vertex Pharmaceuticals Incorporated (U.S.)
- Abbott (U.S.)
Recent Developments
- In February 2025, Pfizer and AbbVie’s combination antibiotic aztreonam/avibactam (Emblaveo) received U.S. FDA approval, offering new options for severe Gram-negative bacterial infections including hospital-acquired respiratory infections.
- In May 2025, GSK announced it will acquire efimosfermin from Boston Pharmaceuticals for up to $2 billion, bolstering its broader inflammatory and infection-linked disease pipeline, which may intersect with respiratory care innovations.
Report Coverage
The research report offers an in-depth analysis based on Strain Type, Indication, Treatment, Drugs and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Tracheitis Treatment Market will continue to grow steadily, supported by the persistent burden of respiratory infections across pediatric and adult populations.
- Increasing focus on early diagnosis and timely intervention will strengthen demand for antibiotic therapies and airway management solutions.
- Hospitals will remain the primary treatment setting due to the need for close monitoring and emergency respiratory support.
- Pediatric-focused treatment protocols will gain wider adoption, driven by higher incidence rates among children.
- Advancements in diagnostic accuracy will enable more targeted and effective treatment approaches.
- Demand for broad-spectrum and pathogen-specific antibiotics will remain strong under standardized clinical guidelines.
- Emerging economies will contribute significantly to market expansion as healthcare infrastructure improves.
- Growing awareness of antimicrobial stewardship will influence prescribing practices and product development.
- Strategic partnerships between pharmaceutical companies and healthcare providers will support market penetration.
- Continuous investment in respiratory care and infection management will sustain long-term market stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Tracheitis Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Tracheitis Treatment Market projected to grow between 2024 and 2032?
How is the market responding to concerns about antibiotic resistance in tracheitis treatment?
What technological advancements are influencing the delivery of tracheitis treatment?
What preventative measures are being emphasized in the tracheitis treatment market?
Who are the leading companies in the Tracheitis Treatment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Tracheitis Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Tracheitis Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,736 million → 2032: USD 7,552.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Tracheitis Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Tracheitis Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Tracheitis Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Tracheitis Treatment Market Drivers
- 3.3 Tracheitis Treatment Market Restraints & Challenges
- 3.4 Tracheitis Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Tracheitis Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Tracheitis Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Tracheitis Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Tracheitis Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Tracheitis Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Tracheitis Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Tracheitis Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Tracheitis Treatment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Tracheitis Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Tracheitis Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Tracheitis Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Tracheitis Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Tracheitis Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Tracheitis Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Tracheitis Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Tracheitis Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Tracheitis Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Tracheitis Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Tracheitis Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
