
Market Overview
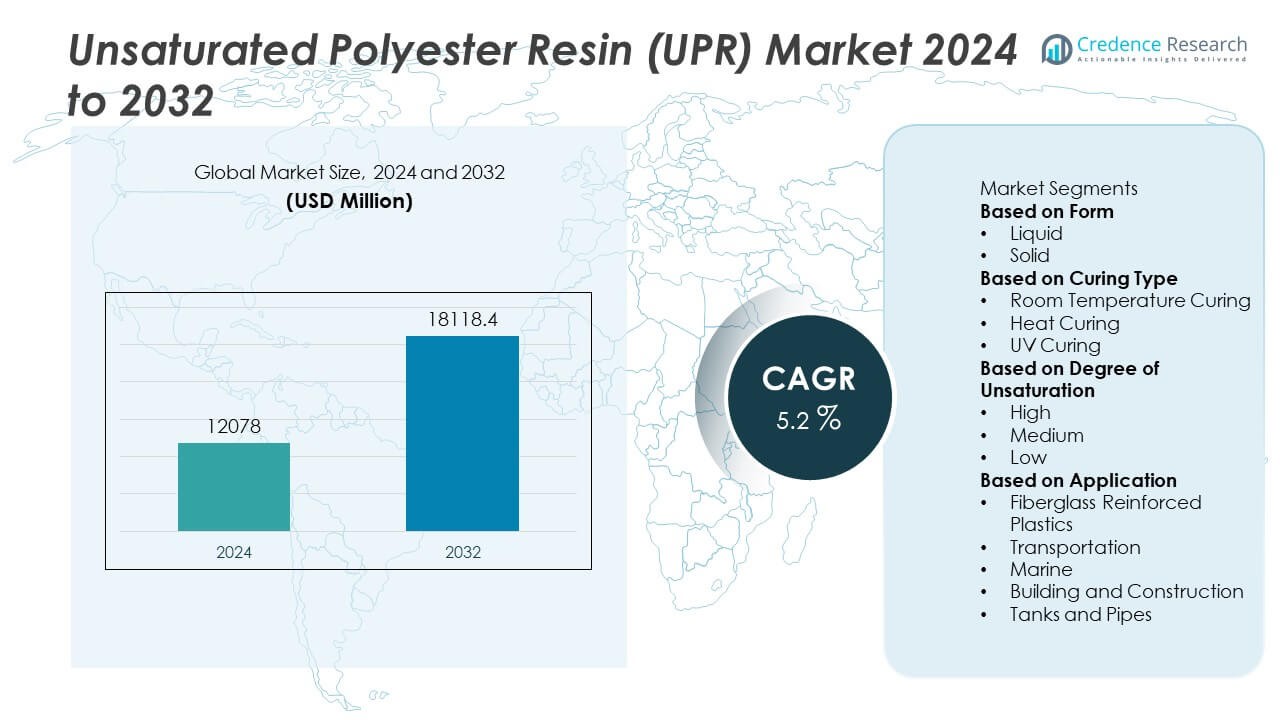
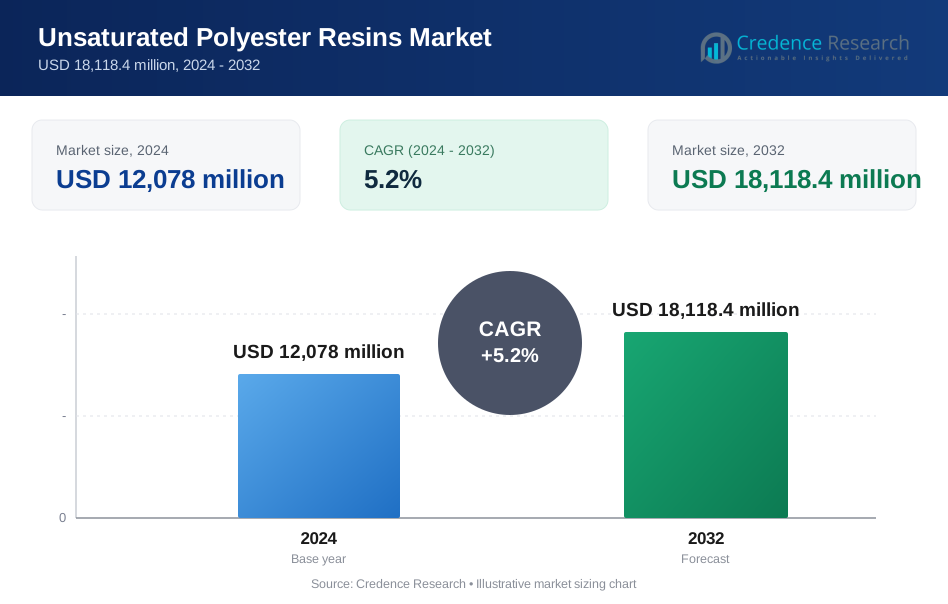
The Unsaturated Polyester Resin (UPR) Market was valued at USD 12,078 million in 2024 and is projected to reach USD 18,118.4 million by 2032, expanding at a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Unsaturated Polyester Resin (UPR) Market Size 2024 | USD 12,078 Million |
| Unsaturated Polyester Resin (UPR) Market, CAGR | 5.2% |
| Unsaturated Polyester Resin (UPR) Market Size 2032 | USD 18,118.4 Million |
The Unsaturated Polyester Resin (UPR) Market grows on the strength of rising demand from construction, automotive, marine, and renewable energy sectors. UPR is widely used in pipes, tanks, building panels, wind turbine blades, and automotive components due to its durability, cost-effectiveness, and versatility.
The Unsaturated Polyester Resin (UPR) Market demonstrates strong growth across regions, supported by rising infrastructure projects, industrial expansion, and renewable energy developments. Asia-Pacific leads demand with rapid urbanization, large-scale construction, and growing automotive production, while Europe emphasizes sustainability and renewable integration through offshore wind and marine applications. North America shows steady growth with UPR used in pipelines, automotive composites, and housing projects, while Latin America and the Middle East & Africa advance with expanding construction and industrial initiatives. Key players shaping the market include Ashland, Arkema, and BASF, which focus on high-performance resins and advanced formulations. Evonik and Huntsman strengthen their portfolios with innovative composite solutions and strategic partnerships, while Polynt and AOC expand their presence through tailored products for infrastructure and automotive applications. Together, these companies drive innovation and competitiveness, ensuring UPR remains a versatile and indispensable material for diverse global industries.
Market Insights
- The Unsaturated Polyester Resin (UPR) Market was valued at USD 12,078 million in 2024 and is projected to reach USD 18,118.4 million by 2032, expanding at a CAGR of 5.2% during the forecast period.
- Rising demand from construction, automotive, marine, and renewable energy sectors drives the adoption of UPR for pipes, tanks, building panels, automotive parts, and wind turbine blades.
- A key trend shaping the market is the development of eco-friendly and bio-based UPR formulations, along with low-styrene emission variants to meet sustainability and regulatory requirements.
- The competitive landscape features major players such as Ashland, Arkema, BASF, Evonik, Huntsman, and Polynt, along with AOC and Reichhold, all investing in R&D, product diversification, and strategic expansions.
- Market restraints include volatility in raw material prices, particularly styrene and maleic anhydride, along with strict environmental regulations that increase compliance costs for producers.
- Regionally, Asia-Pacific leads growth due to large-scale industrialization, urban expansion, and infrastructure investments, while Europe focuses on renewable energy and bio-based composites, and North America shows strong usage in automotive and construction applications.
- The market outlook remains positive as industries continue to prioritize lightweight, durable, and cost-effective composite materials, ensuring UPR’s critical role in supporting global infrastructure and sustainable industrial growth.
Market Drivers
Rising Demand from Construction and Infrastructure
The Unsaturated Polyester Resin (UPR) Market benefits significantly from rapid growth in global construction and infrastructure projects. UPR is widely used in reinforced composites, roofing, cladding, and sanitary ware due to its strength and durability. It helps reduce material costs while maintaining high performance, making it a preferred choice for large-scale applications. Expanding urbanization in emerging economies fuels demand for lightweight and resilient building materials. Governments invest heavily in housing, transportation, and energy infrastructure, driving consistent use of UPR. It positions UPR as a critical material for supporting long-term infrastructure development.
- For instance, China's Unsaturated Polyester Resin (UPR) consumption exceeded 1.2 million metric tons, primarily due to robust infrastructure expansion and high demand from the expanding electric vehicle (EV) industry.
Expanding Applications in Automotive and Transportation
The automotive sector plays a vital role in driving UPR demand due to its requirement for lightweight, fuel-efficient materials. The Unsaturated Polyester Resin (UPR) Market finds strong adoption in automotive parts, including body panels, bumpers, and interior components. It improves vehicle efficiency by reducing overall weight while maintaining strength and design flexibility. Electric vehicle manufacturing also increases UPR use in battery enclosures and lightweight structural parts. Automotive OEMs invest in composite materials that enhance performance and sustainability. It accelerates UPR adoption across both conventional and electric mobility platforms.
- For instance, the automotive and transport sector consumed approximately 1.04 million metric tonnes of UPR in 2023, indicating significant use in vehicle composite applications.
Growth in Marine and Wind Energy Sectors
Marine and renewable energy industries create major opportunities for UPR consumption. The Unsaturated Polyester Resin (UPR) Market supports marine applications such as boat hulls, decks, and interior components due to its water resistance and cost-effectiveness. It also plays a key role in manufacturing wind turbine blades, which demand strong and lightweight materials. Rising investments in offshore wind projects across Europe and Asia further elevate demand. Manufacturers adopt UPR formulations designed for high fatigue resistance and long service life. It reinforces the role of UPR as an enabler of sustainable energy transitions.
Rising Focus on Cost-Effectiveness and Versatility
The cost-effectiveness and versatility of UPR drive its adoption across multiple industries. The Unsaturated Polyester Resin (UPR) Market grows with its ability to be tailored for diverse applications, from electrical components to consumer goods. It offers superior moldability, making it suitable for complex designs in industrial products. Lower production costs compared to alternative resins strengthen its competitiveness in price-sensitive markets. Manufacturers emphasize UPR due to its balance of performance, flexibility, and affordability. It secures UPR’s role as a versatile solution for industries seeking efficient material alternatives.
Market Trends
Shift Toward Sustainable and Eco-Friendly Resins
The Unsaturated Polyester Resin (UPR) Market shows a clear trend toward sustainability as industries adopt eco-friendly materials. Manufacturers develop bio-based and low-styrene emission UPR to reduce environmental impact and meet regulatory requirements. It supports global efforts to cut carbon emissions and improve workplace safety. Consumer preference for greener products drives industries to switch to sustainable composites. Companies invest in R&D to create resins from renewable feedstocks, aligning with circular economy goals. It positions sustainable UPR as a growing segment within the overall market.
- For instance, Evonik introduced DYNACOLL® eCO polyester resins in March 2023, offering partially bio‑based polyols containing 500 grams of renewable content per kilogram of product for use in adhesives and composite formulations.
Rising Use in Lightweight Composites
The demand for lightweight yet durable materials drives innovation in UPR-based composites. The Unsaturated Polyester Resin (UPR) Market benefits from rising adoption in sectors such as automotive, aerospace, and construction. It enables weight reduction without compromising mechanical strength or performance. Industries increasingly replace traditional metals with UPR composites for efficiency gains. Advanced resin formulations deliver high fatigue resistance and longer service life in demanding applications. It reflects the growing role of UPR in supporting material innovation across multiple industries.
- For instance, Huntsman’s VITROX® and RIMLINE® polyurethane composite systems delivered cycle times under 10 minutes and incorporated mass‑balanced bio‑content in formulations used for automotive structural parts.
Increasing Penetration in Renewable Energy Applications
Renewable energy projects contribute significantly to UPR demand, particularly in wind energy and solar panel components. The Unsaturated Polyester Resin (UPR) Market expands as countries invest in clean energy infrastructure. It plays an essential role in producing large wind turbine blades that require lightweight and durable composites. Manufacturers design UPR solutions with enhanced fatigue resistance to withstand extreme operational environments. Offshore wind projects in Europe and Asia create substantial opportunities for UPR suppliers. It strengthens the position of UPR as a key material in the renewable energy sector.
Growing Adoption of Advanced Manufacturing Processes
Technological advancements in manufacturing influence UPR applications across industries. The Unsaturated Polyester Resin (UPR) Market benefits from automated molding, resin transfer molding (RTM), and additive manufacturing techniques. It allows higher precision, reduced waste, and faster production cycles. Integration of digital design tools with composite manufacturing enhances efficiency and quality. Companies leverage automation to meet rising demand for cost-effective, high-volume production. It highlights how process innovation continues to shape UPR adoption in global markets.
Market Challenges Analysis
Volatility in Raw Material Prices
The Unsaturated Polyester Resin (UPR) Market faces significant challenges due to fluctuating raw material costs. Key inputs such as styrene, maleic anhydride, and glycol are derived from petrochemicals, which are highly sensitive to global crude oil price variations. It creates uncertainty in production planning and affects profit margins for manufacturers. Frequent price shifts hinder long-term contracts with buyers and force companies to adjust pricing strategies. Small and mid-sized producers face higher risks in sustaining competitive positions under volatile conditions. It compels manufacturers to explore alternative sourcing and develop bio-based substitutes to reduce dependency.
Environmental and Regulatory Constraints
Stringent environmental regulations present another obstacle to market growth. The Unsaturated Polyester Resin (UPR) Market encounters restrictions on styrene emissions due to their impact on air quality and worker safety. It requires companies to invest in advanced production technologies and comply with strict emission standards, raising operational costs. Regulatory variations across regions make global expansion complex for producers. Growing environmental awareness pressures manufacturers to reduce volatile organic compound (VOC) levels in UPR products. It limits flexibility in traditional formulations and drives demand for costly sustainable alternatives.
Market Opportunities
Expansion in Renewable Energy and Infrastructure Projects
The Unsaturated Polyester Resin (UPR) Market holds strong opportunities in renewable energy and infrastructure development. Demand for wind turbine blades, solar panel components, and hydropower equipment drives new applications for UPR-based composites. It offers durability, lightweight properties, and cost efficiency, making it suitable for large-scale clean energy projects. Governments worldwide invest heavily in renewable capacity, boosting requirements for advanced resin solutions. Infrastructure projects, including bridges, pipelines, and construction reinforcements, also create consistent demand. It strengthens UPR’s role as a strategic material in supporting sustainable development and modern infrastructure.
Growth in Automotive, Marine, and Consumer Applications
Expanding use of composites in automotive, marine, and consumer goods industries opens fresh prospects for UPR producers. The Unsaturated Polyester Resin (UPR) Market benefits from automakers seeking lightweight solutions to improve fuel efficiency and meet emission targets. It supports marine applications such as boat hulls and decks due to its water resistance and long service life. Consumer goods including bathroom fittings, furniture, and household equipment also rely on UPR for cost-effective production. Emerging economies with rising middle-class populations drive demand for affordable, durable, and versatile products. It positions UPR as a material of choice across both industrial and consumer markets.
Market Segmentation Analysis:
By Form
The Unsaturated Polyester Resin (UPR) Market segments by form into liquid and powder types, with liquid resins holding a dominant position. Liquid UPR offers excellent processing flexibility, making it suitable for applications such as coatings, laminates, and fiber-reinforced plastics. It provides uniform curing and adaptability across diverse industries, from construction to automotive. Powder forms, while less prevalent, gain attention in specialized applications requiring enhanced handling safety and reduced emissions. It offers advantages in terms of storage stability and controlled processing. Growing demand for lightweight composites across industries ensures strong adoption of liquid forms, while technological advancements expand the scope for powder-based UPR.
- For instance, Nantong Fangxin Chemical Co. operates a facility in China with a powder-form UPR production capacity of 180,000 metric tonnes per year, serving markets that prioritize safer, low-emission handling.
By Curing Type
Curing type segmentation includes heat-cured and room-temperature-cured UPR. The Unsaturated Polyester Resin (UPR) Market sees high demand for room-temperature curing, especially in construction and consumer products, due to its ease of application and reduced processing costs. It enables efficient fabrication in small- and medium-scale production environments. Heat-cured UPR dominates in industrial applications that demand higher strength, thermal resistance, and durability, such as automotive and marine sectors. Controlled heat curing enhances mechanical performance and extends product lifespan. It ensures that both curing types continue to play critical roles depending on application requirements and performance expectations.
- For instance, BASF operates global UPR production capacity exceeding 800,000 metric tonnes per annum, including a newly commissioned heat‑cured bio‑UPR line of 100,000 metric tonnes capacity dedicated to specialized composite applications.
By Degree of Unsaturation
The degree of unsaturation defines resin performance characteristics, with orthophthalic, isophthalic, and dicyclopentadiene (DCPD)-based resins forming key categories. The Unsaturated Polyester Resin (UPR) Market widely adopts orthophthalic resins due to their cost-effectiveness and versatility in producing pipes, tanks, and panels. It maintains strong demand in general-purpose applications where moderate strength and chemical resistance are sufficient. Isophthalic resins offer superior mechanical strength and corrosion resistance, making them preferred in marine, chemical, and infrastructure applications. DCPD-based UPR provides low viscosity and excellent electrical insulation, supporting applications in electronics and automotive components. It reflects how degree of unsaturation determines resin suitability across diverse industries, driving tailored product development for end users.
Segments:
Based on Form
- Liquid
- Solid
Based on Curing Type
- Room Temperature Curing
- Heat Curing
- UV Curing
Based on Degree of Unsaturation
- High
- Medium
- Low
Based on Application
- Fiberglass Reinforced Plastics
- Transportation
- Marine
- Building and Construction
- Tanks and Pipes
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Asia-Pacific
Asia-Pacific dominates the Unsaturated Polyester Resin (UPR) Market with 41% share, driven by rapid industrialization, infrastructure expansion, and strong growth in automotive and construction sectors. China leads the region with large-scale demand for UPR in building materials, marine products, and wind energy components. It also benefits from India’s fast-growing construction and renewable energy projects, where UPR is widely adopted for pipes, tanks, and composite panels. Japan and South Korea focus on high-performance UPR applications in automotive and electronics, reflecting the region’s advanced manufacturing capabilities. Rising urbanization and increasing demand for affordable housing boost consumption across emerging economies in Southeast Asia. It positions Asia-Pacific as the fastest-growing and most dynamic market for UPR globally.
Europe
Europe accounts for 25% of the Unsaturated Polyester Resin (UPR) Market, supported by strong regulations that emphasize sustainable materials and high-performance composites. Germany, France, and the UK lead adoption, with UPR widely used in construction, automotive, and wind turbine manufacturing. It gains traction in marine applications, where European manufacturers focus on lightweight and corrosion-resistant resins. Investments in offshore wind projects across the North Sea significantly increase demand for UPR-based composites. European firms also emphasize bio-based UPR to align with the EU’s environmental targets. It highlights Europe’s role as a hub for innovation and renewable-driven UPR applications.
North America
North America holds 20% of the Unsaturated Polyester Resin (UPR) Market, driven by demand from construction, automotive, and marine industries. The United States remains the largest consumer, leveraging UPR in infrastructure upgrades, pipelines, and automotive composites. It supports the wind energy sector, where UPR is critical for manufacturing large turbine blades. Canada and Mexico contribute steadily, with increasing adoption in housing and industrial projects. The region’s emphasis on lightweight automotive materials strengthens UPR consumption in OEM production. It reflects a market where innovation, renewable integration, and infrastructure development sustain long-term growth.
Latin America
Latin America represents 8% of the Unsaturated Polyester Resin (UPR) Market, with Brazil and Mexico leading demand. Construction and transportation sectors remain primary consumers, supported by growing urban populations. It finds applications in water storage tanks, pipelines, and building materials across the region. Marine and automotive industries also adopt UPR due to its cost efficiency and versatility. Government-backed infrastructure development and renewable energy projects create further opportunities. It underscores the region’s steady growth despite economic challenges in some markets.
Middle East & Africa
The Middle East & Africa account for 6% of the Unsaturated Polyester Resin (UPR) Market, supported by infrastructure expansion and industrial growth. The UAE and Saudi Arabia lead in construction demand, with UPR used in panels, claddings, and piping systems. It gains relevance in marine and oil & gas applications, where corrosion resistance is critical. South Africa shows rising adoption in housing and industrial products, expanding overall regional demand. Renewable energy projects, particularly solar and wind, add momentum to UPR usage. It reflects a growing market with significant potential for long-term expansion.
Key Player Analysis
Competitive Analysis
The competitive landscape of the Unsaturated Polyester Resin (UPR) Market is shaped by global leaders such as Ashland, Arkema, Evonik, Huntsman, Sartomer, BASF, SigmaAldrich, Polynt, AOC, and Reichhold, all of which actively drive innovation and market expansion. Ashland and Arkema focus on developing advanced resin formulations with improved mechanical performance and lower emissions, aligning with sustainability targets. BASF and Evonik strengthen their positions through diversified product portfolios and strong R&D capabilities, catering to construction, automotive, and marine applications. Huntsman and Sartomer emphasize specialty UPR solutions tailored for high-performance composites, while Polynt and AOC expand their global presence through acquisitions and capacity enhancements to meet rising infrastructure and industrial demand. Reichhold maintains a strong role in supplying resins for marine and wind energy applications, supported by its legacy in composite materials. SigmaAldrich contributes with research-grade resins and specialty chemicals, supporting innovation across multiple industries. Intense competition encourages these players to invest in bio-based alternatives, enhance supply chain networks, and collaborate with end-use industries to meet the growing need for lightweight, durable, and cost-efficient UPR solutions worldwide.
Recent Developments
- In July 2025, Polynt partnered with LyondellBasell to develop marine-grade UPR utilizing LYB’s Styrene +LC (low‑carbon) solution. This approach uses the ISCC PLUS mass-balance method and incorporates bio-based feedstocks.
- In January 2025, AOC, together with Polynt and other members of the Cefic UP/VE Sector Group, contributed to a newly published Life Cycle Assessment (LCA) dataset for UPR and vinyl ester resins. The dataset enhances transparency around global warming impact and eco-footprint using recycled PET (rPET) inputs.
- In February 2024, Evonik launched a novel photopolymer resin with both flame-retardant properties and mechanical durability when cured, designed to meet high-performance application requirements. This resin delivers enhanced safety and robustness for components subjected to demanding operational conditions.
Market Concentration & Characteristics
The Unsaturated Polyester Resin (UPR) Market demonstrates a moderately consolidated structure, with a mix of multinational corporations and regional players competing on product quality, cost efficiency, and technological advancement. Large companies such as Ashland, Arkema, BASF, Huntsman, and Polynt dominate with broad product portfolios, advanced R&D, and global distribution networks, while regional producers like AOC and Reichhold strengthen competition by focusing on niche applications and cost-effective solutions. It is defined by high entry barriers due to capital-intensive production, dependence on petrochemical-derived raw materials, and strict environmental regulations around styrene emissions. Strong demand from construction, automotive, marine, and renewable energy sectors keeps competition intense, with companies investing in sustainable and bio-based UPR formulations to address tightening regulations and shifting customer preferences. It reflects a market where innovation, supply chain resilience, and regulatory compliance remain key competitive differentiators that shape long-term growth and global positioning.
Report Coverage
The research report offers an in-depth analysis based on Type, Curing Type, Degree of Unsaturation, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Unsaturated Polyester Resin (UPR) Market will expand steadily with growing demand across construction, automotive, marine, and renewable sectors.
- Infrastructure development in emerging economies will continue to drive large-scale adoption of UPR composites.
- Renewable energy projects, especially wind and solar, will create strong opportunities for UPR applications in turbine blades and panel components.
- Automotive manufacturers will increase use of UPR to achieve lightweight, fuel-efficient, and durable vehicle parts.
- Advances in bio-based and low-styrene emission formulations will support regulatory compliance and sustainability goals.
- Marine industries will adopt UPR for corrosion-resistant hulls, decks, and structural parts in both small and large vessels.
- Digital design integration and automated molding technologies will improve efficiency and expand industrial-scale use of UPR.
- Regional demand will grow strongest in Asia-Pacific, while Europe and North America focus on high-performance and eco-friendly resin solutions.
- Strategic partnerships and acquisitions will shape competition among leading players aiming to secure market leadership.
- Continuous innovation in resin formulations will enhance durability, thermal resistance, and adaptability for diversified applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Infrastructure and Construction Boom
Rapid urbanization and large-scale infrastructure projects, especially in emerging economies, are driving demand for UPR in pipes, tanks, panels, and reinforced composites due to its durability and cost-effectiveness.
Automotive Lightweighting and Efficiency
The automotive sector increasingly adopts UPR for lightweight, fuel-efficient vehicle components, including body panels and battery enclosures, supporting both conventional and electric vehicle manufacturing.
Growth in Renewable Energy and Marine Sectors
Expanding investments in wind energy and marine industries require strong, lightweight, and corrosion-resistant materials, positioning UPR as a preferred choice for wind turbine blades and marine structures.
Shift Toward Sustainable and Bio-Based Resins
Regulatory pressures and consumer demand for eco-friendly products are accelerating the development and adoption of bio-based and low-styrene emission UPR formulations, opening new market opportunities.
Versatility and Cost-Effectiveness Across Industries
UPR's adaptability for diverse applications, from electrical components to consumer goods, and its lower production costs compared to alternatives, make it a competitive material in multiple end-use sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Unsaturated Polyester Resin (UPR), and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Unsaturated Polyester Resin (UPR) market projected to grow between 2025 and 2032?
Which Unsaturated Polyester Resin (UPR) market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Unsaturated Polyester Resin (UPR) market?
Who are the leading companies in the Unsaturated Polyester Resin (UPR) market?
Which region commanded the largest share of the Unsaturated Polyester Resin (UPR) market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Liquid
- 1.2.2 Solid
- 1.3 By Application
- 1.3.1 Fiberglass Reinforced Plastics
- 1.3.2 Transportation
- 1.3.3 Marine
- 1.3.4 Building and Construction
- 1.3.5 Tanks and Pipes
- 1.4 By Curing Type
- 1.4.1 Room Temperature Curing
- 1.4.2 Heat Curing
- 1.4.3 UV Curing
- 1.5 By Degree of Unsaturation
- 1.5.1 High
- 1.5.2 Medium
- 1.5.3 Low
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,078 million → 2032: USD 18,118.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Unsaturated Polyester Resins Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Unsaturated Polyester Resins Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Unsaturated Polyester Resins Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Unsaturated Polyester Resins Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Unsaturated Polyester Resins Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Unsaturated Polyester Resins Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Unsaturated Polyester Resins Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Unsaturated Polyester Resins Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,078 million → 2032: USD 18,118.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Unsaturated Polyester Resins Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Liquid
- 12.3.7.2 Solid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fiberglass Reinforced Plastics
- 12.4.7.2 Transportation
- 12.4.7.3 Marine
- 12.4.7.4 Building and Construction
- 12.4.7.5 Tanks and Pipes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Curing Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Room Temperature Curing
- 12.5.7.2 Heat Curing
- 12.5.7.3 UV Curing
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Degree of Unsaturation - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 High
- 12.6.7.2 Medium
- 12.6.7.3 Low
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Unsaturated Polyester Resins End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Unsaturated Polyester Resins Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Unsaturated Polyester Resins Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Unsaturated Polyester Resins Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ashland
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Arkema
- 18.4 BASF
- 18.5 Evonik
- 18.6 Huntsman
- 18.7 Polynt
- 18.8 AOC
- 18.9 Reichhold
- 18.10 Sartomer
- 18.11 SigmaAldrich
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

