
Utility Scale PV Inverter Market Overview:
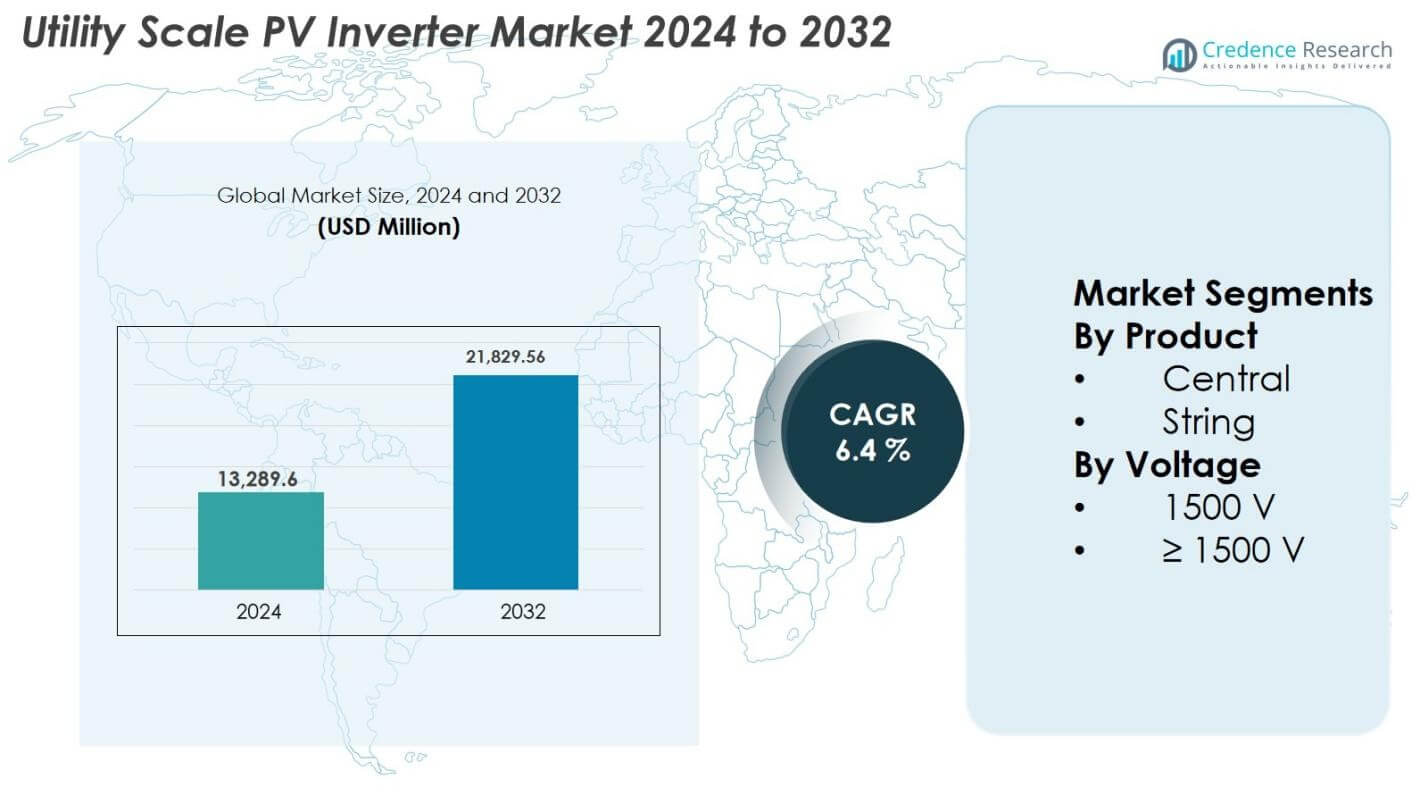
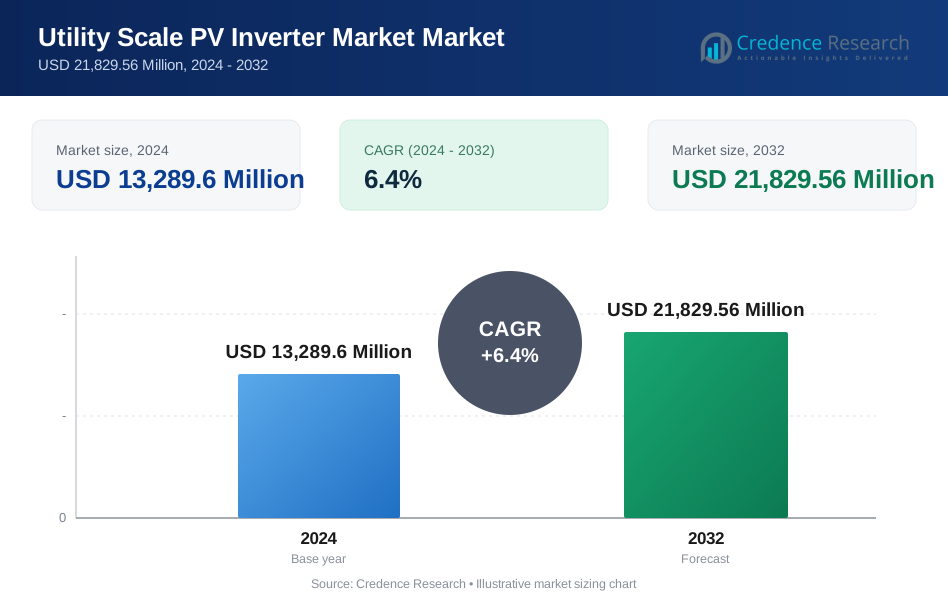
Utility Scale PV Inverter market size was valued at USD 13,289.6 Million in 2024 and is anticipated to reach USD 21,829.56 Million by 2032, at a CAGR of 6.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Utility Scale PV Inverter Market Size 2024 | USD 13,289.6 million |
| Utility Scale PV Inverter Market, CAGR | 6.4% |
| Utility Scale PV Inverter Market Size 2032 | USD 21,829.56 million |
Utility Scale PV Inverter Market Insights
- Large-scale solar capacity expansion, grid modernization initiatives, and rising demand for high-efficiency, grid-compliant inverters drive market growth, with utilities prioritizing reliable power conversion and reduced levelized cost of electricity.
- The market shows a strong shift toward 1500 V systems, which dominate with about 71.4% share due to lower balance-of-system costs, while central inverters lead the product segment with nearly 58.6% share supported by suitability for large solar parks.
- Leading players focus on high-capacity inverter portfolios, digital monitoring, and advanced grid-support features, intensifying competition through technology differentiation and regional service expansion.
- Asia-Pacific leads with 38.9% market share driven by China and India, followed by North America at 24.8% and Europe at 22.6%, reflecting strong regional policy support and utility-scale solar deployment.
Utility Scale PV Inverter Market Segmentation Analysis
By Product
The Utility Scale PV Inverter market by product is dominated by central inverters, which accounted for approximately 58.6% market share in 2024. Central inverters remain the preferred choice for large-scale solar farms due to their high power capacity, lower cost per watt, simplified maintenance, and proven performance in utility-scale deployments. Their ability to efficiently handle multi-megawatt installations and integrate seamlessly with grid infrastructure supports widespread adoption. String inverters continue to gain traction in selective projects for design flexibility and redundancy, but central inverters maintain leadership driven by economies of scale and long-term operational efficiency.
- For instance, utility-oriented units such as the Sungrow SG2500U central inverter are rated for around 2.75 MW output and are designed to meet stringent grid standards across regions like North America, with features that enhance uptime and maintenance access.
By Voltage
The 1500 V segment leads the Utility Scale PV Inverter market, holding around 71.4% market share in 2024. This dominance is driven by the voltage’s ability to significantly reduce balance-of-system costs through lower cable losses, fewer components, and improved system efficiency. Utility developers favor 1500 V architectures for large solar parks as they enable higher power density and reduced installation time. Strong regulatory acceptance, mature supply chains, and compatibility with modern high-capacity PV modules further reinforce the segment’s leadership across global utility-scale solar installations.
- For instance, Huawei’s SUN2000-series 1500 V string inverters for utility applications support high-current PV modules and advanced grid-support functions, demonstrating how mature 1500 V ecosystems align with modern module designs and utility interconnection requirements.
Key Growth Drivers
Expansion of Utility-Scale Solar Installations
Rapid expansion of utility-scale solar power projects remains a primary growth driver for the Utility Scale PV Inverter market. Governments and utilities worldwide are accelerating large solar park developments to meet renewable energy targets and reduce dependence on fossil fuels. These projects require high-capacity, grid-compliant inverters capable of managing large power outputs with high efficiency and reliability. Falling solar module prices, improved project economics, and supportive policy frameworks further stimulate demand. As solar capacity additions increase across Asia-Pacific, the Middle East, and the Americas, inverter demand rises proportionally, strengthening sustained market growth.
- For instance, the Agua Caliente Solar Project in Arizona deployed around 500 SMA 630CP inverters to integrate its ~290 MW_AC of PV capacity into the grid, illustrating how large installations depend on robust inverter fleets for stable grid supply
Grid Modernization and Renewable Integration Requirements
The growing need to modernize power grids to accommodate high renewable penetration strongly drives the Utility Scale PV Inverter market. Utilities increasingly require advanced inverters that support grid stability through voltage regulation, frequency control, and reactive power management. Utility-scale PV inverters play a critical role in ensuring smooth integration of intermittent solar generation into existing transmission networks. Enhanced grid codes and stricter compliance standards push demand for technologically advanced inverter solutions, encouraging utilities to upgrade legacy systems and adopt next-generation inverters with advanced monitoring and control capabilities.
- For instance, GE Vernova introduced a grid-forming utility-scale inverter platform capable of providing synthetic inertia and fast frequency response, enabling solar plants to actively support weak and renewable-heavy grids.
Cost Reduction and Efficiency Improvements in Inverter Technology
Continuous technological advancements leading to higher efficiency and lower levelized cost of electricity significantly drive the Utility Scale PV Inverter market. Improvements in power electronics, cooling systems, and digital control architectures enable higher power density and reduced energy losses. Manufacturers focus on optimizing inverter design to deliver longer operational lifespans and lower maintenance costs. These efficiency gains directly improve project returns for utility-scale developers, making solar installations more economically attractive and accelerating inverter adoption across large-scale renewable energy projects.
Key Trends & Opportunities
Shift Toward High-Voltage and High-Power Inverter Architectures
A major trend shaping the Utility Scale PV Inverter market is the increasing adoption of high-voltage, high-power inverter architectures, particularly 1500 V and above systems. These configurations enable lower balance-of-system costs by reducing cabling, transformers, and installation complexity while improving overall system efficiency. Developers favor high-power inverters to support large block sizes and reduce the number of inverter units required per project. This trend creates strong opportunities for manufacturers offering scalable, high-capacity solutions with enhanced thermal management, grid-forming capabilities, and compatibility with advanced PV modules.
- For instance, SMA’s high-power central inverters operating on 1500 V systems are deployed in large solar parks to support higher string power and improved grid compliance, aligning with utility demand for fewer, higher-capacity inverter units.
Integration of Digital Monitoring and Smart Grid Capabilities
The growing integration of digital technologies presents significant opportunities in the Utility Scale PV Inverter market. Advanced inverters increasingly incorporate real-time monitoring, predictive maintenance, and remote diagnostics to improve system availability and reduce downtime. Compatibility with smart grid platforms and energy management systems enables utilities to optimize power flow and enhance grid resilience. The shift toward data-driven asset management allows operators to maximize performance and extend inverter lifespan, creating opportunities for suppliers offering software-enabled, digitally connected inverter solutions with advanced analytics and cybersecurity features.
- For instance, Delta Electronics equips its high-power utility-scale PV inverters with cloud-connected monitoring platforms that support remote commissioning, continuous health assessment, and grid-support functions aligned with utility SCADA requirements.
Key Challenges
Grid Code Complexity and Regional Compliance Variations
Increasing complexity of grid codes across different regions poses a key challenge for the Utility Scale PV Inverter market. Utilities and regulators impose diverse technical requirements related to voltage support, fault ride-through, and frequency response. Manufacturers must customize inverter designs to meet country-specific standards, increasing development costs and time to market. Frequent regulatory updates further complicate compliance, particularly for global suppliers operating across multiple regions. This variability places pressure on manufacturers to maintain flexible product platforms while ensuring reliable and certified performance.
Supply Chain Constraints and Raw Material Volatility
Supply chain disruptions and volatility in raw material prices present ongoing challenges for the Utility Scale PV Inverter market. Key components such as power semiconductors, electronic modules, and metals are vulnerable to geopolitical tensions and demand fluctuations. These uncertainties can lead to extended lead times, increased production costs, and pricing pressures for manufacturers. Managing supply risks while maintaining competitive pricing remains critical, particularly as large utility-scale projects operate on tight timelines and fixed-cost contracts.
Regional Analysis
North America
North America accounted for 24.8% market share in 2024 in the Utility Scale PV Inverter market, supported by strong utility-scale solar capacity additions across the United States and Canada. Federal and state-level renewable energy mandates, tax incentives, and long-term power purchase agreements continue to drive large solar farm deployments. Grid modernization initiatives and growing demand for advanced inverters with grid-support functionalities further strengthen market growth. The region also benefits from early adoption of high-voltage inverter architectures and digital monitoring solutions, enabling utilities to enhance grid reliability and operational efficiency.
Europe
Europe held 22.6% market share in 2024, driven by aggressive decarbonization targets and large-scale renewable integration across countries such as Germany, Spain, France, and Italy. Utility-scale solar projects are expanding rapidly as governments focus on energy security and reduced fossil fuel dependence. Strict grid codes and emphasis on grid stability fuel demand for technologically advanced PV inverters. High adoption of 1500 V systems, coupled with investments in smart grid infrastructure and cross-border power transmission, supports steady inverter demand across mature and emerging European solar markets.
Asia-Pacific
Asia-Pacific dominated the Utility Scale PV Inverter market with an 38.9% market share in 2024. Strong solar capacity installations in China, India, Japan, Australia, and Southeast Asia drive large-scale inverter demand. Government-backed renewable energy programs, declining project costs, and expanding transmission infrastructure support sustained growth. China leads regional manufacturing and deployment, while India continues to accelerate solar park development. The region shows high adoption of high-capacity central inverters and advanced grid-compliant technologies, positioning Asia-Pacific as the primary growth engine of the global market.
Latin America
Latin America captured 8.1% market share in 2024, supported by increasing utility-scale solar investments in Brazil, Chile, Mexico, and Argentina. Favorable solar irradiation, competitive auction frameworks, and rising electricity demand drive solar project development. Utilities increasingly deploy modern PV inverters to improve grid integration and system efficiency. Although the market remains smaller compared to developed regions, improving regulatory clarity and growing foreign investment continue to strengthen inverter adoption across large solar installations in the region.
Middle East & Africa
The Middle East & Africa region accounted for about 5.6% market share in 2024, driven by large solar mega-projects in the Middle East and gradual expansion across parts of Africa. Countries such as Saudi Arabia, the UAE, and Egypt invest heavily in utility-scale solar to diversify energy sources and reduce carbon emissions. High solar irradiance levels and government-backed renewable strategies support demand for robust, high-capacity PV inverters. In Africa, grid expansion and international funding initiatives are gradually improving market penetration.
Utility Scale PV Inverter Market Segmentations
By Product
- Central
- String
By Voltage
- 1500 V
- ≥ 1500 V
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Utility Scale PV Inverter market features a moderately consolidated competitive landscape characterized by the presence of global technology providers and specialized power electronics manufacturers. Leading players such as Huawei Technologies, Sungrow Power Supply, GE Vernova, Delta Electronics, Canadian Solar, Eaton, Fimer Group, GoodWe, Sofar Solar, and Solis Inverters compete primarily on efficiency, reliability, grid compliance, and lifecycle cost. Companies focus on expanding high-capacity inverter portfolios, particularly 1500 V central and string solutions, to address large utility-scale solar projects. Continuous investment in R&D enables advanced grid-support features, digital monitoring, and improved thermal management. Strategic partnerships with EPC contractors, utilities, and project developers strengthen market positioning, while regional manufacturing expansion and localized service networks enhance competitiveness in high-growth solar markets worldwide.
Key Player Analysis
- Sungrow Power Supply
- Eaton
- Sofar Solar
- GE Vernova
- GoodWe
- Canadian Solar
- Solis Inverters
- Huawei Technologies
- Fimer Group
- Delta Electronics
Recent Developments
- In October 2024, SolarEdge Technologies unveiled its high-power SolarEdge TerraMax Inverter paired with H1300 Power Optimizers in the UK. The SE330K inverter is available for pre-orders, with shipments expected to commence in Q1 2025.
- In September 2024, GE Vernova launched a 6 MVA, 2000-volt DC utility-scale inverter aimed at lowering costs and improving renewable energy integration. The company also deployed a multi-megawatt pilot project in North America, reinforcing its focus on accelerating decarbonization and the clean energy transition.
- In June 2024, SolarEdge Technologies introduced the SolarEdge TerraMax Inverter with H1300 Power Optimizers in Germany. The certified SE300K1 inverter is now open for orders, supporting advanced energy conversion and optimization requirements across the region.
Report Coverage
The research report offers an in-depth analysis based on Product, Voltage and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Utility-scale solar capacity additions will continue to expand, sustaining long-term demand for high-capacity PV inverters.
- Adoption of 1500 V and higher-voltage inverter systems will increase to improve efficiency and reduce balance-of-system costs.
- Central inverters will retain dominance in large solar parks, while advanced string inverters will gain selective adoption for flexible designs.
- Grid-forming and grid-support inverter functionalities will become standard to support higher renewable penetration.
- Digital monitoring, predictive maintenance, and remote diagnostics will be increasingly integrated into inverter platforms.
- Manufacturers will focus on improving inverter reliability, thermal management, and operational lifespan.
- Regional manufacturing and localized service networks will expand to support large-scale project deployments.
- Stricter grid codes and regulatory requirements will drive continuous inverter technology upgrades.
- Energy storage integration with utility-scale PV inverters will accelerate to enhance grid stability.
- Emerging markets will play a growing role in driving future utility-scale solar and inverter demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Utility Scale PV Inverter market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Utility Scale PV Inverter market projected to grow between 2024 and 2032?
Which Utility Scale PV Inverter market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Utility Scale PV Inverter market?
Who are the leading companies in the Utility Scale PV Inverter market?
Which region commanded the largest share of the Utility Scale PV Inverter market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Utility Scale PV Inverter Market Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Utility Scale PV Inverter Market Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 13,289.6 Million → 2032: USD 21,829.56 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Utility Scale PV Inverter Market Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Utility Scale PV Inverter Market Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Utility Scale PV Inverter Market Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Utility Scale PV Inverter Market Market Drivers
- 3.3 Utility Scale PV Inverter Market Market Restraints & Challenges
- 3.4 Utility Scale PV Inverter Market Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Utility Scale PV Inverter Market Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Utility Scale PV Inverter Market Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Utility Scale PV Inverter Market category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Utility Scale PV Inverter Market Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Utility Scale PV Inverter Market Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Utility Scale PV Inverter Market market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Utility Scale PV Inverter Market Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Utility Scale PV Inverter Market Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Utility Scale PV Inverter Market Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Utility Scale PV Inverter Market (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Utility Scale PV Inverter Market Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Utility Scale PV Inverter Market Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Utility Scale PV Inverter Market Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Utility Scale PV Inverter Market Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Utility Scale PV Inverter Market Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Utility Scale PV Inverter Market Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Utility Scale PV Inverter Market Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Utility Scale PV Inverter Market Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Utility Scale PV Inverter Market Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
