
Market Overview:
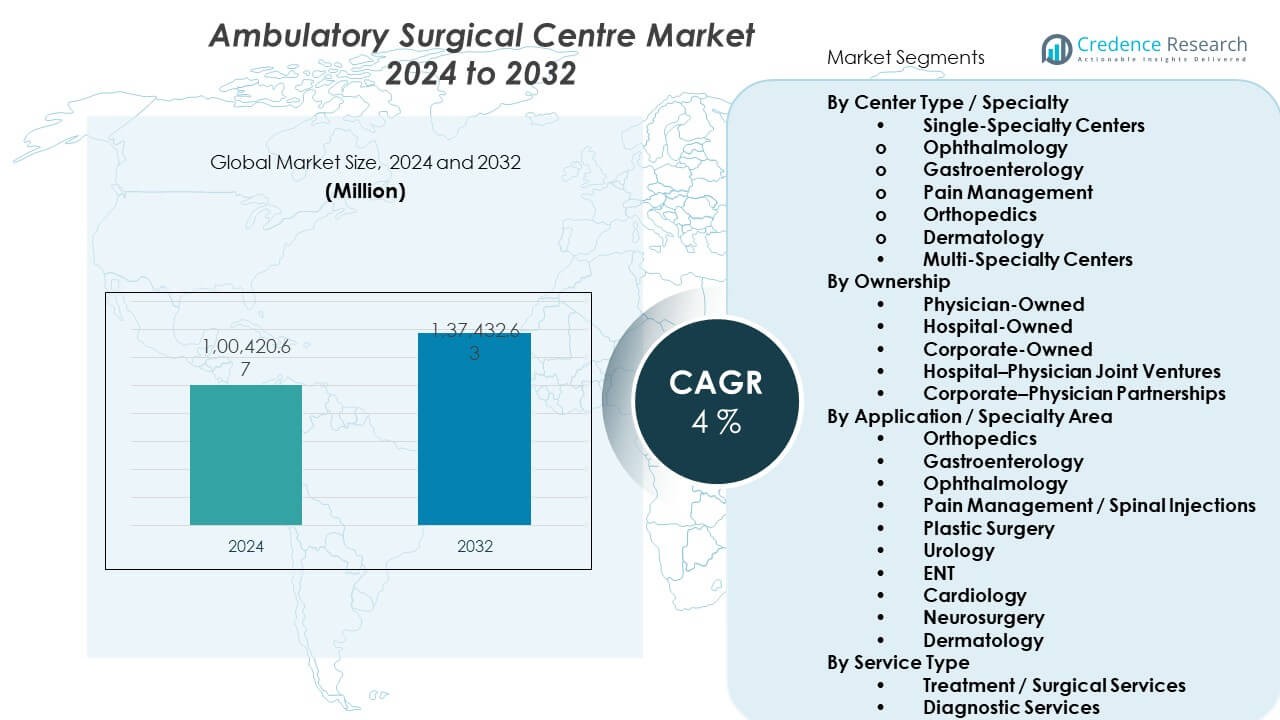
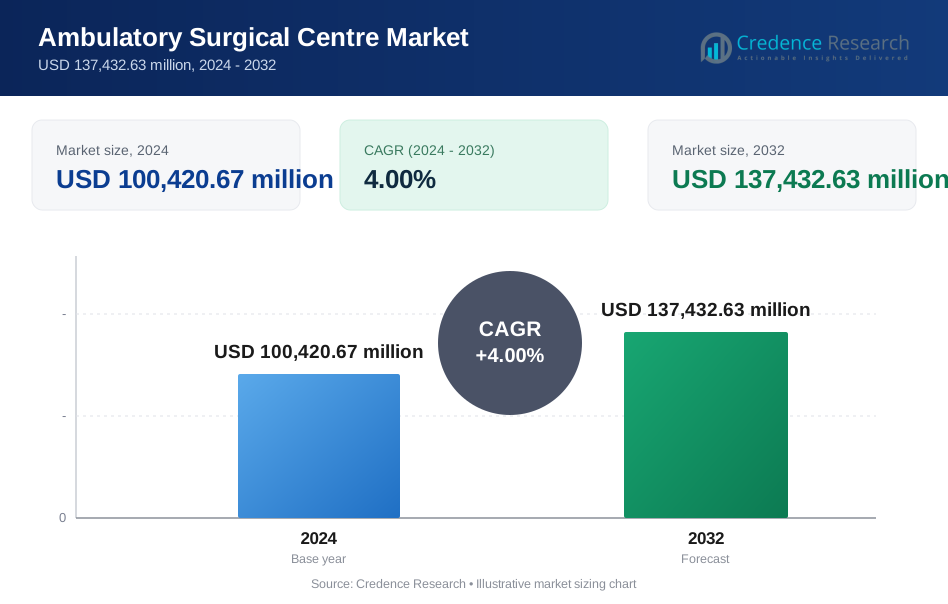
The Ambulatory Surgical Centre market is projected to grow from USD 100,420.67 million in 2024 to an estimated USD 137,432.63 million by 2032, with a CAGR of 4% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ambulatory Surgical Centre Market Size 2024 | USD 100,420.67 Million |
| Ambulatory Surgical Centre Market, CAGR | 4% |
| Ambulatory Surgical Centre Market Size 2032 | USD 137,432.63 Million |
The market gains strength from rising patient preference for shorter stays and quicker recovery. Surgeons adopt advanced tools that support minimally invasive methods across multiple specialties. Payers promote outpatient surgery due to lower overall spending and fewer complications. Hospitals shift procedures to outpatient hubs to manage capacity and improve workflow. Ageing populations raise the need for orthopedic and ophthalmic care. Chronic disease growth pushes higher volumes of outpatient interventions. Wider insurance coverage supports steady adoption across urban and semi-urban zones.
North America leads due to its mature outpatient ecosystem and strong payer support for same-day surgical care. Europe follows with broad acceptance of minimally invasive procedures and strong investment in ambulatory infrastructure. Asia Pacific shows fast progress due to expanding private healthcare and rising patient awareness. China and India drive growth with rapid urban expansion and higher surgical capacity. Latin America builds momentum with improved insurance penetration and new regional outpatient models. Middle East and Africa advance through private-sector investment and modern facility development. The ambulatory surgical centre market grows across both established and emerging regions due to better access and rising demand for faster care.
Market Insights:
- The Ambulatory surgical centre market is valued at USD 100,420.67 million in 2024 and is projected to reach USD 137,432.63 million by 2032, advancing at a 4% CAGR.
- North America leads with 42–45% share due to its mature outpatient ecosystem, followed by Europe at 26–28% with strong clinical pathways, and Asia Pacific at 20–22% supported by expanding surgical demand.
- Asia Pacific remains the fastest-growing region with 20–22% share, driven by private healthcare expansion and wider adoption of minimally invasive procedures.
- Single-specialty centres dominate structure distribution with 61.22% share, supported by strong focus in ophthalmology, gastroenterology, and pain management.
- Orthopedics leads application demand with 26.97% share, strengthened by rising volumes of joint, spine, and sports injury procedures.
Market Drivers:
Rising Demand for Same-Day Surgical Care and Shift Toward Outpatient Efficiency
Growth rises due to wider acceptance of same-day procedures across key specialties. Patients choose outpatient centres to avoid long inpatient stays and reduce recovery burdens. Surgeons prefer advanced tools that support faster interventions while keeping strong care quality. Payers promote outpatient settings to lower costs and reduce unnecessary hospital use. Regulatory bodies support clinical pathways that favour shorter stays and minimal complications. Hospitals transfer selected surgeries to outpatient hubs to manage capacity issues. Ageing populations push higher demand for eye, joint, and pain-related care. The Ambulatory surgical centre market gains momentum due to strong preference for timely and accessible procedures.
- For instance, an independent study on the implementation of the Alcidion Miya Precision platform at Alfred Health identified a wide range of benefits attributed to the adoption of electronic patient journey boards to facilitate inpatient clinical workflows. Other research has shown that various interventions can reduce operating room delays, such as standardizing preoperative communication and paperwork or utilizing quality improvement methodologies.
Expansion of Minimally Invasive Procedures Across Multiple Specialties
Growth strengthens due to rising adoption of minimally invasive tools that reduce surgical strain. Patients choose these procedures due to lower pain, shorter downtime, and better comfort. Surgeons expand service scopes through advanced imaging and precision support systems. Payers recognise stable outcomes and support outpatient reimbursement models. Providers integrate modern equipment to increase surgical throughput in busy centres. Chronic disease growth drives more cardiology, urology, and gastroenterology procedures. Hospitals shift lower-risk interventions to outpatient campuses to free operating rooms. The market benefits from a strong rise in precision-driven procedures across urban regions.
- For instance, Olympus publicly reported that its EVIS X1 endoscopy system achieved higher adenoma detection performance in clinical trials, supported by AI-enabled imaging enhancements.
Increasing Payer Support for Cost-Effective Outpatient Surgical Models
Insurers expand coverage for outpatient care due to clear financial benefits and better patient outcomes. Payers approve more same-day procedures due to predictable cost structures and fewer complications. Providers align care pathways with payer-driven efficiency mandates. Patients choose centres with transparent pricing and minimal administrative hurdles. Hospitals face cost pressure and shift suitable procedures to outpatient settings. Policy reforms favour outpatient models to manage national healthcare budgets. Clinicians adopt evidence-backed protocols that support short recovery cycles. The Ambulatory surgical centre market gains support due to payer-driven cost optimisation.
Growing Preference for Faster Recovery and Patient-Centric Surgical Experiences
Patients choose outpatient facilities due to quicker discharge and minimal disruption to daily life. Surgeons adopt technology that supports safe recovery without extended hospital monitoring. Providers improve patient flow through digital scheduling and streamlined triage systems. Payers promote patient-centric models that lower overall treatment burden. Hospitals build dedicated outpatient units to improve their competitive edge. Chronic diseases drive higher volumes of repeat or follow-up procedures. Clinical bodies standardise outpatient guidelines to ensure safe care delivery. The market advances due to a strong shift toward comfort, speed, and accessible surgical care.
Market Trends:
Adoption of Advanced Surgical Technologies and Smart Workflow Systems
Modern centres adopt robotics, AI-supported imaging, and precision-guided tools to improve outcomes. Providers upgrade operating rooms to support better workflow and reduce delays. Patients choose centres with modern systems due to better comfort and shorter wait times. Surgeons rely on real-time data tools to improve accuracy during short procedures. Providers digitise patient journeys to reduce administrative load. Hospitals integrate remote monitoring options for post-procedure stability. Payers support technology-driven consistency across outpatient pathways. The Ambulatory surgical centre market gains visibility due to rapid tech integration.
- For instance, Intuitive Surgical disclosed in its 2023 annual report that over 2.2 million surgical procedures were performed with the da Vinci system worldwide. This represents a 22% growth compared to 2022. The total number of procedures using the da Vinci system since its inception surpassed 14 million by the end of 2023.
Rising Expansion of Specialty-Focused Ambulatory Centres Worldwide
Providers build centres dedicated to eye care, orthopedics, oncology, or pain management. Patients choose these units due to specialised teams and predictable recovery paths. Surgeons benefit from dedicated tools designed for specific surgical fields. Payers support these facilities due to controlled cost patterns. Hospitals refer high-volume cases to specialty centres to manage pressure. Private players invest in franchise-style outpatient networks. Clinical guidelines support standardised pathways for niche surgeries. The market grows due to increased interest in single-specialty capacity building.
Increasing Use of Value-Based Surgical Models in Outpatient Settings
Payers encourage outcomes-based contracts to ensure strong patient recovery. Providers design care bundles that reduce waste and improve clinical predictability. Surgeons align their methods with measurable clinical indicators. Patients gain access to stable outcomes due to structured recovery plans. Hospitals redesign pathways to meet value-focused benchmarks. Centres adopt digital tools that measure outcomes in real time. Policy frameworks expand to include incentive-based surgical care. The Ambulatory surgical centre market sees wider acceptance of value-based models.
Growth of Retail-Backed and Corporate Healthcare Networks in Outpatient Surgery
Large healthcare chains invest in outpatient networks to reach urban and semi-urban zones. Patients trust these brands due to strong quality assurance and service consistency. Surgeons choose these centres due to better equipment and support staff. Investors fund new centres in high-volume cities. Providers design patient-friendly environments to improve surgical journeys. Digital portals support easier scheduling and pre-operative guidance. Hospitals collaborate with retail-backed centres for select procedures. The market expands due to rising interest in network-driven outpatient care.
Market Challenges Analysis:
Rising Compliance Pressure, Workforce Shortages, and High Regulatory Oversight
Providers face strict compliance rules that raise operational burden across centres. Regulators demand consistent safety standards that require ongoing staff training. Many regions face shortages of skilled surgical nurses and technicians. Competition for specialists raises hiring difficulties and wage pressure. Patients expect consistent outcomes, pushing the need for continuous quality upgrades. Smaller centres struggle with technology adoption due to cost constraints. Hospitals retain complex cases, limiting service mix opportunities. The Ambulatory surgical centre market experiences pressure due to regulatory and staffing hurdles.
Intense Competitive Landscape and Limited Access to Advanced Capital Investment
Private chains expand aggressively, creating intense pricing and service pressure. Independent centres face cost challenges when upgrading digital tools. Providers struggle to access capital for robotics or smart workflow systems. Patients choose larger centres with broader capability sets. Payers negotiate strict contracts, limiting revenue margins. Technology adoption becomes uneven across regions. Hospitals protect their procedure volumes through strategic referrals. The market manages rising competition while facing barriers to modernisation.
Market Opportunities:
Growing Scope for Technology Integration and High-Volume Specialty Services
Centres gain opportunities through precision tools, AI-backed imaging, and smart workflow systems. Providers can expand specialty units that target orthopedics, ophthalmology, or oncology. Patients seek modern care settings that support faster recovery. Surgeons benefit from purpose-built outpatient suites for short procedures. Investors support expansions in high-demand zones. Hospitals partner with centres to expand outpatient coverage. The Ambulatory surgical centre market can leverage wider digital transformation for growth.
Strong Expansion Potential Across Emerging Regions and Private Healthcare Networks
Urbanisation drives demand for efficient surgical pathways across developing economies. Private groups expand franchise-style outpatient models in major cities. Patients choose reliable and cost-effective options for routine surgeries. Payers support outpatient care due to predictable outcomes. Hospitals collaborate with private centres to handle excess volume. Investors fund facilities with scalable models and tech readiness. The market grows through strong emerging-region penetration and network expansion.
Market Segmentation Analysis:
Center Type / Specialty
The Ambulatory surgical centre market expands through strong adoption of single-specialty and multi-specialty formats. Single-specialty centres grow due to clear clinical focus and predictable patient flow across ophthalmology, gastroenterology, pain management, orthopedics, and dermatology. These centres benefit from streamlined workflows that support high-volume procedures. Multi-specialty centres gain traction through broader service portfolios and higher utilisation rates. Providers choose these centres to manage diverse procedures in one setting. Investors support both formats due to stable demand in urban and semi-urban regions. Payers recognise efficient delivery models that support consistent outcomes. The segment structure strengthens market competitiveness across different clinical fields.
- For instance, United Surgical Partners International (USPI), a subsidiary of Tenet Healthcare Corporation, has interests in over 500 surgery centers and 25 surgical hospitals across 37 states. The company had ownership interests in 518 ambulatory surgery centers and 25 surgical hospitals as of December 31, 2024.
Ownership
Ownership patterns shape strategic growth across physician-owned, hospital-owned, and corporate-owned centres. Physician-owned facilities lead due to strong clinical autonomy and efficient decision cycles. Hospital-owned units expand through integration with existing surgical networks. Corporate ownership grows due to scalable models and strong capital backing. Joint ventures between hospitals and physicians support shared control and risk balancing. Corporate–physician partnerships create hybrid models that improve operational reach. Investors favour ownership frameworks that support faster expansion and stable reimbursement pathways.
- For instance, HCA Healthcare reports operating more than 150 outpatient surgery centres across its network, many structured as joint ventures with physicians to strengthen service capability and governance.
Application and Service Type
Application segments such as orthopedics, gastroenterology, ophthalmology, pain management, and ENT lead due to high outpatient suitability. Cardiology and neurosurgery gain momentum through improved minimally invasive tools. Plastic surgery, urology, and dermatology maintain steady uptake. Treatment and surgical services dominate due to high case volume and stronger reimbursement support. Diagnostic services grow steadily through improved pre-procedural evaluation and follow-up pathways.
Model Type
Hospital-based ASCs expand through integrated care pathways and strong referral networks. Freestanding centers grow due to flexible operations and wider patient access. Both models support diversified service delivery across regional markets.
Segmentation:
By Center Type / Specialty
- Single-Specialty Centers
- Ophthalmology
- Gastroenterology
- Pain Management
- Orthopedics
- Dermatology
- Multi-Specialty Centers
By Ownership
- Physician-Owned
- Hospital-Owned
- Corporate-Owned
- Hospital–Physician Joint Ventures
- Corporate–Physician Partnerships
By Application / Specialty Area
- Orthopedics
- Gastroenterology
- Ophthalmology
- Pain Management / Spinal Injections
- Plastic Surgery
- Urology
- ENT
- Cardiology
- Neurosurgery
- Dermatology
By Service Type
- Treatment / Surgical Services
- Diagnostic Services
By Model
- Hospital-Based ASCs
- Freestanding ASCs
Regional Analysis:
North America
North America leads the ambulatory surgical center market with an estimated 42–45% share due to its mature outpatient ecosystem and strong insurance coverage. Growth rises through wide adoption of minimally invasive procedures across orthopedic, ophthalmology, and gastroenterology segments. Hospitals expand outpatient programs to manage inpatient pressure and improve surgical efficiency. Corporate operators scale networks across high-density states to meet rising procedural demand. Patients choose ASCs for shorter stays and predictable outcomes. Payers support outpatient pathways to control escalating healthcare spending. The ambulatory surgical centre market maintains strong dominance in this region due to consistent investment and strong regulatory clarity.
Europe
Europe holds an estimated 26–28% market share, supported by structured clinical guidelines and strong focus on procedure quality. Countries improve outpatient capacities to reduce surgical backlogs and increase patient throughput. Providers build integrated care pathways that support ophthalmology, orthopedics, and gastrointestinal interventions. Private centres expand across Western Europe due to rising demand for quick-access specialty services. Patients choose ASCs for efficient recovery and reduced hospital exposure. Governments encourage outpatient models to optimise national healthcare resources. The market benefits from policy alignment and growing trust in modern outpatient care formats.
Asia Pacific
Asia Pacific accounts for approximately 20–22% share and remains the fastest advancing regional cluster. Urban hospitals expand outpatient wings to support rising surgical loads in China, India, and Southeast Asia. Private operators invest in freestanding centres to meet rapid demand for orthopedic, ophthalmology, and pain management procedures. Patients prefer affordable outpatient services that reduce hospitalisation time. Technology upgrades enable safer minimally invasive interventions across key cities. Payers in several markets adopt structured reimbursement to support outpatient care. The ambulatory surgical centre market gains strong momentum here due to expanding healthcare access and rising clinical awareness.
Key Player Analysis:
- United Surgical Partners International (USPI) – Tenet Healthcare
- SCA Health (Surgical Care Affiliates) – Optum/UnitedHealth Group
- AmSurg Corporation
- Surgery Partners
- HCA Healthcare
Competitive Analysis:
Competition in the Ambulatory surgical centre market intensifies due to rapid expansion of national operators and strong investment in specialty-focused centres. Large groups such as USPI, SCA Health, AmSurg, Surgery Partners, and HCA Healthcare scale their networks across major regions to capture higher procedure volumes. It maintains strong competitive activity through strategic acquisitions, capacity expansion, and technology adoption. Physician-owned centres defend market share through clinical autonomy and efficient decision cycles. Corporate-backed chains strengthen their position through digital workflow systems and broader service portfolios. Hospital-owned centres expand outpatient capacity to shift selected surgical loads outside inpatient environments. The competitive field strengthens through improved reimbursement models and ongoing investments in advanced surgical infrastructure.
Recent Developments:
- As of November 2025, HCA Healthcare continued its strategy of expanding ambulatory services by investing in the development and acquisition of new surgery centers. The company now operates approximately 2,500 ambulatory sites of care, including hundreds of freestanding ASCs. In 2025, HCA reported strong operational and financial performance, with continued growth in admissions, surgeries, and expansions through selected acquisitions, maintaining its status as one of the largest ambulatory care operators in the United States.
- In August 2025, SCA Health (formerly Surgical Care Affiliates), owned by Optum/UnitedHealth Group, completed its acquisition of U.S. Digestive Health, which operates 24 ASCs and over 40 gastroenterology practice sites in Pennsylvania and Delaware. This acquisition significantly expands SCA Health’s presence and its portfolio of gastrointestinal outpatient facilities in the Northeastern United States.
- In June 2025, AmSurg Corporation reached an acquisition agreement with Ascension Health, one of the largest nonprofit health systems in the country. This milestone deal brings more than 250 ASCs across 34 states into Ascension’s network, allowing AmSurg to enhance its community-based, physician-led care model and expand into new markets with comprehensive outpatient services including gastroenterology, ophthalmology, and orthopedics.
- In May 2025, Surgery Partners expanded its reach in California with the acquisition of multiple San Jose-based ambulatory surgery centers, including Montpelier Surgery Center and Advanced Surgery Center. These centers rank among the largest in the region and strengthen Surgery Partners’ position as the largest ASC provider in California’s South Bay area. These acquisitions are part of Surgery Partners’ ongoing national platform expansion through targeted acquisitions and specialty growth initiatives.
Report Coverage:
The research report offers an in-depth analysis based on By Center Type / Specialty, By Ownership, By Application / Specialty Area, By Service Type, and By Model. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of minimally invasive surgery will expand outpatient volumes.
- Large operators will scale national ASC networks across urban clusters.
- Physician-owned facilities will retain strong share due to clinical autonomy.
- Technology integration will improve workflow efficiency and patient outcomes.
- Multispecialty centres will gain traction due to wider procedure capabilities.
- Partnerships between hospitals and corporate groups will increase.
- Freestanding centres will expand in mid-size cities with higher procedure demand.
- Cardiology and neurosurgery will gain momentum through improved tools.
- Digital platforms will strengthen scheduling, monitoring, and pre-operative pathways.
- Payer policies will support sustained shift toward outpatient surgical models.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Outpatient Efficiency and Same-Day Surgical Care
Patients and payers increasingly prefer ambulatory surgical centres for their ability to deliver same-day procedures, reducing hospital stays, lowering costs, and improving recovery times. Hospitals are shifting appropriate surgeries to outpatient hubs to manage capacity and streamline workflow.
Expansion of Minimally Invasive Procedures
Advancements in surgical technology and tools have enabled a broader range of minimally invasive procedures to be performed safely in outpatient settings, increasing patient comfort and reducing recovery periods. This trend is driving higher procedure volumes across multiple specialties such as orthopedics, gastroenterology, and ophthalmology.
Increasing Payer and Policy Support for Outpatient Models
Insurers and government payers are expanding coverage and reimbursement for outpatient surgeries due to their cost-effectiveness and lower complication rates. Policy reforms and payer mandates are accelerating the migration of suitable procedures from inpatient to ambulatory settings.
Aging Population and Chronic Disease Prevalence
The growing elderly demographic and rising incidence of chronic diseases are increasing demand for orthopedic, ophthalmic, and pain management procedures, many of which are well-suited for ambulatory surgical centres. This demographic shift is fueling steady market growth.
Technology Integration and Digital Workflow Adoption
Ambulatory surgical centres are rapidly adopting robotics, AI-enabled imaging, and digital workflow systems to improve surgical precision, patient scheduling, and post-operative monitoring. These innovations enhance operational efficiency and patient outcomes, making ASCs more attractive to both providers and patients.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Ambulatory surgical centre market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ambulatory surgical centre market projected to grow between 2024 and 2032?
Which Ambulatory surgical centre market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ambulatory surgical centre market?
Who are the leading companies in the Ambulatory surgical centre market?
Which region commanded the largest share of the Ambulatory surgical centre market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Model
- 1.2.1 Hospital-Based ASCs
- 1.2.2 Freestanding ASCs
- 1.3 By Ownership
- 1.3.1 Physician-Owned
- 1.3.2 Hospital-Owned
- 1.3.3 Corporate-Owned
- 1.3.4 Hospital–Physician Joint Ventures
- 1.3.5 Corporate–Physician Partnerships
- 1.4 By Center Type / Specialty
- 1.4.1 Single-Specialty Centers (Ophthalmology, Gastroenterology, Pain Management, Orthopedics, Dermatology)
- 1.4.2 Multi-Specialty Centers
- 1.5 By Application / Specialty Area
- 1.5.1 Orthopedics
- 1.5.2 Gastroenterology
- 1.5.3 Ophthalmology
- 1.5.4 Pain Management / Spinal Injections
- 1.5.5 Plastic Surgery
- 1.5.6 Urology
- 1.5.7 ENT
- 1.5.8 Cardiology
- 1.5.9 Neurosurgery
- 1.5.10 Dermatology
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 100,420.67 million → 2032: USD 137,432.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ambulatory Surgical Centre Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ambulatory Surgical Centre Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ambulatory Surgical Centre Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ambulatory Surgical Centre Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ambulatory Surgical Centre Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ambulatory Surgical Centre Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ambulatory Surgical Centre Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ambulatory Surgical Centre Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 100,420.67 million → 2032: USD 137,432.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ambulatory Surgical Centre Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Model - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospital-Based ASCs
- 12.3.7.2 Freestanding ASCs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Ownership - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Physician-Owned
- 12.4.7.2 Hospital-Owned
- 12.4.7.3 Corporate-Owned
- 12.4.7.4 Hospital–Physician Joint Ventures
- 12.4.7.5 Corporate–Physician Partnerships
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Center Type / Specialty - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single-Specialty Centers (Ophthalmology, Gastroenterology, Pain Management, Orthopedics, Dermatology)
- 12.5.7.2 Multi-Specialty Centers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application / Specialty Area - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Orthopedics
- 12.6.7.2 Gastroenterology
- 12.6.7.3 Ophthalmology
- 12.6.7.4 Pain Management / Spinal Injections
- 12.6.7.5 Plastic Surgery
- 12.6.7.6 Urology
- 12.6.7.7 ENT
- 12.6.7.8 Cardiology
- 12.6.7.9 Neurosurgery
- 12.6.7.10 Dermatology
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ambulatory Surgical Centre End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ambulatory Surgical Centre Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ambulatory Surgical Centre Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ambulatory Surgical Centre Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 United Surgical Partners International (USPI) – Tenet Healthcare
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SCA Health (Surgical Care Affiliates) – Optum/UnitedHealth Group
- 18.4 AmSurg Corporation
- 18.5 Surgery Partners
- 18.6 HCA Healthcare
- 18.7 Envision Healthcare
- 18.8 SurgCenter Development
- 18.9 Medical Facilities Corporation
- 18.10 AMSURG
- 18.11 Nobilis Health
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

