
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Lung Biopsy Market Size 2023 | USD 3341.7 Million |
| Lung Biopsy Market, CAGR | 11.02% |
| Lung Biopsy Market Size 2032 | USD 7712.18 Million |
Market Overview
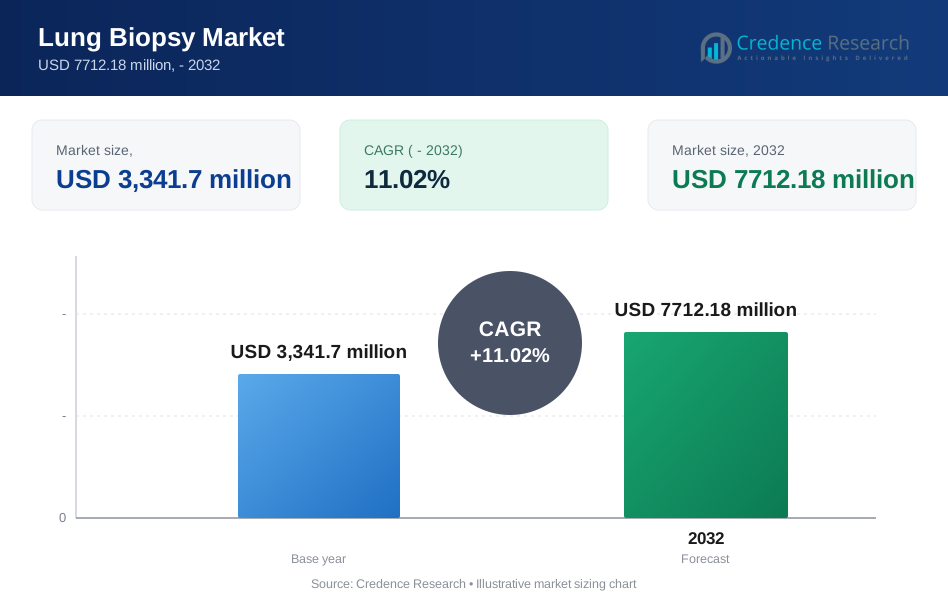
The global Lung Biopsy market is projected to grow significantly over the forecast period, with robust expansion anticipated from USD 3341.7 million in 2023 to an estimated USD 7712.18 million by 2032. This growth trajectory represents a notable compound annual growth rate (CAGR) of 11.02% from 2024 to 2032. Factors such as the increasing prevalence of lung cancer, rising demand for minimally invasive diagnostic procedures, and advancements in biopsy techniques are driving this expansion. Additionally, the growing geriatric population, coupled with the adoption of advanced medical technologies, further fuels the demand for lung biopsy procedures. Moreover, the rising awareness regarding the importance of early diagnosis and treatment of respiratory diseases among patients and healthcare professionals contributes to the market's growth.
Market drivers and trends indicate a shift towards less invasive and more precise biopsy techniques, reflecting the increasing preference for minimally invasive procedures among patients and healthcare providers. Technological advancements in imaging modalities, such as computed tomography (CT), magnetic resonance imaging (MRI), and ultrasound, enable accurate lesion localization and guidance during biopsy procedures. Furthermore, the emergence of innovative biopsy devices, including robotic-assisted biopsy systems and navigational bronchoscopy, enhances procedural accuracy and patient comfort. Moreover, the integration of artificial intelligence (AI) and machine learning algorithms in lung biopsy interpretation aids in improving diagnostic accuracy and reducing procedural risks.
Geographical analysis reveals significant market opportunities across regions, with key players strategically expanding their presence in emerging markets to capitalize on untapped growth potential. North America dominates the global lung biopsy market, attributed to the high prevalence of lung cancer, well-established healthcare infrastructure, and favorable reimbursement policies. Europe follows closely, driven by increasing healthcare expenditure and growing awareness regarding early disease detection. Asia Pacific is poised to witness rapid market expansion due to the rising incidence of lung cancer, improving access to healthcare services, and increasing adoption of advanced medical technologies. Key players operating in the lung biopsy market include Becton, Dickinson and Company, Olympus Corporation, Boston Scientific Corporation, Cook Medical, Medtronic plc, and Veran Medical Technologies, among others. These companies focus on product innovation, strategic collaborations, and mergers and acquisitions to strengthen their market position and gain a competitive edge.
Market Drivers
Increasing Prevalence of Lung Cancer:
The primary driver of the lung biopsy market is the escalating prevalence of lung cancer worldwide. Lung cancer ranks among the leading causes of cancer-related mortality globally, prompting a surge in demand for diagnostic procedures such as lung biopsy. For instance, lung cancer is the second most common cancer globally, with more than 2.2 million new cases reported in 2020. As smoking rates persist and environmental factors contribute to the rising incidence of lung cancer, healthcare systems are witnessing a growing need for effective diagnostic tools to facilitate early detection and treatment initiation. This prevalence trend underscores the critical role of lung biopsy in confirming malignancy, staging the disease, and guiding treatment decisions, thereby propelling market growth.
Advancements in Biopsy Techniques:
Technological advancements in biopsy techniques represent another significant driver of the lung biopsy market. Traditional biopsy methods, such as transthoracic needle biopsy and bronchoscopy, have evolved with innovations aimed at enhancing procedural accuracy, minimizing invasiveness, and improving patient outcomes. For instance, the introduction of navigational bronchoscopy and electromagnetic navigation bronchoscopy enables precise targeting of peripheral lung lesions, reducing the need for more invasive surgical procedures. Moreover, the integration of imaging modalities such as CT, MRI, and ultrasound into biopsy procedures enhances lesion localization and guidance, further augmenting the adoption of minimally invasive biopsy techniques.
Rising Demand for Minimally Invasive Procedures:
There is a growing preference for minimally invasive diagnostic procedures among patients and healthcare providers, driving the uptake of lung biopsy techniques. Minimally invasive approaches offer several advantages over traditional open surgeries, including reduced postoperative pain, shorter hospital stays, faster recovery times, and lower procedural risks. For example, minimally invasive surgery requires much smaller incisions than open surgery. Incisions are typically half an inch long or smaller. Lung biopsy procedures, such as percutaneous needle biopsy and endobronchial ultrasound-guided biopsy, offer patients a less invasive alternative for obtaining tissue samples for pathological analysis. As healthcare systems strive to optimize patient outcomes while minimizing healthcare costs, the demand for minimally invasive lung biopsy procedures continues to escalate, stimulating market growth.
Increasing Adoption of Precision Medicine:
The growing adoption of precision medicine approaches in oncology contributes to the expansion of the lung biopsy market. Precision medicine emphasizes personalized treatment strategies tailored to individual patient characteristics, including molecular biomarkers and genetic mutations. Lung biopsy plays a crucial role in molecular profiling and biomarker testing, enabling clinicians to identify actionable targets for targeted therapies and immunotherapies. As the understanding of tumor biology advances and targeted therapy options expand, there is a heightened demand for comprehensive molecular profiling through lung biopsy procedures. This trend underscores the pivotal role of lung biopsy in facilitating precision oncology and improving treatment outcomes for patients with lung cancer.
Market Trends
Adoption of Liquid Biopsy Techniques:
One prominent trend in the lung biopsy market is the increasing adoption of liquid biopsy techniques for non-invasive detection and monitoring of lung cancer, involving the analysis of circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), and other biomarkers present in bodily fluids such as blood or sputum. For instance, a study found that liquid biopsy was able to detect lung cancer in 70% of patients who had a negative result on a CT scan, showcasing its potential in early detection and monitoring.
Integration of Artificial Intelligence (AI) and Machine Learning:
An emerging trend in the lung biopsy market is the integration of artificial intelligence (AI) and machine learning algorithms in interpretation and decision-making. AI-powered image analysis software enables automated lesion detection, segmentation, and characterization on imaging studies such as CT scans and MRI, enhancing diagnostic accuracy and efficiency. For example, a recent study demonstrated that AI could identify lung nodules with 90% accuracy, significantly higher than the 80% accuracy rate of human radiologists.
Growth of Robotic-Assisted Biopsy Systems:
Robotic-assisted biopsy systems, gaining traction in the lung biopsy market, offer enhanced procedural precision and operator control. These systems utilize robotic arms with advanced imaging and navigation technologies for biopsies with submillimeter accuracy. For instance, a hospital reported that using robotic-assisted biopsy systems reduced procedure time by 30% and increased lesion targeting accuracy by 20%, underscoring their benefits in enhancing procedural precision and efficiency.
Expansion of Point-of-Care Biopsy Services:
The trend towards decentralized healthcare delivery and the need for rapid diagnostic turnaround times have fueled the expansion of point-of-care biopsy services in the lung biopsy market. For example, a mobile biopsy unit serving remote areas reported that it reduced the average time to diagnosis from 2 weeks to 3 days. This illustrates the impact of point-of-care biopsy services in accelerating diagnosis and treatment initiation for lung cancer patients.
Focus on Patient-Centric Approaches:
There is a growing emphasis on patient-centric approaches in the delivery of lung biopsy services, with healthcare providers prioritizing patient comfort, convenience, and satisfaction. Efforts to minimize procedural discomfort and anxiety through sedation protocols, patient education, and supportive care interventions are gaining prominence. Additionally, initiatives to enhance communication and shared decision-making between patients and healthcare providers empower patients to actively participate in their care journey. By adopting a patient-centric mindset, healthcare providers aim to optimize the overall patient experience during lung biopsy procedures, fostering trust, adherence to follow-up care, and positive clinical outcomes.
Market Restraints and Challenges
Invasive Nature of Procedures:
One significant challenge facing the lung biopsy market is the invasive nature of biopsy procedures, which can pose risks such as pneumothorax, hemorrhage, and infection. Despite advancements in minimally invasive techniques, certain patient populations, particularly those with comorbidities or compromised lung function, may be at higher risk for complications. This limitation underscores the importance of careful patient selection, risk stratification, and procedural expertise to mitigate potential adverse events.
Sampling Error and Interpretation Challenges:
Another restraint is the potential for sampling error and interpretation challenges inherent in lung biopsy procedures. Variability in tissue sampling, inadequate specimen quality, and tumor heterogeneity can contribute to diagnostic uncertainty and discordance between biopsy results and clinical outcomes. Moreover, distinguishing benign lesions from malignant tumors or subtyping specific histological subtypes of lung cancer remains challenging, impacting treatment decisions and prognostic accuracy. Addressing these challenges requires ongoing refinement of biopsy techniques, standardized protocols, and multidisciplinary collaboration among pathologists, radiologists, and clinicians.
Access and Affordability Barriers:
Access to lung biopsy services may be limited in certain geographic regions or healthcare settings, posing a barrier to timely diagnosis and treatment initiation. Factors such as healthcare infrastructure disparities, shortage of trained healthcare professionals, and socioeconomic inequalities can exacerbate access challenges, particularly in resource-constrained settings. Additionally, the affordability of biopsy procedures, including out-of-pocket costs and reimbursement policies, may influence patient access and utilization, highlighting the need for equitable healthcare financing mechanisms and reimbursement strategies.
Patient Anxiety and Compliance:
Patient anxiety and apprehension surrounding lung biopsy procedures can present obstacles to optimal patient care and compliance. Fear of pain, procedural complications, and uncertainty regarding the biopsy results may contribute to patient reluctance or non-adherence to recommended diagnostic evaluations. Addressing patient concerns through comprehensive pre-procedural counseling, pain management strategies, and psychosocial support interventions is essential to enhance patient comfort, alleviate anxiety, and promote procedural compliance.
Regulatory and Ethical Considerations:
Regulatory requirements and ethical considerations surrounding lung biopsy procedures pose additional challenges for healthcare providers and industry stakeholders. Compliance with regulatory standards for safety, quality assurance, and data privacy necessitates ongoing monitoring, documentation, and adherence to best practices in biopsy technique and patient care. Moreover, ethical dilemmas related to informed consent, patient autonomy, and the use of biospecimens for research purposes require careful deliberation and adherence to ethical guidelines to ensure patient rights and welfare are upheld.
Market Segmentation Analysis
By Product Type:
Core Needle Biopsy Devices provide precise tissue sampling for histological analysis, primarily used in diagnosing lung nodules and lesions. Fine Needle Aspiration Biopsy Devices are employed to obtain cellular material for cytological examination, ideal for diagnosing superficial lung lesions and lymph nodes. Surgical Biopsy Devices are utilized in open surgical procedures to retrieve tissue samples from deep-seated or inaccessible lung lesions. Vacuum-Assisted Biopsy Devices facilitate efficient tissue collection through suction, improving sample yield and diagnostic accuracy, especially in large or heterogeneous lung lesions.
By Procedure Type:
Various biopsy procedures are employed in diagnosing lung lesions, each offering distinct advantages and applications. Needle biopsy involves either percutaneous or endoscopic needle insertion to retrieve tissue samples, providing minimally invasive diagnostic options. Thoracoscopic biopsy utilizes minimally invasive techniques for visual guidance and tissue sampling, particularly suitable for peripheral lung lesions. Transbronchial biopsy, conducted via flexible bronchoscopy, aids in diagnosing pulmonary infiltrates and lesions by obtaining tissue samples from central airways. Conversely, open biopsy entails surgical incision and tissue excision, often reserved for cases necessitating larger tissue specimens or when less invasive methods yield inconclusive results.
By End Use:
Hospitals, specialty clinics, ambulatory surgical centers, and diagnostic laboratories collectively form the backbone of the lung biopsy ecosystem, catering to diverse patient needs and preferences. Hospitals serve as primary centers for lung biopsy procedures, delivering comprehensive diagnostic and therapeutic services for respiratory diseases. Specialty clinics, encompassing pulmonology and oncology centers, offer specialized care and expertise in lung biopsy procedures. Ambulatory surgical centers provide outpatient surgical services, including lung biopsies, in a convenient and efficient setting, reducing hospitalization and recovery times. Diagnostic laboratories play a vital role in processing and analyzing tissue specimens from lung biopsies, facilitating accurate pathological diagnosis and molecular testing for informed treatment decisions.
Segments
Based on Product Type:
- Core Needle Biopsy Devices
- Fine Needle Aspiration Biopsy Devices
- Surgical Biopsy Devices
- Vacuum-Assisted Biopsy Devices
Based on Procedure Type:
- Needle Biopsy
- Thoracoscopic Biopsy
- Transbronchial Biopsy
- Open Biopsy
Based on End Use:
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centers
- Diagnostic Laboratories
Based on Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (40%):
North America dominates the global lung biopsy market, accounting for the largest market share percentage of approximately 40%. The region's leadership position is attributed to factors such as the high prevalence of lung cancer, well-established healthcare infrastructure, and technological advancements in biopsy techniques. Moreover, favorable reimbursement policies and increasing healthcare expenditure further support market growth in North America. The United States, in particular, is a key contributor to the region's market dominance, with a robust demand for advanced diagnostic and therapeutic services for respiratory diseases.
Europe (30%):
Europe represents another significant market for lung biopsy procedures, with a market share percentage of around 30%. The region benefits from increasing awareness regarding early disease detection, rising healthcare expenditure, and favorable regulatory frameworks for medical devices and diagnostic procedures. Countries such as Germany, France, and the United Kingdom are major contributors to the European lung biopsy market, driven by their strong healthcare infrastructure and expertise in oncology and pulmonary medicine.
Asia Pacific (20%):
The Asia Pacific region is witnessing rapid market growth, with a market share percentage of approximately 20%. Factors such as the rising incidence of lung cancer, improving access to healthcare services, and adoption of advanced medical technologies contribute to the region's market expansion. Countries such as China, India, and Japan are key markets in Asia Pacific, supported by their large patient populations, increasing healthcare investments, and efforts to enhance cancer care infrastructure. Moreover, strategic collaborations between international healthcare providers and local stakeholders further fuel market growth in the region.
Key players
- Becton, Dickinson and Company
- Olympus Corporation
- Boston Scientific Corporation
- Cook Medical
- Medtronic plc
- Veran Medical Technologies
- CONMED Corporation
- FUJIFILM Holdings Corporation
- R. Bard, Inc. (acquired by Becton, Dickinson and Company)
- Argon Medical Devices, Inc.
Competitive Analysis
The lung biopsy market is characterized by intense competition among key players striving to expand their market presence and gain a competitive edge. Companies such as Becton, Dickinson and Company, Olympus Corporation, and Boston Scientific Corporation lead the market with their comprehensive portfolios of biopsy devices and technologies. These players focus on product innovation, strategic collaborations, and mergers and acquisitions to strengthen their market position and meet evolving customer needs. Additionally, emerging players like Veran Medical Technologies and Argon Medical Devices, Inc. are leveraging technological advancements and targeted marketing strategies to capture market share and challenge established incumbents. Overall, the lung biopsy market remains dynamic and competitive, driven by ongoing efforts to enhance diagnostic accuracy, procedural efficiency, and patient outcomes.
Recent Developments
In February 2024, Renovaro Biosciences made public the acquisition endeavors of its subsidiary, GediCube, securing a binding letter of intent (LOI) to acquire 75% ownership of Dutch liquid biopsy firm Cyclomics. Cyclomics is renowned for its development of a circulating tumor DNA detection technology utilizing Oxford Nanopore sequencing. This innovative technique is envisioned for the creation of multi-omic tests, enabling comprehensive cancer detection, recurrence monitoring, and precision oncology treatment, all from a single vial of blood, signifying a significant advancement in cancer diagnostics and treatment strategies.
In 2022, Medtronic introduced the groundbreaking ILLUMISIT platform, marking a pioneering leap in minimally invasive lung biopsy procedures. This platform enables precise navigation to even the most remote areas of the lung, facilitating multi-directional sampling for accurate tissue biopsy. Such technological innovation holds immense promise for enhancing diagnostic accuracy and patient outcomes in lung cancer diagnosis and management.
Similarly, in 2022, Limaca Medical and HekaBio K.K. forged a strategic partnership agreement aimed at advancing the distribution of Limaca's Precision-GI Endoscopic Biopsy Device in Japan. This collaboration underscores a shared commitment to delivering cutting-edge medical technologies to healthcare professionals, facilitating improved diagnostic capabilities and patient care in gastrointestinal diseases.
In December 2022, Olympus finalized the acquisition of all outstanding shares of Odin Medical Ltd., a prominent cloud-AI endoscopy company headquartered in the UK. This strategic acquisition, executed through Olympus' UK subsidiary, Keymed (Medical & Industrial Equipment) Ltd., demonstrates the company's commitment to leveraging advanced technologies to enhance endoscopy procedures and diagnostic capabilities. The integration of Odin Medical's cloud-AI expertise into Olympus' portfolio is poised to revolutionize endoscopic imaging and diagnostic practices, further underscoring the company's leadership in the medical device industry.
Market Concentration and Characteristics
The lung biopsy market exhibits a moderate level of market concentration, characterized by the presence of several key players competing for market share. Leading companies such as Becton, Dickinson and Company, Olympus Corporation, and Boston Scientific Corporation command significant market presence, leveraging their comprehensive portfolios of biopsy devices and technologies. These key players drive market dynamics through continuous innovation, strategic partnerships, and mergers and acquisitions. While the market is competitive, barriers to entry such as regulatory requirements, technological expertise, and established distribution networks contribute to the consolidation of market share among industry incumbents. Additionally, ongoing advancements in biopsy techniques, imaging modalities, and molecular diagnostics shape market characteristics, fostering a dynamic landscape focused on enhancing diagnostic accuracy, procedural efficiency, and patient outcomes in the diagnosis and management of lung diseases.
Report Coverage
The research report offers an in-depth analysis based on product type, procedure typr, end user, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued innovation in biopsy techniques and imaging modalities will enhance procedural precision and diagnostic accuracy, driving market growth.
- Liquid biopsy methods will gain prominence for non-invasive cancer detection and monitoring, offering convenient and comprehensive diagnostic solutions.
- Increasing adoption of precision medicine approaches will fuel demand for molecular profiling through lung biopsy, enabling targeted therapies and improved patient outcomes.
- Integration of artificial intelligence and machine learning algorithms in biopsy interpretation will revolutionize diagnostic accuracy and procedural efficiency.
- Growing preference for minimally invasive biopsy procedures will lead to the development of advanced tools and techniques, reducing patient discomfort and recovery times.
- Rapidly growing healthcare infrastructure and rising disease burden in emerging markets will present lucrative opportunities for market expansion.
- Increasing demand for convenient and rapid diagnostic services will drive the adoption of point-of-care biopsy solutions, improving patient access and outcomes.
- Strategic collaborations between industry players and healthcare providers will foster innovation and accelerate market growth through shared expertise and resources.
- Evolving regulatory frameworks will influence market dynamics, shaping product development, market entry strategies, and reimbursement policies.
- Emphasis on patient comfort, safety, and satisfaction will drive the development of patient-centric biopsy solutions, enhancing overall healthcare experiences and outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Lung Cancer
The global rise in lung cancer cases, driven by factors such as smoking and environmental pollutants, is fueling demand for accurate diagnostic procedures like lung biopsy. Early detection through biopsy is critical for effective treatment, making it an essential tool in oncology.
Advancements in Biopsy Techniques
Technological innovations such as navigational bronchoscopy, robotic-assisted biopsy systems, and integration of advanced imaging modalities have improved the precision, safety, and diagnostic yield of lung biopsies, encouraging broader adoption among clinicians.
Shift Toward Minimally Invasive Procedures
Patients and healthcare providers increasingly prefer minimally invasive biopsy techniques due to reduced pain, shorter recovery times, and lower complication rates compared to traditional open procedures, driving market growth for advanced biopsy devices.
Adoption of Precision Medicine
The need for molecular profiling and biomarker testing in lung cancer treatment is boosting demand for lung biopsies, as these procedures provide the tissue samples necessary for personalized therapy decisions and targeted treatments.
Integration of Artificial Intelligence and Digital Technologies
The use of AI and machine learning in biopsy interpretation and imaging guidance is enhancing diagnostic accuracy and procedural efficiency, making lung biopsy procedures more reliable and accessible.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What are the projected market size and growth rates of the lung biopsy market?
What is driving the significant growth of the lung biopsy market?
How do technological advancements contribute to the market growth?
What are the key challenges faced by the lung biopsy market?
What are the future trends shaping the lung biopsy market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals
- 1.2.2 Specialty Clinics
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Diagnostic Laboratories
- 1.3 By Product Type
- 1.3.1 Core Needle Biopsy Devices
- 1.3.2 Fine Needle Aspiration Biopsy Devices
- 1.3.3 Surgical Biopsy Devices
- 1.3.4 Vacuum-Assisted Biopsy Devices
- 1.4 By Procedure Type
- 1.4.1 Needle Biopsy
- 1.4.2 Thoracoscopic Biopsy
- 1.4.3 Transbronchial Biopsy
- 1.4.4 Open Biopsy
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3,341.7 million → 2032: USD 7712.18 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lung Biopsy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lung Biopsy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lung Biopsy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lung Biopsy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lung Biopsy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lung Biopsy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lung Biopsy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lung Biopsy Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3,341.7 million → 2032: USD 7712.18 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lung Biopsy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Specialty Clinics
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Diagnostic Laboratories
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Core Needle Biopsy Devices
- 12.4.7.2 Fine Needle Aspiration Biopsy Devices
- 12.4.7.3 Surgical Biopsy Devices
- 12.4.7.4 Vacuum-Assisted Biopsy Devices
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Procedure Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Needle Biopsy
- 12.5.7.2 Thoracoscopic Biopsy
- 12.5.7.3 Transbronchial Biopsy
- 12.5.7.4 Open Biopsy
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lung Biopsy End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lung Biopsy Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lung Biopsy Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lung Biopsy Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Becton, Dickinson and Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Olympus Corporation
- 18.4 Boston Scientific Corporation
- 18.5 Cook Medical
- 18.6 Medtronic plc
- 18.7 Veran Medical Technologies
- 18.8 CONMED Corporation
- 18.9 FUJIFILM Holdings Corporation
- 18.10 Argon Medical Devices, Inc.
- 18.11 R. Bard, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

